
 Golf Equipment Market | 2026-2036
Golf Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Equipment Market Intelligence
REACH compliance is pivoting material sourcing strategies across European supply chains, compelling manufacturers to reformulate adhesives and coatings. Callaway Golf Company leverages vertical integration to control graphite shaft production from prepreg to finished club. Mizuno Corporation anchors its reputation on forged iron craftsmanship honed in Yoro, Japan. TaylorMade Golf Company competes through aggressive R&D cycles in adjustable-weight driver systems.
Golf equipment encompasses clubs, balls, bags, gloves, shoes, and accessories engineered to conform with USGA and R&A equipment rules governing dimensions, spring-like effect coefficients, and aerodynamic symmetry. Clubs incorporate titanium faces with variable thickness mapping, graphite or carbon composite shafts with torque ratings below 4 degrees, and multi-material weighting to optimize launch conditions for swing speeds spanning 70 to 130 mph. The clubs segment dominates absolute revenue, while carbon composite technology captures expanding share as players seek lighter configurations; amateur competitions and recreational play represent the fastest-growing application channels, whereas professional tournaments concentrate brand prestige and endorsement economics. Shoes and gloves sustain steady replacement cycles tied to wear rates rather than technology obsolescence.
The USGA equipment standards, EPA chemical restrictions on solvent-based finishes, and EU REACH substance regulations collectively constrain formulation choices and market access timelines for non-compliant manufacturers. Japan's METI industrial standards and China's GB product safety codes add further certification layers for Asia-Pacific distribution. Stakeholders must monitor evolving sustainability mandates around synthetic rubber cores and recycled polymer grips, as regulatory breadth expands faster than harmonization across jurisdictions.
Market Dynamics
Carbon composite shaft technology is compressing traditional steel shaft market share while REACH compliance forces European manufacturers to reformulate adhesives and coatings across their supply chains.
Growth Catalysts
- Recreational youth participation:Younger demographics entering golf through simulator venues and entertainment-focused formats are expanding the addressable buyer base beyond traditional club membership models.
- Japan's METI industrial standards:Certification alignment with METI performance benchmarks is accelerating carbon composite adoption by validating torque ratings and durability metrics for premium shaft exports.
- Variable thickness face mapping:Titanium face engineering with computational thickness optimization is enabling manufacturers to maximize spring-like effect coefficients within USGA limits.
Market Restraints
- Graphite prepreg supply concentration:Japanese and Taiwanese suppliers control over 70 percent of aerospace-grade carbon fiber feedstock, creating vulnerability for shaft manufacturers without backward integration.
- EPA solvent restrictions:EPA limitations on volatile organic compounds in solvent-based club finishes are extending production cycles and requiring capital-intensive waterborne coating conversions.
- Equipment longevity:Multi-material driver constructions with 5-7 year durability cycles are suppressing replacement frequency among casual players compared to historical 3-year upgrade patterns.
Strategic Opportunities
- India course infrastructure buildout:Greenfield golf development in Delhi, Bangalore, and Hyderabad corridors presents equipment penetration potential as middle-class leisure spending expands.
- Adjustable weight system convergence:Integration of movable sole weights with launch monitor data feedback is creating premium tier differentiation for fitting-centric retail channels.
- EU Green Deal circularity mandates:Upcoming requirements for recycled polymer content in grips and synthetic rubber core traceability will favor early movers with certified sustainable supply chains.
Industry Challenges
- Master forging artisan scarcity:Japan's Yoro and Himeji clusters face generational transfer gaps in hand-forged iron craftsmanship as younger workers migrate to automated manufacturing sectors.
- Multi-jurisdiction certification complexity:Simultaneous USGA, R&A, METI, and GB standard compliance is extending product launch timelines and fragmenting regional SKU strategies.
- Launch monitor integration costs:Capital requirements for fitting bay technology and staff certification are compressing margins for independent specialty retailers competing against vertically integrated chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Equipment Market |
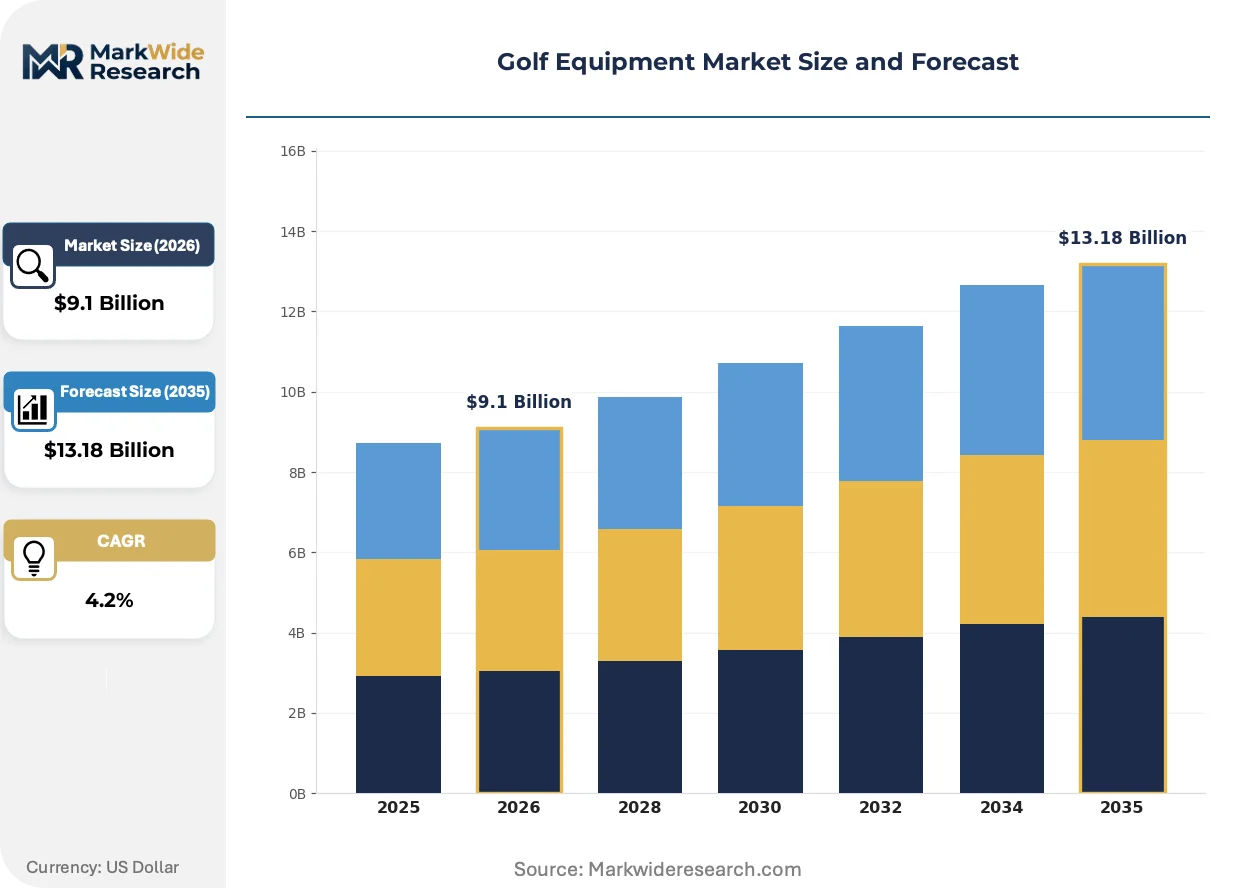
| Market Size in 2026 | $9.1 Billion |
| Market Size in 2035 | $13.18 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clubs, Balls, Bags, Gloves, Shoes, Accessories Technology: Forged, Cast, Titanium, Graphite Shafts, Carbon Composite, Multi-Material Application: Professional Tournaments, Amateur Competitions, Practice Facilities, Driving Ranges, Recreational Play, Training Centers End User: Golf Courses, Sports Academies, Private Clubs, Retailers, Online Resellers, Rental Services |
| Companies Covered | PING, Mizuno Corporation, TaylorMade Golf Company, PXG, Srixon, Callaway Golf Company, Cobra Golf, Titleist, Acushnet Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Equipment Market Strategic Shifts & Innovations
Computational design tools and biometric feedback systems are compressing product development cycles while reshaping how players select and purchase equipment.
Artificial intelligence-driven face topology optimization is automating thickness pattern generation that previously required months of physical prototyping. Mid-handicap players seeking forgiveness gains are adopting AI-designed drivers at accelerated rates through direct-to-consumer fitting platforms. This capability compression is automating the displacement of traditional CAD-reliant engineering workflows in mid-tier manufacturer R&D departments.
REACH substance restrictions on chromium VI in electroplating processes are compelling European foundries to transition toward trivalent chromium and PVD coating alternatives. The regulatory burden falls heaviest on small-batch iron manufacturers serving continental markets, forcing consolidation of finishing operations into specialized third-party providers. German and French suppliers are responding by pooling compliance certification costs through industry consortium arrangements.
Subscription-based equipment access models are emerging as an alternative to outright purchase for recreational players with compressed commitment horizons. Direct-to-consumer brands and specialty retailers in the United States are piloting annual club refresh programs with embedded fitting services. This channel experimentation is most visible in coastal metropolitan markets where simulator venue density supports try-before-subscribe logistics.
Golf Equipment Market Segmentation
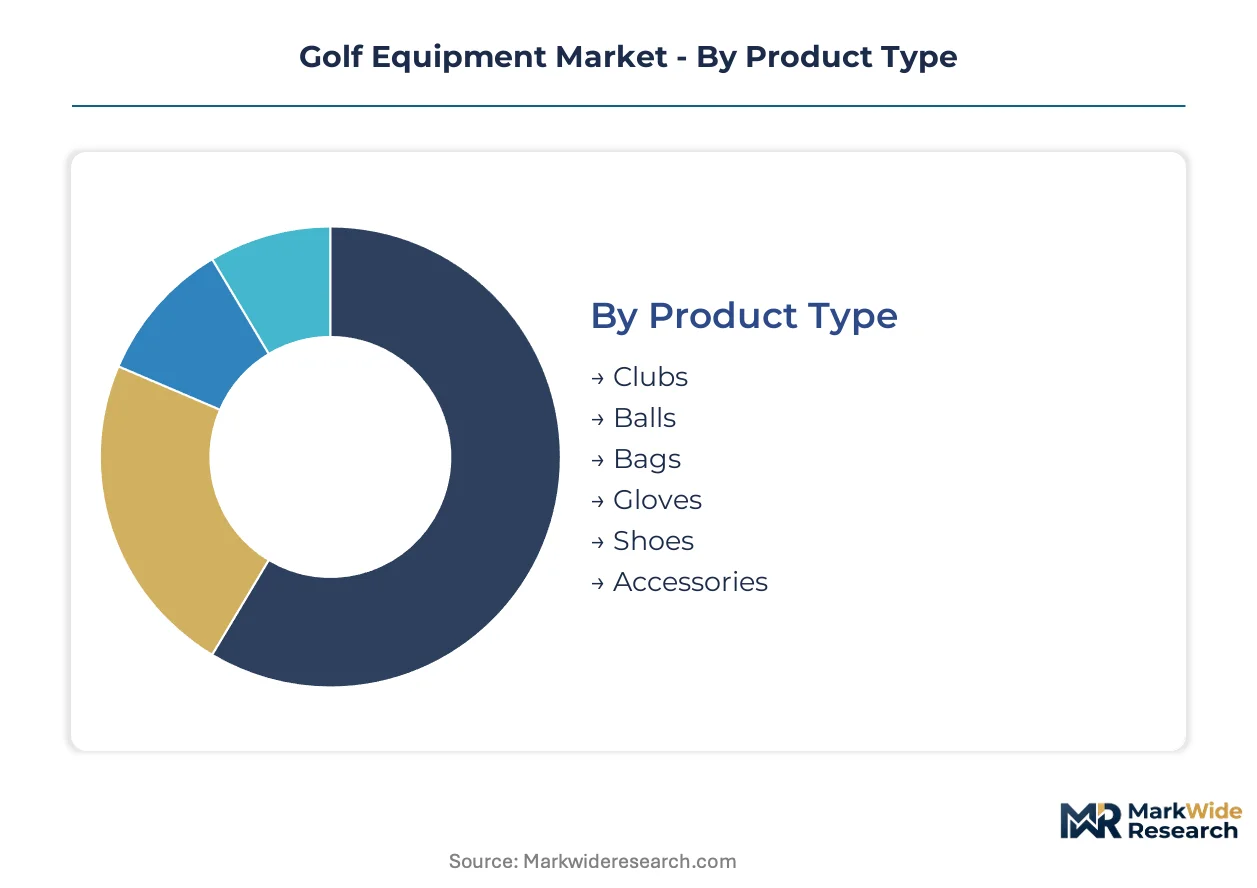
Segmentation in golf equipment reveals how material science, performance certification, and channel economics fragment purchasing behavior across player skill levels and venue types. Manufacturers configure product portfolios around torque specifications, USGA conformance tiers, and replacement cycle patterns rather than simple demographic splits.
Product Type:
Titanium face engineering and multi-material weighting separate premium tiers from commodity offerings across each equipment category.
- Clubs:Drivers incorporate variable thickness face mapping with spring-like effect coefficients optimized to USGA limits; irons split between forged carbon steel from Japan's Yoro cluster and cast stainless configurations. Demand concentrates in the United States where fitting bay density supports premium shaft upgrades.
- Balls:Multi-layer urethane cover constructions with synthetic rubber cores dominate performance tiers; two-piece ionomer formulations serve high-handicap recreational volume. Replacement frequency among competitive amateurs in Florida and Arizona sustains premium pricing power.
- Bags:Carbon composite stand bags with waterproof polymer bases capture walking-course preference in the United Kingdom; cart bags with 14-way top dividers dominate motorized play in the United States.
- Gloves:Cabretta leather constructions from Indonesian tanneries sustain tour-level feel requirements; synthetic microfiber alternatives extend durability for humid climates.
- Shoes:Waterproof membrane integration with carbon fiber shank plates separates spikeless comfort designs from traditional cleated traction systems.
- Accessories:Launch monitor alignment aids and GPS-enabled rangefinders represent the fastest-growing attach rate as fitting culture penetrates mid-handicap demographics.
Clubs lead on scale; accessories lead on momentum.
Technology:
Material sourcing concentration and regulatory compliance burden differentiate manufacturing economics across process categories.
- Forged:Hand-finished carbon steel irons from Japan's Himeji and Yoro forging clusters command premium positioning through grain structure density. Master artisan scarcity constrains volume expansion as generational transfer gaps widen.
- Carbon Composite:Toray and Mitsubishi Chemical carbon fiber prepreg supply vertical integration separates shaft manufacturers with captive aerospace-grade feedstock from assembly-dependent competitors. Japanese METI certification validates torque ratings below 4 degrees for export markets.
- Cast:Investment casting of 17-4 stainless steel enables complex cavity-back geometries at volume price points.
- Titanium:Face cup welding to beta-titanium bodies maximizes COR distribution across off-center strikes.
- Graphite Shafts:Intermediate modulus fiber configurations balance weight reduction with stability for swing speeds below 95 mph.
- Multi-Material:Tungsten screw weighting in sole positions optimizes launch angle and spin decay through movable mass systems.
Carbon composite shafts expand most quickly; forged craftsmanship retains pricing power.
Application:
Venue type dictates equipment durability requirements, fitting service intensity, and brand exposure value.
- Recreational Play:Simulator venue proliferation in metropolitan United States markets compresses commitment horizons and accelerates trial-to-purchase conversion through data-driven fitting. Entertainment-focused formats expand the addressable buyer base beyond traditional club membership models.
- Professional Tournaments:Equipment contracts concentrate endorsement economics and R&D amortization across tour staff rosters; USGA conformance validation precedes any competitive deployment.
- Amateur Competitions:Regional tournament circuits in Texas and California sustain mid-tier driver refresh cycles through prize table exposure.
- Practice Facilities:High-volume ball consumption and durability-optimized range equipment separate training economics from retail purchase patterns.
- Driving Ranges:Mat surface interaction requirements favor specific sole grind configurations in iron selection.
- Training Centers:Biometric feedback integration with adjustable equipment supports instruction revenue models.
Recreational play leads on scale; professional tournaments lead on brand prestige.
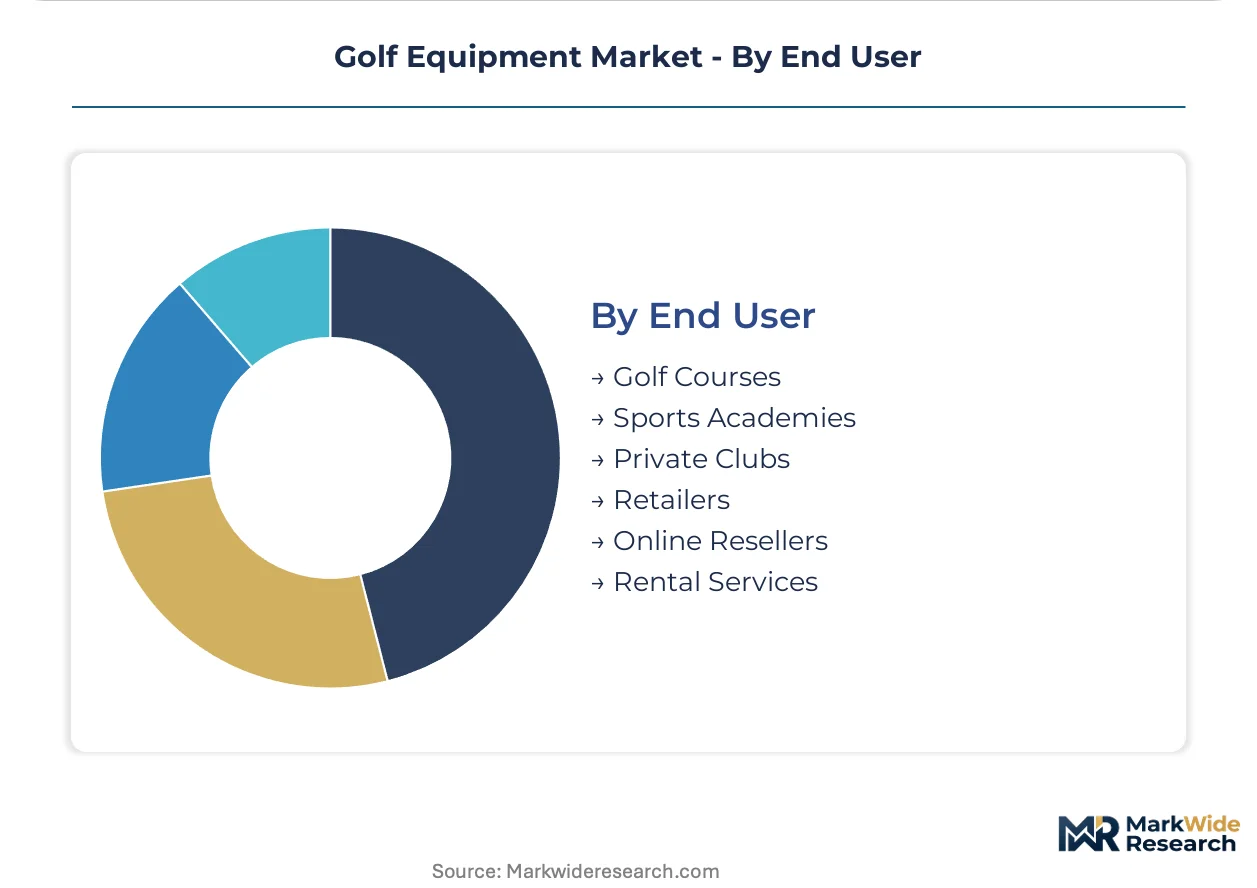
End User:
Channel control and inventory velocity separate vertically integrated retailers from specialty fitting operations.
- Retailers:Big-box sporting goods chains in the United States leverage private label ball sourcing and seasonal promotional calendars; specialty green grass shops monetize fitting bay technology through shaft upgrade attach rates.
- Golf Courses:Pro shop merchandise mix balances impulse accessory purchases with custom order club specifications; resort properties in Scottsdale and Palm Springs capture destination spending with regional headcover and apparel exclusives.
- Online Resellers:Direct-to-consumer brands bypass wholesale margin stacking through subscription-based annual refresh programs piloted in coastal metropolitan markets.
- Sports Academies:Instruction bundling with equipment trial accelerates junior player conversion.
- Private Clubs:Member equity structures support higher average transaction values in apparel and accessories.
- Rental Services:Durability-optimized club configurations with standardized lie angles minimize maintenance overhead.
Retailers lead on volume throughput; online resellers lead on channel experimentation velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master forging artisans in Japan's Gifu Prefecture anchor the highest-value club manufacturing workforce, while carbon fiber prepreg specialists in Taiwan and the United States concentrate shaft engineering talent. These geographic concentrations of craft and material science expertise shape competitive positioning across premium equipment tiers.
United States
Simulator venue proliferation in metropolitan markets accelerates trial-to-purchase conversion through data-driven fitting culture. EPA volatile organic compound restrictions on solvent-based club finishes extend production cycles and necessitate waterborne coating conversions. Scottsdale and Palm Springs resort corridors capture destination spending with regional merchandise exclusives.
Japan
METI industrial standards certification validates torque ratings below 4 degrees for carbon composite shaft exports to premium markets. Yoro and Himeji forging clusters face generational transfer gaps as younger workers migrate toward automated manufacturing sectors. Osaka-based material suppliers maintain aerospace-grade carbon fiber feedstock vertical integration.
Germany
REACH substance restrictions on chromium VI in electroplating processes compel foundries toward trivalent chromium and PVD coating alternatives. German suppliers pool compliance certification costs through industry consortium arrangements. Bavarian finishing operations consolidate into specialized third-party providers serving continental markets.
United Kingdom
Carbon composite stand bags with waterproof polymer bases capture walking-course preference across links-style venues. EU Green Deal circularity mandates for recycled polymer content in grips favor early movers with certified sustainable supply chains. London metropolitan simulator density supports subscription-based equipment access model pilots.
China
GB product safety codes add certification layers for Asia-Pacific distribution of imported equipment brands. Yangtze River Delta manufacturing bases produce volume-tier cast stainless iron configurations. Domestic middle-class leisure spending expansion drives greenfield course development in satellite city corridors.
Golf Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure concentrates around shaft manufacturing where carbon fiber prepreg supply constraints favor backward-integrated players. Three archetypes dominate: vertically integrated equipment conglomerates controlling graphite production from prepreg to finished club; heritage forging houses anchored on hand-finished craftsmanship; and direct-to-consumer brands bypassing wholesale margin stacking. Capacity expansion in fitting bay technology and strategic partnerships with launch monitor providers represent the dominant competitive vectors.
Within the heritage forging tier, Mizuno Corporation and PING exemplify craft-centered positioning rooted in multi-generational manufacturing expertise. Callaway Golf Company occupies a position among diversified equipment conglomerates with upstream control over critical material inputs. These three anchors represent distinct strategic postures: artisanal reputation monetization, scale-driven portfolio breadth, and captive supply chain security respectively.
| Leading Market Players |
|---|
| PING |
| Mizuno Corporation |
| TaylorMade Golf Company |
| PXG |
| Srixon |
| Callaway Golf Company |
| Cobra Golf |
| Titleist |
| Acushnet Holdings Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into carbon fiber prepreg production anchors pricing power for shaft manufacturers with captive aerospace-grade feedstock from Japanese and Taiwanese suppliers, while assembly-dependent competitors absorb margin compression from concentrated raw material sourcing.
Pricing Analysis
Bundled fitting services with launch monitor data separate premium channel pricing from transactional retail, while unbundled club-only sales compete on specification transparency. Three-tier pricing structure across premium, standard, and economy levels stratifies by shaft torque rating and face material certification. Pricing pressure stems from simulator venue proliferation compressing commitment horizons and accelerating trial-to-substitution. Recreational players entering through entertainment formats exhibit highest price sensitivity; competitive amateurs seeking USGA-conformance validation show lowest.
Supply Chain Analysis
Carbon fiber prepreg supply rests on Japanese and Taiwanese specialty chemical producers controlling aerospace-grade feedstock, with German finishing operations consolidating trivalent chromium conversion. Raw material dependencies span Toray and Mitsubishi Chemical carbon fiber, Indonesian cabretta leather tanneries, and synthetic rubber core formulations. Single-source vulnerability concentrates in Japanese shaft manufacturing clusters facing generational artisan transfer gaps. Distribution runs through vertically integrated retail chains, specialty green grass fitting bays, and direct-to-consumer subscription pilots in coastal metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment manufacturers can exploit geographic arbitrage between EPA solvent restriction compliance costs in the United States and REACH reformulation burdens in Europe, shifting finishing operations toward jurisdictions with lighter volatile organic compound mandates.
For Market Incumbents: Deepen backward integration into graphite shaft production to secure carbon fiber prepreg allocation against Japanese and Taiwanese supply concentration. Consolidate finishing operations into specialized third-party providers to pool REACH and EPA compliance certification costs. Channel control through fitting bay technology investments defends against direct-to-consumer subscription models eroding wholesale margins. For New Entrants and Emerging Players: Enter via simulator venue partnerships in metropolitan United States markets, where entertainment-focused formats expand addressable demand beyond traditional club membership. White-space targets include subscription-based annual refresh programs with embedded fitting services, and India course infrastructure buildout in Delhi and Bangalore corridors. Go-to-market through launch monitor data integration differentiates against established brand heritage positioning. For Investors and Strategic Acquirers: Roll-up economics work for specialized shaft manufacturers with METI certification and captive carbon fiber supply because supply-side concentration favors backward-integrated players with validated torque ratings. Long-term viability hinges on sustainability certification alignment with EU Green Deal circularity mandates for recycled polymer grips. Watch for generational transfer resolution in Japan's Yoro forging clusters as inflection indicator for premium iron supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Captive aerospace-grade feedstock from Toray and Mitsubishi Chemical secures shaft manufacturing allocation against supply concentration. |
| Launch Monitor Technology Partnership | Fitting bay integration with TrackMan and Foresight Sports compresses trial-to-purchase conversion in simulator venues. |
| EU Green Deal Circularity Certification | Recycled polymer grip content validation from early movers captures sustainable supply chain preference. |
| India Course Infrastructure Joint Venture | Greenfield development in Delhi and Bangalore corridors penetrates middle-class leisure spending expansion. |
| Artisan Forging Apprenticeship Program | Generational transfer pipeline in Japan's Yoro cluster addresses master craftsman scarcity constraining premium iron volume. |
Research Approach
Direct dialogue with equipment R&D directors, shaft manufacturing procurement leads, specialty retail fitting bay operators, and USGA conformance validation engineers combined with secondary analysis of customs trade data, SEC 10-K filings, METI certification registries, and EPA solvent restriction compliance disclosures. Bottom-up demand modeling across player skill segments triangulated against top-down equipment shipment value estimates.
Top-down macroeconomic framing anchored volume projections across the modeling period, while bottom-up segment builds aggregated discrete demand from torque specification tiers, USGA conformance categories, and channel economics. Segmentation dimensions modeled include product type, material technology, application venue, and end-user channel control. CAGRs derived from fitted trend analysis incorporating recreational participation rates, carbon composite adoption curves, and regulatory compliance cost trajectories.
The model holds under stable recreational participation growth and continued carbon fiber supply concentration; deviation in Japanese artisan generational transfer resolution or REACH substance restriction expansion would shift premium tier supply elasticity. A small set of named triggers—METI certification timeline changes, EPA waterborne coating mandate acceleration, and India course development financing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Golf Club Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Knee Pads Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Sports Devices Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Global Skateboard Market