
 Premium Bicycle Market | 2026-2036
Premium Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Bicycle Market Insights
Urban commuter demand is expanding as professionals replace short car trips with high-performance bicycles. Trek Bicycle Corporation leverages its dealer network and domestic manufacturing to sustain market presence across North American cities. Giant Manufacturing anchors global volume through vertically integrated carbon fiber frame production in Taiwan. Specialized Bicycle Components differentiates via proprietary suspension technology and direct-to-consumer digital channels.
Premium bicycles are lightweight, high-performance human-powered vehicles engineered from advanced composites or alloys, typically weighing under eight kilograms for road racing variants, designed for speed, endurance, or terrain-specific performance in competitive and recreational settings. Carbon fiber frame material dominates margin pools due to manufacturing complexity and performance differentiation, while electric bikes represent the fastest-expanding product type as pedal-assist technology broadens accessibility across age and fitness demographics. Competitive racing and fitness training applications command premium pricing, whereas leisure riding sustains volume through seasonal replacement cycles.
FDA regulates consumer product safety standards for bicycles sold in the United States, while the EU Green Deal and CE marking requirements under the F-Gas Regulation shape environmental compliance and component sourcing across European supply chains. The EU AI Act introduces emerging oversight for smart-enabled electric bike systems with autonomous features. Stakeholders must monitor evolving battery certification standards and carbon border adjustment mechanisms that will reshape sourcing economics and market access conditions.
Market Dynamics
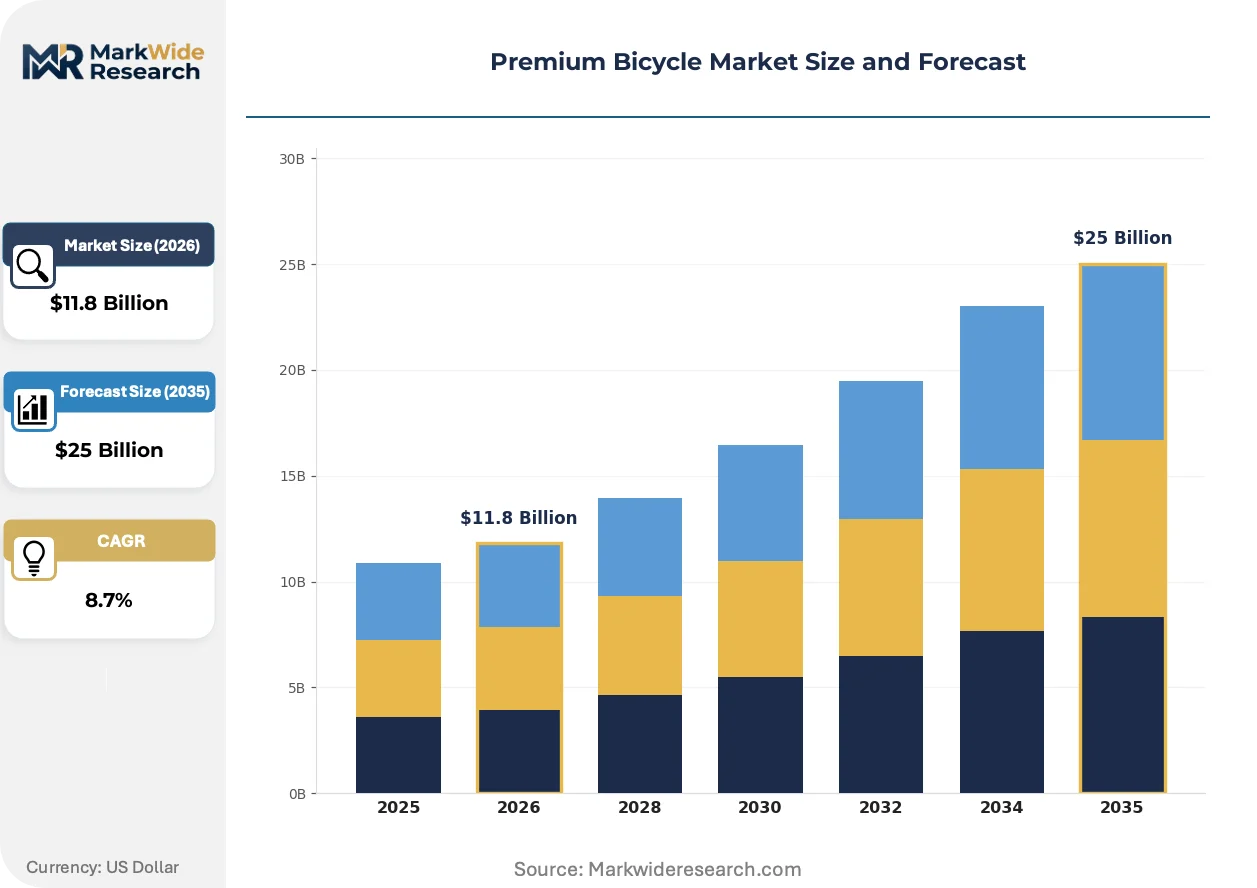
The premium bicycle market is undergoing structural compression as EU carbon border adjustment mechanisms and battery certification standards force supply chain reconfiguration, while pedal-assist technology simultaneously broadens addressable demand across age demographics.
Growth Catalysts
- EU Green Deal low-emission mobility frameworks:Member state subsidies for cycling infrastructure and purchase incentives accelerate replacement of short car trips with high-performance bicycles in urban commuter segments.
- Carbon fiber manufacturing advances:Automated layup and resin transfer molding reduce frame production costs, enabling performance differentiation at accessible price points for competitive racing applications.
- Municipal protected cycling infrastructure:Cities in Germany, the Netherlands, and Denmark expand dedicated lane networks, reducing perceived safety barriers and sustaining modal share above fifteen percent.
Market Restraints
- Taiwanese carbon fiber supply concentration:Frame and component manufacturing clusters on the island create geopolitical exposure and logistics bottlenecks for global brands dependent on just-in-time delivery.
- Lithium-ion battery raw material volatility:Cobalt and nickel price swings compress electric bike margin pools and complicate long-term pricing commitments to dealer networks.
- REACH chemical compliance friction:European pre-market registration requirements for composite resins and surface coatings delay product launches and increase regulatory overhead for specialty frame finishes.
Strategic Opportunities
- Underpenetrated US urban commuter corridors:Protected lane construction in Austin, Denver, and Seattle creates first-mover positioning for direct-to-consumer brands targeting professional car-trip substitution.
- EU AI Act smart-system compliance:Early certification of autonomous electric bike features—collision avoidance, adaptive pedal assist—creates regulatory moats against late entrants.
- Direct-to-consumer digital channel expansion:Virtual fit algorithms and mobile service networks bypass traditional dealer markups, capturing margin and customer data simultaneously.
Industry Challenges
- Composite technician skill scarcity:Carbon fiber layup and repair expertise concentrates in legacy aerospace and automotive supply bases, forcing bicycle manufacturers to compete for trained labor or fund apprenticeship programs.
- CE marking and battery UN38.3 certification timelines:Extended testing cycles for electric bike systems delay seasonal product launches and tie up working capital in pre-approved inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Bicycle Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road Bikes, Mountain Bikes, Hybrid Bikes, Electric Bikes, Touring Bikes Frame Material: Carbon Fiber, Aluminum, Steel, Titanium, Bamboo Application: Competitive Racing, Commuting, Adventure Touring, Fitness Training, Leisure Riding Customer Type: Professional Athletes, Cycling Enthusiasts, Urban Commuters, Adventure Travelers, Fitness Enthusiasts |
| Companies Covered | Trek Bicycle Corporation, Specialized Bicycle Components, Giant Manufacturing, Cannondale, Canyon Bicycles, BMC Switzerland, Merida Industry, Cervélo Cycles, Pon Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Bicycle Market Trends and Innovations
Pedal-assist technology is actively redrawing competitive boundaries in the premium bicycle market, forcing incumbents to recalibrate portfolio architecture and supply chain partnerships.
Integrated torque-sensor pedal-assist systems are expanding into road racing and gravel segments previously dominated by pure human-power designs. Competitive cyclists and gran fondo participants adopt lightweight mid-drive motors for hill-intensive courses. This technology is expanding into price tiers and use cases that mechanical drivetrains previously controlled.
EU F-Gas Regulation refrigerant phase-down mandates are reshaping thermal management strategies for electric bike battery packs and motor controllers. Manufacturers must redesign cooling architectures to eliminate hydrofluorocarbon dependencies. High-performance electric bike categories face compressed development cycles to meet 2027 compliance deadlines.
Subscription-based ownership models are displacing outright purchase in urban commuter segments. Fleet operators and mobility-as-a-service providers bundle maintenance, insurance, and upgrade rights into monthly fees. This shift concentrates procurement decisions among commercial buyers in Copenhagen, Amsterdam, and Berlin, reducing brand loyalty among individual consumers.
Premium Bicycle Market Segmentation
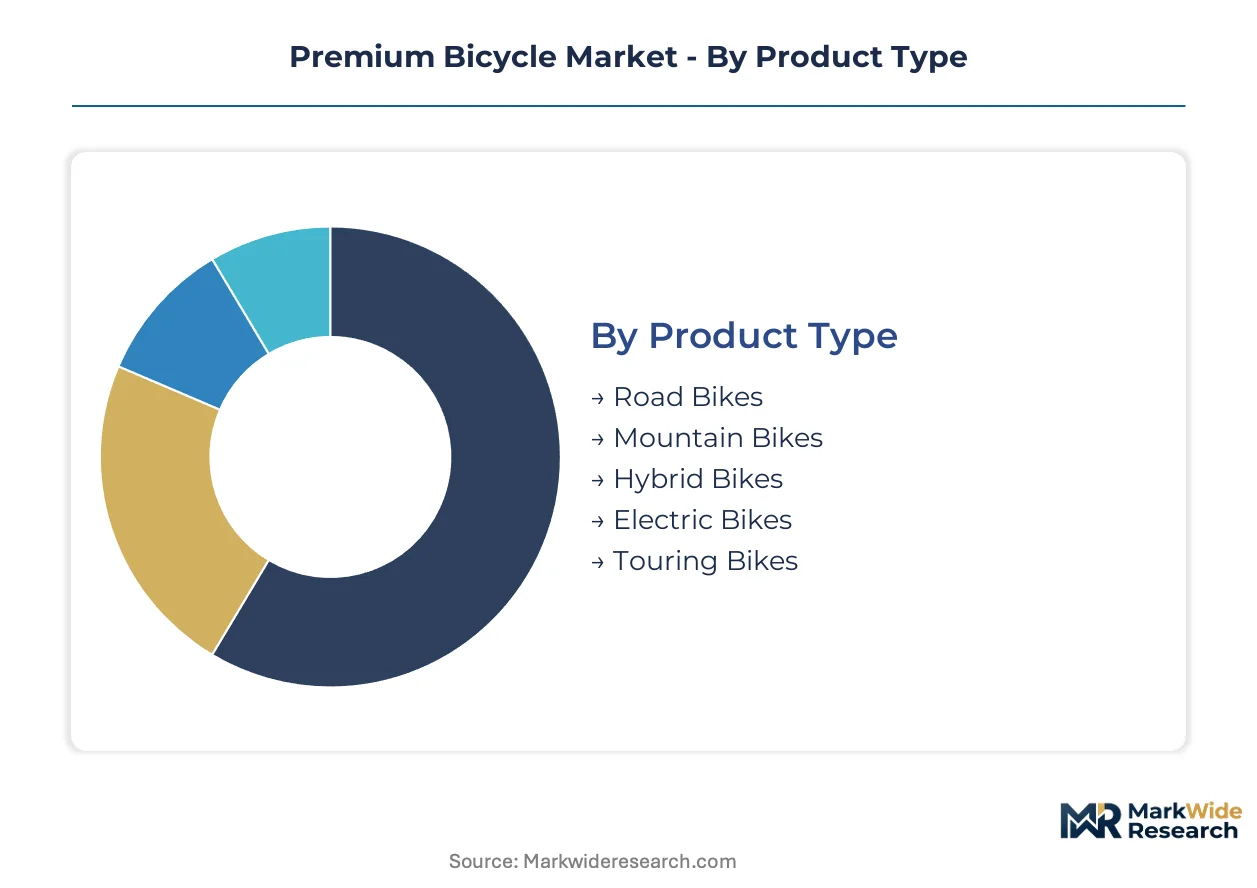
Premium bicycle segmentation reflects divergent manufacturing economics and performance requirements across use cases. Supply chain configuration varies sharply between lightweight road racing platforms and electric-assist urban mobility systems.
Product Type:
Carbon fiber layup capacity concentrates among Taiwanese contract manufacturers, creating sourcing bottlenecks for high-performance categories while electric bike assembly disperses across European and North American facilities.
- Electric Bikes:Pedal-assist systems integrate lithium-ion battery packs, mid-drive motors, and torque sensors into frames requiring reinforced bottom bracket shells. Demand concentrates in German, Dutch, and Danish urban commuter corridors where municipal purchase subsidies reduce acquisition costs. EU battery UN38.3 certification and F-Gas Regulation thermal management compliance compress margin pools for non-compliant entrants.
- Road Bikes:Sub-eight-kilogram carbon fiber frames with aerodynamic tube profiles and integrated cable routing dominate competitive racing and gran fondo participation. Manufacturing clusters in Taichung supply global brands with monocoque construction and automated resin transfer molding.
- Mountain Bikes:Suspension travel categories from cross-country to downhill demand alloy or carbon rear triangles with linkage-driven shock absorption.
- Hybrid Bikes:Flat handlebar geometry and wider tire clearance bridge fitness training and urban utility applications.
- Touring Bikes:Steel or titanium frames with rack and fender mounts prioritize load capacity over weight minimization for multi-day expedition use.
Electric bikes absorb the bulk of installed capacity expansion; road bikes retain the steepest margin concentration.
Frame Material:
Raw material selection determines factory location, labor skill requirements, and regulatory exposure across manufacturing footprints.
- Carbon Fiber:Pre-preg layup and autoclave curing yield strength-to-weight ratios unmatched by metallic alternatives. Taichung manufacturing clusters supply Trek, Specialized, and Giant with frame monocoques and rim components. REACH chemical registration for epoxy resins and surface coatings creates European market access friction for smaller brands lacking compliance infrastructure.
- Aluminum:Hydroformed 6061-T6 alloy tubes deliver cost-efficient performance for entry-premium mountain and hybrid categories. Extrusion and welding capacity localizes more readily than carbon fiber expertise.
- Steel:Chromoly tubing persists in touring and custom frame segments for repairability and ride quality.
- Titanium:Aerospace-grade Ti-3Al-2.5V tubing commands artisan production scales with limited volume elasticity.
- Bamboo:Laminated grass fiber composites serve niche sustainability-positioned brands with localized supply chains.
Carbon fiber commands premium pricing tiers; aluminum scales most efficiently across mid-market positioning.
Application:
End-use differentiation drives component specification, distribution channel selection, and replacement cycle frequency.
- Competitive Racing:UCI-compliant frame geometries, electronic shifting, and aerodynamic wheelsets target sanctioned event participation. Professional and elite amateur cyclists in Belgium, Italy, and Spain sustain demand for technical performance differentiation.
- Commuting:Fenders, lighting integration, and rack compatibility prioritize utility over weight minimization. Protected lane construction in Copenhagen, Amsterdam, and Berlin reduces perceived safety barriers for daily car-trip substitution.
- Fitness Training:Power meter integration and training platform connectivity support structured workout protocols.
- Adventure Touring:Frame bag compatibility and tire clearance for unpaved surfaces enable bikepacking expedition use.
- Leisure Riding:Comfort-oriented geometry and step-through accessibility broaden demographic reach across age segments.
Commuting applications are gaining share fastest; competitive racing sustains absolute margin contribution.
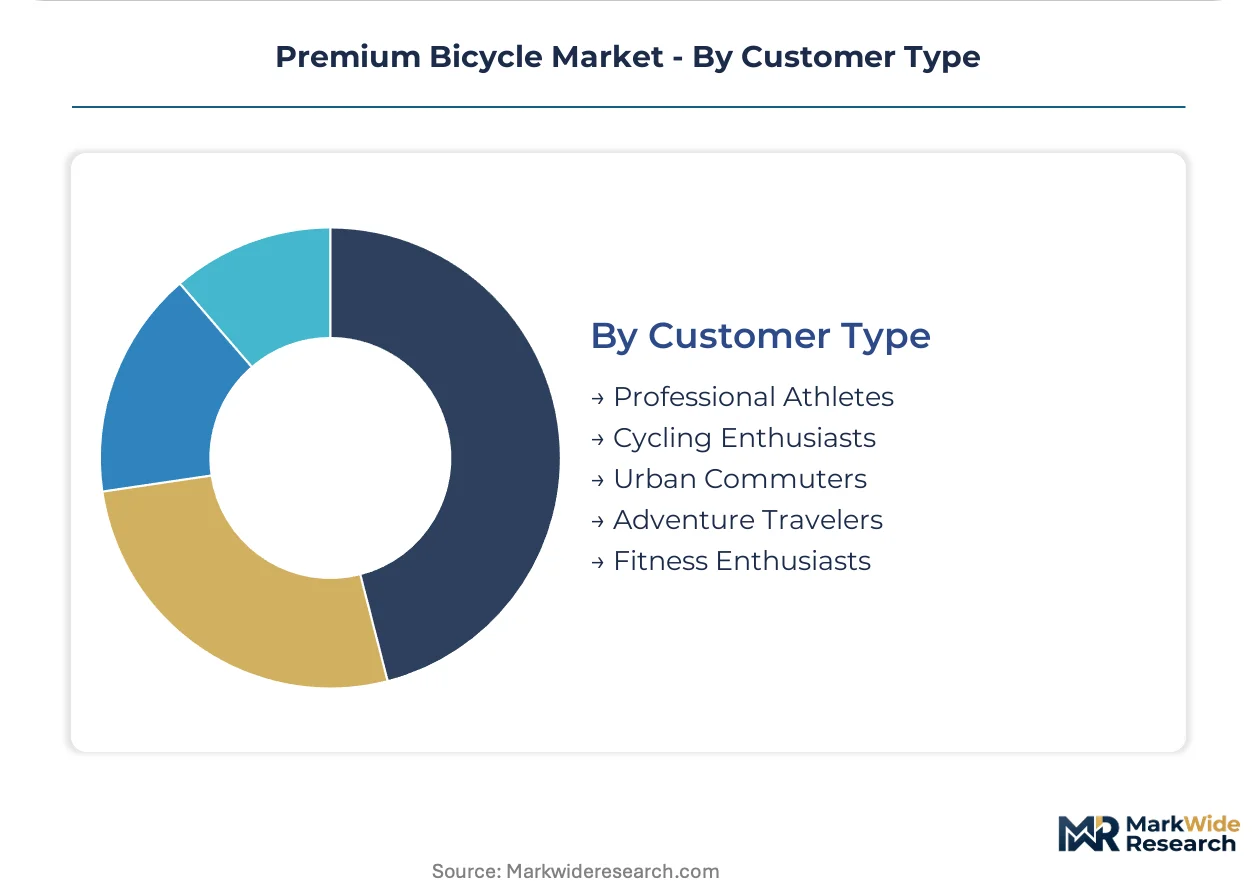
Customer Type:
Procurement authority and price sensitivity diverge sharply between institutional purchasers and individual consumers.
- Urban Commuters:Professionals replacing sub-ten-kilometer car trips demand integrated security features, weather protection, and low maintenance requirements. Municipal fleet procurement in Scandinavian and German cities concentrates volume among commercial buyers with subscription-based ownership preferences.
- Cycling Enthusiasts:Hobbyist collectors and club participants drive component upgrade cycles and seasonal frame replacement. This segment tolerates premium pricing for limited-edition collaborations and heritage brand positioning.
- Professional Athletes:Sponsored riders and elite competitors receive equipment through team supply agreements with minimal direct revenue contribution.
- Adventure Travelers:Expedition tour operators and independent bikepackers prioritize frame durability and repairability in remote settings.
- Fitness Enthusiasts:Health club members and home trainer users seek training platform integration and biometric data capture.
Cycling enthusiasts absorb the bulk of aftermarket component spend; urban commuters are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taichung Science Park bicycle manufacturing incentives concentrate carbon fiber frame production in Taiwan, while EU Green Deal subsidies redirect assembly capacity toward European facilities.
Germany
Urban commuter demand surges in Berlin and Munich as professionals abandon sub-ten-kilometer car trips. KBA vehicle registration data tracks accelerating bicycle-to-car substitution ratios. Stuttgart manufacturing clusters host mid-drive motor assembly operations for pedal-assist road racing platforms.
United States
Protected lane construction in Austin, Denver, and Seattle reduces perceived safety barriers for daily bicycle commuting. NHTSA consumer product safety standards govern frame integrity and component durability testing. Pacific Northwest metro areas concentrate direct-to-consumer brand headquarters and virtual fit technology development.
Netherlands
Cycling modal share exceeds twenty percent in Amsterdam and Utrecht urban cores. EU F-Gas Regulation thermal management mandates reshape electric bike battery pack engineering specifications. Eindhoven manufacturing corridors host automated resin transfer molding facilities for high-volume carbon fiber production.
Denmark
Copenhagen municipal fleet procurement concentrates volume among commercial buyers with subscription-based ownership preferences. REACH chemical registration requirements for composite resins delay specialty frame finish launches. Odense industrial zones accommodate final assembly operations for North European distribution.
Taiwan
Taichung manufacturing clusters supply Trek, Specialized, and Giant with monocoque carbon fiber construction. EPA Taiwan environmental compliance standards govern volatile organic compound emissions from autoclave curing operations. Kaohsiung port facilities manage just-in-time component logistics for North American and European brand networks.
Premium Bicycle Market Competitive Landscape
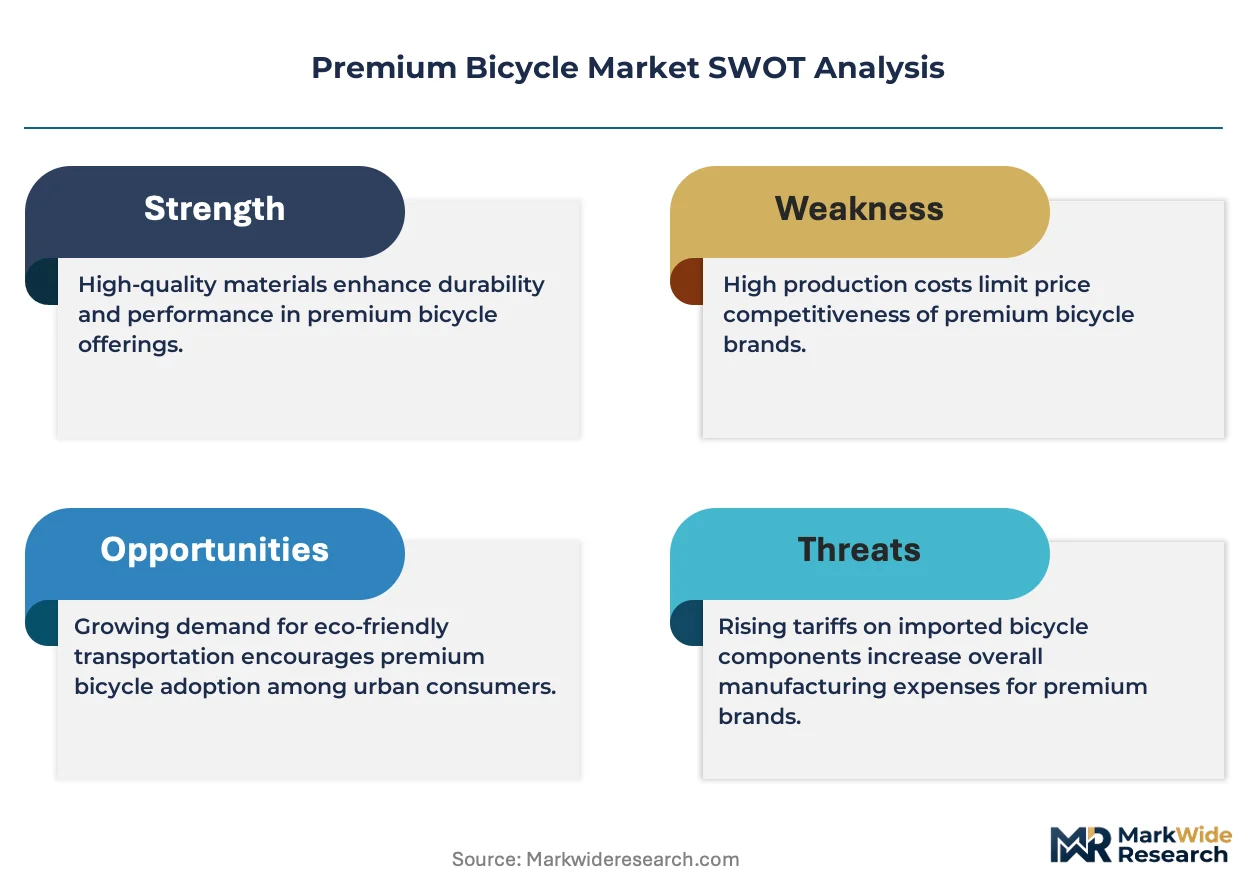
Top-tier vendors anchor premium carbon fiber road racing and electric bike categories, while mid-tier specialists populate aluminum hybrid and entry-premium mountain segments. The vendor base organizes around manufacturing scale, proprietary suspension technology, and direct-to-consumer channel control. Three archetypes dominate: vertically integrated frame manufacturers with captive carbon fiber layup capacity; component-technology licensors leveraging proprietary pedal-assist systems; and digital-native brands bypassing dealer networks through virtual fit platforms. Competitive moves concentrate on strategic partnerships with battery cell suppliers and geographic expansion into underpenetrated US urban commuter corridors.
Among Taiwan-based fabricators, Giant Manufacturing Co. Ltd. and Merida Industry Co. Ltd. occupy positions as scale-driven frame suppliers with upstream control over carbon fiber monocoque production. Trek Bicycle Corporation exemplifies the brand-architect archetype, anchoring North American market presence through domestic assembly and dealer network relationships. These three entities represent the dominant competitive anchors shaping procurement authority and pricing architecture across premium road racing and electric-assist categories.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Specialized Bicycle Components |
| Giant Manufacturing |
| Cannondale |
| Canyon Bicycles |
| BMC Switzerland |
| Merida Industry |
| Cervélo Cycles |
| Pon Holdings |
| Others |
Pricing and Supply Chain Analysis
Family-owned Taiwanese frame fabricators anchor carbon fiber supply, translating captive layup expertise into sustained pricing power over global brands while resisting margin compression from European assemblers.
Pricing Analysis
Short lead-time premiums separate urgent seasonal orders from standard contract cycles, with carbon fiber road frames commanding steep markups for expedited autoclave slots. Three-tier pricing structure across premium, standard, and economy levels reflects frame material grade and certification tier, with UN38.3 battery compliance adding cost layers to electric bike categories. Pricing pressure stems from lithium-ion raw material volatility compressing electric bike margins. Urban commuters exhibit highest price sensitivity, while cycling enthusiasts tolerate premiums for limited-edition collaborations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Singapore manage hub-and-spoke patterns for finished bicycle logistics. Manufacturing concentrates in Taiwan, China, and Vietnam, with Taichung clusters supplying monocoque carbon fiber construction. Raw material dependencies include Toray pre-preg carbon fiber, Shimano drivetrain components, and Panasonic or Samsung SDI battery cells. Single-source vulnerability concentrates in Taiwanese autoclave curing capacity. Distribution runs through authorized dealer networks for legacy brands and direct-to-consumer platforms for digital-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber layup technician scarcity props pricing across premium tiers, constraining volume expansion regardless of downstream demand signals.
For Market Incumbents: Hedge against Taiwanese supply concentration by qualifying secondary carbon fiber sources in China or Vietnam, while securing long-term lithium supply agreements to buffer battery cost swings. Defensive moves should prioritize CE marking pre-approval for smart electric bike systems under EU AI Act timelines. For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels targeting underpenetrated US urban commuter corridors in Austin, Denver, and Seattle, where protected lane construction reduces safety barriers. White-space exists in subscription-based ownership models for municipal fleet procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-technology licensors with proprietary pedal-assist systems in European manufacturing corridors, where EU Green Deal subsidies redirect assembly capacity. Long-term viability hinges on battery chemistry diversification beyond cobalt-dependent formulations. Watch EU carbon border adjustment mechanism implementation as inflection signal for sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Layup | Taiwanese autoclave capacity secures frame supply against geopolitical logistics bottlenecks. |
| Direct-to-Consumer Platform Launch | Virtual fit algorithms bypass dealer markups while capturing customer data in Austin and Denver corridors. |
| EU AI Act Smart-System Certification | Early collision-avoidance approval creates regulatory moats against late electric bike entrants. |
| Battery Supply Agreement Diversification | Long-term lithium contracts with South Korean suppliers buffer raw material price volatility. |
| Subscription Ownership Model Expansion | Copenhagen and Amsterdam municipal fleet procurement concentrates volume among commercial buyers. |
Research Methodology
Document review covered SEC filings from bicycle and component manufacturers, EU regulatory databases, and Taiwan EPA compliance records, complemented by interviews with supply chain directors at frame fabricators, procurement leads at global brand networks, and regulatory affairs specialists at electric bike system integrators. Secondary validation drew from customs trade data, KBA vehicle registration statistics, and municipal cycling infrastructure investment disclosures. Bottom-up demand modeling and top-down supply capacity assessment were triangulated against primary fieldwork.
Cross-referencing historical production volumes against panel input from manufacturing executives yielded growth trajectory estimates across the projection horizon. Segmentation dimensions modeled include frame material tier, propulsion architecture, end-use application, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements and substitution elasticity assumptions for car-to-bicycle mode shift. Forecast inputs incorporated EU Green Deal subsidy trajectories and lithium price curve projections.
Geopolitical logistics disruption, battery chemistry transition timelines, and REACH chemical compliance friction are the dominant revision risks warranting scenario analysis. Forecasts reflect documented assumptions around infrastructure buildout rates and subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Golf Bags Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Trampoline Market
Sports Equipment
Mouthguard Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Pitching Machine Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Cleat Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Power Sports Aftermarket Market