
 Diving Board Market | 2026-2036
Diving Board Market Size, Share, and Industry Trends Forecast 2026-2036
Diving Board Market Analytics
Certified aquatic equipment fabricators is reorganizing supply capacity as commercial pool builders face backlogs stretching into multiple seasons. S.R. Smith leverages its vertically integrated fiberglass molding operation to control raw material flow from resin sourcing to finished board lamination. Duraflex International anchors its position through exclusive partnerships with Olympic training facilities, sustaining premium pricing power in the competitive swimming segment.
A diving board is a cantilevered spring platform, typically manufactured from laminated fiberglass reinforced with epoxy resin or laminated hardwood cores with non-slip acrylic surfaces, designed to store and release kinetic energy for controlled aquatic entry. Fiberglass dominates product type volume due to superior weather resistance and reduced maintenance cycles versus wood alternatives. Competitive swimming applications command the highest specification thresholds and associated margin pools, while water parks drive volume through standardized replacement schedules across multi-unit installations.
Consumer Product Safety Commission guidelines and ASTM F2387 standards govern structural load testing and surface traction requirements, with state health departments adding inspection mandates that accelerate replacement of non-compliant legacy boards. The American National Standards Institute updates to aquatic facility codes are tightening deflection tolerances and hardware corrosion specifications, pushing municipal buyers toward certified manufacturers. Stakeholders must weigh certification compliance costs against the risk of exclusion from public procurement channels as standards converge across jurisdictions.
Market Dynamics
Fiberglass composite lamination is displacing wood-core construction as the dominant manufacturing platform, driven by municipal procurement mandates for reduced maintenance cycles and extended service life in high-UV environments.
Growth Catalysts
- Sun Belt Infrastructure Investment:Municipal aquatic centers in Florida, Texas, and Arizona are accelerating diving board replacement schedules as part of broader public recreation bond programs.
- ASTM F2387 Compliance Deadlines:State health departments are enforcing inspection mandates that disqualify legacy wood-core boards from continued operation, forcing accelerated upgrade cycles.
- Fiberglass Weather Resistance:Epoxy-resin lamination systems eliminate seasonal delamination risks that plague hardwood alternatives in freeze-thaw climates.
Market Restraints
- Resin Price Volatility:Epoxy and polyester feedstock costs fluctuate with petrochemical commodity indices, compressing margin predictability for laminated product manufacturers.
- Specialized Fabricator Concentration:Certified aquatic equipment production capacity clusters among a narrow base of vertically integrated molders, creating supply bottleneck risks during peak construction seasons.
- Competitive Swimming Specification Ceiling:Olympic-grade Duraflex platforms set performance benchmarks that limit premium pricing headroom for second-tier fiberglass alternatives.
Strategic Opportunities
- Water Park Standardization Contracts:Multi-unit installation operators seek single-source replacement programs across regional park networks, favoring manufacturers with national service infrastructure.
- ANSI Deflection Tolerance Updates:Tightened aquatic facility codes create certification-barrier entry points for compliant fabricators against non-certified import competition.
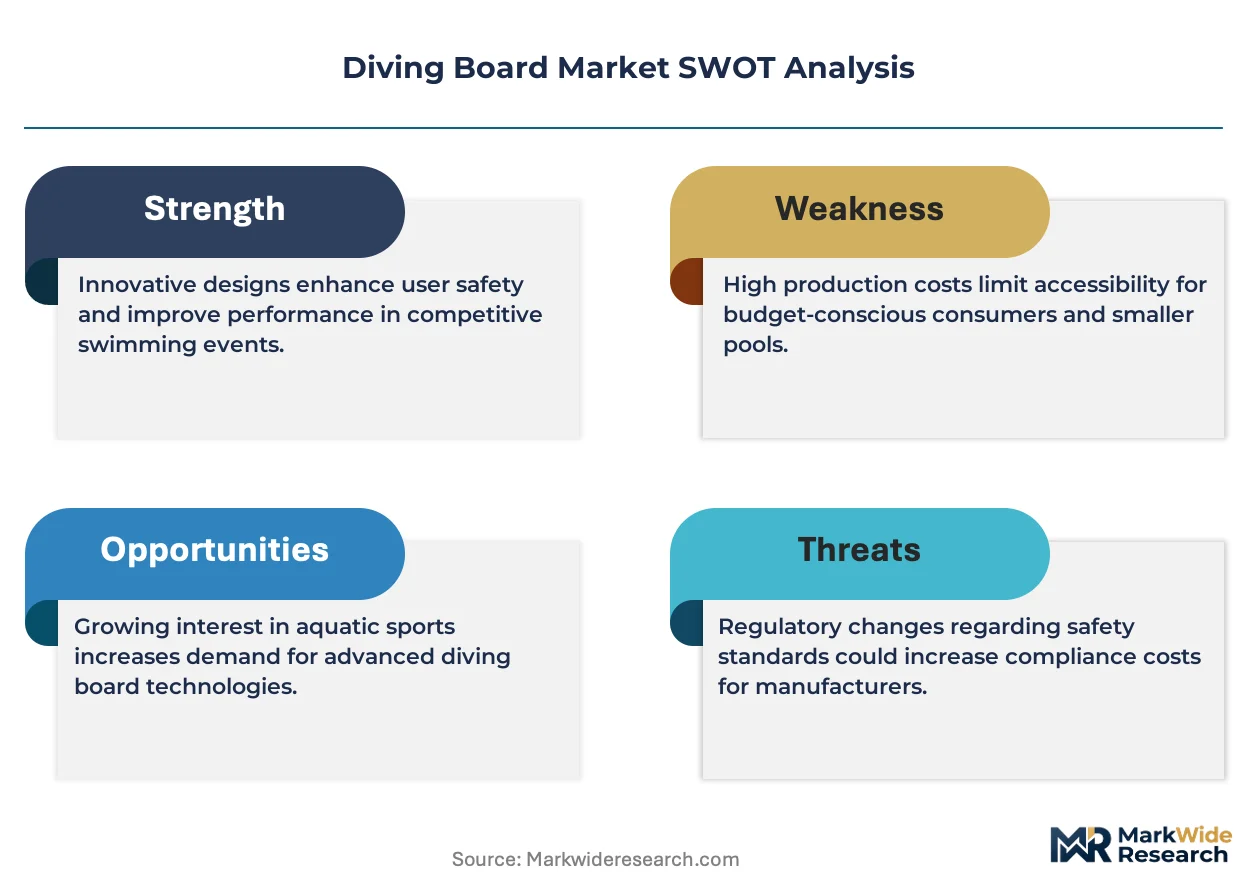
- Smart Sensor Integration:Embedded load-monitoring systems converging with facility management software enable predictive maintenance offerings for high-traffic municipal pools.
Industry Challenges
- Certified Lamination Technician Scarcity:Hand-layup and vacuum-infusion expertise for marine-grade fiberglass remains concentrated among legacy boat-building labor pools.
- Municipal Procurement Cycle Compression:Public-sector budget approval timelines frequently misalign with seasonal construction windows, forcing inventory carry costs on fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving Board Market |
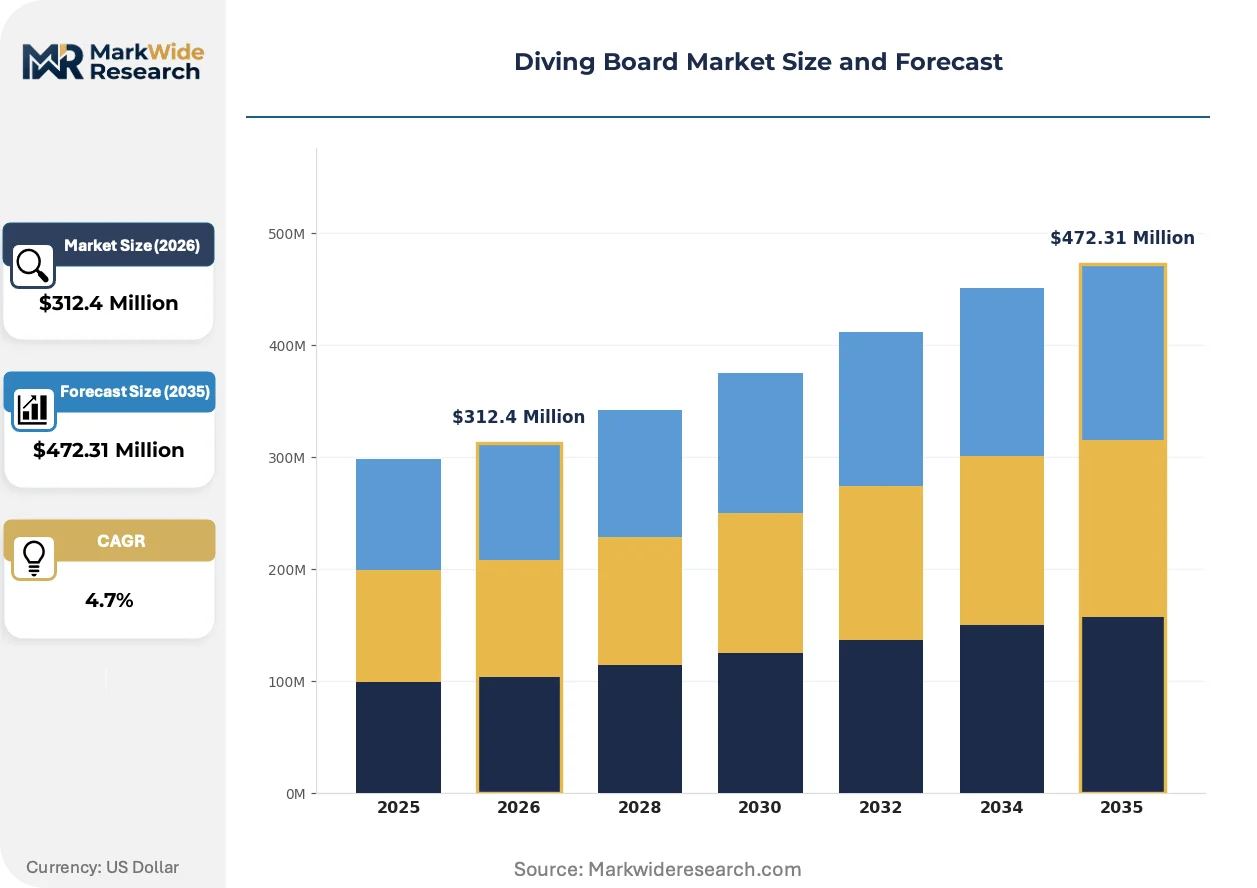
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Wood, Plastic, Stainless Steel Application: Recreational Pools, Competitive Swimming, Aquatic Centers, Water Parks Installation Type: In-Ground, Above-Ground, Portable, Removable Weight Capacity: 300 lbs, 400 lbs, 500 lbs, Others |
| Companies Covered | S.R. Smith, Duraflex International, Inter-Fab, Inc., Myrtha Pools, Diving Innovations, AquaCrete Enterprises, Natare, Kelley Technical Coatings, DG Designs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving Board Market Evolving Landscape
Material science advances and procurement digitization are restructuring how diving boards are specified, manufactured, and maintained across municipal and commercial aquatic facilities.
Carbon-fiber hybrid reinforcement is displacing pure fiberglass layups in competitive swimming platform construction. Elite training facilities specify these composites for reduced oscillation damping and precise spring-rate calibration. The technology is displacing traditional fiberglass-only specifications at the premium tier, compressing margin pools for conventional laminate suppliers.
ANSI updates to aquatic facility codes are tightening hardware corrosion specifications and deflection tolerances for diving equipment installations. These revisions disqualify legacy wood-core platforms from continued certification, forcing municipal buyers toward compliant fiberglass alternatives. Sun Belt states with year-round pool operations face the most accelerated replacement timelines.
Facility managers are consolidating vendor relationships through multi-year service agreements that bundle board replacement, inspection compliance, and hardware maintenance. This model is displacing transactional spot purchasing in municipal procurement channels. Texas and Florida municipalities are pioneering these integrated contracts as bond-funded recreation projects expand.
Diving Board Market Segmentation
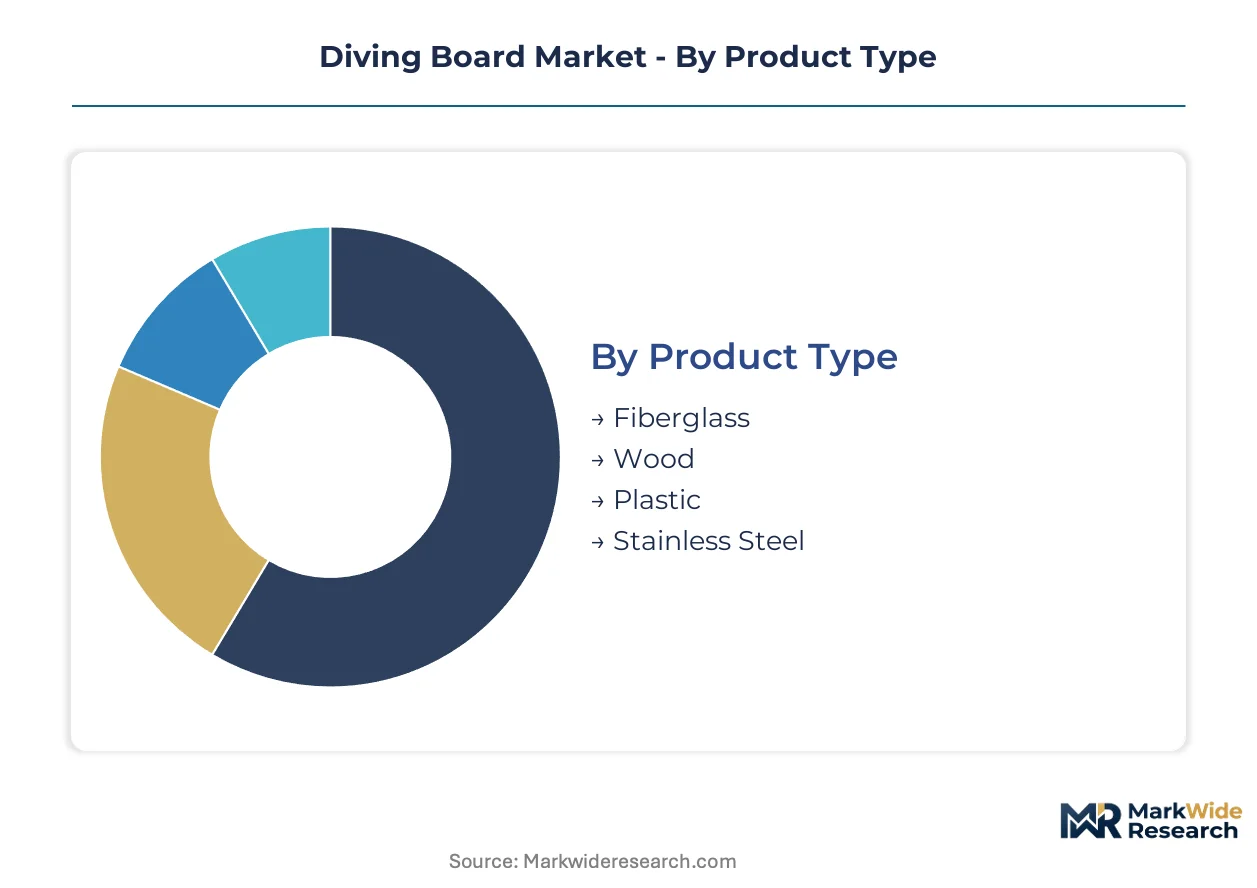
Material composition and installation permanence dictate procurement patterns across municipal and commercial aquatic facilities. Specification tiers diverge sharply between recreational replacement cycles and competitive swimming certification requirements.
Product Type:
Margin pools concentrate in laminated composite systems where epoxy-resin weather resistance commands premium positioning against legacy alternatives.
- Fiberglass:Epoxy-resin lamination with marine-grade gelcoat surfaces dominates municipal procurement for UV stability and freeze-thaw durability. Sun Belt aquatic centers in Florida, Texas, and Arizona specify these for reduced seasonal maintenance cycles.
- Wood:Laminated hardwood cores with non-slip acrylic surfaces persist in residential and budget-conscious recreational installations. ASTM F2387 compliance deadlines are disqualifying legacy wood-core boards from continued public facility operation.
- Plastic:Rotomolded polymer construction serves above-ground residential pools with lower load-bearing requirements.
- Stainless Steel:Marine-grade 316L alloy platforms anchor permanent high-traffic installations requiring maximum corrosion resistance.
Fiberglass holds installed capacity. Wood is rotating up the replacement volume rankings as compliance deadlines accelerate.
Application:
Volume concentrates in standardized replacement schedules across multi-unit water park networks, while competitive swimming sustains the highest specification thresholds.
- Recreational Pools:Residential and community pool installations drive replacement volume through seasonal wear cycles. Municipal bond programs in Sun Belt states are expanding public recreation infrastructure procurement.
- Competitive Swimming:Elite training facilities and Olympic venues demand precise spring-rate calibration and oscillation damping. Carbon-fiber hybrid reinforcement is displacing pure fiberglass layups at this specification tier.
- Aquatic Centers:Multi-use municipal facilities balance diving infrastructure with broader programming needs. ANSI aquatic facility code updates are tightening deflection tolerances for these installations.
- Water Parks:Regional park networks seek single-source replacement programs across multi-unit installations. Standardized hardware specifications favor manufacturers with national service infrastructure.
Recreational pools anchor volume share. Competitive swimming is climbing the fastest on margin contribution.
Installation Type:
Permanence of mounting determines hardware specification depth and inspection frequency requirements.
- In-Ground:Cantilevered concrete anchor systems with stainless steel fulcrum hardware serve permanent municipal and competitive installations. These carry the most stringent ASTM F2387 load-testing and surface traction mandates.
- Above-Ground:Deck-mounted bracket systems for residential and seasonal facilities face lower regulatory scrutiny but higher replacement frequency.
- Portable:Freestanding frame systems enable temporary event deployment and seasonal water park configuration changes.
- Removable:Quick-detach mounting hardware allows winterization and flexible pool programming in multi-use aquatic centers.
In-ground systems retain structural specification leadership. Above-ground is gaining share in residential retrofit markets.
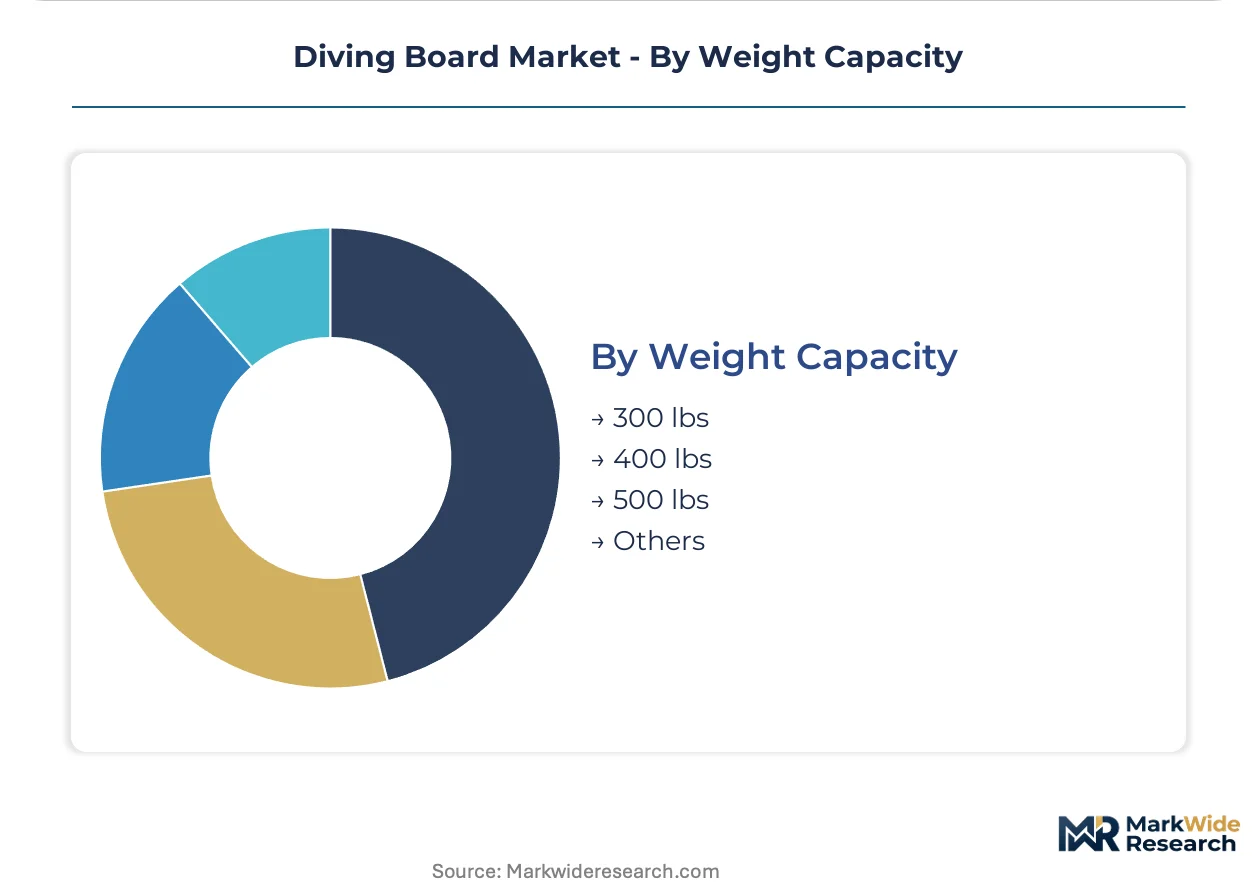
Weight Capacity:
Load rating tiers separate municipal liability compliance from residential cost optimization.
- 300 lbs:Residential and light-commercial specifications serve single-family pools and small community installations. These face the most price compression from import competition.
- 400 lbs:Standard municipal aquatic center rating balances accessibility requirements with structural hardware costs. Consumer Product Safety Commission guidelines inform minimum thresholds.
- 500 lbs:Heavy-duty platforms for high-traffic water parks and competitive training facilities where dynamic loading peaks exceed static ratings. ANSI deflection tolerance updates are tightening margin requirements.
- Others:Custom-engineered specifications for adaptive aquatic therapy and specialized training applications.
400 lbs holds municipal procurement volume. 500 lbs is expanding most quickly in water park standardization contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Consumer Product Safety Commission governs structural load testing and surface traction requirements across the United States, establishing baseline compliance thresholds that municipal aquatic centers must satisfy. State health departments layer additional inspection mandates atop federal guidelines. Sun Belt jurisdictions with year-round pool operations face accelerated replacement timelines.
United States
Florida, Texas, and Arizona municipal aquatic centers are expanding diving infrastructure through public recreation bond programs. The Consumer Product Safety Commission guidelines and ASTM F2387 standards enforce load-testing protocols that disqualify non-compliant legacy boards. Miami-Dade County and Phoenix metropolitan clusters concentrate replacement demand as cities modernize aging facilities.
Germany
Competitive swimming facilities and municipal aquatic centers drive specification-grade procurement across Bavaria and North Rhine-Westphalia. The DIN standards system and EU CE marking requirements govern structural safety and material performance for aquatic equipment. Stuttgart and Munich industrial clusters host specialized composite fabricators serving central European municipal buyers.
Australia
New South Wales and Queensland municipal pools face accelerated replacement cycles due to coastal corrosion exposure and UV degradation. Standards Australia and state health department inspection regimes enforce surface traction and hardware corrosion specifications. Sydney and Brisbane metropolitan aquatic centers concentrate demand for marine-grade fiberglass platforms.
Canada
Ontario and British Columbia municipal recreation departments are modernizing diving infrastructure through provincial infrastructure funding. Health Canada and CSA standards govern aquatic facility safety equipment requirements. Toronto and Vancouver metropolitan clusters lead procurement volume as freeze-thaw durability becomes a critical specification criterion.
Japan
Kanto and Kansai region municipal aquatic centers maintain rigorous replacement schedules for competitive training facilities. METI industrial standards and JIS certification requirements enforce deflection tolerance and material durability specifications. Tokyo and Osaka metropolitan clusters concentrate demand for precision-calibrated spring platforms.
Diving Board Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the diving board manufacturing structure. Vertically integrated fiberglass molders control resin sourcing through finished lamination, while specialized aquatic equipment fabricators concentrate on certification-compliant production. Three archetypes dominate: integrated composite manufacturers, Olympic-grade precision specialists, and regional service-focused suppliers. Capacity expansion and strategic partnerships represent the dominant competitive vectors as fabricators seek to secure municipal procurement channel access.
Among North American fabricators, S.R. Smith exemplifies the vertically integrated archetype through captive control over fiberglass molding operations. Duraflex International occupies a position within the precision-tier segment, anchoring competitive swimming specification standards. Inter-Fab, Inc. represents the service-oriented archetype, targeting regional municipal replacement programs with streamlined logistics infrastructure.
| Leading Market Players |
|---|
| S.R. Smith |
| Duraflex International |
| Inter-Fab, Inc. |
| Myrtha Pools |
| Diving Innovations |
| AquaCrete Enterprises |
| Natare |
| Kelley Technical Coatings |
| DG Designs |
| Others |
Value Network & Pricing Analysis
Capacity utilization at vertically integrated fiberglass molders in the United States concentrates pricing power among three dominant fabricators, while resin feedstock volatility compresses margin floors for second-tier competitors bidding on municipal contracts.
Pricing Analysis
Geographic price spreads between Sun Belt states and freeze-thaw climate municipalities reach double-digit percentage differentials driven by freight costs and UV-stabilization specifications. Three-tier pricing structure across Olympic-grade, municipal-certified, and residential-economy levels separates Duraflex platforms from S.R. Smith municipal lines and import alternatives. Pricing pressure stems from epoxy resin commodity index swings that compress laminate fabricator margins. Water park operators exhibit highest price sensitivity due to multi-unit volume procurement, while Olympic training facilities prioritize performance calibration over cost.
Supply Chain Analysis
The United States and China anchor global fiberglass roving and epoxy resin production for marine-grade lamination systems. Raw material flows draw from petrochemical feedstocks, bauxite-derived alumina for gelcoat pigments, and marine-grade stainless steel for fulcrum hardware. Single-source vulnerability concentrates in certified lamination technician labor pools inherited from legacy boat-building regions. Distribution runs through commercial pool builder networks and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as ANSI code updates and ASTM compliance deadlines fragment demand across certification tiers, creating niche entry points for specialized fabricators.
For Market Incumbents: Shield market position through captive resin sourcing agreements and accelerated certification investment ahead of deflection tolerance updates. Carbon-fiber hybrid displacement threatens premium fiberglass margin pools. Backward integration into epoxy formulation secures supply continuity during petrochemical volatility cycles. For New Entrants and Emerging Players: Anchor in water park standardization contracts across regional park networks where national service infrastructure gaps persist. Multi-year maintenance bundling represents the most penetrable procurement channel. Target above-ground residential retrofit segments with streamlined logistics models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among municipal service-contract operators with inspection compliance bundling. Long-term viability favors fabricators with captive lamination capacity and health department certification relationships. Monitor ANSI aquatic facility code revision timing as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Embedded load-monitoring systems enable predictive maintenance contracts with municipal aquatic centers. |
| Carbon-Fiber Hybrid Platform Development | Oscillation damping specifications at elite training facilities command premium positioning above fiberglass-only alternatives. |
| Multi-Year Service Agreement Expansion | Texas and Florida municipalities pioneer bundled replacement and inspection compliance contracts. |
| Certified Lamination Technician Training | Labor scarcity in vacuum-infusion expertise constrains capacity expansion for compliant fabricators. |
| Sun Belt Distribution Infrastructure | Florida and Arizona logistics hubs reduce freight spreads and accelerate municipal procurement response times. |
Research Methodology
The analysis maps fiberglass lamination systems, wood-core alternatives, and hybrid composite platforms, each validated through municipal procurement officers, commercial pool builders, aquatic facility managers, and certified equipment inspectors. Primary interview data triangulates against ASTM F2387 compliance records, Consumer Product Safety Commission guidelines, state health department inspection mandates, and municipal bond program disclosures. Bottom-up unit demand modeling reconciles with top-down market sizing across material composition tiers.
Consistency checks validate volume and value outputs against municipal recreation expenditure databases, commercial construction permit filings, and aquatic facility inspection cycle records. Segmentation dimensions span material type, application tier, installation permanence, and weight capacity rating across the projection horizon. CAGRs derive from replacement cycle analysis, compliance deadline impacts, and infrastructure investment trajectories. Forecast inputs incorporate resin commodity index projections and ANSI code revision timelines.
Material uncertainties — resin price volatility, certification standard revisions, and municipal budget approval delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding compliance enforcement intensity and infrastructure bond passage rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
BMX Bikes Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Golf Shoes Market