
 Europe E-Commerce Home Fitness Products Market | 2026-2036
Europe E-Commerce Home Fitness Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Commerce Home Fitness Products Market Analytics
Modular equipment bundles that pair base hardware with subscription content tiers is recalibrating how European consumers evaluate lifetime cost against upfront spend. Technogym leverages its Italian manufacturing heritage to sustain premium positioning across direct-to-consumer channels. Decathlon S.A. anchors mass-market volume through its integrated marketplace and private-label ecosystem. Sport-Tiedje GmbH specializes in curated assortments that dominate German-speaking markets for specialist home gym configurations.
Europe e-commerce home fitness products encompass physical training apparatus sold through digital channels, typically featuring steel or aluminum frames with polymer-coated grips, Bluetooth connectivity modules, and foldable designs rated for residential floor loads. These products serve consumers seeking structured exercise capacity without facility membership commitments. Treadmills and connected cardio equipment capture the largest revenue share due to higher unit values and replacement cycles. Resistance bands and kettlebells represent the fastest-expanding segments as entry-price flexibility attracts first-time home gym builders. The B2C channel controls dominant transaction volume, though B2B procurement by corporate wellness programs is emerging as a concentrated margin pool.
The EU Green Deal and national implementations of the Digital Product Passport framework impose material traceability requirements on fitness equipment sold across member states. CE marking under the Machinery Directive governs structural safety standards for motorized equipment, while REACH compliance restricts hazardous substances in polymer components. ECHA substance evaluations are tightening restrictions on certain flame retardants used in treadmill belt assemblies. Stakeholders must monitor evolving extended producer responsibility schemes that will shift end-of-life collection costs toward original manufacturers.
Market Dynamics
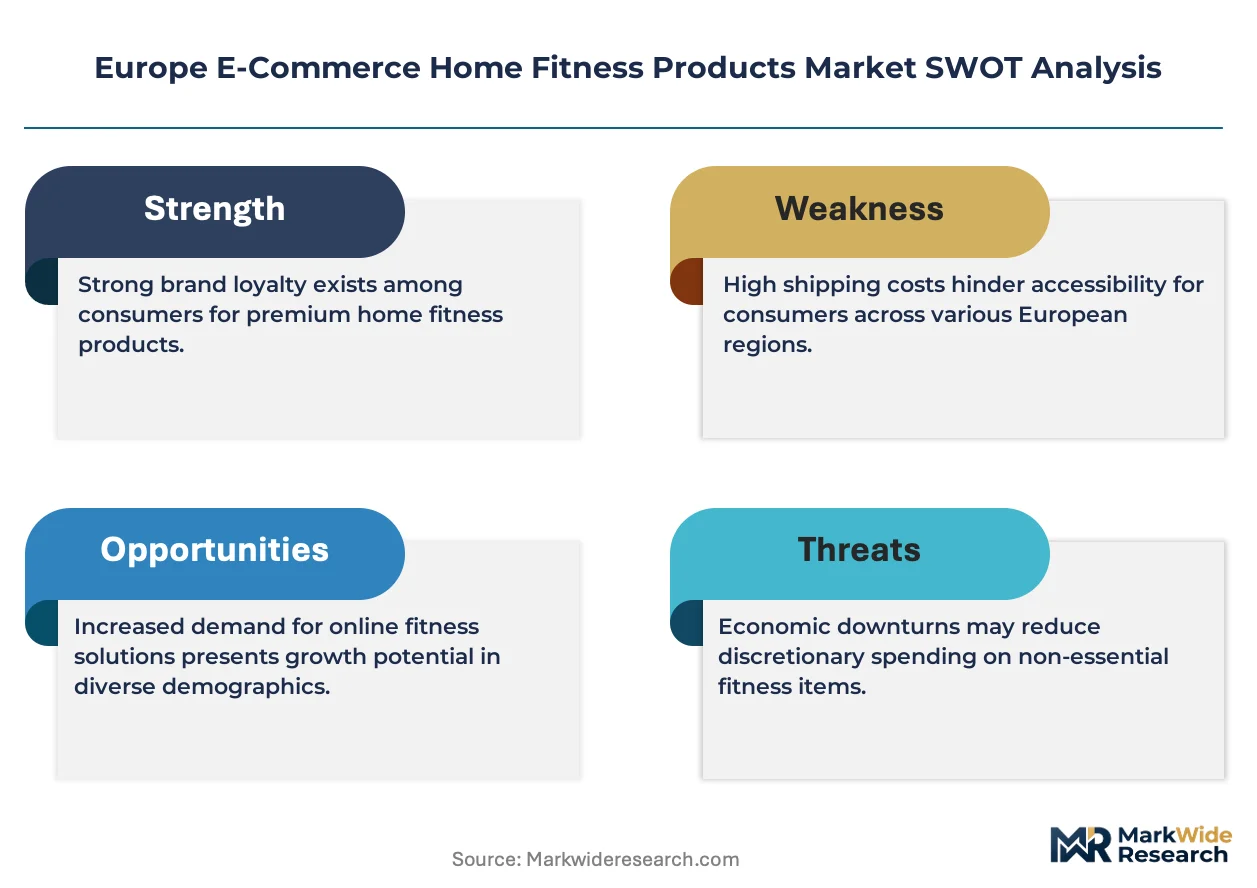
The EU Green Deal's Digital Product Passport requirements are forcing fitness equipment manufacturers to restructure material traceability systems across their entire supply chains, with compliance costs concentrating on cross-border sellers serving multiple member states.
Growth Catalysts
- Digital Product Passport mandates:The EU Green Deal is accelerating material disclosure investments among manufacturers seeking seamless cross-border distribution. This regulatory pressure is compressing compliance timelines for polymer and electronic component sourcing.
- Urban apartment densification:German and French metropolitan housing stock is driving demand for foldable equipment rated for residential floor loads. Space-constrained consumers prioritize Bluetooth-connected compact units over traditional gym apparatus.
- Corporate wellness procurement:B2B channels are emerging as concentrated margin pools as employers expand structured exercise benefits. This end-use shift is diversifying revenue beyond individual consumer transactions.
Market Restraints
- Aluminum and steel input volatility:Frame material costs fluctuate with energy-intensive European smelter output. Price instability compresses margin predictability for equipment with long production lead times.
- CE marking complexity under Machinery Directive:Motorized treadmill certification requires extensive third-party testing for structural safety. This regulatory friction extends time-to-market for new connected cardio entrants.
- Facility membership substitution:Hybrid work normalization has renewed commercial gym competitiveness in some urban clusters. This substitute threat caps home equipment penetration in certain demographic segments.
Strategic Opportunities
- Nordic broadband infrastructure:Sweden and Norway's fiber penetration rates support latency-dependent live fitness streaming. These markets remain underpenetrated relative to German e-commerce maturity.
- Extended producer responsibility schemes:Evolving EU-wide end-of-life collection mandates will favor manufacturers with established reverse logistics. Early compliance investment creates competitive moats against smaller cross-border sellers.
- AI form-correction convergence:Computer vision integration with resistance equipment is expanding addressable markets beyond cardio-traditionalists. This technology pairing targets form-conscious strength training adopters.
Industry Challenges
- REACH substance evaluation timelines:ECHA restrictions on treadmill belt flame retardants require rapid reformulation. Certification delays risk inventory obsolescence for non-compliant stock.
- Last-mile delivery capacity constraints:Bulky equipment strains established networks in high-penetration Western European markets. Carrier specialization gaps increase damage rates and return processing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Commerce Home Fitness Products Market |
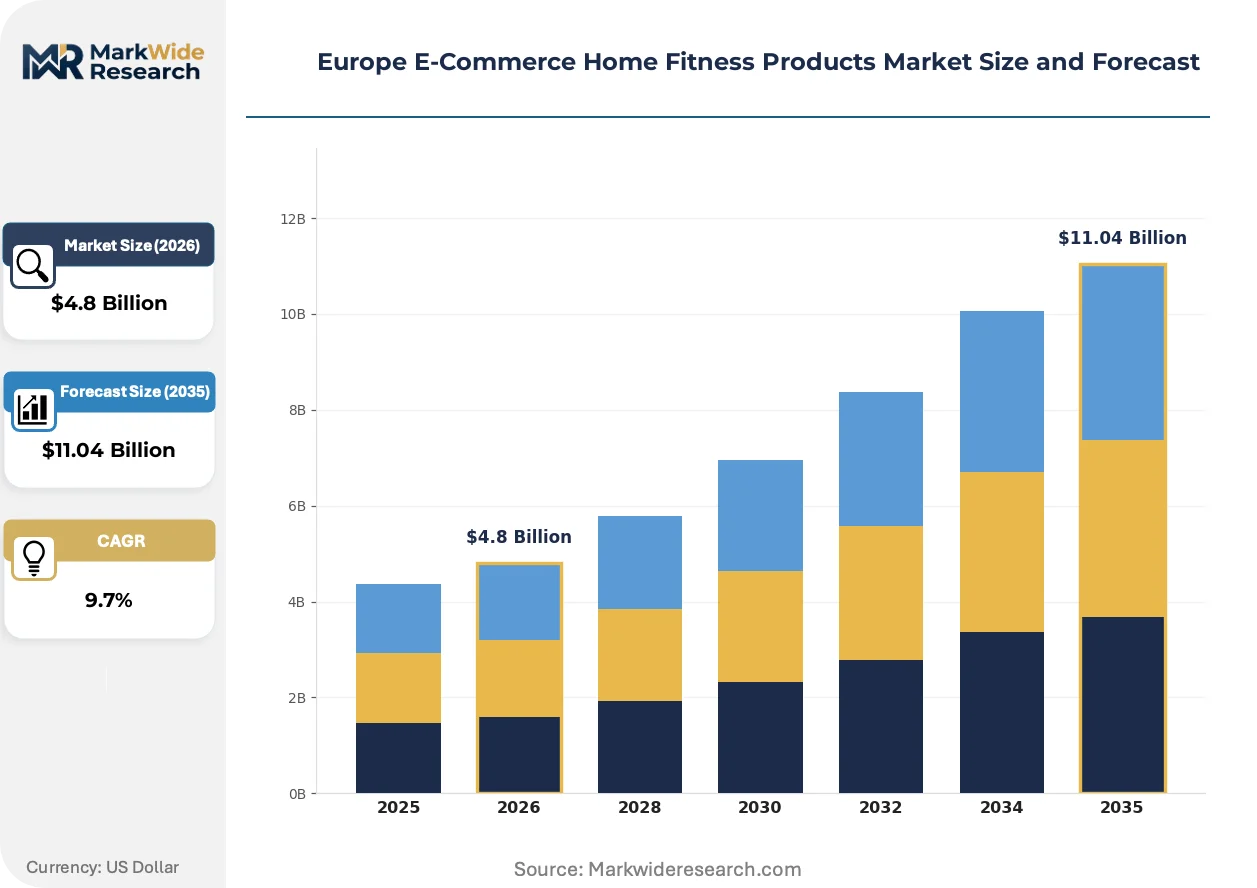
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Dumbbells, Resistance Bands, Kettlebells End User: Athletes, Fitness Enthusiasts, General Consumers, Home Users Distribution Channel: Online Retailers, Brand Websites, Marketplaces, Fitness Equipment Stores Customer Type: B2B, B2C, Government, Educational Institutions |
| Companies Covered | Sport-Thieme GmbH, Technogym, Johnson Health Tech, Life Fitness, Peloton Interactive, Inc., Sport-Tiedje GmbH, Horizon Fitness, Decathlon S.A., Hammer Sport AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Commerce Home Fitness Products Market Evolving Landscape
Subscription-content bundling is restructuring how European consumers evaluate lifetime equipment costs, while regulatory material traceability and procurement model evolution are simultaneously reshaping competitive requirements across the value chain.
Biometric-integrated resistance equipment is expanding into form-critical training segments previously dominated by personal trainer dependency. Serious home gym builders in German-speaking markets are adopting sensor-embedded kettlebells and adjustable dumbbells at accelerating rates. This hardware-software convergence is compressing addressable markets for standalone content platforms without captive device ecosystems.
REACH compliance deadlines for polymer component disclosure are forcing reformulation investments across treadmill and connected bike manufacturers. The European Chemicals Agency's tightening flame retardant evaluations are extending R&D cycles for belt and grip assemblies. Motorized equipment categories face the steepest compliance cost escalation as material traceability requirements phase in through 2027.
Modular subscription tiers are displacing upfront-heavy purchasing patterns among first-time home gym builders. Entry-price flexibility through resistance bands and basic connectivity modules is capturing consumers who previously deferred equipment investment. This behavioral shift is most visible in French and Spanish markets where facility membership culture historically dominated exercise expenditure patterns.
Europe E-Commerce Home Fitness Products Market Segmentation
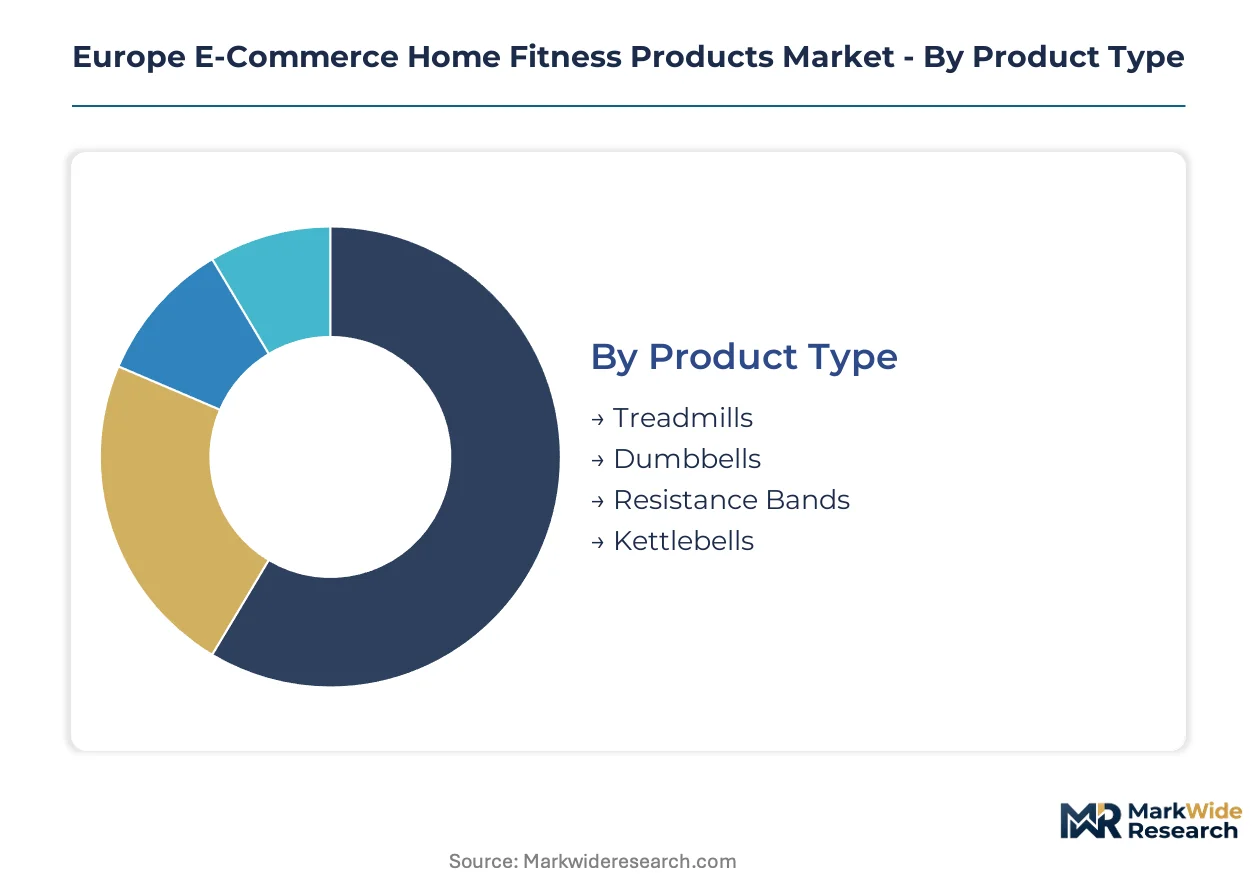
Equipment configuration and procurement pathway determine margin architecture for European sellers navigating the Digital Product Passport compliance burden. Segmentation reveals where subscription bundling and corporate procurement are restructuring traditional transaction patterns.
Product Type:
Frame material sourcing and connectivity module integration concentrate manufacturing investment in motorized equipment categories.
- Treadmills:Steel-framed motorized units with polymer belt assemblies and Bluetooth telemetry modules. German and French urban apartments drive demand for foldable designs rated at residential floor loads. CE marking under the Machinery Directive extends certification timelines for new entrants.
- Dumbbells:Cast iron or rubber-encased hexagonal sets with modular weight increment systems. Serious home gym builders in German-speaking markets favor quick-adjust mechanisms paired with form-tracking applications. REACH compliance for grip polymer coatings adds reformulation costs.
- Resistance Bands:Latex or fabric-loop configurations with color-coded tension ratings. Entry-price flexibility captures first-time home gym builders in Spanish and Italian markets.
- Kettlebells:Cast iron or steel shells with powder-coated finishes and flat bases for stability. Sensor-embedded variants are gaining traction among form-conscious strength training adopters.
Treadmills absorb the bulk of installed capacity; resistance bands are expanding most quickly.
End User:
Training intensity and equipment durability requirements stratify purchasing behavior across user commitment levels.
- Athletes:Performance-calibrated equipment with power measurement accuracy and competition-grade specifications. Nordic markets with established fiber infrastructure support latency-dependent live coaching integration.
- Fitness Enthusiasts:Connected hardware with subscription content tiers and biometric tracking capabilities. This segment concentrates revenue in Western European markets with mature e-commerce fulfillment networks.
- General Consumers:Entry-level apparatus prioritizing storage efficiency and basic functionality. Price sensitivity shapes procurement through marketplace channels.
- Home Users:Space-constrained households seeking multi-functional compact configurations. French metropolitan housing stock drives preference for foldable and stowable designs.
Fitness enthusiasts absorb the bulk of installed capacity; athletes are climbing the fastest.
Distribution Channel:
Last-mile delivery specialization and return processing capacity determine viable channel participation for bulky equipment categories.
- Online Retailers:Aggregator platforms with established carrier relationships for residential freight. Damage rate differentials favor sellers with specialized fitness equipment handling protocols.
- Brand Websites:Direct-to-consumer channels capturing subscription bundling economics. Technogym leverages Italian manufacturing heritage to sustain premium positioning through owned digital storefronts.
- Marketplaces:Third-party platforms with integrated fulfillment and customer acquisition scale. Decathlon S.A. anchors mass-market volume through its integrated marketplace ecosystem.
- Fitness Equipment Stores:Hybrid digital-physical channels offering showroom experience with e-commerce transaction completion. Specialist curation dominates German-speaking markets for complex home gym configurations.
Brand websites absorb the bulk of installed capacity; marketplaces are gaining share fastest.
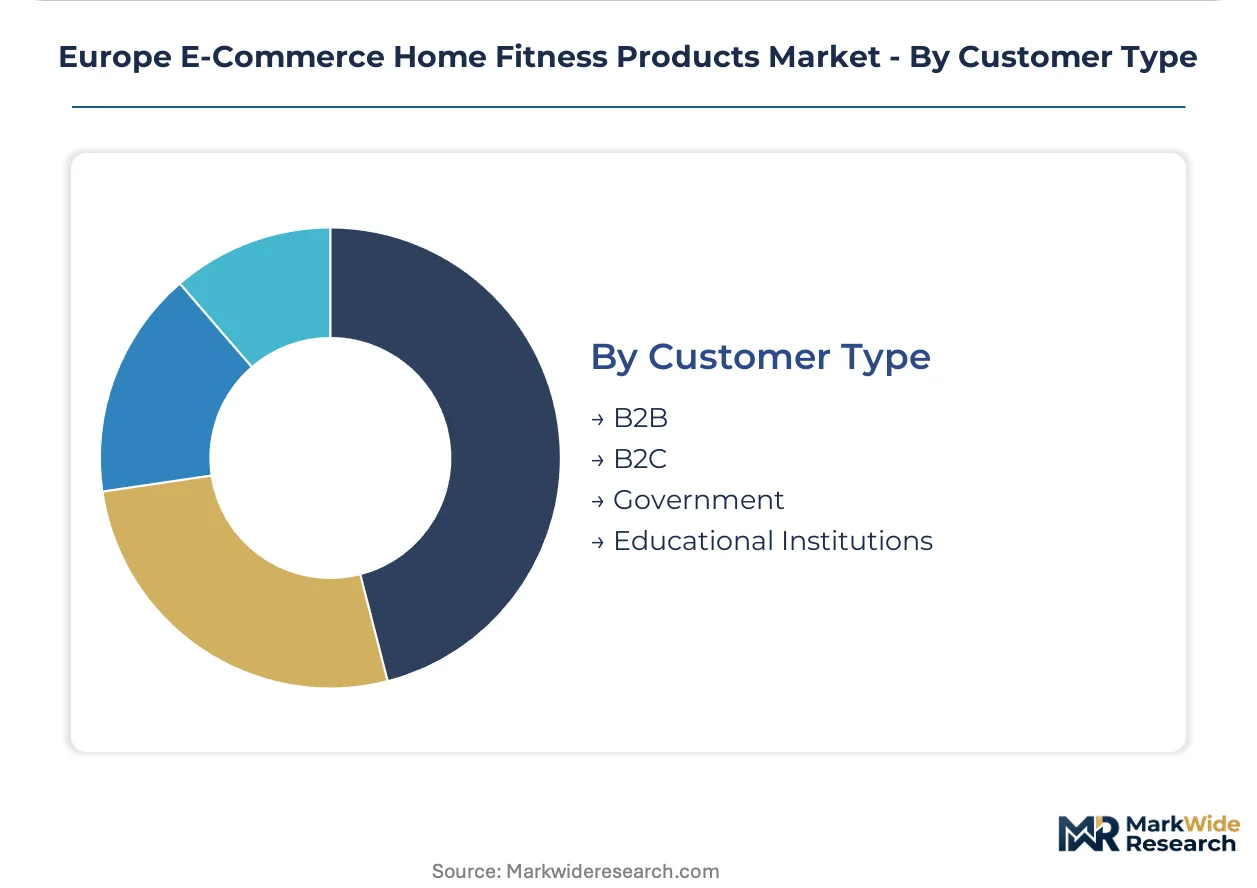
Customer Type:
Procurement scale and contract structure determine margin stability and inventory predictability for manufacturers.
- B2B:Corporate wellness programs and commercial facility procurement with concentrated volume and extended payment terms. This segment is emerging as a margin pool distinct from individual consumer transactions.
- B2C:Individual household purchases through digital channels with immediate payment and higher return rates. Subscription-content bundling is restructuring lifetime value calculations.
- Government:Public sector procurement for institutional fitness facilities and community health programs. Extended producer responsibility schemes will shift end-of-life collection costs toward original manufacturers.
- Educational Institutions:University and school district procurement for campus recreation infrastructure. Budget cycles and compliance documentation requirements extend sales timelines.
B2C absorbs the bulk of installed capacity; B2B is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux special economic zones concentrating e-commerce fulfillment infrastructure are accelerating cross-border distribution capacity for bulky fitness equipment across Western Europe.
Germany
Metropolitan apartment densification in Berlin and Munich drives demand for foldable treadmills rated at residential floor loads. CE marking under the Machinery Directive imposes structural safety certification burdens on motorized equipment entrants. The Rhine-Ruhr industrial corridor hosts specialized last-mile carriers developing damage-reduction protocols for steel-framed apparatus.
France
Parisian housing stock constraints prioritize compact connected equipment with Bluetooth telemetry modules. The EU Green Deal's Digital Product Passport requirements are compressing material traceability timelines for polymer component sourcing. Lyon clusters specialist fitness equipment stores offering hybrid showroom-digital transaction completion.
United Kingdom
Post-pandemic hybrid work normalization has renewed facility membership substitution threats in London urban clusters. REACH compliance through ECHA governs hazardous substance restrictions in rubber-encased dumbbell grip coatings. Manchester logistics hubs are expanding residential freight capacity for bulky resistance equipment categories.
Italy
Manufacturing heritage in Emilia-Romagna sustains premium positioning for direct-to-consumer steel-frame production. Extended producer responsibility schemes under EU-wide mandates will shift end-of-life collection costs toward original equipment manufacturers. Milan serves as the primary demand concentration for biometric-integrated resistance training configurations.
Netherlands
Randstad broadband penetration supports latency-dependent live fitness streaming integration with connected hardware. The EU AI Act's emerging framework will govern computer vision applications for form-correction technologies. Rotterdam port infrastructure facilitates aluminum and steel frame material imports for regional assembly operations.
Europe E-Commerce Home Fitness Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment configuration tiers, producing a bifurcated structure where scale-driven mass-market volume sits adjacent to curated premium positioning. Consolidation pressure concentrates among motorized equipment categories with extended CE marking timelines. Three archetypes dominate: integrated marketplace operators with captive private-label ecosystems, heritage manufacturers leveraging direct-to-consumer digital storefronts, and specialist retailers dominating German-speaking markets through curated assortment depth. Competitive moves center on subscription-content bundling economics and reverse logistics infrastructure investment for extended producer responsibility compliance.
Within the heritage manufacturer tier, Technogym and Hammer Sport AG exemplify Italian and German manufacturing-origin positioning respectively. Sport-Tiedje GmbH anchors specialist curation archetypes in German-speaking markets. Decathlon S.A. occupies the integrated marketplace position with mass-market volume concentration. These three represent distinct strategic postures without implying specific operational or financial performance claims.
| Leading Market Players |
|---|
| Sport-Thieme GmbH |
| Technogym |
| Johnson Health Tech |
| Life Fitness |
| Peloton Interactive, Inc. |
| Sport-Tiedje GmbH |
| Horizon Fitness |
| Decathlon S.A. |
| Hammer Sport AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap manufacturers concentrated in Italy's Emilia-Romagna and Germany's North Rhine-Westphalia regions anchor supply discipline through conservative capacity expansion and selective customer onboarding. Their ownership structure insulates pricing from quarterly earnings pressure while embedding quality premiums into direct-to-consumer channels.
Pricing Analysis
Margin tightening in motorized equipment tiers reflects aluminum smelter energy cost pass-through and extended CE marking timelines under the Machinery Directive. Three-tier pricing structure across premium, standard, and economy levels stratifies by connectivity module integration and after-sales service bundling. Cost compression accelerates in entry-level resistance categories as private-label marketplace volume concentrates procurement leverage. General consumers exhibit highest price sensitivity, while fitness enthusiasts absorb premium positioning for subscription-tethered hardware.
Supply Chain Analysis
Regional distribution centers in the Netherlands' Randstad and Germany's Rhine-Ruhr corridor aggregate steel frame imports from Italian and German mills before last-mile fragmentation. Raw material dependencies center on European aluminum smelter output, polymer compounds for grip coatings, and electronic modules from Asian component suppliers. Single-source vulnerability concentrates in specialized treadmill motor assemblies. Distribution runs through hybrid online-offline channels with carrier specialization determining damage rate differentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Last-mile delivery capacity constraints in high-penetration Western European markets prop pricing power for sellers with established carrier relationships and damage-reduction protocols.
For Market Incumbents: Hedge aluminum input volatility through long-term smelter offtake agreements indexed to energy futures. Backward integration into polymer compounding for grip assemblies defends margin position against REACH reformulation cost spikes. CE marking certification bottlenecks under the Machinery Directive create defensive moats against fast-follower entrants in motorized categories.
For New Entrants and Emerging Players: The EU Green Deal's Digital Product Passport requirements in Germany and France open a window for compliance-native entrants without legacy material traceability debt. Nordic broadband infrastructure in Sweden and Norway offers underpenetrated white-space for latency-dependent live fitness streaming hardware. Corporate wellness procurement channels provide concentrated B2B entry with extended payment terms that favor working capital-light business models.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist retailers with curated German-speaking market presence and established reverse logistics infrastructure. Extended producer responsibility scheme compliance investments will separate viable acquirers from stranded cross-border sellers. The signal to watch is carrier specialization gaps in residential freight capacity as a predictor of damage-rate-driven margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Content Bundling | Restructures lifetime value calculations for hardware purchasers across French and Spanish markets. |
| Reverse Logistics Investment | Positions manufacturers for EU-wide extended producer responsibility cost shifts toward original equipment makers. |
| CE Marking Acceleration | Compresses time-to-market for motorized entrants under Machinery Directive structural safety requirements. |
| Biometric Hardware Integration | Expands addressable markets beyond cardio-traditionalists into form-critical strength training segments. |
| Nordic Market Entry | Captures fiber-penetration-supported live streaming integration in underpenetrated Scandinavian geographies. |
Research Methodology
Trade databases, EU regulatory filings, and carrier logistics disclosures formed the secondary backbone for supply chain mapping and compliance timeline assessment. Primary interviews with e-commerce operations directors, fitness equipment procurement managers, last-mile carrier specialists, and polymer compound suppliers validated demand patterns and input cost trajectories. Bottom-up equipment shipment data triangulated against top-down consumer expenditure surveys across the analysis window.
Bottom-up modeling aggregated transaction-level data by product type, end user commitment tier, distribution channel, and customer procurement mode. Top-down validation cross-referenced household fitness expenditure surveys with broadband penetration and residential floor load specifications by metropolitan housing stock. CAGRs derived from installed base replacement cycles and subscription attach rate assumptions. Aluminum smelter output volatility and REACH substance evaluation timelines fed industry-specific scenario inputs.
Caveats apply where ECHA flame retardant restriction timelines or carrier capacity constraints could materially shift the outlook. Forecasts reflect documented assumptions around regulatory phase-in schedules and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Lateral Fitness Equipment Market