
 Shuffleboard Equipment Market | 2026-2036
Shuffleboard Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Shuffleboard Equipment Market Analytics
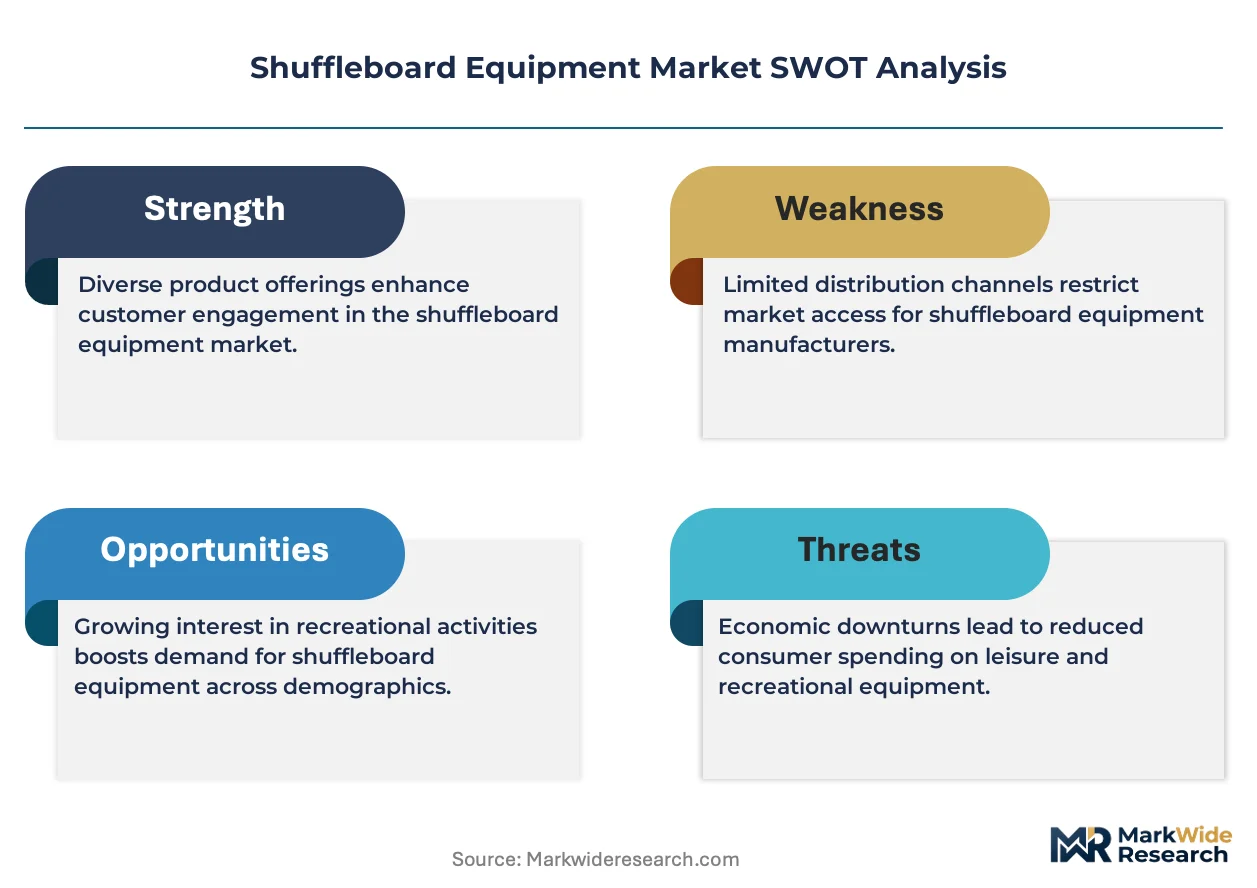
Artisan woodworking expertise is bifurcating the competitive landscape as heritage craftsmanship becomes scarcer and premium table makers compete for limited talent pools. Champion Shuffleboard leverages its Florida-based production heritage to sustain domestic manufacturing scale. Hudson Shuffleboards anchors its position through specialized custom builds for commercial venues. Brunswick Billiards competes by extending its century-old brand recognition across billiards-adjacent categories.
Shuffleboard equipment encompasses playing surfaces, cues, discs, and accessories engineered to standardized dimensions with polymer or wax-coated finishes that enable controlled puck glide. Tables typically range from nine to twenty-two feet in length, with playing fields constructed from maple, polymer, or synthetic composites designed to maintain flatness within thousandths of an inch. Indoor shuffleboards dominate residential and club installations where climate control preserves surface integrity, while outdoor models built from marine-grade aluminum and weather-resistant composites are capturing growing share in hospitality settings. Composite materials represent the fastest-expanding segment as manufacturers balance weight reduction with structural stability.
The Consumer Product Safety Commission oversees recreational equipment safety standards in the United States, while ISO 8124 governs physical and mechanical properties for consumer products in international trade. California's Proposition 65 chemical disclosure requirements shape material sourcing decisions for manufacturers distributing in the state. Stakeholders must monitor evolving state-level chemical regulations and composite material certifications to maintain market access and avoid compliance-driven supply disruptions.
Market Dynamics
Composite material substitution is bifurcating the shuffleboard equipment supply base as polymer-surface manufacturers capture share from traditional maple-craft workshops, compressing lead times while fragmenting artisan capacity across North American production clusters.
Growth Catalysts
- REACH chemical compliance:European manufacturers reformulating wax coatings and polymer resins to meet ECHA substance restrictions are unlocking export access across EU member states, expanding addressable market for compliant producers.
- Hospitality venue installation:Bar and restaurant operators in the United States are specifying shuffleboard tables as core entertainment infrastructure, driving replacement cycles and new-location procurement.
- Climate-adaptive surface engineering:Marine-grade aluminum framing and UV-stabilized polymer playing fields are enabling outdoor table deployments in coastal and high-humidity environments previously unsuitable for wood construction.
Market Restraints
- Heritage craft labor scarcity:Master woodworkers capable of hand-planing competition-grade maple surfaces to thousandth-inch tolerances are retiring faster than apprenticeship pipelines replenish, constraining premium table output.
- Prop 65 disclosure burden:California's chemical warning requirements force manufacturers to reformulate finishes or absorb labeling costs, creating compliance friction for national distribution strategies.
- Multi-purpose entertainment substitution:Electronic gaming systems and interactive projection tables are capturing share in space-constrained venues, pressuring shuffleboard's position in commercial entertainment budgets.
Strategic Opportunities
- ISO 8124 certification pathway:Manufacturers achieving international toy safety standard compliance can access institutional procurement channels in educational and municipal recreation sectors previously blocked by liability concerns.
- Direct-to-venue configuration platforms:Online customization tools allowing hospitality buyers to specify dimensions, finishes, and branding are compressing sales cycles and capturing margin previously allocated to distributor networks.
- Modular outdoor system convergence:Tables designed for rapid assembly and seasonal storage are penetrating residential markets in northern climates where permanent installation was previously impractical.
Industry Challenges
- Surface flatness certification backlog:Third-party metrology labs capable of verifying playing-field tolerance to competition standards operate with 8-12 week queues, delaying commercial venue openings and triggering penalty clauses.
- Legacy woodshop digitization:Artisan manufacturers lacking CAD-CAM integration struggle to produce repeatable documentation for warranty claims and insurance underwriting, limiting contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shuffleboard Equipment Market |
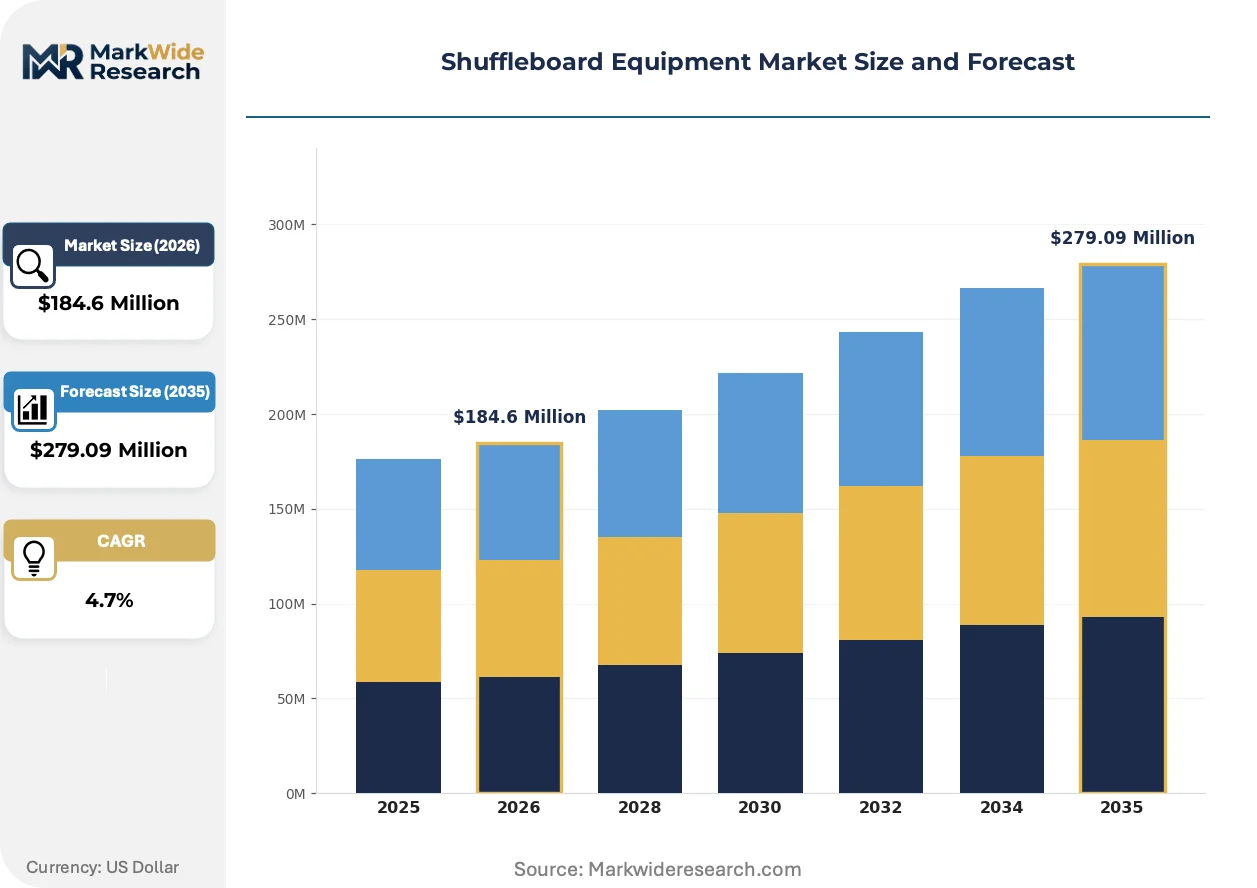
| Market Size in 2026 | $184.6 Million |
| Market Size in 2035 | $279.09 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Shuffleboards, Outdoor Shuffleboards, Shuffleboard Cues, Shuffleboard Discs Material: Wood, Plastic, Composite, Aluminum End User: Residential Users, Recreational Facilities, Clubs, Educational Institutions Application: Leisure Centers, Home Use, Tournaments, Bar/Restaurant |
| Companies Covered | Allen Shuffleboard, Berner Billiards, Champion Shuffleboard, RS Barcelona, Imperial USA, Hudson Shuffleboards, Playcraft, California House, Brunswick Billiards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shuffleboard Equipment Market Evolving Landscape
Material science advances and regulatory chemistry requirements are reshaping how shuffleboard equipment is engineered, sourced, and certified across residential and commercial channels.
Polymer composite playing surfaces are displacing traditional maple construction in mid-market and outdoor segments. Marine-grade polymer formulations from suppliers in Florida and California now constitute the fastest-growing input category for hospitality-specified tables. This material transition is bifurcating the competitive landscape into volume polymer producers and scarcity-positioned heritage woodshops.
California Proposition 65 enforcement is intensifying scrutiny of wax coatings and polymer stabilizers used in playing surface finishes. Manufacturers distributing in the state must reformulate or disclose chemical content, raising compliance costs and favoring larger producers with in-house regulatory capacity. The commercial venue segment is most affected, as liability-averse hospitality chains demand documented compliance from suppliers.
Configuration-driven procurement is replacing catalog-based ordering in the hospitality vertical. Venue operators now specify table dimensions, finish grades, and accessory packages through manufacturer-hosted platforms, compressing the specification-to-delivery timeline. This pattern is most visible in Texas and Florida, where multi-location bar operators standardize equipment across rolling expansion programs.
Shuffleboard Equipment Market Segmentation
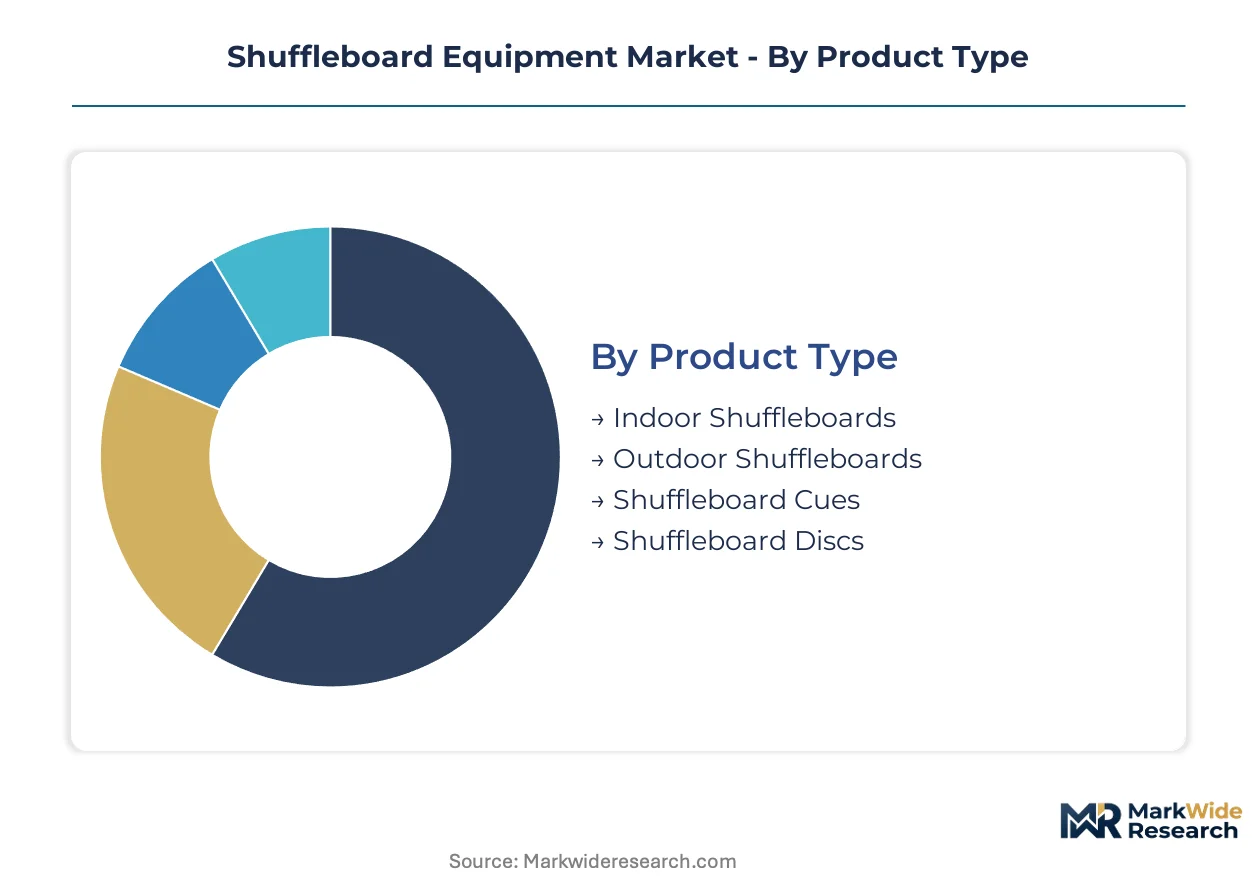
Shuffleboard equipment manufacturers navigate distinct demand profiles across product configurations, material specifications, and venue types. Segment-specific procurement patterns shape inventory planning, certification requirements, and distribution channel selection throughout the value chain.
Product Type:
Domestic production clusters in Florida and Wisconsin supply the bulk of indoor table demand, while export-oriented manufacturers in California and Texas concentrate on outdoor models engineered for climate resilience.
- Indoor Shuffleboards:Climate-controlled maple or polymer surfaces ranging nine to twenty-two feet dominate residential basements and private clubs. Demand concentrates in the United States Northeast and Midwest where winter installation cycles drive seasonal procurement spikes.
- Outdoor Shuffleboards:Marine-grade aluminum framing with UV-stabilized polymer playing fields enables deployment in coastal hospitality venues. Florida and California bar operators specify these for patio entertainment infrastructure, replacing wood tables that warp in humidity.
- Shuffleboard Cues:Standardized 6-8 foot lengths with polymer or hardwood shafts, weighted for controlled disc delivery. Recreational facilities in Texas purchase replacement cues in volume bundles.
- Shuffleboard Discs:Regulation-weight polymer pucks with stainless steel ball bearings for consistent glide. Tournament organizers in Wisconsin enforce strict weight tolerances.
Indoor Shuffleboards holds the largest share; momentum sits with Outdoor Shuffleboards.
Material:
Cost tier stratification separates premium heritage craftsmanship from volume polymer production, with mid-market buyers trading off durability against aesthetic authenticity.
- Wood:Hard maple harvested from Great Lakes basin forests, hand-planed to thousandth-inch flatness tolerances for competition-grade surfaces. Master woodshop capacity constraints in Pennsylvania and Ohio limit output.
- Composite:Glass-reinforced polymer formulations from Florida suppliers deliver structural stability at reduced weight. Hospitality procurement teams in California specify composite for multi-location rollout standardization.
- Plastic:Injection-molded polymer components for cues, discs, and budget table surfaces. Mass retailers in Texas stock entry-level plastic tables for seasonal residential demand.
- Aluminum:Marine-grade extrusions for outdoor table framing with anodized finishes resisting salt corrosion. Coastal venue operators in Florida require aluminum substructures for warranty compliance.
Wood commands premium positioning; composite gains share fastest in commercial specifications.
End User:
Customer type determines specification complexity, with institutional buyers demanding documentation that residential purchasers rarely require.
- Residential Users:Basement and game room installations favoring nine to fourteen-foot tables with traditional maple aesthetics. Midwest homeowners drive replacement cycles during renovation seasons.
- Recreational Facilities:Municipal parks departments and community centers requiring ISO 8124 certification for liability coverage. Procurement in Wisconsin and Minnesota emphasizes documented safety compliance.
- Clubs:Private membership venues specifying tournament-grade twenty-two foot tables with climate control systems. Florida retirement communities maintain dedicated shuffleboard courts.
- Educational Institutions:K-12 and university recreation programs selecting durable composite tables for high-traffic student use. Texas school districts bundle equipment into athletic facility bonds.
Recreational Facilities generate the highest volume; Educational Institutions show the steepest expansion trajectory.
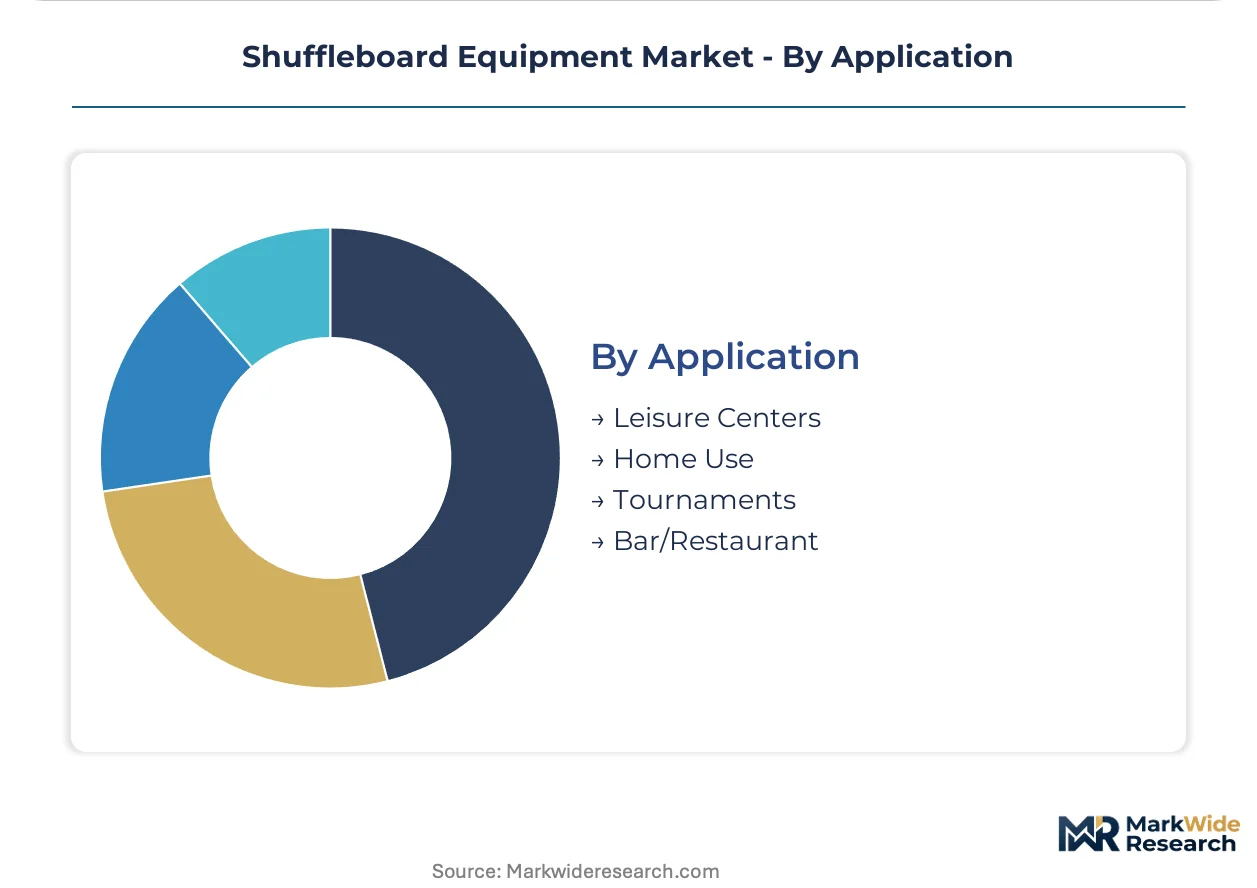
Application:
Volume concentration varies sharply by venue type, with hospitality-driven replacement cycles outpacing residential purchase frequency.
- Bar/Restaurant:Entertainment-focused hospitality operators in Texas and Florida specify branded tables as core infrastructure. Multi-location chains standardize dimensions across rolling expansion programs.
- Home Use:Discretionary purchases tied to housing market activity and basement finishing projects. Northeast residential buyers favor traditional maple construction.
- Leisure Centers:Dedicated recreation facilities combining shuffleboard with complementary entertainment options. California operators integrate tables into mixed-activity membership packages.
- Tournaments:Sanctioned competition venues requiring certified flatness verification from third-party metrology labs. Wisconsin hosts the largest concentration of tournament-grade facilities.
Bar/Restaurant absorbs the most units; Leisure Centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between hospitality-driven coastal markets and residential-focused interior regions. Florida and California operators prioritize weather-resistant outdoor installations, while Midwest buyers concentrate procurement in basement renovation seasons.
United States
Bar and restaurant chains in Texas and Florida specify shuffleboard tables as core entertainment infrastructure, driving replacement cycles across multi-location rollouts. The Consumer Product Safety Commission oversees recreational equipment safety standards, shaping liability documentation requirements for commercial venues. Domestic production clusters in Florida and Wisconsin supply differentiated product lines for climate-specific applications.
Canada
Municipal recreation departments in Ontario and Quebec procure shuffleboard equipment for community centers and seasonal outdoor installations. Health Canada regulates consumer product safety under the Canada Consumer Product Safety Act, mandating documentation for institutional procurement channels. Toronto-area distributors coordinate cross-border supply from Wisconsin woodshops and Florida polymer manufacturers.
Germany
Hotel operators in Bavaria and North Rhine-Westphalia integrate shuffleboard into wellness-focused entertainment offerings for domestic tourists. ECHA substance restrictions under REACH compliance frameworks reformulate wax coatings and polymer resins for EU market access. Frankfurt-based importers source composite tables from North American manufacturers seeking European distribution expansion.
United Kingdom
Private membership clubs in London and Southeast England specify tournament-grade tables for competitive play and social programming. The UK's Office for Product Safety and Standards enforces consumer protection regulations affecting import documentation and warranty terms. Manchester-area hospitality groups standardize equipment specifications across regional bar portfolios.
Australia
Coastal hospitality venues in New South Wales and Queensland deploy marine-grade aluminum tables for outdoor patio entertainment. The Australian Competition and Consumer Commission administers product safety standards that shape import certification requirements. Sydney-based distributors coordinate procurement from California and Florida manufacturers with UV-stabilized polymer expertise.
Shuffleboard Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with heritage woodcraft workshops competing against volume polymer producers for differentiated market positions. The competitive terrain separates into three strategic archetypes: domestic-scale manufacturers with regional production heritage, custom-build specialists serving commercial venues, and brand-extend incumbents from adjacent recreation categories. Consolidation pressure operates through vertical integration into polymer resin supply and direct-to-venue digital configuration platforms that disintermediate traditional distributor networks.
Among heritage-positioned fabricators, Champion Shuffleboard anchors the domestic manufacturing tier through its Florida production base, while Hudson Shuffleboards occupies the custom-build specialist position for commercial venue specifications. Brunswick Billiards represents the brand-extension archetype, leveraging century-old recognition across billiards-adjacent recreation equipment categories.
| Leading Market Players |
|---|
| Allen Shuffleboard |
| Berner Billiards |
| Champion Shuffleboard |
| RS Barcelona |
| Imperial USA |
| Hudson Shuffleboards |
| Playcraft |
| California House |
| Brunswick Billiards |
| Others |
Value Network & Pricing Analysis
Eight-to-twelve-week metrology certification queues compress commercial venue opening timelines and amplify pricing power for third-party verification labs, while inventory buffers at Florida polymer suppliers insulate hospitality buyers from maple-craft capacity constraints. This lead-time asymmetry between composite and heritage wood inputs concentrates margin capture with volume manufacturers serving multi-location bar chains.
Pricing Analysis
Project-based contracts dominate hospitality procurement, with venue operators negotiating bundled specifications across dimensions, finishes, and accessory packages. Three-tier pricing structure across premium, standard, and economy levels separates tournament-grade maple tables with documented flatness certification from polymer-composite mid-market units and injection-molded plastic entry-level surfaces. Cost compression in the plastic tier is intensifying because mass retailers in Texas are consolidating seasonal purchase volumes. Recreational facilities exhibit highest price sensitivity due to municipal budget cycles, while private clubs demonstrate lowest sensitivity given membership-funded capital reserves.
Supply Chain Analysis
Great Lakes basin maple harvesting capacity operates as a chokepoint constraining competition-grade surface output, with Pennsylvania and Ohio woodshops drawing from finite master craftsman pools. Marine-grade polymer formulations from Florida and California suppliers, aluminum extrusions from coastal metal fabricators, and UV-stabilized coatings from specialty chemical producers constitute core input dependencies. Single-source vulnerability in heritage craft labor exposes premium table manufacturers to retirement-driven supply disruption. Distribution runs through manufacturer-hosted configuration platforms disintermediating traditional distributor networks for hospitality buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-venue digital configuration platforms are reconstituting shuffleboard equipment procurement as a platform-economics inflection, with interoperability between customization tools and hospitality property management systems enabling rolling standardization across multi-location bar portfolios.
For Market Incumbents: Compound brand equity in heritage craftsmanship by capturing retiring master woodworker expertise through structured documentation protocols and CAD-CAM integration investments. Defend against polymer substitution by establishing in-house regulatory capacity for California Proposition 65 compliance, insulating national distribution from disclosure-driven margin erosion. Prioritize backward integration into marine-grade polymer resin supply to secure input cost stability for hospitality-specified outdoor tables.
For New Entrants and Emerging Players: Anchor in modular outdoor system convergence for northern climate residential markets where seasonal storage requirements previously blocked permanent installation. Target educational institutions in Texas exhibiting steepest expansion trajectory through ISO 8124 certification pathway, accessing liability-averse procurement channels. Pursue direct-to-venue configuration platform development capturing margin previously allocated to distributor networks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because artisan woodshop digitization gaps and metrology certification backlogs favor scaled producers with in-house compliance and documentation capacity. Acquisition targets should demonstrate captive polymer formulation expertise or established hospitality chain relationships. Monitor ECHA substance restriction enforcement intensity as signal for REACH-compliant manufacturer valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Venue Configuration Platform | Compresses sales cycles for Florida and Texas hospitality chains standardizing equipment specifications. |
| Marine-Grade Polymer Formulation Investment | Secures input supply for UV-stabilized outdoor tables displacing wood in coastal venues. |
| ISO 8124 Certification Pathway | Unlocks institutional procurement in Wisconsin and Minnesota municipal recreation departments. |
| CAD-CAM Integration for Heritage Woodshops | Enables repeatable documentation for warranty claims and insurance underwriting eligibility. |
| California Proposition 65 Compliance Program | Maintains market access for national distribution strategies without reformulation-driven cost absorption. |
Research Methodology
A spread of perspectives from commercial venue procurement managers, heritage woodshop master craftsmen, polymer formulation chemists, and hospitality chain operations directors converged on the working assumptions shaping this analysis. Primary fieldwork with Florida and Wisconsin production clusters combined with secondary validation from CPSC safety standard filings, ECHA substance restriction databases, California Office of Environmental Health Hazard Assessment enforcement records, and SEC 10-K disclosures from adjacent recreation equipment manufacturers. Bottom-up unit economics from individual table configurations triangulated against top-down addressable market sizing across bar, restaurant, and institutional end-use segments.
Segmentation dimensions modeled span product type, material specification, end-user category, and application venue across the analysis window. CAGRs derive from installed base replacement cycle analysis, hospitality expansion program tracking, and climate-adaptive product substitution elasticity. Industry-specific forecast inputs include bar and restaurant opening rates in Texas and Florida, maple craft labor pipeline graduation data from Pennsylvania trade programs, and polymer resin price indices from Gulf Coast chemical suppliers.
Decision-makers should treat outputs as directional under assumptions of sustained hospitality venue investment and stable regulatory enforcement intensity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA substance restriction scope expansion and California chemical disclosure enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Football Equipment Market
Sports Equipment
Cleat Market
Sports Equipment
Riding Gear Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Crampon Market
Sports Equipment
Power Sports Aftermarket Market