
 Global Sports Sunglasses Market | 2026-2036
Global Sports Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Sunglasses Market Foresight
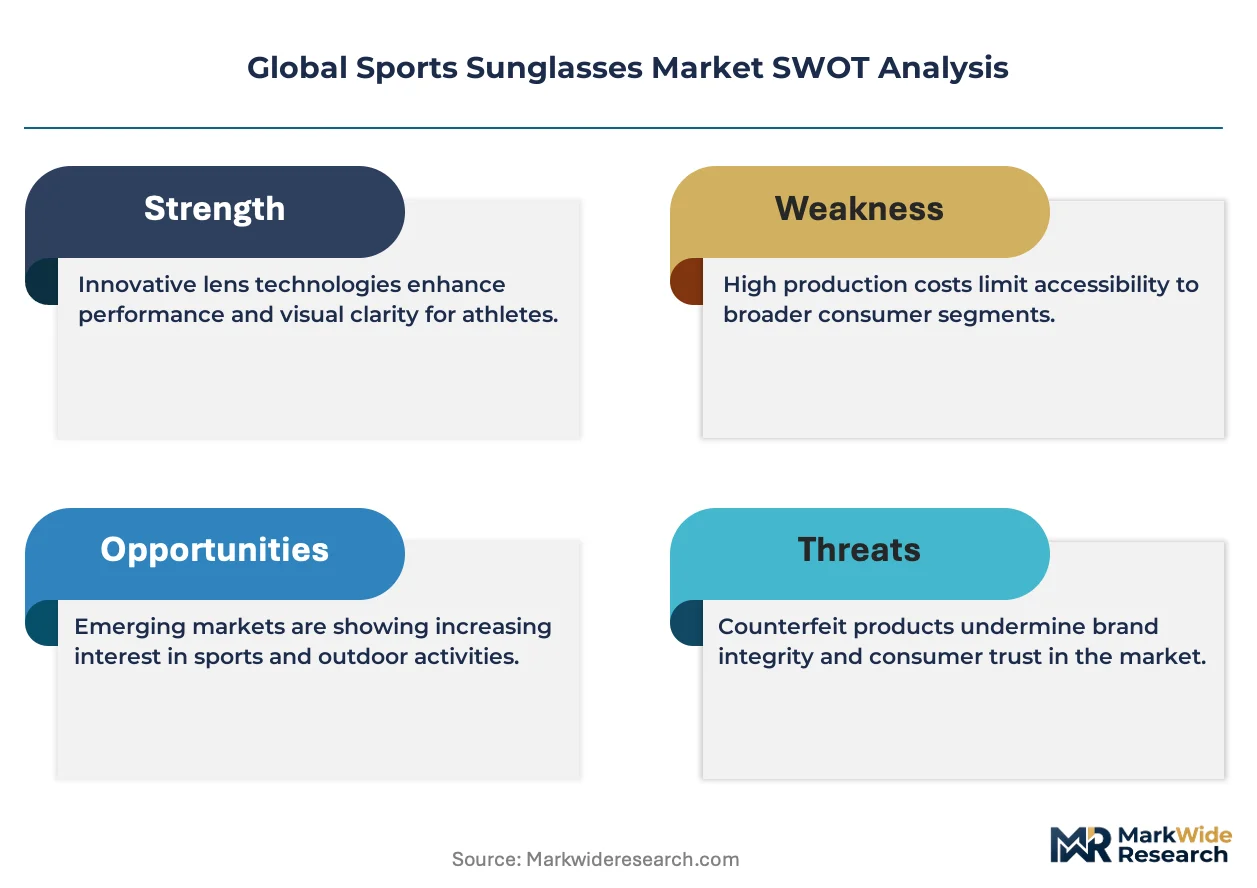
The EU Green Deal is hardening sustainability requirements for sports eyewear manufacturers serving European cycling and running segments. EssilorLuxottica leverages its integrated lens manufacturing footprint to control raw material sourcing for performance optics. Oakley anchors its position through proprietary Plutonite lens technology developed in-house at its Foothill Ranch facility. Rudy Project specializes in aerodynamic frame geometries targeting triathlon and road racing disciplines.
Global sports sunglasses are protective eyewear systems engineered with impact-rated polycarbonate or Trivex lenses, typically featuring 100% UVA/UVB blocking, anti-fog ventilation channels, and hydrophobic oleophobic coatings designed to maintain optical clarity during high-exertion activities. Polarized lenses dominate value contribution in fishing and water sports applications where glare reduction commands measurable performance premiums. Photochromic variants are gaining structural share among trail runners and cyclists who transition between shaded canopy and exposed ridge conditions within single sessions. Amateur athletes represent the deepest volume pool, though professional athletes and sponsored teams concentrate brand leverage and technical co-development relationships.
The US FDA regulates sports sunglasses as medical devices when labeled with UV protection claims, while the EU's REACH framework restricts hazardous substances in frame polymers and lens coatings. ISO 12312-1 governs impact resistance and optical quality benchmarks that manufacturers must satisfy for CE marking and cross-border market access. Stakeholders should monitor evolving national implementations of the EU AI Act's product safety protocols and track California's Proposition 65 enforcement patterns for bisphenol-A disclosures in polycarbonate frames.
Market Dynamics
The EU Green Deal's extended producer responsibility framework is forcing frame manufacturers toward recycled nylon and bio-based lens coatings, restructuring material sourcing decisions across European supply chains.
Growth Catalysts
- REACH substance restrictions:The EU's REACH framework bans hazardous chemicals in frame polymers, accelerating compliant material innovation among suppliers serving German and French cycling clubs.
- Photochromic lens technology:Trail runners and cyclists traversing shaded-to-exposed terrain drive replacement demand for adaptive optics that eliminate multiple-eyewear carry.
- California coastal clusters:High-altitude UV exposure in coastal California and the Swiss Alps compresses replacement cycles for premium polarized systems.
Market Restraints
- Polycarbonate resin volatility:Bisphenol-A feedstock costs fluctuate with petrochemical pricing, squeezing margin structures for injection-molded frame producers.
- Asian optical component concentration:Precision lens grinding and anti-reflective coating capacity clusters in coastal Chinese manufacturing zones, creating single-source vulnerability.
- FDA medical device classification:UV protection claims trigger US medical device regulations, extending certification timelines and compliance documentation burdens.
Strategic Opportunities
- Australian amateur racing leagues:Procurement expansion by cycling clubs across Victoria and New South Wales creates volume anchor demand for mid-tier performance eyewear.
- EU AI Act product safety protocols:Early compliance with emerging algorithmic product standards positions suppliers for preferential placement in automated quality verification systems.
- Direct-to-athlete subscription models:Replacement lens programs and seasonal frame exchanges bypass traditional retail markup structures.
Industry Challenges
- ISO 12312-1 certification bottlenecks:Impact resistance and optical quality testing capacity constraints delay CE marking for new product introductions.
- California Proposition 65 disclosure complexity:Bisphenol-A warning requirements for polycarbonate frames demand reformulation or extensive labeling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Sunglasses Market |
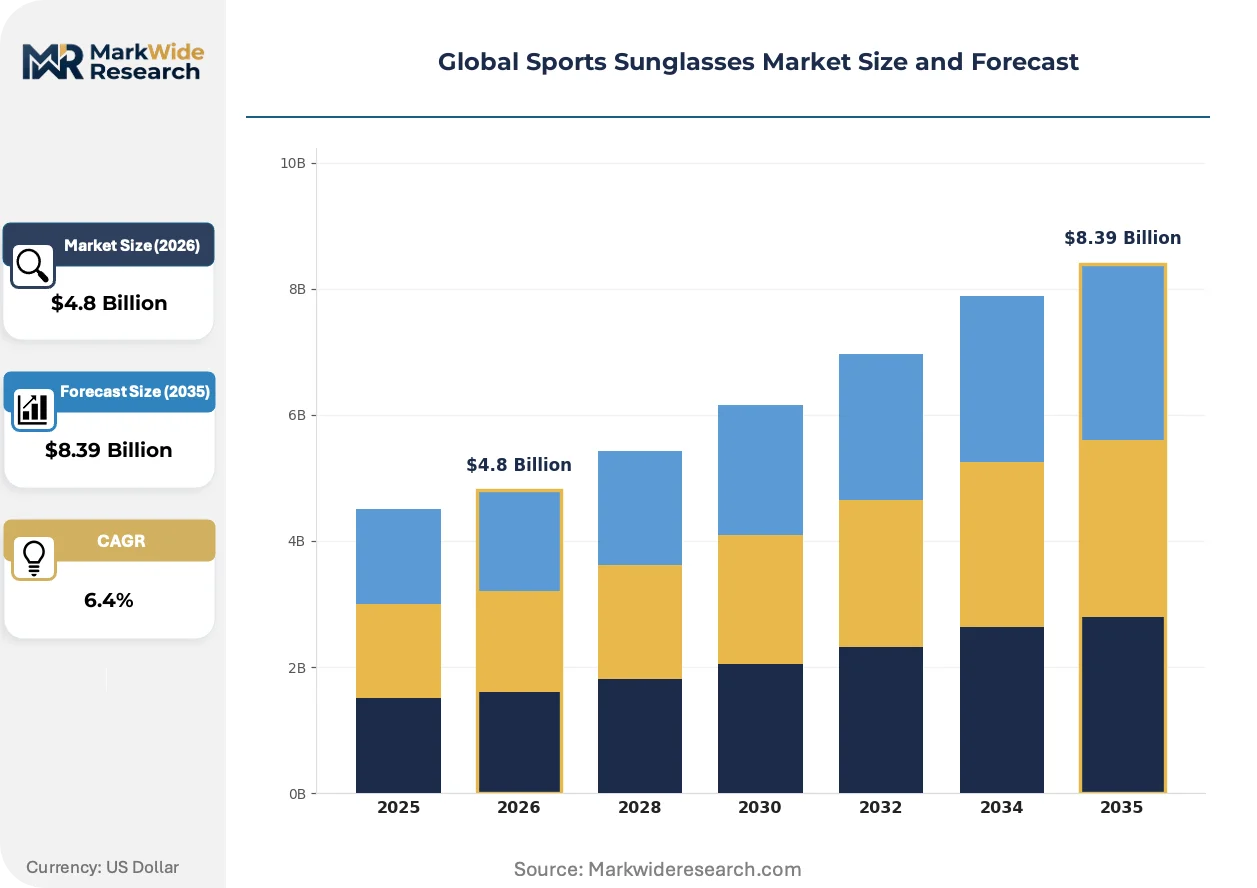
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarized, Non-Polarized, Photochromic, Prescription Customer Type: Amateur Athletes, Professional Athletes, Sports Enthusiasts, Casual Users End Use: Cycling, Running, Fishing, Golf Material: Polycarbonate, Nylon, Metal, Trivex |
| Companies Covered | Adidas Eyewear, Safilo Group, EssilorLuxottica, Rudy Project, Decathlon, Oakley, Under Armour, Smith Optics, Nike Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Sunglasses Market Shifts & Advancements
Material science breakthroughs and regulatory stringency are compressing product development cycles while fragmenting distribution pathways across amateur and professional athlete segments.
Bio-based thermoplastic elastomers derived from castor oil are overtaking petroleum-derived frame materials in premium positioning. Triathlon and road racing specialists specify these polymers for weight reduction and skin-contact biocompatibility. The shift is overtaking conventional ABS and TR-90 formulations in European markets where sustainability claims drive purchase decisions.
REACH authorization procedures for novel chemical substances in lens coatings are tightening substance approval timelines. Manufacturers reformulating hydrophobic oleophobic layers face extended pre-market notification periods. German and French frame assemblers are responding by qualifying existing approved substances rather than pursuing novel chemistry pathways.
Amateur athletes now source replacement lenses through manufacturer-direct portals rather than specialty retail channels. This pattern disrupts traditional optician and sporting goods store margins while concentrating brand relationship data with original equipment suppliers. The behavioral shift is most pronounced in US and Australian markets where digital-native consumers dominate cycling and running club memberships.
Global Sports Sunglasses Market Segmentation
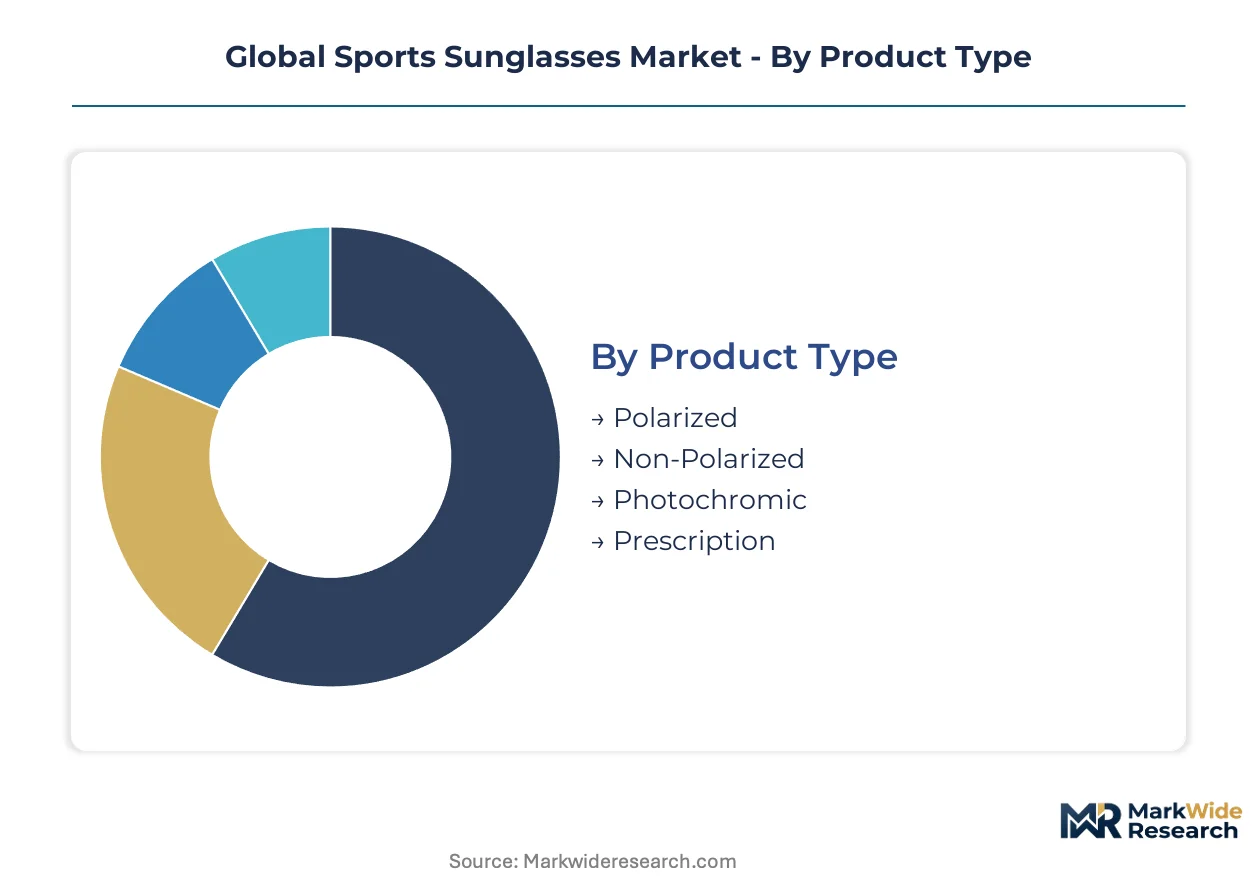
Segmentation in sports sunglasses reveals how performance requirements, regulatory exposure, and material science converge into distinct purchasing behaviors across athlete categories and use environments. Manufacturers configure product lines around optical technology tiers, frame material compliance profiles, and end-use intensity levels that dictate replacement frequency and price elasticity.
Product Type:
Optical technology separates buyers by glare sensitivity, light adaptation needs, and prescription integration requirements.
- Polarized:These lenses incorporate vertical filtering layers that block horizontal glare reflection from water, snow, and asphalt surfaces. Demand concentrates in coastal California fishing communities and Swiss Alps ski touring circuits where surface glare creates measurable safety hazards.
- Photochromic:Adaptive tint molecules embedded in Trivex or polycarbonate substrates darken under UV exposure and clear in shade. Trail runners traversing German Black Forest canopy-to-ridge routes drive replacement cycles for single-eyewear solutions that eliminate carry burden.
- Non-Polarized:Standard UV-blocking lenses without polarization filtering serve budget-conscious cyclists and gym-based training environments where glare reduction delivers marginal performance return.
- Prescription:Custom-ground corrective lenses integrated into wraparound sport frames address myopic and astigmatic athletes requiring optical correction during high-exertion activities.
Volume sits with Non-Polarized; growth tilts toward Photochromic.
Customer Type:
Purchase frequency, price tolerance, and brand relationship intensity distinguish these buyer pools.
- Amateur Athletes:Cycling club members and weekend triathlon participants constitute the deepest volume pool, sourcing mid-tier polarized systems through direct-to-consumer portals that bypass traditional retail markup structures.
- Professional Athletes:Sponsored teams and elite competitors concentrate technical co-development relationships and brand leverage, though absolute unit volumes remain constrained by population size.
- Sports Enthusiasts:Recreational hikers and casual runners purchase entry-level protection primarily for UV safety rather than performance optimization, showing lower replacement frequency.
- Casual Users:Fashion-forward consumers selecting sport-styled frames for daily wear prioritize aesthetics over impact certification, creating a separate demand stream with distinct distribution channels.
Amateur Athletes carry volume; Professional Athletes command margin.
End Use:
Activity-specific optical demands and environmental exposure patterns structure product configuration requirements.
- Cycling:Road and gravel disciplines demand aerodynamic frame geometries with anti-fog ventilation channels. Australian amateur racing leagues across Victoria and New South Wales anchor procurement expansion for mid-tier performance eyewear in this segment.
- Running:Trail variants require photochromic adaptation for canopy-to-exposure transitions, while road running prioritizes lightweight nylon frames with hydrophobic coatings for sweat management.
- Fishing:Water surface glare reduction commands measurable performance premiums, concentrating polarized demand in coastal California and Australian reef fishing communities.
- Golf:Precision depth perception and green-reading contrast drive demand for enhanced color definition lenses, typically in non-polarized configurations that preserve LCD screen visibility for GPS devices.
Cycling dominates unit volume; trail running within Running expands most quickly.
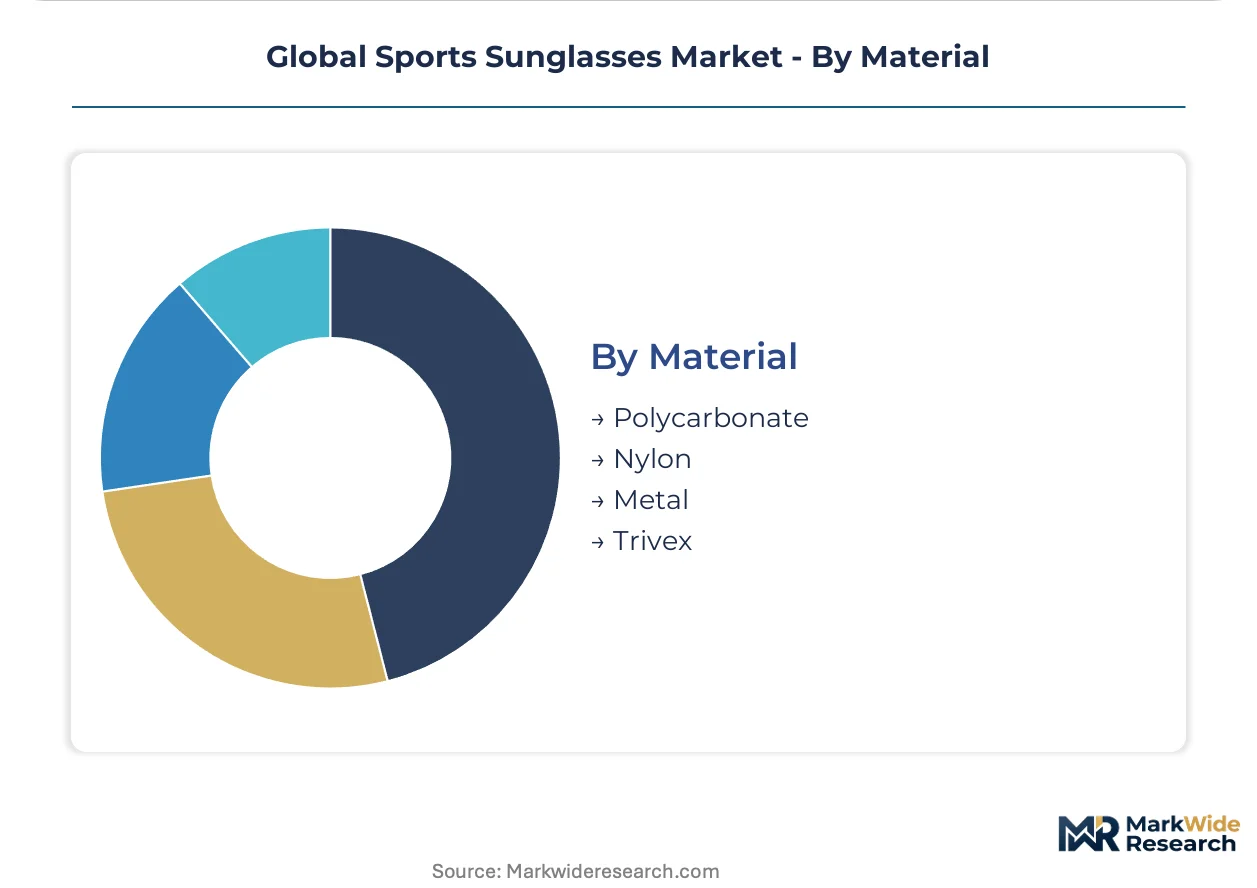
Material:
Frame and lens substrate selection balances impact rating, weight, chemical compliance, and sustainability positioning.
- Polycarbonate:Injection-molded frames and lenses deliver impact-rated protection at mass-market price points. California Proposition 65 disclosure requirements for bisphenol-A content are forcing reformulation or extensive labeling infrastructure for manufacturers serving US markets.
- Nylon:Grilamid and bio-based polyamide variants from castor oil feedstocks dominate premium European positioning, satisfying EU Green Deal extended producer responsibility frameworks while reducing frame weight for triathlon applications.
- Metal:Titanium and aluminum alloys serve fashion-forward casual segments and prescription frame integration where adjustability and hypoallergenic contact properties outweigh weight penalties.
- Trivex:This urethane-based lens material delivers superior optical clarity and impact resistance compared to polycarbonate, commanding price premiums in prescription sport applications where visual acuity is paramount.
Polycarbonate holds volume share; Nylon gains share fastest on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal California and the Swiss Alps anchor premium polarized and photochromic replacement cycles, while Australian amateur racing leagues and German cycling clubs drive procurement expansion across mid-tier performance eyewear segments.
United States
Coastal California clusters concentrate demand for high-altitude UV protection systems. The FDA regulates UV protection claims as medical devices, extending certification timelines for polycarbonate frame producers. Los Angeles and San Diego metro areas compress replacement cycles for premium polarized fishing and water sports applications.
Germany
Cycling clubs across Bavaria and Baden-Württemberg expand protective eyewear procurement for amateur racing leagues. The EU Green Deal's extended producer responsibility framework pressures manufacturers toward recycled nylon frames. The Black Forest region drives photochromic lens demand for trail runners transitioning between shaded canopy and exposed ridge terrain.
Switzerland
Alpine ski touring and high-altitude mountaineering concentrate premium polarized system demand. Swissmedic maintains medical device oversight for prescription sport eyewear integration. The Interlaken-Zermatt corridor anchors replacement cycles for Trivex lens substrates in extreme UV exposure environments.
Australia
Amateur racing leagues across Victoria and New South Wales create volume anchor demand for mid-tier performance eyewear. The TGA regulates therapeutic goods claims on UV-blocking products. Reef fishing communities along the Queensland coast command measurable premiums for glare-reduction polarized systems.
France
Triathlon and road racing disciplines in Provence-Alpes-Côte d'Azur specify aerodynamic frame geometries with anti-fog ventilation. ANSM oversees product safety for lens coatings and frame polymers. The French Riviera cluster concentrates fashion-forward sport-styled frame demand among casual users prioritizing aesthetics.
Global Sports Sunglasses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical technology tiers, with proprietary lens substrates and integrated manufacturing footprints commanding pricing power. The vendor base stratifies between integrated optics conglomerates, specialist aerodynamic frame designers, and mass-market sporting goods retailers. Three archetypes dominate: technology-integrated manufacturers controlling raw material sourcing, performance specialists co-developing with professional athletes, and volume-driven private-label suppliers. Capacity consolidation and direct-to-athlete subscription models represent the dominant competitive moves reshaping distribution economics.
Among technology-integrated manufacturers, EssilorLuxottica and Oakley exemplify archetypes built on captive lens production and proprietary substrate development. Rudy Project occupies a position within the performance specialist tier, representing frame geometry innovation targeting aerodynamic efficiency. These three companies anchor the competitive structure across premium and mid-market segments without dominating absolute volume.
| Leading Market Players |
|---|
| Adidas Eyewear |
| Safilo Group |
| EssilorLuxottica |
| Rudy Project |
| Decathlon |
| Oakley |
| Under Armour |
| Smith Optics |
| Nike Vision |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-classified medical devices and recreational eyewear bifurcates both margin structures and sourcing strategies across the sports sunglasses market. Premium Trivex lens systems command value-based pricing anchored to optical clarity outcomes, while polycarbonate commodity tiers compete on injection-molding scale and bisphenol-A disclosure compliance costs.
Pricing Analysis
Value-based pricing anchors to measurable optical performance outcomes including impact resistance certification and prescription integration precision. Three-tier pricing structure across premium, standard, and economy levels separates Trivex prescription systems from nylon-frame photochromic mid-tier offerings and injection-molded polycarbonate entry products. Cost compression in polycarbonate frames intensifies because California Proposition 65 labeling requirements add compliance overhead without commensurate price recovery. Amateur athletes through cycling club procurement show highest price sensitivity, while professional athletes and sponsored teams demonstrate lowest elasticity due to technical co-development relationships.
Supply Chain Analysis
Dual-sourcing requirements for optical-grade polycarbonate and Trivex substrates mandate multi-supplier qualification across German chemical producers and Japanese urethane specialists. Precision lens grinding and anti-reflective coating capacity clusters in coastal Chinese manufacturing zones, creating single-source vulnerability for hydrophobic oleophobic layer application. Frame assembly draws from Italian acetate heritage producers and Austrian titanium processors for premium metal integrations. Tariff exposure on Chinese optical components threatens margin stability for mid-tier assemblers. Distribution runs through manufacturer-direct portals disrupting traditional optician and sporting goods store economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics dominate competitive positioning as players pursue captive lens substrate production to escape petrochemical feedstock volatility and Asian optical component concentration risks.
For Market Incumbents: To counter direct-to-athlete subscription models eroding retail channel control, incumbents should deepen backward integration into Trivex and bio-based nylon production while locking exclusive procurement contracts with Australian amateur racing leagues and German cycling clubs. Certification investment in EU AI Act product safety protocols creates preferential placement in automated quality verification systems. For New Entrants and Emerging Players: Specialty running retailers and triathlon event organizers represent the most accessible channel partners for white-space penetration. Trail running photochromic demand in the German Black Forest and Swiss Alps offers the most penetrable segment given incumbent focus on cycling volume. Direct-to-consumer seasonal frame exchange programs bypass entrenched retail relationships. For Investors and Strategic Acquirers: Re-rating potential sits with integrated lens-frame manufacturers given REACH authorization timeline compression and bio-based material substitution catalysts. Long-term viability over the coming decade favors suppliers with captive optical substrate production and European sustainability compliance infrastructure. The signal to watch is FDA medical device classification expansion beyond UV claims into impact resistance certification tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Transition | Castor oil-derived Grilamid frames satisfy EU Green Deal extended producer responsibility mandates ahead of competitors. |
| Direct-to-Athlete Subscription Launch | Replacement lens programs concentrate brand relationship data with original equipment suppliers bypassing retail markup. |
| Prescription Sport Integration | Custom-ground corrective lenses in wraparound frames address myopic athletes requiring optical correction during exertion. |
| REACH Compliance Pre-Qualification | Early substance approval for hydrophobic coatings accelerates CE marking timelines against reformulation-lagged rivals. |
| Photochromic Technology Licensing | Adaptive tint molecule embedding in Trivex substrates captures trail runner canopy-to-ridge transition demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with frame design engineers, optical coating specialists, cycling club procurement officers, and sporting goods category buyers provided qualitative validation. FDA 510(k) submissions, EU REACH authorization databases, ISO certification registries, and Australian TGA therapeutic goods listings supplied regulatory trajectory signals. Bottom-up demand modeling across amateur athlete club memberships and top-down value chain analysis triangulated market sizing.
Granularity-level modeling addressed optical technology tiers, frame material compliance profiles, end-use intensity levels, and customer archetype price elasticity across the projection horizon. Segment-level CAGRs derived from replacement cycle compression in high-UV exposure clusters and procurement expansion patterns in Australian amateur racing leagues. Photochromic adoption curves and bio-based material penetration rates informed technology transition assumptions.
Caveats apply where polycarbonate resin volatility, REACH substance restriction expansion, or FDA medical device reclassification could materially shift the outlook. Deviation in Asian optical component trade policy or EU AI Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Surfing Equipment Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Surfboard Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Running Gear Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Backboard Market
Sports Equipment
Tetherball Market