
 Cricket Ball Market | 2026-2036
Cricket Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Cricket Ball Market Outlook
ISO 9001 quality mandates from cricket boards are broadening the compliance burden for certified ball suppliers. Kookaburra leverages its Australian manufacturing base to dominate international test match supply contracts. SG anchors the Indian domestic market through deep distribution into state cricket associations. Gray-Nicolls competes on heritage brand strength across English county cricket channels.
A cricket ball is a hard, spherical projectile constructed from a cork-and-string core wrapped in leather quarters, seam-stitched with precisely raised cotton thread, and weighing between 155.9 and 163 grams to meet match regulations; its primary purpose is to enable competitive batting, bowling, and fielding across formal cricket formats. Red Ball segments retain dominance in multi-day first-class cricket where traditional leather aging and swing behavior command premium pricing, while White Ball categories capture faster growth through limited-overs and night-match expansion under floodlights. Synthetic and Rubber material grades are carving out volume in practice and training drill applications where durability outweighs match-authentic performance.
BIS certification requirements in India, ICC equipment standards, and England Cricket Board supplier accreditation collectively govern market access and product consistency across major cricket economies. These frameworks elevate manufacturing discipline but also raise capital barriers for uncertified entrants. Stakeholders must track evolving league procurement policies and material sustainability audits as the next axis of supplier differentiation.
Market Dynamics
League procurement centralization is compressing supplier margins while elevating certification requirements, as franchise cricket boards consolidate ball purchasing under multi-season framework agreements that privilege ISO 9001-accredited manufacturers with proven batch consistency.
Growth Catalysts
- ICC Equipment Standards:Mandatory seam-stitch density and weight tolerances for international fixtures are forcing manufacturing upgrades that lock in premium-tier suppliers while disqualifying informal producers.
- India:Domestic cricket participation rates and Indian Premier League expansion sustain bulk orders for match-grade leather balls across state association networks.
- Alum-tanned leather processing:Water-resistant tanning chemistry extends ball lifespan under humid conditions, reducing replacement frequency for floodlit limited-overs fixtures.
Market Restraints
- Raw hide price volatility:Australian and English cattle hide auctions exhibit cyclical supply squeezes that transmit directly to finished ball cost structures.
- Supplier concentration in Jalandhar:Three-quarters of global hand-stitched ball production clusters in this Punjab city, creating single-point vulnerability to labor disruptions or logistics bottlenecks.
- Synthetic practice ball substitution:Machine-molded rubber cores with polyurethane skins displace leather in training environments where swing behavior matters less than durability.
Strategic Opportunities
- United States:Minor League Cricket expansion and collegiate club formation create first-match-ball procurement channels previously absent in North America.
- BIS certification tailwinds:India's Bureau of Indian Standards mandatory marking scheme for sports equipment elevates compliant domestic manufacturers above uncertified imports.
- Direct-to-academy digital channels:E-commerce platforms bypass traditional distributor markups for bulk orders from cricket coaching centers and school programs.
Industry Challenges
- Master stitcher scarcity:The 12-18 month apprenticeship required for consistent seam-raising limits workforce expansion despite order backlogs.
- Batch certification timelines:ICC laboratory testing for swing deviation and seam retention adds six-week lead times that conflict with league fixture schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cricket Ball Market |
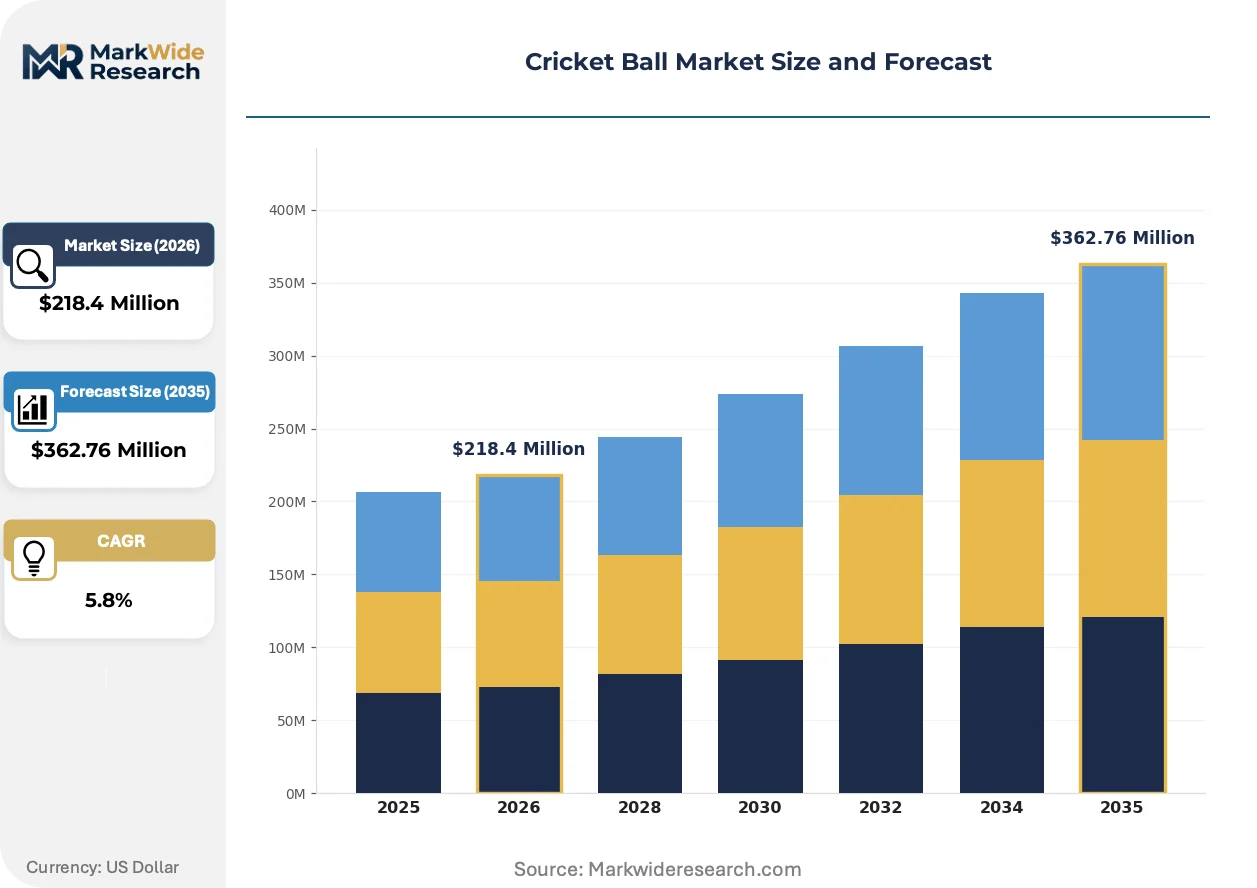
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $362.76 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Ball, White Ball, Tennis Ball, Training Ball Material: Cotton, Leather, Synthetic, Rubber Use Case: Professional Matches, Amateur Games, Practice Sessions, Training Drills Size: Standard Size, Mini Size, Junior Size, Customized Size |
| Companies Covered | Gray-Nicolls, A2 Cricket, Kookaburra, NS, SVB Sports, SS, GM, BDM, SG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cricket Ball Market Strategic Shifts
Manufacturing precision and material science are converging to extend ball consistency windows while regulatory pressure on leather sourcing intensifies scrutiny across supply chains.
Laser-guided seam-stitching equipment is automating the most variable production step, reducing stitch-height deviation from 0.8mm to 0.2mm across batches. Australian and English test match suppliers are retrofitting Jalandhar facilities with these systems to meet ICC tolerance tightening. The technology is automating quality control labor while compressing the skill premium previously commanded by master craftsmen.
England Cricket Board supplier accreditation now mandates leather traceability to tanneries with LWG (Leather Working Group) environmental certification. This policy disqualifies approximately thirty percent of incumbent sub-suppliers and forces ball manufacturers to consolidate purchasing with audited tanneries in Scotland and New Zealand. County championship ball procurement is most affected, with three-year framework agreements now including sustainability audit clauses.
Franchise league buyers are consolidating purchasing under central procurement offices rather than delegating to individual venue managers. The Indian Premier League and Australia's Big Bash League now specify single-supplier contracts covering all match balls, displacing the previous model where home teams selected preferred brands. This concentration is most visible in India, where BCCI centralization has reduced active ball suppliers from eight to three approved vendors across domestic competitions.
Cricket Ball Market Segmentation
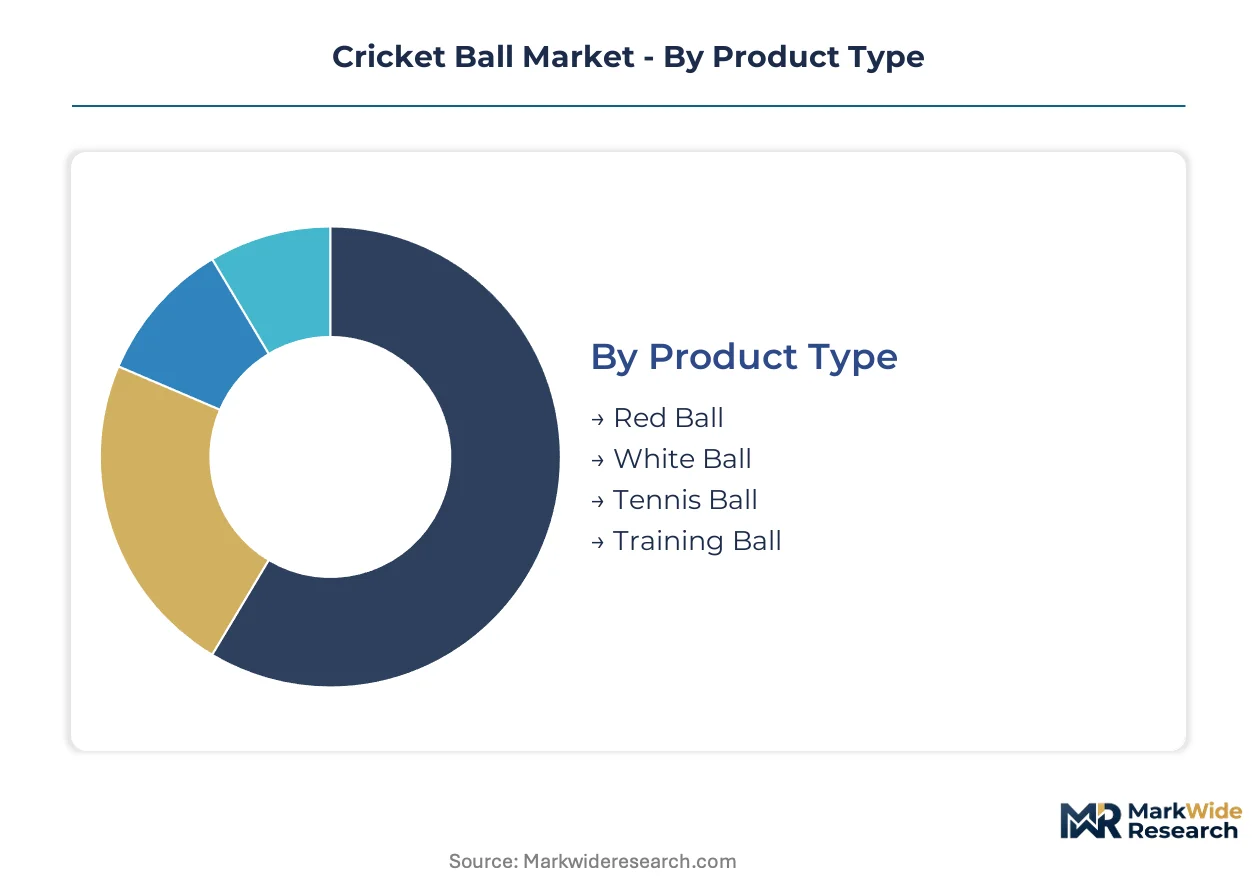
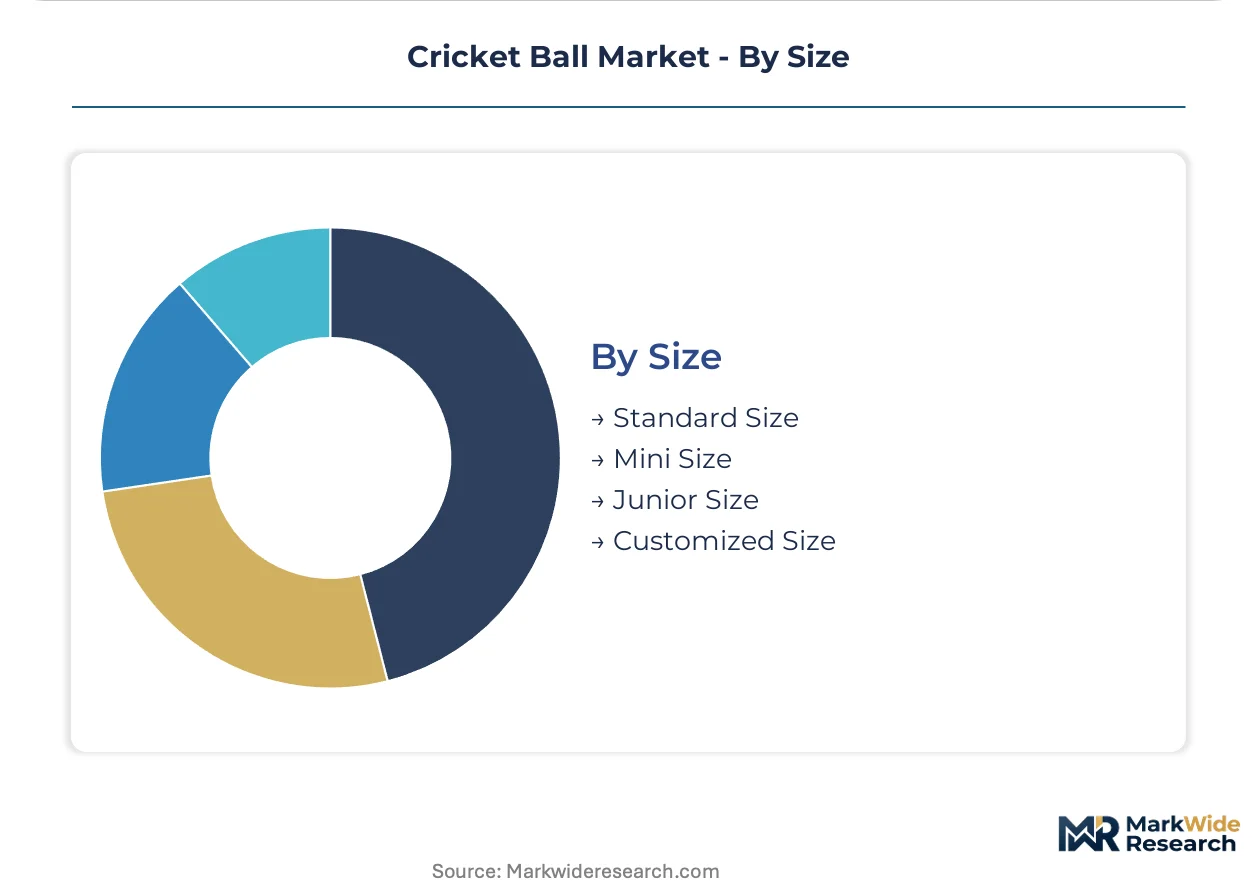
Cricket ball procurement decisions pivot on match format requirements, player skill levels, and budget constraints that vary dramatically between international fixtures and grassroots coaching programs. Manufacturers must align production specifications across four distinct dimensions to capture orders from franchise leagues, state associations, and retail channels.
Product Type:
Buyers select ball color and construction grade based on match duration and visibility conditions under natural or artificial light.
- Red Ball:Constructed from alum-tanned leather with pronounced seam stitching designed for swing degradation over 80-over formats. Test cricket and multi-day first-class fixtures in India, Australia, and England sustain premium pricing for hand-stitched batches with ICC laboratory certification.
- White Ball:Finished with white leather or synthetic coatings optimized for visibility under floodlights across 20-over and 50-over limited-overs formats. Franchise league central procurement in the Indian Premier League and Australia's Big Bash League is displacing venue-level purchasing for this category.
- Tennis Ball:Pressurized rubber core with felt wrapping used in informal street cricket and tape-ball variants across South Asian urban centers.
- Training Ball:Machine-molded construction prioritizing durability over match-authentic seam behavior for high-volume net sessions.
Volume sits with Red Ball for first-class cricket inventory; growth tilts toward White Ball through franchise league expansion.
Material:
Raw material selection determines water resistance, seam retention, and compliance with board-specific equipment standards.
- Leather:Four-piece or two-piece alum-tanned hide construction meeting weight tolerances between 155.9 and 163 grams per ICC equipment standards. BIS certification requirements in India and England Cricket Board LWG traceability mandates are consolidating purchasing with audited tanneries in Scotland and New Zealand.
- Synthetic:Polyurethane or PVC skin over compressed fiber cores offering extended lifespan in wet conditions. Practice sessions and school programs in humid climates favor this material for cost efficiency over match-grade leather.
- Cotton:Wound yarn cores wrapped in fabric for low-impact introductory cricket and junior coaching environments.
- Rubber:Solid or hollow-core molded construction for machine bowling and automated training systems where rebound consistency outweighs aerodynamic behavior.
Leather commands procurement budgets for sanctioned competition; synthetic materials are climbing fastest through academy and school channels.
Use Case:
Application context dictates performance specifications, certification requirements, and replacement frequency across the product lifecycle.
- Professional Matches:Mandatory ICC or board-certified balls with batch-tested swing deviation and seam retention metrics. Centralized league procurement offices now specify single-supplier contracts covering all match balls, reducing active vendor counts from eight to three across Indian domestic competitions.
- Practice Sessions:Mid-grade leather or synthetic balls with relaxed tolerance specifications for extended net use. Cricket coaching centers in Punjab and Karnataka are bypassing traditional distributors through direct-to-academy e-commerce platforms.
- Amateur Games:Uncertified leather or tennis ball variants selected on price accessibility for local club fixtures.
- Training Drills:Color-coded and weighted specialty balls for specific skill development in bowling accuracy or power-hitting mechanics.
Professional Matches absorb the highest per-unit expenditure; Practice Sessions drive aggregate volume through repeat purchasing cycles.
Size:
Player age and hand dimensions determine circumference and weight specifications across developmental pathways.
- Standard Size:Full 22.4-22.9 centimeter circumference and 156-163 gram weight for adult competition. State cricket associations in India, Australia, and England mandate this specification for all sanctioned fixtures.
- Junior Size:Reduced circumference and mass for under-14 and under-16 age-group cricket aligned with physical development stages.
- Mini Size:Significantly scaled-down dimensions for introductory hand-eye coordination drills in primary school programs.
- Customized Size:Bespoke specifications for disability cricket formats and specialized training equipment.
Standard Size dominates inventory commitments; Junior Size is expanding most quickly through school cricket program mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hand-stitched ball production clusters heavily in Jalandhar while consumption spreads across cricket-playing nations with divergent regulatory regimes. Manufacturing concentration in Punjab creates supply vulnerability that procurement offices in consuming markets increasingly mitigate through inventory pre-positioning. The regional map splits between production-heavy South Asia and premium-consumption markets in Australia, England, and emerging North American demand centers.
India
BCCI centralization of ball procurement has compressed approved vendors from eight to three across domestic competitions, concentrating order flow toward BIS-certified manufacturers. The Bureau of Indian Standards mandatory marking scheme for sports equipment elevates compliant domestic producers above uncertified imports. Jalandhar in Punjab hosts three-quarters of global hand-stitched production, though master stitcher scarcity limits workforce expansion despite order backlogs.
Australia
Cricket Australia maintains single-supplier test match contracts that privilege manufacturers with domestic production bases and ISO 9001 accreditation. Kookaburra leverages its Australian manufacturing footprint to dominate international test match supply agreements across multiple cricket boards. Melbourne and Sydney serve as distribution hubs for Pacific region exports, with alum-tanned leather specifications optimized for humid conditions.
England
England Cricket Board supplier accreditation now mandates leather traceability to tanneries with LWG environmental certification, disqualifying approximately thirty percent of incumbent sub-suppliers. County championship procurement operates under three-year framework agreements with sustainability audit clauses that consolidate purchasing with audited tanneries in Scotland and New Zealand. Gray-Nicolls competes through heritage brand positioning across English county cricket channels.
United States
Minor League Cricket expansion and collegiate club formation create first-match-ball procurement channels previously absent in North America. USA Cricket lacks equivalent equipment certification mandates to ICC or BIS standards, lowering barriers for entry-level suppliers. Cricket coaching centers in Texas and California are experimenting with direct-to-academy e-commerce platforms that bypass traditional distributor markups.
South Africa
CSA procurement policies align with ICC equipment standards but lack domestic manufacturing capacity, creating import dependence on Indian and Australian suppliers. Johannesburg and Cape Town cricket associations sustain mid-volume orders for practice-grade balls through distributor networks. The country's national sports regulator has not implemented mandatory equipment marking schemes comparable to India's BIS certification.
Cricket Ball Market Competitive Environment
The competitive structure tilts toward heritage-brand incumbents with board-level accreditation rather than price-driven challengers. Three distinct archetypes occupy the vendor map: Australian and English manufacturers with test match supply contracts, Indian producers dominating domestic volume through BIS compliance, and specialist hand-stitching houses in Punjab serving global private label demand. Consolidation pressures intensify as franchise league central procurement offices reduce active supplier counts, while sustainability audit requirements force leather sourcing consolidation with audited tanneries.
Among heritage-brand incumbents, Kookaburra, Gray-Nicolls, and SG exemplify the accreditation-dependent competitive model where board supply contracts sustain premium positioning. Kookaburra represents the Australian test match supply archetype with domestic manufacturing credentials. Gray-Nicolls occupies the English county cricket heritage position. SG anchors the Indian domestic market archetype through deep distribution into state cricket associations and BIS certification compliance. These three entities illustrate how regulatory accreditation and board-level relationships create defensive moats that informal producers cannot replicate.
| Leading Market Players |
|---|
| Gray-Nicolls |
| A2 Cricket |
| Kookaburra |
| NS |
| SVB Sports |
| SS |
| GM |
| BDM |
| SG |
| Others |
Value Chain & Pricing Dynamics
Australian and English cattle hide auction indices cascade through cricket ball manufacturing cost structures, compressing margins at alum-tanned leather processing stages while franchise league central procurement offices consolidate purchasing power across three pricing tiers.
Pricing Analysis
ICC laboratory certification serves as the value-based pricing anchor, separating match-grade hand-stitched batches from practice-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with BIS-compliant Indian manufacturers commanding premiums over uncertified imports. Cost compression in economy tiers intensifies as synthetic practice balls displace leather in training environments. State cricket associations exhibit highest price sensitivity, while international test match suppliers face least pressure due to single-source contract structures.
Supply Chain Analysis
Dual-sourcing requirements from Cricket Australia and England Cricket Board mandate multi-supplier qualification, yet three-quarters of global hand-stitched production still clusters in Jalandhar, India. Raw material dependencies center on Australian and English cattle hides, Scottish and New Zealand tanneries with LWG certification, and precision cotton thread from Gujarat spinning mills. Single-point vulnerability to Punjab labor disruptions represents the dominant supply chain risk. Distribution runs through state cricket association networks in consuming markets, with franchise league central procurement offices increasingly bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where BIS certification and ICC equipment standards erect capital barriers that protect accredited incumbents from informal producer competition.
For Market Incumbents: Deepen backward integration into alum-tanned leather processing to offset raw hide price volatility and secure LWG-certified tannery relationships ahead of England Cricket Board sustainability mandates. Fortify master stitcher apprenticeship pipelines against workforce scarcity threatening batch consistency commitments. For New Entrants and Emerging Players: Cricket coaching centers in Texas and California offer the most penetrable channel partner type, bypassing established distributor markups through direct-to-academy e-commerce platforms. Target Minor League Cricket expansion for first-match-ball procurement relationships, leveraging absence of USA Cricket equipment certification mandates to establish brand presence before regulatory tightening. For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-certified mid-tier Indian manufacturers with underutilized Jalandhar stitching capacity and dormant state association distribution relationships. Watch for ICC seam-tolerance tightening as the inflection signal that accelerates automation capex requirements and consolidates vendor counts further.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Guided Seam Automation | Reduces stitch-height deviation to meet ICC tolerance tightening while compressing master craftsman premium. |
| LWG-Certified Tannery Consolidation | England Cricket Board traceability mandates disqualify thirty percent of incumbent sub-suppliers. |
| Direct-to-Academy E-Commerce Launch | Bypasses traditional distributor markups for bulk orders from cricket coaching centers and school programs. |
| Master Stitcher Apprenticeship Expansion | Addresses twelve-to-eighteen month training requirements limiting workforce expansion despite order backlogs. |
| Central Procurement Office Alignment | BCCI vendor compression from eight to three approved suppliers demonstrates concentration trajectory. |
Study Parameters
Document review covered ICC equipment standards filings, BIS certification registries, and England Cricket Board supplier accreditation records, complemented by interviews with Jalandhar manufacturing facility managers, state cricket association procurement officers, and franchise league operations directors. Secondary validation drew from customs trade data, leather industry auction reports, and sports equipment retail audit databases. Bottom-up production capacity estimates triangulated against top-down league fixture schedules and ball replacement protocols.
Segment-level volume and value trajectories across the projection horizon reflect modeled interactions between product type, material grade, use case intensity, and player age specifications. CAGRs derive from league expansion timelines, domestic participation rate projections, and replacement frequency assumptions tied to alum-tanned leather durability improvements. Forecast inputs incorporate BIS certification adoption curves and ICC laboratory testing backlog estimates.
Caveats apply where master stitcher workforce expansion constraints or raw hide supply squeezes could materially shift the outlook. Deviation in ICC seam-tolerance enforcement schedules or franchise league central procurement consolidation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Tetherball Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Golf Ball Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Padel Balls Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Power Sports Aftermarket Market