
 Europe Sports Team and Clubs Market | 2026-2036
Europe Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports Team and Clubs Market Insights
Corporate hospitality and experiential tourism is restructuring how commercial buyers allocate sports entertainment budgets across Europe. Real Madrid CF leverages its Santiago Bernabéu redevelopment to anchor premium revenue streams in the Spanish capital. Manchester United FC competes through its global brand licensing network, while Paris Saint-Germain FC differentiates via luxury positioning in the French market.
Europe sports teams and clubs comprise organized competitive athletic entities operating across professional and amateur tiers, generating revenue through broadcast rights, matchday operations, and commercial partnerships, with stadium infrastructure typically requiring seating capacities from ten thousand to over eighty thousand spectators. The revenue stream dimension shows media rights and sponsorships capturing the deepest margin pools, while ticket sales face structural pressure from streaming alternatives. Within sport category, football dominates absolute value across the continent, though basketball franchises in Spain and Turkey are gaining traction among younger demographics.
The EU Green Deal and national building codes in Germany, England, and Spain are mandating stadium energy retrofits and sustainable transport access, reshaping capital allocation for venue operators. GDPR compliance requirements affect how clubs collect and monetize fan data across digital membership platforms. Stakeholders must monitor how CSRD disclosure rules will force listed clubs to report environmental and social metrics, altering investor due diligence frameworks.
Market Dynamics
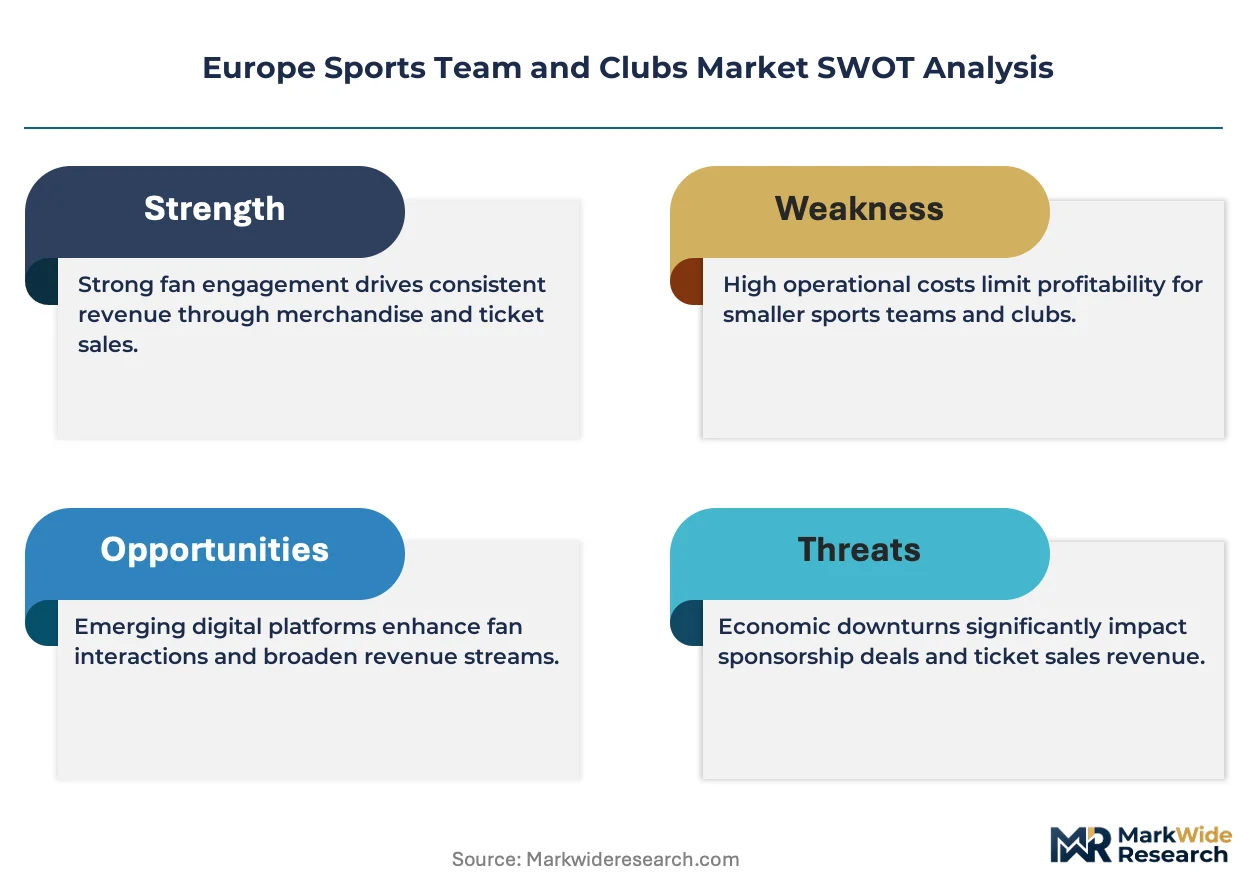
CSRD disclosure mandates and the EU Green Deal are forcing stadium operators across Germany, Spain, and England to reallocate capital toward decarbonization retrofits while simultaneously restructuring revenue models around premium experiential offerings.
Growth Catalysts
- EU Green Deal stadium mandates:Germany's building energy codes and England's net-zero pathway are accelerating venue retrofit spending, creating captive demand for low-carbon infrastructure suppliers.
- Broadcast rights fragmentation:Streaming platforms are disaggregating traditional media bundles, enabling clubs to monetize direct-to-consumer content across younger demographics in Spain and Turkey.
- Corporate hospitality expansion:Premium matchday experiences from Manchester to London are capturing commercial entertainment budgets previously allocated to traditional conferencing.
Market Restraints
- Construction cost escalation:Steel and concrete input volatility is compressing margins on stadium redevelopment projects, particularly affecting mid-tier clubs with limited debt capacity.
- Energy price exposure:German and English venues face structural operating cost pressure from natural gas dependency in heating and pitch maintenance systems.
- GDPR data monetization friction:Fan data collection restrictions are limiting personalization revenue streams that clubs had projected from digital membership platforms.
Strategic Opportunities
- Underpenetrated Turkish basketball:Istanbul and Ankara franchises are attracting institutional investment as basketball viewership concentrates among urban youth demographics.
- CSRD-aligned green bonds:Listed clubs in Spain and England can access preferential capital for stadium retrofits by structuring environmental disclosure frameworks.
- Multi-use venue conversion:Concert and esports programming is extending revenue hours at English Premier League stadiums beyond traditional matchday windows.
Industry Challenges
- Sustainability certification timelines:BREEAM and LEED accreditation processes are extending project completion schedules for German venue operators facing fixed season deadlines.
- Legacy ticketing system integration:Mobile-first access platforms are colliding with entrenched season-ticket holder databases, creating customer experience friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports Team and Clubs Market |
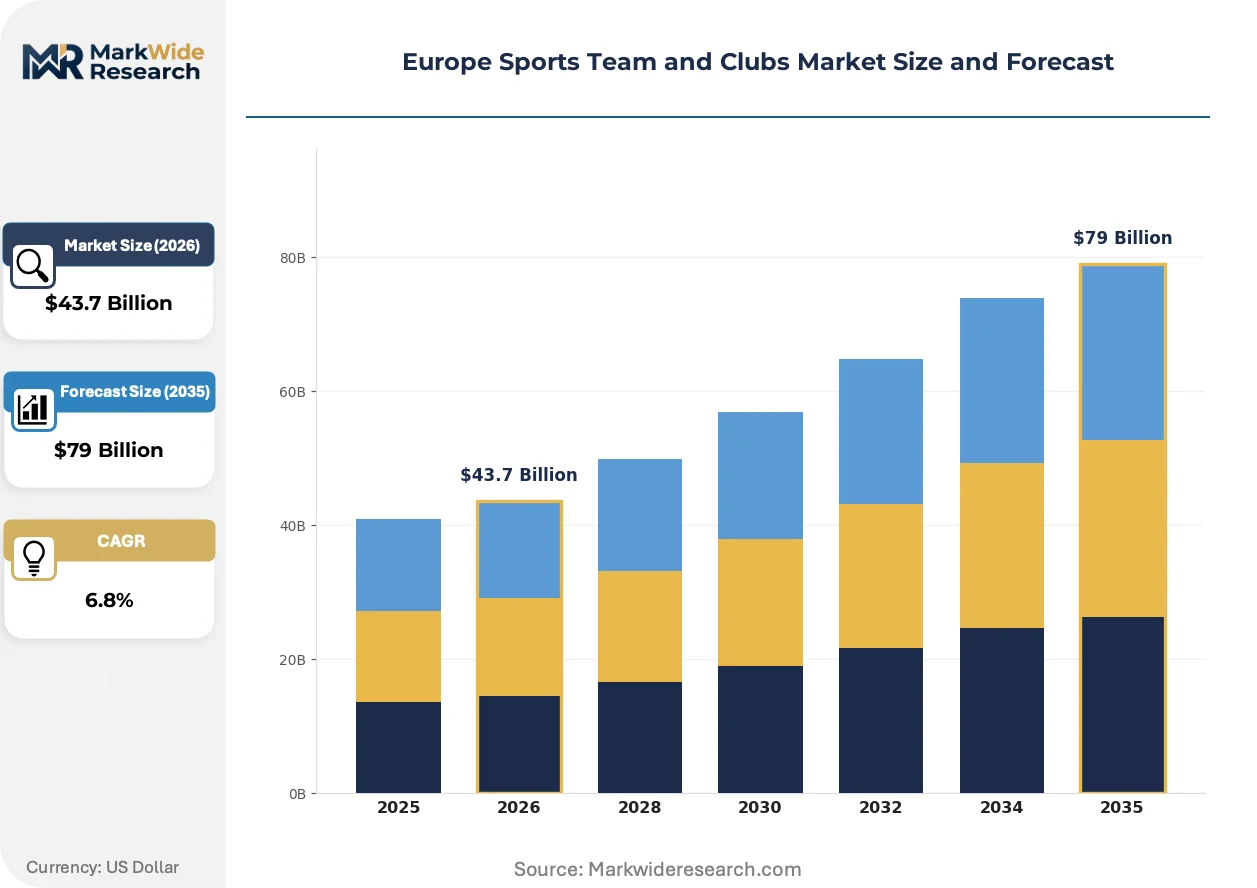
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, Franchises, Non-profit Organizations Revenue Stream: Ticket Sales, Merchandise, Sponsorships, Media Rights Membership Model: Seasonal Memberships, Annual Memberships, Pay-per-Event, Family Packages Sport Category: Football, Basketball, Rugby, Ice Hockey |
| Companies Covered | Real Madrid CF, FC Barcelona, Manchester United FC, FC Bayern München AG, Paris Saint-Germain FC, Manchester City FC, Liverpool FC, Juventus FC, Borussia Dortmund, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports Team and Clubs Market Trends and Innovations
Stadium infrastructure and fan engagement technologies are converging around decarbonization imperatives and premium experience monetization, reshaping how European clubs allocate capital and structure commercial partnerships.
Smart pitch management systems integrating IoT soil sensors and automated irrigation are overtaking traditional groundskeeping approaches across English Premier League venues. Grounds teams at Manchester and London clubs are deploying these platforms to reduce water consumption while maintaining broadcast-quality playing surfaces. The technology is compressing operating cost structures and enabling real-time environmental compliance reporting required under CSRD frameworks.
CSRD disclosure rules are mandating granular environmental and social metric reporting for listed clubs across Germany, Spain, and England. Stadium operators must now quantify Scope 3 emissions from fan travel and supply chain procurement, altering investor due diligence processes. French and Italian clubs with private ownership structures face competitive pressure to voluntarily adopt equivalent transparency standards.
Subscription-based membership models are displacing traditional season-ticket hierarchies as younger fans in Spain and Turkey prioritize flexibility over fixed-seat commitments. Digital platforms are capturing this demand through tiered access passes that bundle streaming, merchandise discounts, and limited matchday privileges. The shift is most visible in basketball franchises targeting urban demographics with lower disposable income than traditional football season-ticket bases.
Europe Sports Team and Clubs Market Segmentation
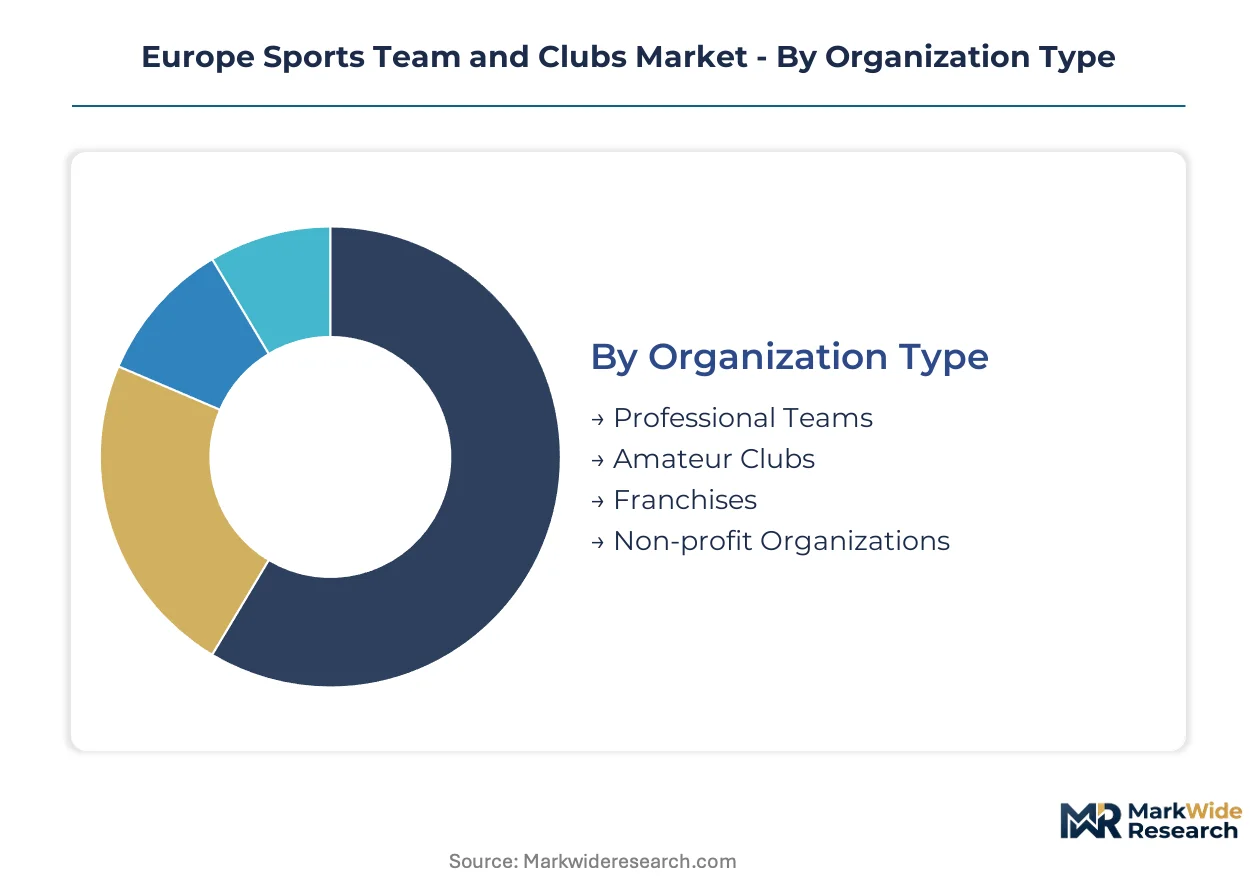
European sports clubs structure their operations around distinct organizational forms, revenue architectures, and fan engagement mechanisms that determine capital intensity and margin profiles. Segmentation reveals where commercial investment concentrates and which models face structural pressure from regulatory and technological shifts.
Organization Type:
Professional teams command premium valuations through broadcast contract access, while amateur clubs operate within federated subsidy frameworks that vary by national sporting culture.
- Professional Teams:These entities maintain full-time athlete rosters and negotiate collective bargaining agreements with player unions across England, Spain, and Germany. Revenue diversification into corporate hospitality and global licensing distinguishes top-tier operations from mid-table competitors facing debt covenant pressure.
- Amateur Clubs:Volunteer-driven structures dominate participation sports in France and Italy, relying on municipal facility subsidies and regional federation grants. CSRD disclosure exemptions reduce compliance burdens but limit institutional capital access for venue upgrades.
- Franchises:Closed-league models in basketball and ice hockey concentrate in Turkey and Central Europe, featuring territorial exclusivity and salary cap mechanisms.
- Non-profit Organizations:German Verein structures and Spanish socios-owned clubs reinvest surplus into youth academies and community programs rather than distributing returns.
Professional teams lead volumes today; franchises are gaining share fastest through private equity consolidation.
Revenue Stream:
Margin depth varies dramatically across income sources, with recurring contractual revenue commanding valuation multiples that transactional matchday sales cannot replicate.
- Ticket Sales:Matchday operations generate immediate cash flow but face ceiling effects from stadium capacity constraints and price elasticity among working-class fan bases in Northern England and the Ruhr Valley.
- Merchandise:Apparel and licensed products scale through e-commerce platforms and third-party retail partnerships, with Turkish and Polish clubs expanding into adjacent lifestyle categories.
- Sponsorships:Front-of-shirt and sleeve inventory commands premium rates from betting operators, airlines, and automotive brands seeking young male demographics.
- Media Rights:Collective selling arrangements in the Premier League and La Liga distribute broadcast revenue through parachute payment formulas, while OTT fragmentation enables direct-to-consumer experiments in secondary markets.
Media rights anchor valuation multiples; sponsorships are expanding most quickly through gambling legalization.
Membership Model:
Flexibility preferences among younger demographics are eroding traditional season-ticket hierarchies that locked in multi-decade loyalty patterns.
- Seasonal Memberships:Fixed-seat commitments for home match schedules retain core support in legacy football markets but face cancellation risk from remote work migration and generational turnover.
- Annual Memberships:Year-round packages bundling ticketing priority, merchandise discounts, and digital content access build recurring revenue bases for clubs investing in CRM infrastructure.
- Pay-per-Event:Single-match mobile purchases attract casual attendees and tourist segments in London, Paris, and Barcelona, with dynamic pricing algorithms optimizing yield per seat.
- Family Packages:Multi-ticket bundles with child-focused amenities and educational programming target household entertainment budgets in suburban catchment areas.
Annual memberships dominate recurring revenue; pay-per-event is climbing the fastest through mobile platform adoption.
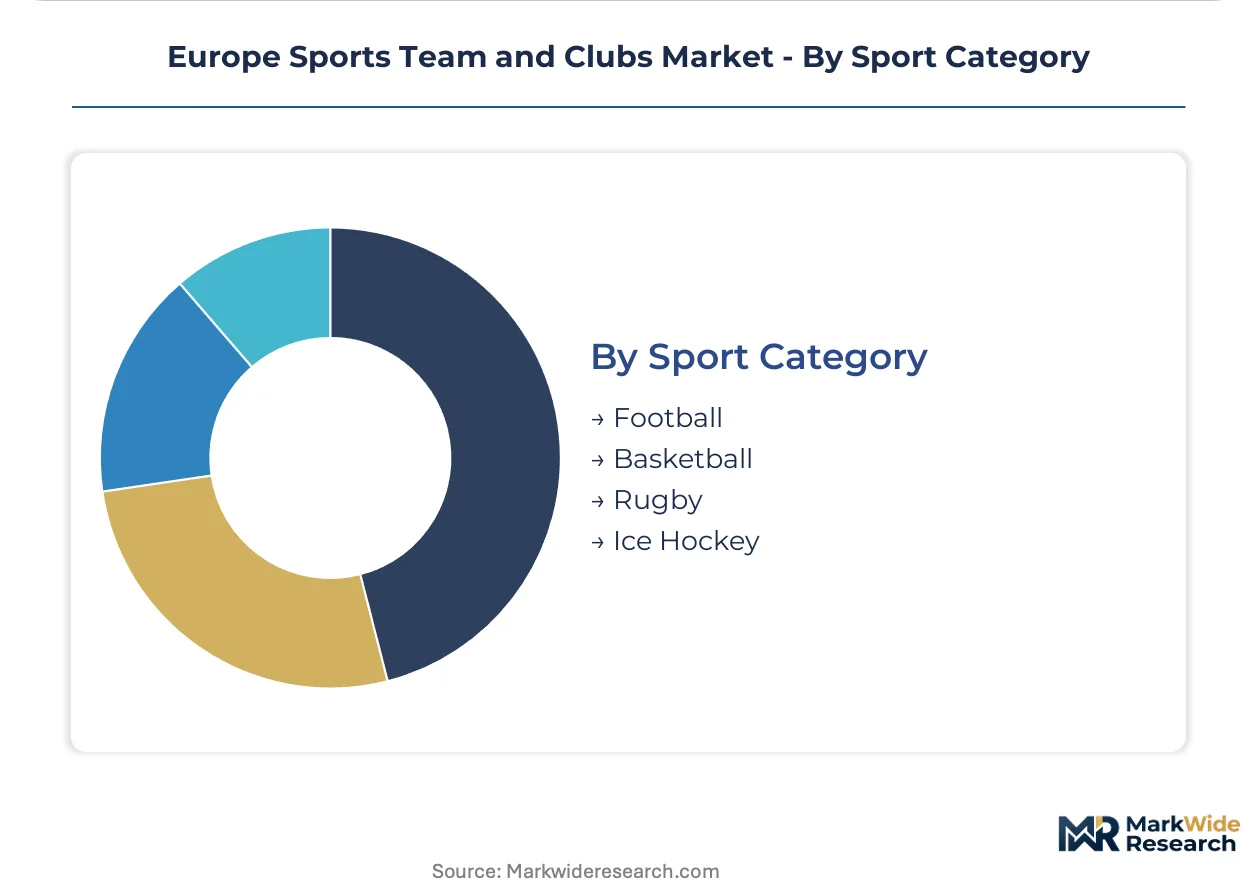
Sport Category:
Commercial infrastructure and media investment intensity diverge sharply between football's mass-market dominance and secondary sports cultivating niche affluence.
- Football:The sport commands stadium capital allocations exceeding eighty thousand seats in Madrid, Barcelona, and Manchester, with UEFA Financial Fair Play regulations constraining wage-to-revenue ratios.
- Basketball:EuroLeague franchises in Istanbul, Athens, and Madrid attract institutional investment as urban youth viewership concentrates on mobile streaming platforms.
- Rugby:Premiership and Top 14 clubs in England and France operate within stricter salary cap regimes, with private equity funds acquiring distressed assets.
- Ice Hockey:Kontinental Hockey League and national league operations in Sweden, Finland, and the Czech Republic maintain regional broadcast arrangements with limited pan-European reach.
Football leads absolute revenue; basketball shows the steepest expansion trajectory through demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stadium operators across Europe face divergent compliance costs under the EU Green Deal, creating investment migration patterns toward jurisdictions with faster permitting timelines and more flexible building energy codes. Clubs in England and Spain capture premium hospitality revenue while German operators absorb higher retrofit costs. The regulatory arbitrage gap between member states is reshaping where institutional capital deploys for venue development.
England
Premier League clubs generate the continent's highest matchday yields through corporate hospitality packages concentrated in the Manchester-London corridor. The UK's net-zero pathway mandates stadium decarbonization timelines that outpace continental counterparts, compressing capital return schedules for venue operators. Tottenham Hotspur's North London facility exemplifies multi-use venue conversion, hosting NFL fixtures and concerts beyond football matchdays.
Germany
Bundesliga franchises operate under stricter building energy codes that accelerate Scope 1 and 2 emissions reporting requirements for stadium infrastructure. The country's national building codes enforce heat pump mandates and renewable energy quotas that elevate capital expenditure thresholds for venue retrofits. Munich and Dortmund clusters concentrate the highest stadium investment density, with Allianz Arena operators piloting district heating integration from municipal networks.
Spain
La Liga clubs leverage milder climate conditions to reduce heating demand, lowering compliance costs under EU Green Deal mandates relative to northern European competitors. The country's building regulations permit longer retrofit timelines, enabling Santiago Bernabéu and Camp Nou redevelopments to phase sustainability investments across multiple seasons. Madrid and Barcelona anchor the Iberian premium hospitality market, capturing international tourism flows that English clubs cannot replicate.
France
Ligue 1 operations concentrate in Paris and Lyon, where stadium operators face intermediate regulatory stringency between German rigor and Spanish flexibility. The country's national low-carbon strategy mandates transport decarbonization around major venues, pressuring clubs to coordinate with municipal transit authorities on matchday access. Parc des Princes operators are restructuring revenue models around luxury positioning rather than volume ticketing.
Italy
Serie A clubs in Milan, Turin, and Rome confront aging stadium infrastructure and slower municipal permitting processes that extend sustainability retrofit timelines. The country's building code enforcement varies regionally, creating compliance cost disparities between northern and central Italian operations. Juventus and AC Milan are pursuing stadium ownership models that accelerate capital deployment flexibility relative to municipally leased venues.
Europe Sports Team and Clubs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage football institutions commanding valuation premiums through global licensing networks while newer franchise operations compete on operational efficiency. The market structure concentrates among twenty to thirty elite clubs that capture disproportionate broadcast and commercial revenue pools, leaving mid-tier competitors vulnerable to debt covenant pressure. Three archetypes dominate: global brand licensors with century-old fan bases, state-backed franchises deploying sovereign wealth for talent acquisition, and privately held operations optimizing hospitality yield per seat. Competitive moves center on stadium asset ownership transitions and multi-use venue programming expansion.
Within the heritage institution tier, Real Madrid CF and FC Barcelona occupy positions as Spanish socios-owned archetypes reinvesting surplus into infrastructure rather than distributions. Manchester United FC exemplifies the publicly traded global licensor model, while Paris Saint-Germain FC represents state-backed franchise positioning in luxury market segments.
| Leading Market Players |
|---|
| Real Madrid CF |
| FC Barcelona |
| Manchester United FC |
| FC Bayern München AG |
| Paris Saint-Germain FC |
| Manchester City FC |
| Liverpool FC |
| Juventus FC |
| Borussia Dortmund |
| Others |
Pricing and Supply Chain Analysis
Backward integration into stadium asset ownership anchors pricing power for Europe's elite football clubs by eliminating municipal lease premiums and enabling direct control over hospitality yield optimization. This structural choice concentrates margin capture among England's Premier League operators while mid-tier competitors remain exposed to third-party venue cost pass-throughs.
Pricing Analysis
Direct-to-consumer subscription margins bypass traditional broadcast intermediary markups that previously captured forty to sixty percent of media rights value. Three-tier pricing structure across premium hospitality, standard season tickets, and economy general admission segments club offerings by experiential intensity rather than seat location alone. Cost compression in mid-tier ticketing intensifies as streaming alternatives erode price inelasticity among younger demographics. Corporate hospitality buyers show least price sensitivity while casual pay-per-event attendees drive yield management algorithm deployment.
Supply Chain Analysis
Freight cost volatility in steel and concrete inputs elevates stadium construction budgets across German and English retrofit projects. Manufacturing concentration in China, Germany, and Turkey supplies pitch irrigation systems, LED display infrastructure, and seating components. Supply chain vulnerability rests on single-source dependencies for specialized turf management technology from Netherlands-based agritech specialists. Distribution runs through club-procurement teams coordinating directly with EPC contractors rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Sports Team and Clubs Market compounds regulatory-driven capital demand as CSRD disclosure mandates and EU Green Deal retrofit timelines force sustained infrastructure investment across the forecast window.
For Market Incumbents: Lock in stadium ownership transitions before municipal lease renegotiations accelerate under decarbonization cost allocation disputes. Prioritize BREEAM certification investment to capture green bond financing advantages as interest rate environments pressure traditional debt structures. Defend against private equity consolidation by embedding multi-use venue programming that extends revenue hours beyond matchday windows. For New Entrants and Emerging Players: Capture underpenetrated Turkish basketball franchises where urban youth viewership concentrates on mobile streaming platforms and institutional capital seeks demographic exposure. Target pay-per-event membership models in secondary Spanish and Italian cities where legacy season-ticket hierarchies face generational turnover. Deploy digital-first fan engagement platforms as primary go-to-market infrastructure rather than physical season-ticket office networks. For Investors and Strategic Acquirers: Consolidation pressure builds where CSRD compliance costs exceed standalone club cash generation capacity, particularly among mid-tier German Bundesliga operators facing accelerated building energy code timelines. Prioritize acquisition targets with unencumbered stadium assets and established corporate hospitality revenue bases. Monitor green bond issuance spreads as inflection signal for capital cost advantages accruing to sustainability-certified venue operators.| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Asset Ownership Transition | Eliminates municipal lease premiums and enables direct hospitality revenue capture for Premier League operators. |
| CSRD-Aligned Green Bond Issuance | Accesses preferential capital for German venue retrofits under national building energy code mandates. |
| Multi-Use Venue Programming Expansion | Extends revenue hours at Tottenham Hotspur's facility through NFL fixtures and concert scheduling. |
| Direct-to-Consumer Streaming Platform | Bypasses traditional broadcast intermediaries for Turkish and Spanish basketball demographic targeting. |
| Smart Pitch Management System Deployment | Reduces water consumption at Manchester and London clubs while enabling real-time CSRD compliance reporting. |
Research Methodology
Direct dialogue with stadium operations directors, corporate hospitality sales executives, broadcast rights procurement officers, and sustainability compliance leads grounded the qualitative foundation. Secondary validation drew from UEFA financial reports, national federation licensing disclosures, CSRD implementation guidance documents, and municipal stadium lease filings. Bottom-up club revenue modeling and top-down sector aggregation triangulated market size estimates.
Segment-level projections across organization type, revenue stream architecture, membership model flexibility, and sport category intensity populated the analytical framework throughout the forecast period. CAGRs derived from historical revenue trajectory analysis and regulatory-driven capital deployment assumptions. Stadium retrofit spending pipelines and broadcast contract renewal schedules served as industry-specific demand inputs.
Regulatory timeline delays, construction cost escalation beyond modeled ranges, and fan subscription churn acceleration are the dominant revision risks that could compress forecast values. Stakeholders should weight assumptions against their own operating context and local jurisdiction compliance schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market