
 Global Spikeball Equipment Market | 2026-2036
Global Spikeball Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spikeball Equipment Market Outlook
Subscription-based replacement part programs is consolidating recurring revenue into the equipment value chain. Spikeball Inc. leverages its tournament ecosystem to anchor brand loyalty across competitive players. Franklin Sports sustains mass-market penetration through big-box retail partnerships. GoSports competes on price-accessible entry sets for casual household buyers.
Spikeball equipment comprises a circular trampoline-style net tensioned on a tubular frame, paired with inflatable balls designed for four-player volley-style play; frame assemblies typically specify powder-coated steel legs with adjustable net tension mechanisms to regulate bounce response. The primary commercial purpose centers on portable recreational competition enabling setup on grass, sand, or indoor surfaces. Spikeball Sets command the dominant revenue share as the bundled entry point for new participants, while Replacement Parts capture expanding margin pools as installed bases mature. Online Retail channels are growing fastest, though Specialty Stores retain outsized influence in tournament-grade equipment selection.
ISO 8124 toy safety standards and ASTM F963 mechanical hazard specifications constrain frame edge geometry and ball inflation valve design for youth-accessible equipment. The US Consumer Product Safety Commission monitors incident reports for frame collapse risks, while EU REACH chemical restrictions govern phthalate content in PVC ball coatings. Stakeholders must monitor evolving sports federation recognition decisions that determine whether spikeball qualifies for school physical education procurement budgets or remains confined to extracurricular purchase channels.
Market Dynamics
Tournament infrastructure expansion is compressing the path from casual purchase to competitive equipment upgrade, creating tiered demand pools that manufacturers must serve simultaneously.
Growth Catalysts
- ASTM F963 mechanical hazard specifications:Standardized youth-accessible frame geometry expands school procurement eligibility in the United States, opening institutional volume channels previously restricted to extracurricular buyers.
- Recreational center capital expenditure cycles:Municipal and private fitness facilities in Germany are prioritizing portable court sports to maximize space utilization rates across programming schedules.
- Adjustable net tension mechanisms:Precision-engineered frame assemblies enable bounce calibration for skill-level matching, reducing beginner churn and extending equipment lifecycle value.
Market Restraints
- Powder-coated steel input volatility:Frame leg manufacturing faces cost pressure from fluctuating cold-rolled steel and coating chemical feedstocks, compressing margin on entry-price sets.
- EU REACH phthalate restrictions:PVC ball coating reformulation requirements add compliance testing overhead for European market access, disadvantaging smaller import-only suppliers.
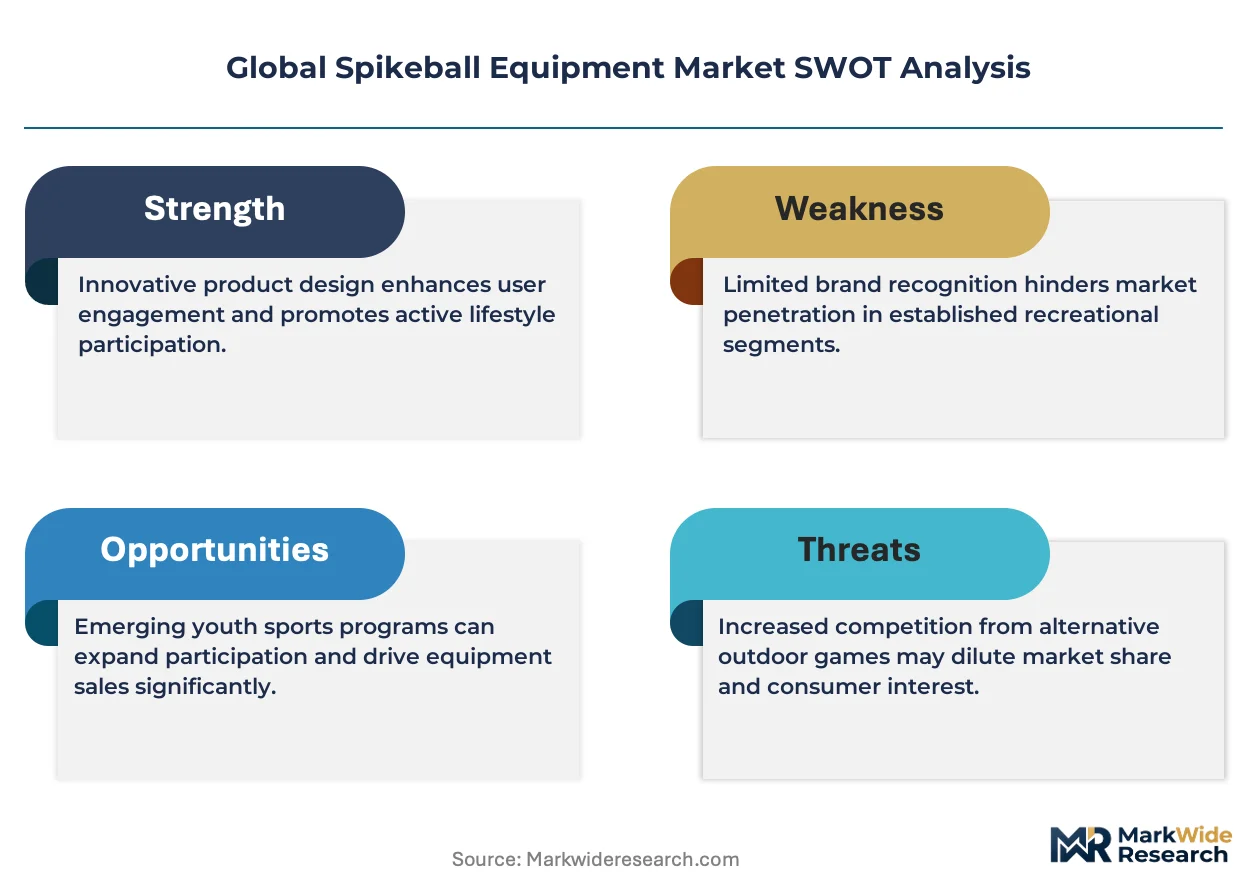
- Inflatable ball substitution risk:Generic beach balls and alternative volley-style equipment capture price-sensitive casual buyers unwilling to invest in proprietary systems.
Strategic Opportunities
- Australia school physical education procurement:Pending sports federation recognition decisions could qualify spikeball for national curriculum equipment budgets, institutionalizing demand generation.
- Subscription replacement part programs:Recurring revenue models for net and ball replenishment capture lifetime value from installed bases as competitive play frequency accelerates wear cycles.
- Indoor surface compatibility engineering:Rubberized foot and frame stability modifications enable gymnasium deployment, expanding addressable occasions beyond grass and sand environments.
Industry Challenges
- ISO 8124 toy safety certification timelines:Multi-phase testing protocols for youth-marketed equipment delay product launches and freeze inventory commitments during approval windows.
- Frame collapse incident response capacity:US Consumer Product Safety Commission monitoring requires rapid traceability systems and recall infrastructure that smaller manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spikeball Equipment Market |
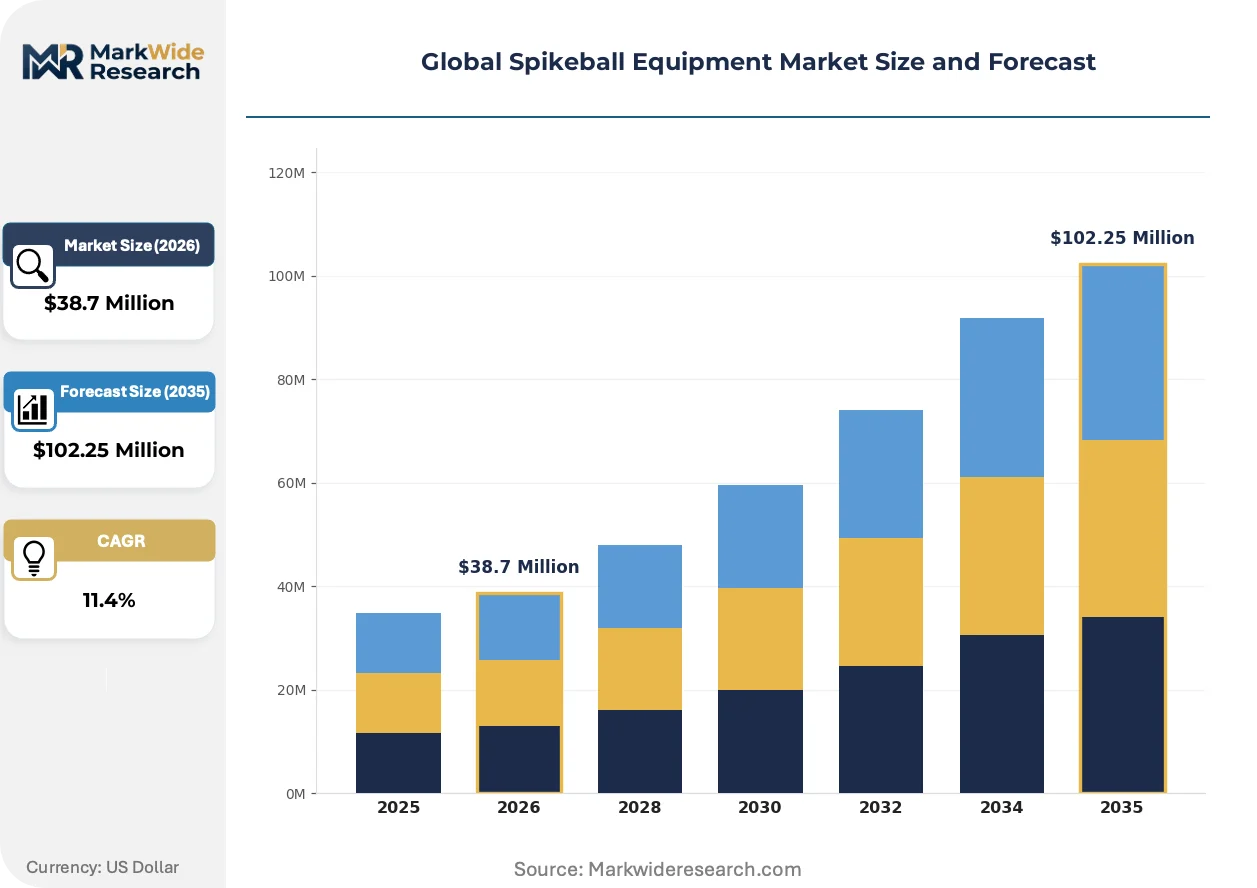
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spikeball Set, Balls, Replacement Parts, Accessories Material: Plastic, Steel, Nylon, Foam End User: Households, Schools, Sports Clubs, Recreational Centers Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Direct Sales |
| Companies Covered | Spikeball Inc., Franklin Sports, Gopher Sports, Rogue Fitness, GoSports, Park & Sun Sports, Slammo, Champion Sports, EastPoint Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spikeball Equipment Market Strategic Shifts
Equipment intelligence and channel restructuring are fragmenting the traditional bundled-set purchase model into componentized, service-attached relationships.
Carbon fiber-reinforced leg assemblies are electrifying competitive-grade equipment specifications. Tournament organizers in Australia specify these frames for official play due to weight reduction and transport efficiency. The technology is electrifying premium tier positioning by compressing the performance gap between portable recreational and fixed-installation sports equipment.
REACH chemical restrictions are tightening compliance scope for PVC ball coatings across European markets. Manufacturers must reformulate surface treatments or source alternative elastomer materials to maintain market access. Youth-accessible product lines face the steepest reformulation costs, pushing some suppliers toward phthalate-free TPU alternatives.
Online retail channel preference is reshaping buyer discovery and comparison behavior. Casual household purchasers in the United States now initiate research through direct-to-consumer platforms rather than specialty store consultation. Specialty retailers retain influence only in tournament-grade selection, where hands-on tension testing and frame inspection remain valued.
Global Spikeball Equipment Market Segmentation
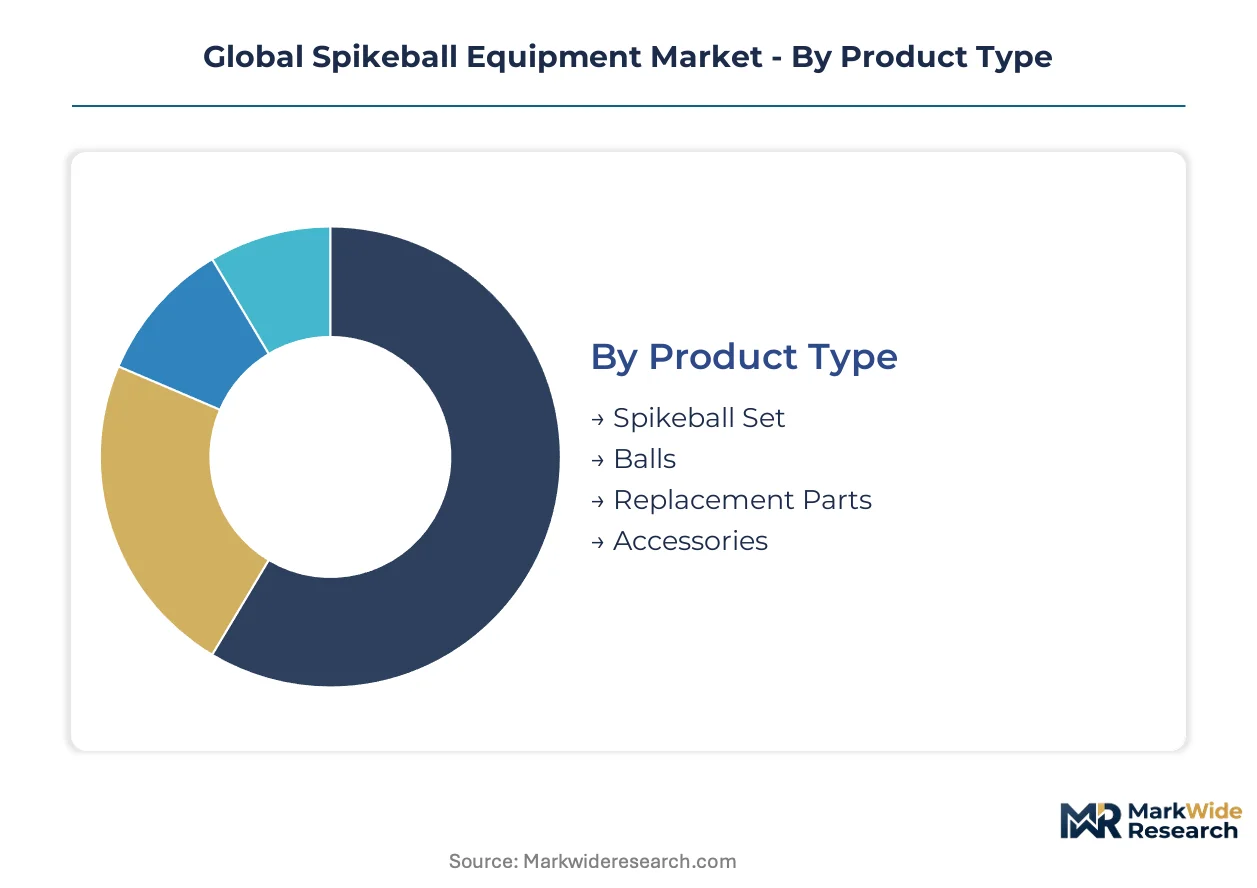
Equipment configuration and purchase occasion fragmentation create distinct margin pools across the spikeball value chain. Buyers self-select into bundled entry purchases, component replacements, or tournament-grade upgrades based on participation intensity and skill progression.
Product Type:
Purchase intent splits between first-time acquisition and lifecycle replenishment, with bundled sets anchoring household penetration while replacement components capture recurring spend from installed bases.
- Spikeball Set:Complete bundled systems comprise powder-coated steel frames, tension-adjustable nets, and inflatable balls calibrated for four-player volley play. Demand concentrates in United States suburban households where backyard recreation and beach portability drive seasonal purchase timing.
- Replacement Parts:Net tension mechanisms and inflatable ball replenishment generate recurring revenue as competitive play frequency accelerates wear cycles. Sports clubs in Germany prioritize rapid component availability to minimize court downtime across programming schedules.
- Balls:Proprietary inflatable designs with reinforced seams and calibrated bounce response serve tournament specifications.
- Accessories:Carrying cases, boundary markers, and scorekeeping tools extend equipment utility for organized play.
Volume sits with Spikeball Set; growth tilts toward Replacement Parts.
Material:
Cost-performance tradeoffs and regulatory compliance scope shape supplier selection across youth-accessible and competitive-grade product lines.
- Steel:Cold-rolled and powder-coated tubular leg assemblies provide frame rigidity and corrosion resistance for outdoor deployment. Australian tournament organizers specify steel specifications for official play certification.
- Nylon:Woven net matrices with adjustable tension threading enable bounce calibration for skill-level matching. Recreational centers in the United States specify commercial-grade nylon for high-frequency institutional use.
- Plastic:Injection-molded frame connectors and leg caps reduce unit cost for entry-price positioning.
- Foam:Padded ball coatings and protective frame wraps address youth safety requirements under ISO 8124 toy standards.
Steel dominates unit economics; nylon commands margin expansion.
End User:
Procurement authority and budget source fragmentation create parallel sales motions across consumer, institutional, and commercial channels.
- Households:Casual recreational purchasers prioritize portability and price accessibility for backyard and beach occasions. United States household demand peaks in spring-summer seasons aligned with outdoor activity migration.
- Sports Clubs:Competitive programming requires tournament-grade equipment with standardized specifications for league play. German sports clubs drive volume through municipal facility procurement frameworks.
- Schools:Physical education curriculum integration depends on sports federation recognition decisions for budget eligibility.
- Recreational Centers:Space utilization optimization priorities favor portable court sports with rapid setup-breakdown cycles.
Households anchor volume base; sports clubs drive premium tier absorption.
Distribution Channel:
Discovery behavior and purchase confidence requirements fragment channel preference by buyer sophistication and equipment grade.
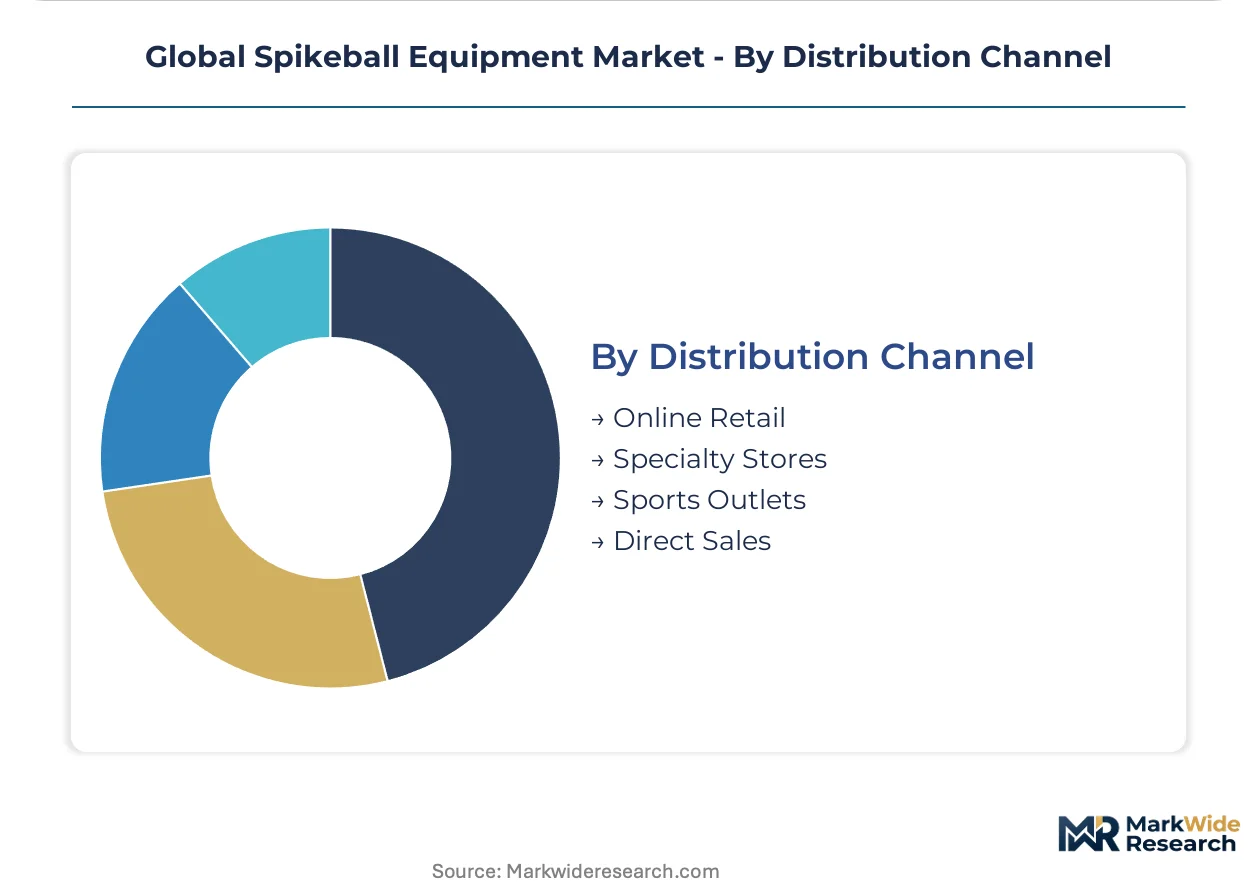
- Online Retail:Direct-to-consumer platforms enable specification comparison and bundled pricing transparency for casual purchasers. United States household buyers initiate research through digital channels before finalizing purchase.
- Specialty Stores:Hands-on tension testing and frame inspection support tournament-grade selection for competitive players. Australian specialty retailers anchor brand authority through official play certification partnerships.
- Sports Outlets:Mass-market sporting goods chains provide seasonal visibility and impulse purchase placement for entry sets.
- Direct Sales:Tournament ecosystem and club partnerships enable volume pricing for institutional procurement.
Online Retail climbs fastest; Specialty Stores retain premium tier control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors tournament infrastructure development for competitive spikeball, with municipal parks departments investing in portable court installations across lakefront recreational corridors.
United States
Suburban household penetration peaks in spring-summer seasons aligned with backyard recreation migration. The US Consumer Product Safety Commission monitors frame collapse incident reports, tightening traceability requirements for youth-accessible equipment. Austin and Denver clusters concentrate tournament organizer activity, driving premium-tier equipment certification demand.
Germany
Municipal fitness facilities prioritize portable court sports to maximize space utilization across programming schedules. EU REACH phthalate restrictions govern PVC ball coating formulations, adding compliance testing overhead for market access. Bavarian sports clubs anchor volume procurement through regional facility management frameworks.
Australia
Pending sports federation recognition decisions could qualify spikeball for national physical education curriculum budgets. The Therapeutic Goods Administration adjacent product safety oversight influences youth equipment import standards. Sydney and Melbourne clusters concentrate tournament-grade carbon fiber frame adoption for official play specifications.
United Kingdom
Coastal recreational demand concentrates in Cornwall and Devon beach tourism corridors during peak summer windows. CE marking requirements under EU-UK Trade and Cooperation Agreement alignment maintain safety standard continuity. London specialty retailers anchor brand authority through hands-on equipment inspection services.
Canada
Seasonal outdoor recreation demand compresses purchase timing into May-September windows across Ontario and British Columbia. Health Canada product safety guidelines constrain inflatable ball valve design for youth-marketed sets. Toronto municipal recreation centers pilot portable court sports programming to diversify facility utilization.
Global Spikeball Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent equipment grade specifications. The vendor base stratifies into three tiers: tournament-ecosystem anchors, mass-market retail penetrators, and price-accessible entry set suppliers. Strategic archetypes include brand-loyalty builders leveraging competitive play infrastructure, margin optimizers focusing on replacement part recurring revenue, and seasonal impulse marketers capturing casual household trial. Dominant competitive moves encompass direct-to-consumer platform expansion and institutional procurement partnership formation.
Within the tournament-ecosystem tier, Spikeball Inc. exemplifies brand-loyalty anchoring through competitive play infrastructure investment. Franklin Sports occupies a position among mass-market retail penetrators with big-box distribution scale. GoSports represents the price-accessible entry set archetype targeting casual household trial occasions.
| Leading Market Players |
|---|
| Spikeball Inc. |
| Franklin Sports |
| Gopher Sports |
| Rogue Fitness |
| GoSports |
| Park & Sun Sports |
| Slammo |
| Champion Sports |
| EastPoint Sports |
| Others |
Value Chain & Pricing Dynamics
EU REACH phthalate restrictions on PVC ball coatings gate qualified supply access for European market entry while simultaneously compressing margin pools for non-compliant producers, creating a bifurcation where premium-tier pricing power concentrates with reformulation-capable manufacturers.
Pricing Analysis
Tournament-grade equipment certification anchors value-based pricing for competitive players seeking official play eligibility. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber-reinforced tournament frames from powder-coated steel recreational sets from plastic connector entry units. Price differentiation stems from frame material grade and sports federation certification status. Cost compression in entry-tier steel sets is intensifying because cold-rolled steel input volatility squeezes producer margins. Casual household buyers exhibit highest price sensitivity, while Australian tournament organizers demonstrate lowest sensitivity due to official play specification requirements.
Supply Chain Analysis
Powder-coated steel tubing supply rests on Chinese cold-rolled steel producers and German specialty coating chemical manufacturers. Nylon net matrices draw from United States textile weavers and Southeast Asian synthetic fiber suppliers. Inflatable ball production hinges on Taiwan elastomer processors and domestic PVC compounders. Single-source vulnerability concentrates in certified carbon fiber leg assemblies for tournament-grade equipment. Distribution runs through direct-to-consumer platforms for casual purchasers and specialty retail partnerships for competitive-grade selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as EU REACH compliance costs and ISO 8124 certification timelines force capital-constrained import-only suppliers toward exit, concentrating share among reformulation-capable incumbents with established recall infrastructure.
For Market Incumbents: Anticipate frame collapse incident response requirements by building rapid traceability systems and recall logistics before US Consumer Product Safety Commission enforcement intensifies. Deepen vertical integration into cold-rolled steel sourcing to buffer powder-coated leg input volatility. Prioritize subscription replacement part program infrastructure to capture lifetime value from installed bases as competitive play frequency accelerates wear cycles.
For New Entrants and Emerging Players: Direct-to-consumer platform penetration offers the most viable entry route for price-accessible household trial sets bypassing specialty retail gatekeeping. Target underpenetrated Canadian municipal recreation center procurement frameworks where portable court sports programming is expanding. Position around indoor surface compatibility engineering to differentiate from grass-sand legacy positioning.
For Investors and Strategic Acquirers: Pending Australia sports federation recognition decisions are the leading indicator that institutional demand generation will accelerate, qualifying spikeball for national physical education curriculum budgets. Long-term viability favors acquisition targets with established tournament ecosystem partnerships and reformulation-compliant European market access. Watch carbon fiber frame adoption rates in Sydney and Melbourne tournament clusters as premium-tier demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Replacement Part Program Launch | Captures recurring revenue from installed bases as competitive wear cycles accelerate. |
| Carbon Fiber Frame Manufacturing Scale-Up | Meets Australian tournament organizer specifications for official play certification. |
| Indoor Surface Compatibility Engineering | Expands addressable occasions beyond grass and sand into gymnasium deployment. |
| EU REACH Phthalate-Free Reformulation | Maintains European market access as chemical restrictions tighten compliance scope. |
| Tournament Ecosystem Partnership Expansion | Anchors brand loyalty through competitive play infrastructure investment. |
Study Parameters
Document review covered sports equipment trade publications, regulatory filing databases, and municipal procurement records, complemented by interviews with tournament organizers, specialty retail buyers, and physical education curriculum directors. Primary fieldwork engaged spikeball equipment manufacturers, steel tubing suppliers, and synthetic net weavers. Secondary validation drew from customs import data, recreational facility capital expenditure disclosures, and sports federation recognition proceedings. Bottom-up demand modeling triangulated against top-down market sizing across household, institutional, and commercial end-use segments.
Segment-level outputs across product type, material grade, end-user category, and distribution channel fed into consolidated projections over the analysis window. Competitive intensity scoring incorporated tournament certification status, retail partnership depth, and replacement part program maturity. CAGRs derived from equipment lifecycle analysis, wear rate assumptions tied to competitive play frequency, and institutional procurement pipeline tracking. Carbon fiber adoption curves and school curriculum integration timelines served as industry-specific forecast inputs.
Inputs from tournament organizers and municipal recreation directors were available through the study window; gaps in proprietary manufacturer cost data introduce uncertainty bands around margin pool estimates. Forecasts reflect documented assumptions regarding sports federation recognition timing and steel input cost trajectories. Regulatory enforcement intensity and substitute equipment substitution rates warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Concussion Helmets Market
Sports Equipment
Surfboard Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Golf Bags Market
Sports Equipment
Wetsuits Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Crampon Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Global Cycling Power Meters Market