
 Bicycle Shoe Market | 2026-2036
Bicycle Shoe Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Shoe Market Outlook
Multi-source carbon fiber sourcing is restructuring supply economics for mid-tier producers while Shimano leverages captive resin compounding to sustain margin control. Giro competes through domestic last-making expertise, and Specialized anchors premium positioning via proprietary Body Geometry fit systems. Northwave dominates European mountain bike channels with reinforced toe protection.
A bicycle shoe is a stiff-soled, pedal-interface footwear engineered with carbon fiber or nylon composite platforms, closure tension systems, and cleat mounting standards to maximize power transfer and reduce repetitive strain during cycling. Road shoes command the highest unit margins through ultra-stiff carbon soles, while mountain shoes capture volume through walkable rubber outsoles and recessed cleat pockets. Mesh uppers are displacing leather in humid climates, and the Boa closure system is concentrating share in triathlon shoes where rapid transitions determine competitive outcomes.
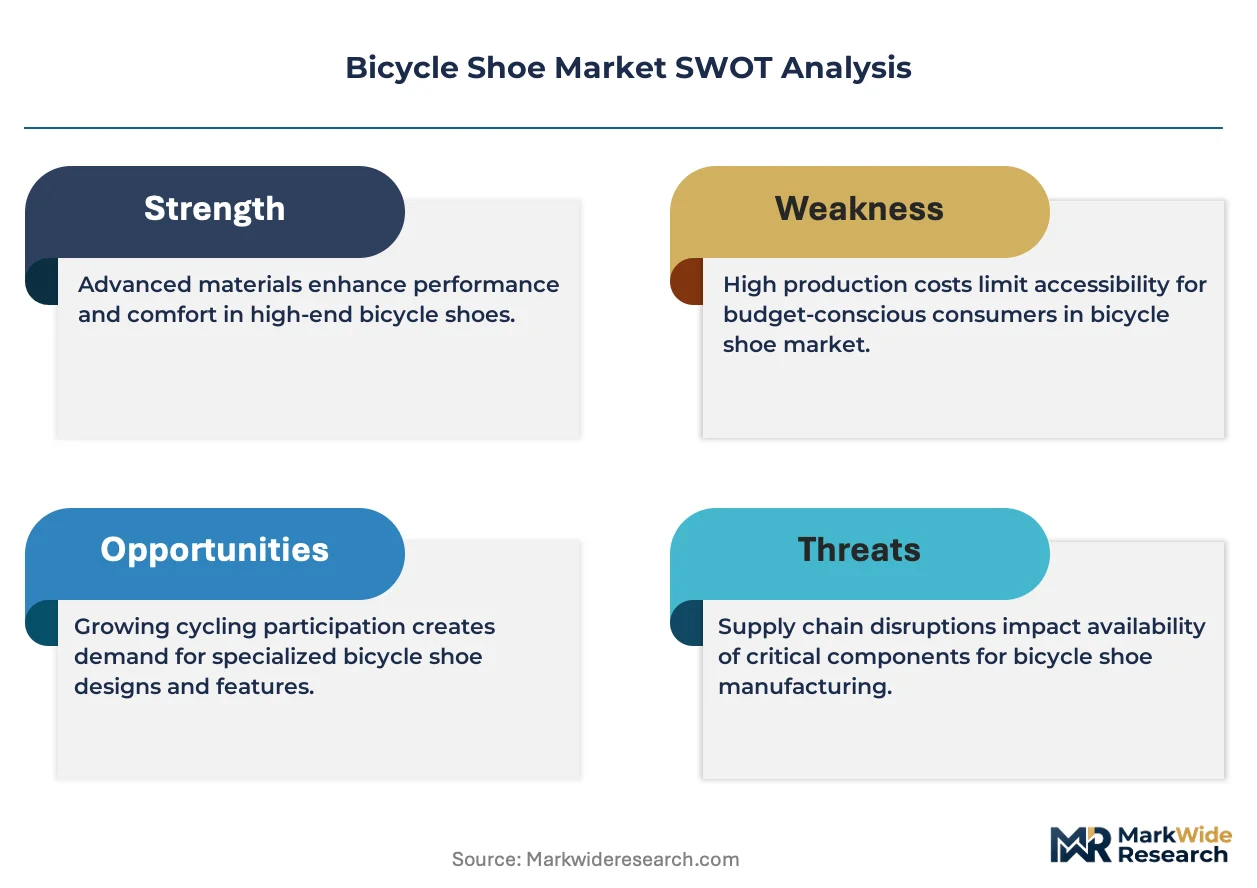
ISO 20344 impact resistance standards, EU REACH chemical compliance for solvent-based adhesives, and CPSC cleat release torque specifications collectively elevate compliance costs for new entrants. The EU Green Deal's recycled-content mandates are redirecting R&D budgets toward bio-based synthetics and reclaimed carbon fiber. Stakeholders must monitor how closure-system patents expire and whether heat-moldable midsole platforms become table stakes for the competitive athlete tier.
Market Dynamics
Carbon fiber plate integration is restructuring procurement priorities across competitive cycling tiers, redirecting volume toward suppliers capable of captive resin compounding and heat-moldable platform manufacturing.
Growth Catalysts
- EU Green Deal recycled-content mandates:Bio-based synthetic development is capturing R&D investment from premium manufacturers seeking compliance advantage ahead of enforcement timelines.
- Gravel racing participation:Mixed-terrain competitive formats are expanding addressable demand beyond traditional road and mountain bike silos, requiring versatile sole stiffness profiles.
- Heat-moldable uppers:Custom fit technology is reducing return rates and elevating average selling prices in the competitive athlete segment.
Market Restraints
- Carbon fiber supply concentration:Toray and Hexcel captive capacity limits mid-tier producer access to aerospace-grade prepregs, forcing reliance on industrial-grade alternatives with performance tradeoffs.
- REACH solvent adhesive compliance:EU chemical registration costs are elevating entry barriers for artisan manufacturers in Veneto and Portugal.
- Walkable rubber outsole substitution:Mountain bike shoes face margin pressure as hiking footwear manufacturers enter the gravel segment with dual-purpose designs.
Strategic Opportunities
- Indian competitive cycling infrastructure:National federation investment in velodrome construction is creating first-mover advantage for heat-moldable platform introduction.
- Direct-to-fit retail kiosks:3D foot scanning combined with same-day manufacturing is compressing distribution layers in urban cycling hubs.
- Boa closure patent expiration:Alternative dial-system suppliers are entering with royalty-free architectures, enabling margin recovery for mid-tier brands.
Industry Challenges
- Last-making artisan scarcity:Traditional footwear pattern engineering expertise is concentrating among Italian and Portuguese family operations, limiting production scale-up.
- ISO 20344 certification timelines:Impact resistance testing protocols are extending product development cycles by four to six months for new entrants.
- Cleat standard fragmentation:Competing three-bolt and two-bolt mounting specifications are forcing inventory duplication across regional distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Shoe Market |
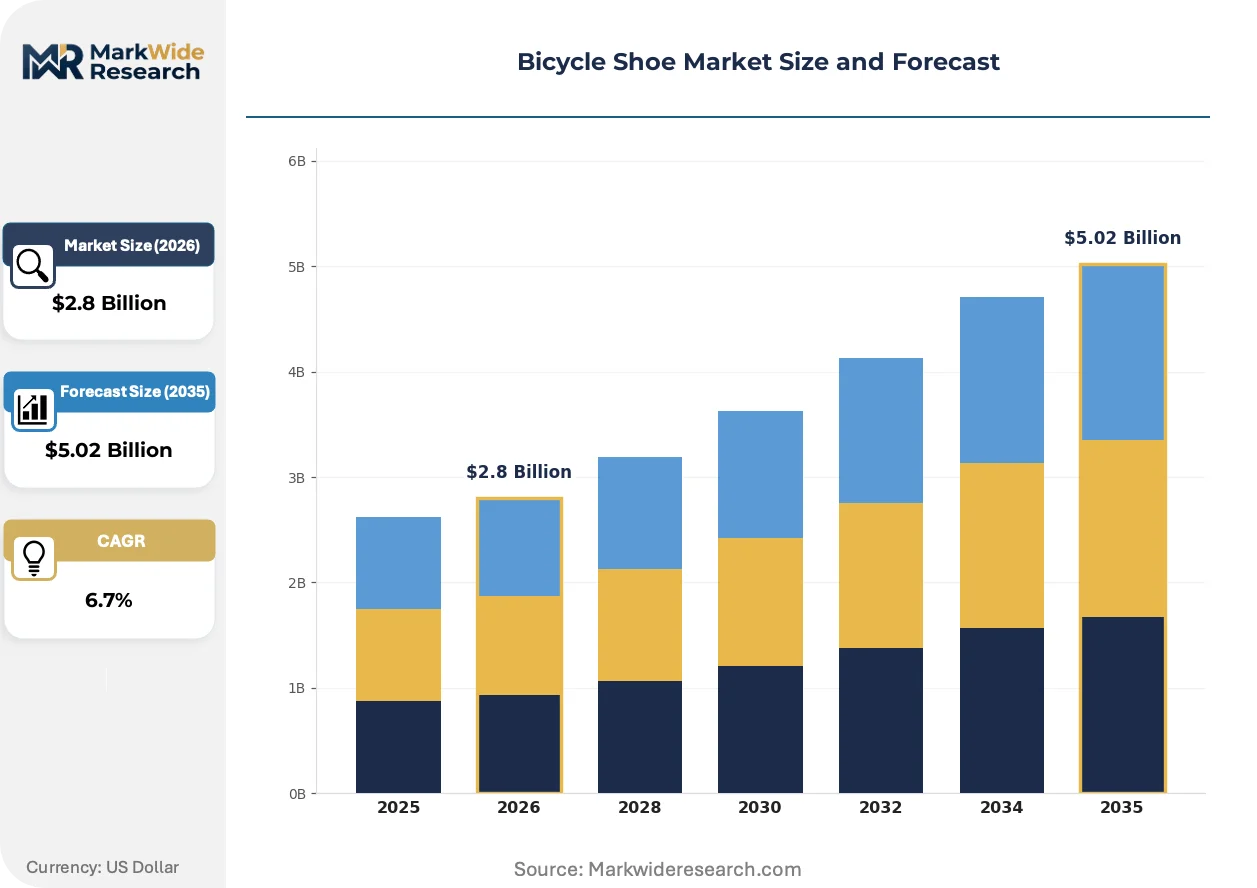
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road Shoes, Mountain Shoes, Triathlon Shoes, Commuter Shoes Material: Leather, Synthetic, Mesh, Carbon Fiber Closure Type: Lace, Velcro, Boa System, Double Strap End User: Professional Cyclists, Recreational Riders, Commuters, Competitive Athletes |
| Companies Covered | Lake, Giro, Shimano, Bont, Fizik, Specialized, Northwave, DMT, Sidi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Shoe Market Strategic Shifts
Closure system architecture, sole platform materials, and fit customization protocols are converging to redefine performance benchmarks and supplier selection criteria across competitive cycling tiers.
Carbon fiber plate technology is integrating into mid-sole platforms to deliver longitudinal stiffness without weight penalty. Competitive triathletes and gravel racers are adopting these platforms fastest, demanding walkable stiffness indices above twelve. This is integrating performance road and mountain bike categories into unified product architectures that compress supplier specialization.
REACH chemical compliance for solvent-based adhesives is elevating formulation costs for European manufacturers. ECHA registration requirements are redirecting adhesive procurement toward water-based alternatives with extended curing times. Italian artisan clusters in Veneto are absorbing these costs through premium positioning, while volume producers are relocating finishing operations to non-EU jurisdictions.
Direct-to-consumer fit customization is displacing traditional retail inventory models. Urban cycling hubs in Copenhagen, Amsterdam, and Portland are piloting 3D scanning kiosks linked to regional micro-factories. Competitive athletes in these markets are accepting two-week delivery windows in exchange for personalized last geometry, compressing distributor margins and elevating manufacturer capture rates.
Bicycle Shoe Market Segmentation
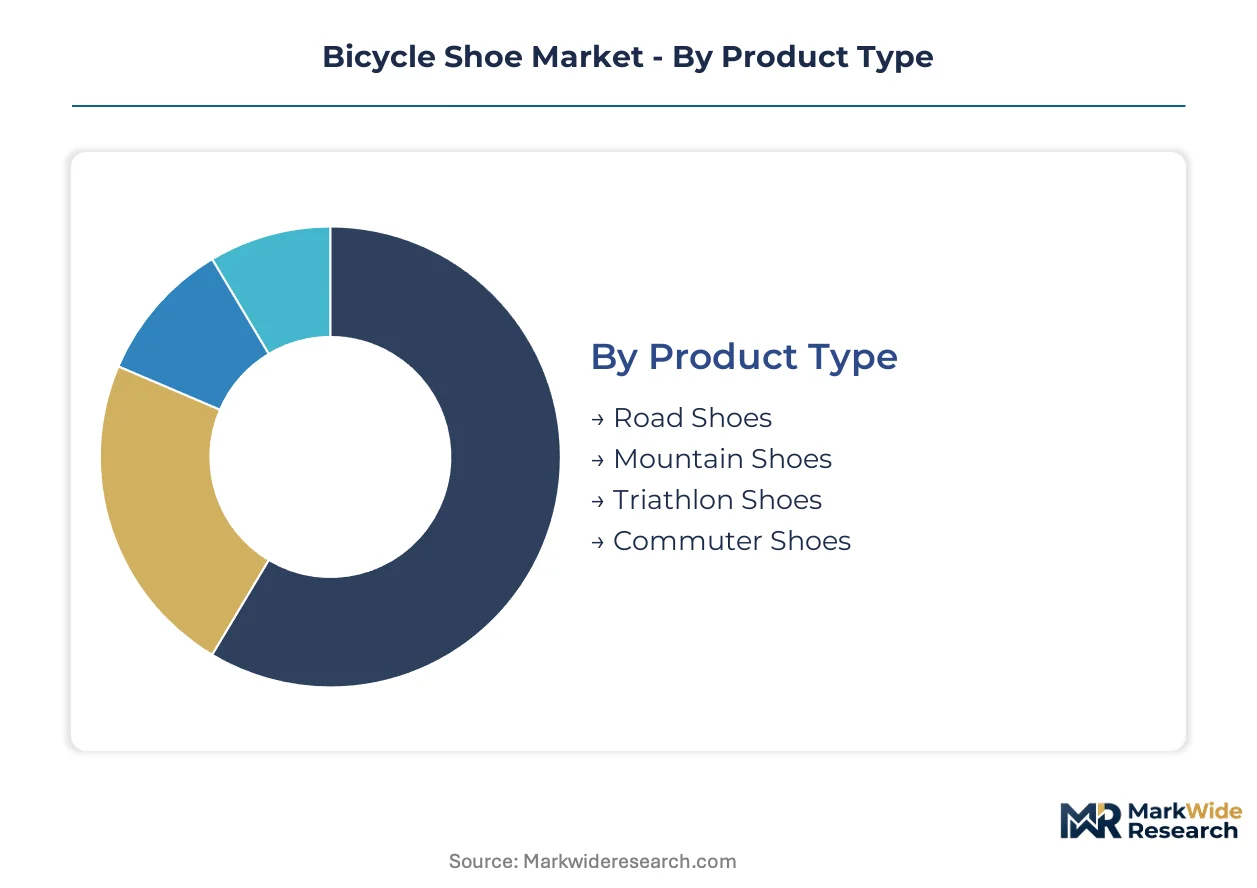
Segmentation in bicycle footwear reveals how construction specifications, material choices, and user intensity levels create divergent margin profiles and supplier specialization requirements across competitive cycling tiers.
Product Type:
Stiffness indices and cleat mounting standards define performance ceilings and channel placement for each product architecture.
- Road Shoes:Ultra-stiff carbon fiber platforms with three-bolt cleat interfaces maximize power transfer on paved surfaces. Italian artisan clusters in Veneto anchor premium manufacturing for competitive road cyclists seeking sub-200-gram weights.
- Mountain Shoes:Walkable rubber outsoles with recessed two-bolt cleat pockets balance pedaling efficiency with hike-a-bike functionality. Demand concentrates in Pacific Northwest trail networks where enduro racing formats require reinforced toe protection.
- Triathlon Shoes:Single-strap or Boa closure systems enable rapid transitions between swim, bike, and run segments. Kona Ironman qualifiers drive specification requirements for drainage ports and barefoot-friendly linings.
- Commuter Shoes:Casual styling with internal cleat mounting accommodates urban cyclists requiring workplace-appropriate aesthetics. Copenhagen and Amsterdam cycling infrastructure investments elevate demand for weather-sealed uppers.
Road shoes lead on scale; triathlon shoes lead on momentum.
Material:
Weight-to-strength ratios and climate adaptability determine material selection hierarchies across price tiers.
- Carbon Fiber:Longitudinal stiffness plates integrated into mid-sole platforms deliver power transfer efficiency without weight penalty. Gravel racing adoption is accelerating demand for walkable carbon constructions with stiffness indices above twelve.
- Synthetic:Bio-based polyurethane formulations are capturing R&D investment ahead of EU Green Deal recycled-content mandates. Volume producers favor synthetic uppers for heat-moldable customization at mid-tier price points.
- Mesh:Breathable synthetic weaves displace leather in humid climates where moisture management determines comfort outcomes. Southeast Asian competitive cycling federations specify mesh-dominant constructions for national team procurement.
- Leather:Traditional full-grain uppers retain positioning in heritage-oriented road segments. REACH solvent-based adhesive compliance costs are concentrating leather finishing among Italian artisan operations with established ECHA registration pathways.
Synthetic materials lead on scale; carbon fiber leads on momentum.
Closure Type:
Tension distribution and micro-adjust precision separate competitive performance from recreational convenience.
- Boa System:Dial-actuated stainless steel cables enable single-hand adjustment and uniform pressure distribution. Patent expiration timelines are enabling alternative dial-system suppliers to enter with royalty-free architectures.
- Velcro:Hook-and-loop straps deliver cost-effective security for entry-level road and commuter categories. Portuguese contract manufacturers specialize in high-cycle-life Velcro specifications for rental fleet applications.
- Double Strap:Traditional two-strap configurations retain share in cyclocross where mud clearance trumps micro-adjust capability. Belgian and Dutch domestic racing calendars sustain niche demand.
- Lace:Classic eyelet constructions persist in gravel and bikepacking segments where field repairability matters. Custom lace colorways support limited-edition collaborations with regional cycling collectives.
Velcro leads on scale; Boa system leads on momentum.
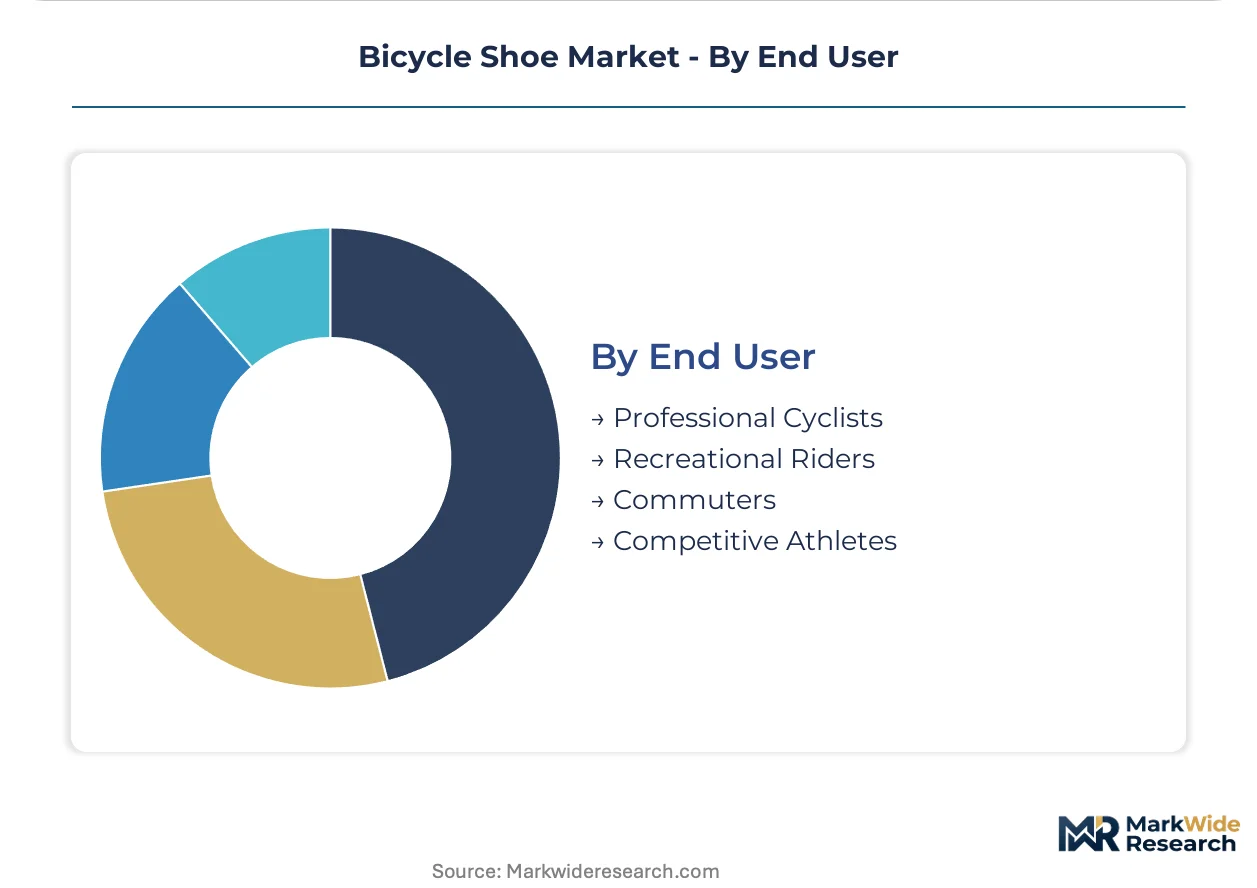
End User:
Training volume and competitive intensity create divergent durability expectations and fit customization requirements.
- Competitive Athletes:Heat-moldable uppers and proprietary fit systems reduce repetitive strain injuries during high-volume training blocks. Gravel racing and triathlon participation broadening is expanding this segment most quickly.
- Professional Cyclists:UCI WorldTour teams receive custom last development with seasonal colorway exclusivity. Sponsor-driven specification lock-in limits switching behavior across contract cycles.
- Recreational Riders:Weekend enthusiasts prioritize walkable comfort over maximum stiffness. Retail inventory models favor this segment with immediate-availability standard widths.
- Commuters:Urban utility cyclists demand weather protection and reflective elements over performance metrics. City-specific bike-share integration programs in Paris and London influence bulk procurement specifications.
Recreational riders lead on scale; competitive athletes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veneto's artisan cycling footwear cluster anchors premium manufacturing for competitive road and triathlon segments, while gravel racing adoption spreads demand across North American trail networks and Asian velodrome construction programs.
United States
Pacific Northwest enduro racing formats and Colorado gravel series drive demand for walkable carbon constructions with reinforced toe protection. EPA oversight of solvent-based adhesive emissions affects domestic finishing operations. Portland and Boulder anchor direct-to-consumer fit customization pilots with 3D scanning kiosks.
Italy
Veneto's last-making heritage sustains premium road shoe manufacturing for UCI WorldTour supply chains. EU REACH chemical registration requirements concentrate solvent-based adhesive finishing among established ECHA-registered artisan operations. Montebelluna's industrial district hosts heat-moldable platform R&D for competitive athlete tiers.
Germany
Ruhrgebiet urban cycling infrastructure and Bavarian mountain bike tourism elevate commuter and trail shoe specifications. KBA-aligned product safety standards intersect with EU Green Deal recycled-content mandates for bio-based synthetic development. Stuttgart's engineering clusters prototype stiffness-index optimization for gravel racing applications.
China
National velodrome construction and competitive cycling federation investment create demand for heat-moldable entry-level platforms. MIIT industrial standards for footwear manufacturing quality shape export compliance requirements. Guangdong Province contract manufacturers supply synthetic upper volumes for mid-tier global brands.
India
National federation investment in velodrome infrastructure and competitive cycling development programs drives first-mover opportunity for heat-moldable platform introduction. BIS certification requirements for imported footwear safety standards affect premium product entry timelines. Maharashtra's emerging manufacturing zones absorb assembly relocation from EU jurisdictions facing REACH cost pressures.
Bicycle Shoe Market Competitive Environment
Global majors compete with regional champions across closure-system technology and carbon fiber sourcing dimensions, producing a tiered structure where captive resin compounding separates premium positioning from mid-tier volume play. Japanese and Italian conglomerates anchor proprietary fit system development, while Portuguese and Chinese contract manufacturers capture synthetic upper and Velcro assembly scale. Three archetypes dominate: vertically integrated material specialists, last-making artisan houses, and direct-to-consumer fit technology platforms. Strategic moves concentrate on heat-moldable platform licensing and regional micro-factory partnerships.
Within the premium-tier vector, Specialized and Shimano exemplify divergent approaches to proprietary technology capture, while Giro represents North American domestic last-making expertise. Italian specialists including Sidi, DMT, and Northwave occupy positions anchored in Veneto's artisan manufacturing heritage. Lake and Bont exemplify the heat-moldable customization archetype, with Fizik representing performance road positioning within European competitive cycling supply chains.
| Leading Market Players |
|---|
| Lake |
| Giro |
| Shimano |
| Bont |
| Fizik |
| Specialized |
| Northwave |
| DMT |
| Sidi |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recycled-content mandates gate qualified supply and premium-tier pricing access, concentrating compliant bio-based synthetic sourcing among established Italian and Portuguese manufacturers while elevating entry costs for artisan competitors lacking ECHA registration pathways.
Pricing Analysis
Input-cost pass-through from aerospace-grade carbon fiber prepregs concentrates pricing power among producers with captive resin compounding capabilities. Three-tier pricing structure across premium, standard, and economy levels separates heat-moldable platforms with proprietary fit systems from Velcro-strap commuter models. Pricing pressure stems from industrial-grade carbon fiber substitution as Toray and Hexcel captive capacity limits mid-tier access. Recreational riders exhibit highest price sensitivity; competitive athletes accept premium positioning for injury-reduction benefits.
Supply Chain Analysis
Reverse-logistics flows for heat-moldable platform refurbishment remain underdeveloped, with most worn carbon fiber mid-soles entering landfill rather than reclamation streams. Manufacturing concentrates in Italy, Portugal, and China, drawing from Toray carbon fiber prepregs, synthetic upper textiles, and Boa closure system components. Single-source vulnerability runs through Japanese carbon fiber suppliers and Swiss dial-system architectures. Distribution runs through specialty cycling retailers, direct-to-consumer fit kiosks in urban cycling hubs, and OEM team sponsorship channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in heat-moldable platform licensing and regional micro-factory partnerships, with bio-based synthetic development capturing compliance premiums ahead of enforcement timelines.
For Market Incumbents: Extend proprietary fit system ecosystems through heat-moldable platform licensing to regional manufacturers, defending against direct-to-consumer fit technology entrants. Deepen backward integration into captive carbon fiber resin compounding to sustain margin control as industrial-grade alternatives proliferate. Anchor Veneto manufacturing heritage against Portuguese cost-competitive positioning.
For New Entrants and Emerging Players: Direct-to-consumer fit kiosks represent the most penetrable channel, particularly in Copenhagen, Amsterdam, and Portland where cyclists accept extended delivery windows for personalized geometry. Target Indian velodrome construction programs with entry-level heat-moldable introductions ahead of established brand presence. Pursue Boa patent expiration timing to deploy royalty-free dial architectures at mid-tier price points.
For Investors and Strategic Acquirers: Roll-up economics work for Italian last-making artisan houses because generational succession pressures concentrate proprietary pattern engineering expertise among shrinking family operations. Five-to-ten-year viability hinges on heat-moldable platform standardization becoming table stakes for competitive athlete tiers. Monitor Boa closure patent expiration and EU Green Deal enforcement timelines as inflection indicators for mid-tier margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Moldable Platform Licensing | Specialized and Bont capture recurring revenue from regional manufacturers seeking fit customization capabilities without R&D investment. |
| Bio-Based Synthetic Development | Italian manufacturers absorb REACH compliance costs through premium positioning while volume producers relocate finishing to non-EU jurisdictions. |
| Direct-to-Consumer Fit Kiosk Expansion | 3D scanning infrastructure in Copenhagen and Amsterdam compresses distributor margins and elevates manufacturer capture rates. |
| Carbon Fiber Prepreg Supply Agreement | Shimano's captive resin compounding sustains margin control unavailable to mid-tier producers dependent on industrial-grade alternatives. |
| Regional Micro-Factory Partnership | Same-day manufacturing pilots in Portland and Boulder reduce inventory carrying costs and enable personalized last geometry at scale. |
Study Parameters
Multiple input streams — primary interviews with competitive cyclists, footwear procurement managers at UCI WorldTour teams, and Veneto artisan manufacturers; secondary validation through customs records, ECHA chemical registration databases, and cycling federation procurement specifications — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material composition, closure architecture, and end-user intensity dimensions shaped analytical frameworks over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating gravel racing participation trajectories, velodrome construction programs, and heat-moldable platform adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon fiber supply concentration, Boa patent expiration timing, and EU Green Deal recycled-content mandate enforcement. Practitioners should monitor Indian federation infrastructure investment and alternative dial-system supplier entry for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Golf Bags Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Rowing Oars Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Knee Pads Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Global Weighted Hula Hoop Market