
 Golf Shoes Market | 2026-2036
Golf Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Shoes Market Intelligence
Chinese contract footwear manufacturing is decoupling from pure volume contracts as brands seek dedicated golf-specific production lines. FootJoy leverages its century-long heritage in cleated performance to sustain dominance among tour professionals and serious amateurs. Adidas competes through its Boost midsole platform, which extends running-shoe cushioning science into spikeless course footwear. TRUE Linkswear specializes in minimalist silhouettes that occupy the casual-wear crossover niche, blurring boundaries between on-course performance and street-ready aesthetics.
Golf shoes are purpose-built athletic footwear engineered with waterproof leather or synthetic uppers, thermoplastic cleat receptacles or molded rubber traction patterns, and torsion-resistant midsole plates to stabilize rotational swing forces. Their primary commercial function is to deliver ground grip, lateral support, and weather protection across varied turf conditions during the golf swing. Spikeless configurations now lead volume growth as municipal and resort courses restrict traditional metal or plastic cleats to preserve greens surfaces, while leather uppers command the premium margin pool due to durability perceptions and tour-player association. The professionals end-user tier generates outsized brand halo effects despite smaller unit scale, shaping R&D priorities across manufacturers.
The United States Consumer Product Safety Commission oversees general footwear safety standards, while ASTM International publishes slip-resistance test methods that influence golf shoe outsole design requirements for liability-conscious retailers. California's Proposition 65 chemical disclosure rules affect synthetic material sourcing decisions for brands distributing in that state. Stakeholders must monitor evolving course access policies and sustainability disclosure mandates as these forces increasingly determine which product architectures secure retail placement and consumer preference.
Market Dynamics
Spikeless traction systems are compressing traditional cleated architectures as municipal courses tighten surface preservation rules and recreational golfers prioritize versatility across clubhouse-to-street transitions.
Growth Catalysts
- California Proposition 65:Chemical disclosure mandates for synthetic uppers are accelerating transparency investments that premium brands leverage as competitive differentiation in coastal retail channels.
- Waterproof membrane integration:eVent and Gore-Tex laminates are expanding addressable season length for golfers in temperate climates, converting three-season buyers into year-round equipment purchasers.
- Recreational participation:Municipal course expansion across Texas, Florida, and Arizona is creating first-time footwear demand outside traditional country club demographics.
Market Restraints
- Leather input volatility:Full-grain hide costs fluctuate with cattle supply cycles and tanning capacity constraints in Italian and Portuguese supplier networks.
- Chinese production concentration:Dedicated golf-specific manufacturing lines remain concentrated in Dongguan and Putian, creating single-source vulnerability for mid-tier brands without captive factory relationships.
- Thermoplastic cleat receptacle lifespan:Mechanical fatigue in rotational stress zones limits product replacement cycles compared to leather upper durability, compressing recurring revenue timing.
Strategic Opportunities
- India course development:DLF Golf and Country Club expansions near Delhi and Bangalore signal underpenetrated demand for performance footwear among emerging upper-middle-class participants.
- EU Green Deal alignment:Bio-based polyurethane midsoles and solvent-free adhesives position products for preferential retail placement in German and Dutch sustainability-focused pro shops.
- Direct-to-consumer fit technology:3D foot scanning and AI-driven last recommendations reduce return rates while capturing margin previously allocated to specialty retail.
Industry Challenges
- Biomechanical engineering talent:Specialized golf swing kinematics expertise sits concentrated within incumbent brands, constraining new entrant R&D velocity.
- ASTM slip-resistance certification:Multi-surface traction testing protocols extend product development timelines by four to six months for liability-conscious retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Shoes Market |
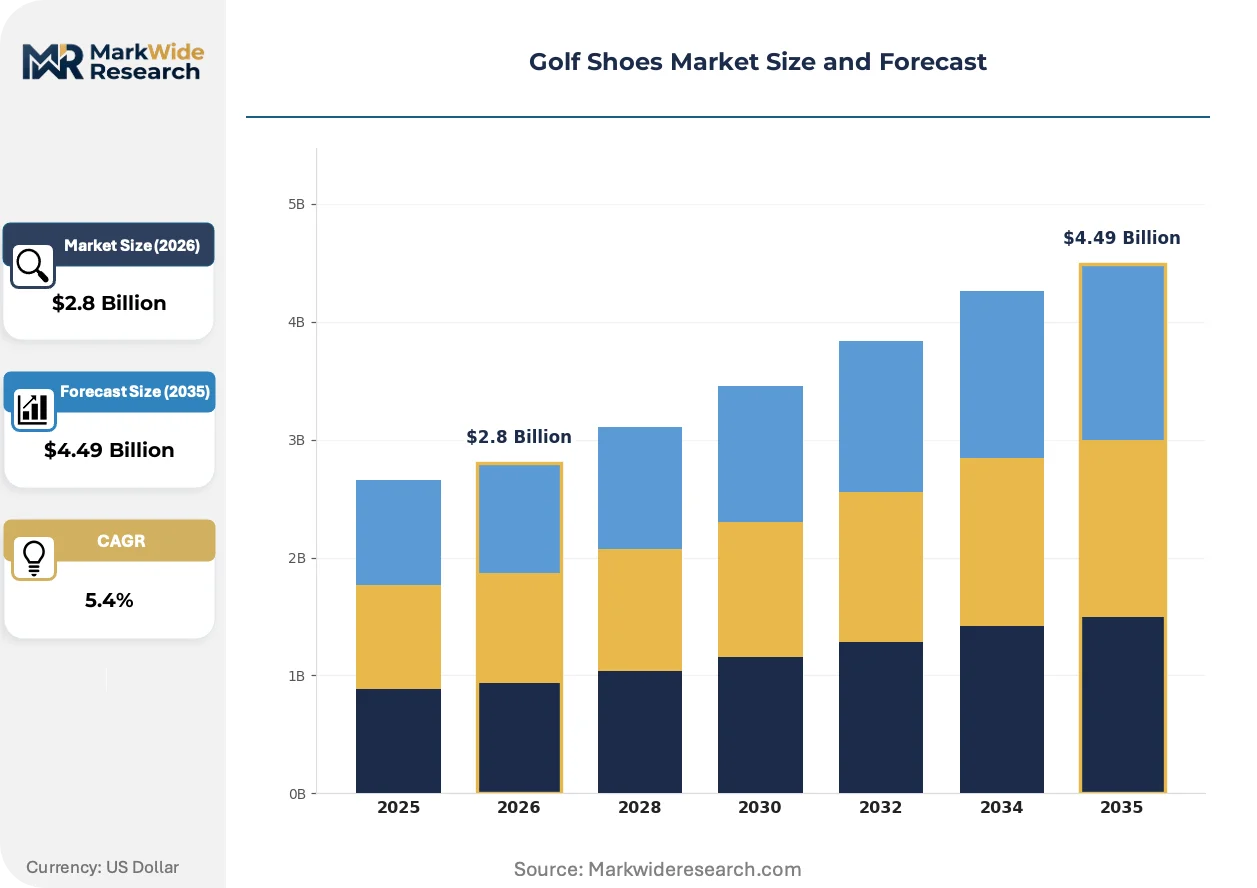
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiked, Spikeless, Retro, Lightweight Material: Leather, Synthetic, Mesh, Rubber End User: Men, Women, Juniors, Professionals Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Puma Golf, G/FORE, FootJoy, Payntr, TRUE Linkswear, Adidas, ECCO Golf, Skechers, Nike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Shoes Market Strategic Shifts & Innovations
Material science convergence with athletic footwear platforms is dissolving category boundaries between performance golf equipment and lifestyle sneaker aesthetics.
Knit uppers with targeted compression zones are overtaking stitched leather constructions as the dominant premium architecture. Recreational golfers under age forty-five are adopting these configurations at twice the rate of traditional buyers. This shift is overtaking durability-based purchase criteria with immediate comfort and breathability preferences that reshape seasonal release calendars.
REACH SVHC candidate list expansion is forcing reformulation of phthalate-based plasticizers in outsole compounds across EU-bound production lots. Manufacturers are accelerating migration to bio-circular alternatives ahead of 2027 restriction timelines. German and Benelux distributors now require pre-submitted safety data sheets as standard procurement documentation.
Specialty retail consolidation is compressing wholesale account diversity as PGA Tour Superstore and Golf Galaxy expand floor space dominance. Independent pro shops are responding with custom fitting services and localized brand curation that mass channels cannot replicate. This bifurcation is most visible in Arizona and South Carolina markets where destination golf tourism sustains independent operator viability.
Golf Shoes Market Segmentation
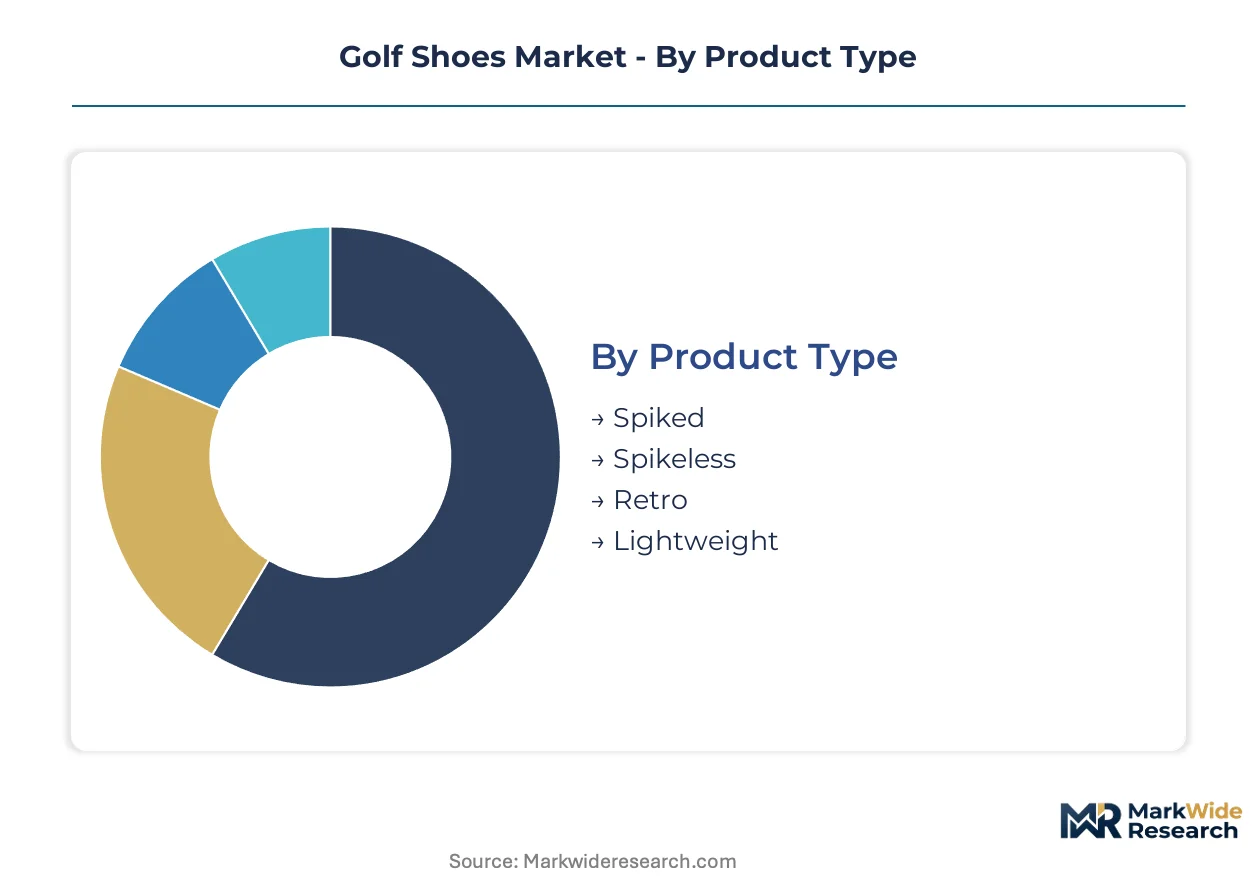
Golf shoe segmentation reveals divergent engineering priorities across player commitment levels and course access patterns. Manufacturers must architect distinct product lines for competitive swing stability versus clubhouse versatility, with material choices and closure systems calibrated to each buyer tier's performance expectations and aesthetic preferences.
Product Type:
Course surface preservation rules and lifestyle crossover desires split buyers between traditional traction engineering and hybrid versatility.
- Spiked:Thermoplastic cleat receptacles and rotational stress plates deliver maximum ground penetration for competitive play on wet or hilly terrain. Demand concentrates among tournament participants in the United Kingdom and Ireland where damp turf conditions persist through extended seasons.
- Spikeless:Molded rubber traction patterns with multidirectional lugs enable seamless transitions from fairway to clubhouse pavement without cleat replacement. Recreational golfers under age forty in Texas and Florida municipal courses are adopting these configurations at accelerating rates as dress codes relax.
- Retro:Saddle silhouettes and brogue detailing reference mid-century tournament aesthetics for collectors and heritage-focused buyers. Japanese and South Korean markets sustain niche demand through limited-edition collaborations with domestic fashion labels.
- Lightweight:Foam midsole platforms and engineered mesh uppers reduce fatigue across walking-intensive resort courses. Arizona and Palm Springs destination golfers prioritize these specifications for eighteen-hole endurance in elevated temperatures.
Volume sits with spiked configurations among dedicated amateurs; growth tilts toward spikeless as municipal access broadens.
Material:
Climate exposure duration and sustainability disclosure requirements determine upper construction selection across regional retail channels.
- Leather:Full-grain hides with waterproof membrane backing command premium positioning through durability perceptions and tour-player association. Italian tannery supply constraints in Vicenza and Tuscany are elongating procurement timelines for heritage-focused brands.
- Synthetic:Polyurethane microfiber and bio-based alternatives enable color consistency and lower unit costs for entry-tier positioning. California Proposition 65 compliance investments are accelerating transparency documentation that coastal retailers now require as standard.
- Mesh:Knit constructions with targeted compression zones prioritize breathability for summer play in humid climates. Southeast Asian manufacturing clusters in Vietnam are developing specialized knitting capacity for golf-specific tension mapping.
- Rubber:Outsole compounds with silica-enhanced wet traction dominate waterproof bootie constructions for Pacific Northwest and Scottish links conditions. REACH SVHC candidate list expansion is forcing reformulation away from phthalate-based plasticizers ahead of restriction timelines.
Revenue concentrates in leather uppers; synthetic alternatives are climbing the fastest as sustainability certifications reshape procurement criteria.
End User:
Anatomical last engineering and closure system complexity vary sharply across gender and age-based biomechanical requirements.
- Men:Wider forefoot lasts and aggressive arch support accommodate higher swing speeds and rotational torque. The United States sustains dominant volume through established course infrastructure and retail channel density.
- Women:Narrower heel cups and reduced volume lasts address distinct pressure distribution patterns. South Korean and Japanese markets are expanding addressable demand through female-specific pro shop merchandising and fitting services.
- Juniors:Adjustable closure systems and growth-accommodating sizing architectures extend product lifespan across rapid foot development. Texas and Florida junior academy programs are creating concentrated replacement demand outside traditional retail seasons.
- Professionals:Custom orthotic compatibility and tour van modification access generate outsized brand halo effects despite minimal unit scale. R&D prioritization follows professional feedback on torsional rigidity and ground interaction feel.
Unit volume flows through men's specifications; women's and junior categories are gaining share fastest as participation demographics broaden.
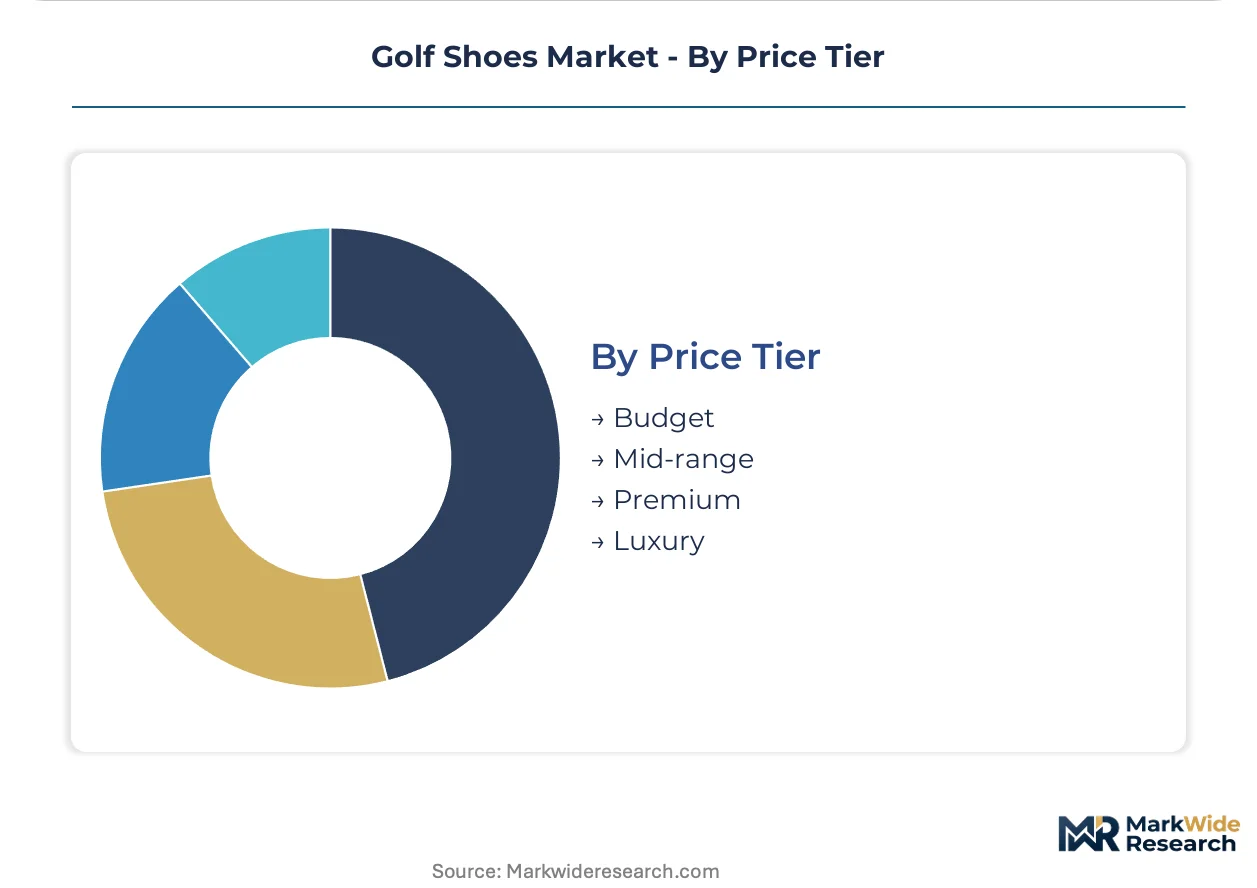
Price Tier:
Performance certification depth and material provenance separate buyers across four distinct expenditure thresholds.
- Budget:Bonded synthetic uppers and basic rubber outsoles serve entry-level municipal golfers with minimal waterproofing requirements. Mass retail channels in Walmart and Dick's Sporting Goods sustain volume through seasonal promotional calendars.
- Mid-range:Partial leather overlays and entry waterproof membranes balance durability with accessible price points for committed recreational players. This tier captures the largest absolute unit flow across United States specialty retail.
- Premium:Full-grain leather, Gore-Tex laminates, and replaceable cleat systems target serious amateurs with multi-season durability expectations. PGA Tour Superstore and Golf Galaxy floor space allocation favors these specifications.
- Luxury:Italian leather sourcing, hand-finished details, and limited production runs address collector and gift purchase occasions. Tokyo and Seoul flagship retail generates disproportionate revenue per square foot for heritage European brands.
Mid-range specifications anchor volume; premium and luxury tiers are expanding most quickly as equipment investment correlates with participation frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Portuguese tanneries supply premium full-grain leather to heritage manufacturers worldwide, anchoring material provenance for high-end golf footwear production.
United States
Municipal course expansion across Texas, Florida, and Arizona generates first-time footwear demand outside traditional country club demographics. The Consumer Product Safety Commission oversees general footwear safety standards while ASTM International publishes slip-resistance test methods influencing outsole design. PGA Tour Superstore and Golf Galaxy floor space concentration in Scottsdale and Orlando sustains specialty retail momentum.
United Kingdom
Wet turf conditions across Scottish links and Irish parkland courses sustain demand for thermoplastic cleat receptacles and waterproof membrane integration. REACH SVHC candidate list expansion forces reformulation of phthalate-based plasticizers in outsole compounds for EU-bound production. London and Manchester retail clusters favor heritage European brands with tour-player association.
Japan
Female-specific pro shop merchandising and fitting services expand addressable demand among women participants in Tokyo and Osaka metropolitan areas. METI standards influence product safety documentation for domestic distribution. Nagoya manufacturing clusters develop specialized knitting capacity for golf-specific tension mapping in premium uppers.
South Korea
Limited-edition collaborations with domestic fashion labels sustain niche demand for retro saddle silhouettes and brogue detailing in Seoul and Busan markets. The MFDS monitors chemical safety in synthetic material imports. Gwangju-Honam region junior academy programs create concentrated replacement demand outside traditional retail seasons.
Germany
EU Green Deal alignment positions bio-based polyurethane midsoles and solvent-free adhesives for preferential retail placement in Munich and Frankfurt sustainability-focused pro shops. ECHA enforcement of REACH restrictions accelerates migration to bio-circular alternatives ahead of 2027 timelines. Bavarian distributors now require pre-submitted safety data sheets as standard procurement documentation.
Golf Shoes Market Key Industry Players
Global majors compete with regional champions across heritage positioning and athletic technology platforms, creating a tiered structure where century-old specialists face running-shoe giants. Incumbents leverage biomechanical engineering talent concentrated within established R&D departments, while new entrants struggle to match swing kinematics expertise. Three archetypes dominate: heritage cleated-performance specialists, athletic-platform extenders, and minimalist crossover purists. Competitive moves center on dedicated golf-specific production line contracts and direct-to-consumer fit technology deployment.
Among heritage specialists, FootJoy anchors the cleated-performance tier through century-long association with tour professionals. Adidas exemplifies the athletic-platform extender archetype, translating running-shoe cushioning science into spikeless course footwear. TRUE Linkswear occupies the minimalist crossover position, blurring boundaries between on-course performance and street-ready aesthetics. Each represents distinct engineering priorities rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Puma Golf |
| G/FORE |
| FootJoy |
| Payntr |
| TRUE Linkswear |
| Adidas |
| ECCO Golf |
| Skechers |
| Nike |
| Others |
Cost & Logistics Intelligence
California Proposition 65 chemical disclosure mandates for synthetic uppers are forcing brands to absorb transparency investment costs or risk coastal retail exclusion, compressing margin structures at entry-tier price points while premium players convert compliance spend into competitive differentiation.
Pricing Analysis
Warranty bundling separates premium positioning from stripped-down economy tiers, with Gore-Tex membrane guarantees and cleat replacement programs anchoring luxury price points. Three-tier pricing structure across premium, standard, and economy levels reflects material provenance and certification depth rather than manufacturing cost alone. Price differentiation hinges on Italian tannery sourcing and ASTM slip-resistance certification status. Cost compression in the budget tier is intensifying as mass retailers demand promotional depth, while professionals exhibit lowest price sensitivity due to tour-van service expectations.
Supply Chain Analysis
Dual-sourcing requirements from liability-conscious retailers are fragmenting production across Dongguan, Putian, and emerging Vietnamese clusters to mitigate single-factory exposure. Full-grain leather feeds from Italian and Portuguese tanneries, thermoplastic cleat receptacles from specialized molders, and waterproof membranes from licensed laminators. Tariff exposure on Chinese-assembled finished goods creates margin vulnerability for mid-tier brands without captive factory relationships. Distribution runs through PGA Tour Superstore and Golf Galaxy concentration in destination markets, with independent pro shops retaining custom-fitting niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
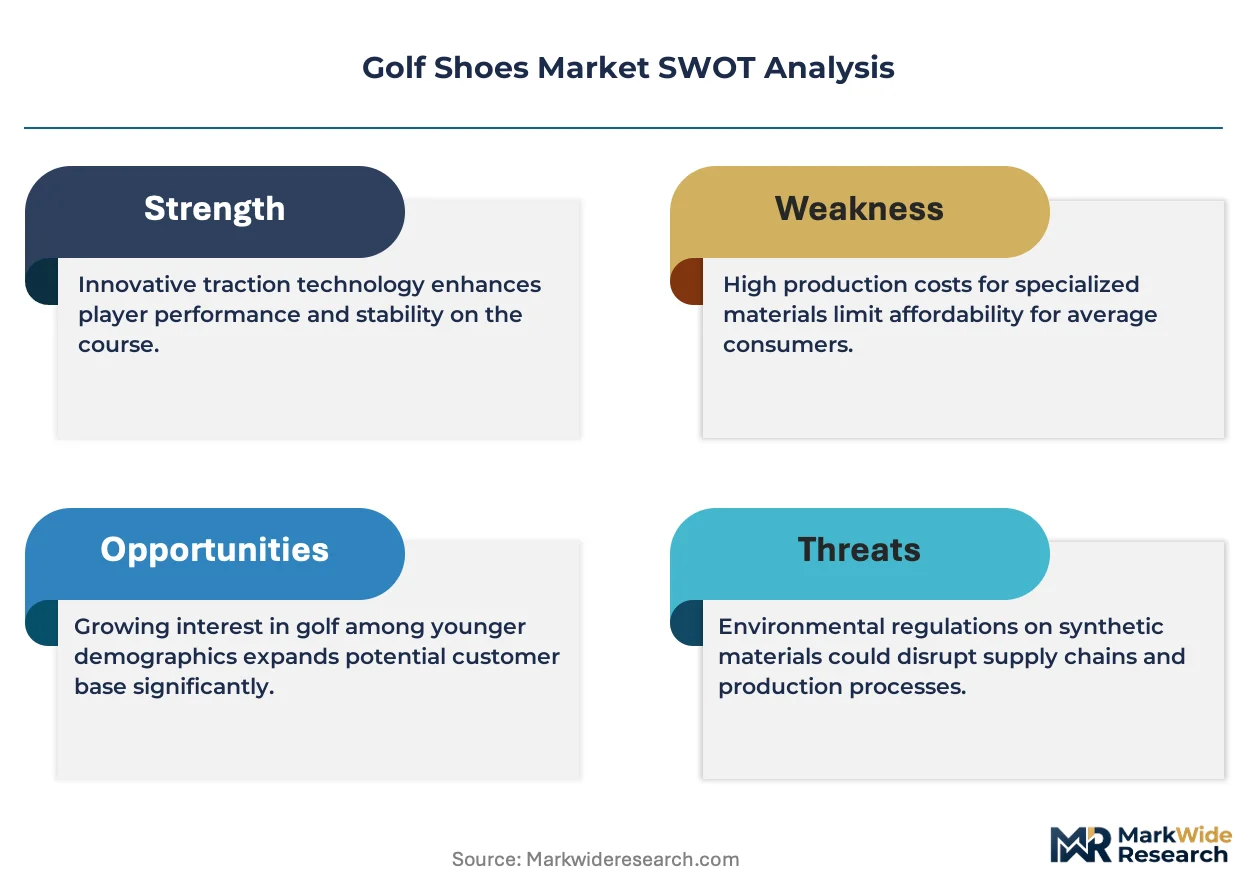
This market reads as a cost-of-compliance story where REACH SVHC expansion and California Proposition 65 enforcement erect regulatory moats that favor incumbents with dedicated legal and sourcing infrastructure.
For Market Incumbents: Cement dominance through captive factory relationships in Vietnamese manufacturing clusters developing golf-specific knitting capacity. Deepen backward integration into waterproof membrane lamination to control input costs as eVent and Gore-Tex licensing fees escalate. Defend against minimalist crossover entrants by accelerating spikeless platform R&D velocity.
For New Entrants and Emerging Players: Enter via direct-to-consumer fit technology deployment targeting female and junior segments where specialty retail service gaps persist. White-space concentrates in India course development zones near Delhi and Bangalore where performance footwear demand outpaces brand presence. Lead with AI-driven last recommendations and 3D scanning to reduce return rates without wholesale channel investment.
For Investors and Strategic Acquirers: The window for entry favors heritage brands with tour-player association and established biomechanical engineering talent. Long-term viability hinges on sustainability certification depth ahead of EU Green Deal restriction timelines. Watch for cleat receptacle lifespan improvements as the signal that replacement cycle compression is reversing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Fit Technology Launch | AI-driven last recommendations capture margin previously allocated to Golf Galaxy and PGA Tour Superstore. |
| Sustainability Certification Investment | Bio-based polyurethane midsoles secure preferential placement in German pro shops under EU Green Deal alignment. |
| Vietnamese Manufacturing Footprint Expansion | Specialized knitting capacity in Vietnam reduces Dongguan concentration risk for mesh upper production. |
| Waterproof Membrane Backward Integration | In-house lamination of eVent and Gore-Tex alternatives controls cost escalation in temperate climate positioning. |
| Female-Specific Pro Shop Merchandising Partnership | Tokyo and Osaka retail clusters expand addressable demand through anatomical last engineering differentiation. |
Research Approach
Document review covered customs records, SEC footwear segment filings, and ASTM International test method publications, complemented by interviews with brand product development directors, Italian tannery procurement managers, and PGA Tour Superstore category buyers. Secondary validation drew from retail audit data, course development permits in Texas and Florida, and REACH SVHC candidate list regulatory filings. Bottom-up unit demand modeling triangulated against top-down category spend estimates.
Segmented outputs across spiked, spikeless, retro, and lightweight product types, leather, synthetic, mesh, and rubber materials, and men, women, juniors, and professionals end users were generated across the analysis window. CAGRs were derived from regression against participation rate projections and equipment replacement cycle assumptions. Forecast inputs incorporated municipal course expansion permits, thermoplastic cleat receptacle lifespan data, and waterproof membrane adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under leather input volatility from cattle supply cycles and tanning capacity constraints. Deviation in Chinese production concentration policy or REACH restriction acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Knee Pads Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Ladderball Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Alpine Ski Equipment Market