
 Rowing Boats Market | 2026-2036
Rowing Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Rowing Boats Market Intelligence
The growing preference of recreational enthusiasts over a sole focus on competitive rowers is redrawing the market's demand profile. Empacher sustains its leadership in the elite racing segment through precision German engineering and a focus on Olympic-class boats. In contrast, Hudson Boat Works positions its products to serve both high-performance collegiate programs in Canada and the United States and dedicated club rowers globally.
Rowing boats are watercraft propelled by the muscular force of rowers using oars, designed with narrow, hydrodynamically efficient hulls to minimize drag. Construction often involves advanced composite materials like carbon fiber pre-pregs cured in autoclaves to achieve high stiffness-to-weight ratios. While Coxed Eights represent the pinnacle of team competition, Single Sculls and Double Sculls constitute the core volume for individual athletes. Carbon Fiber material options command premium pricing, while fiberglass serves the broader sports academies and training markets.
Equipment standards set by World Rowing for international competitions directly influence high-performance boat design and material specifications. Concurrently, manufacturers must adhere to broader maritime safety regulations, such as ISO 12217 for stability, and specific US Coast Guard requirements for recreational craft. The primary decision for boat builders now centers on integrating more sustainable materials and manufacturing processes without compromising on-water performance and durability.
Market Dynamics
The market's central dynamic is the divergence between the demands of elite competitive rowing and the expanding recreational segment. This creates a manufacturing tension between optimizing for hydrodynamic efficiency with advanced, costly materials and designing for durability, stability, and affordability for a broader user base in coastal and open-water environments.
Growth Catalysts
- Recreational Health Trends:The expansion of coastal and touring rowing as a fitness and leisure activity, particularly in countries with extensive coastlines like Australia, provides a significant new consumer base beyond traditional competitive clubs.
- Material Science Advancement:Innovations in carbon fiber composite manufacturing, including automated tape laying and out-of-autoclave curing, enable the production of lighter, stiffer, and more damage-tolerant hulls for high-performance applications.
- Olympic and Collegiate Sport Prestige:The continued prominence of rowing in events like the Olympic Games and major university regattas sustains demand for top-tier racing shells, driving innovation and upholding brand value in the elite segment.
Market Restraints
- High Equipment Cost:The premium pricing of racing shells, driven by the expense of carbon fiber pre-pregs and labor-intensive manufacturing processes, remains a significant barrier to entry for individuals and underfunded clubs.
- Specialized Manufacturing Requirements:Production of high-performance boats requires significant capital investment in large autoclaves, precision molds, and a highly skilled workforce trained in composite layup, limiting the number of capable manufacturers.
- Competition from Alternative Water Sports:For the recreational user, sports like kayaking, stand-up paddleboarding, and surf skiing offer lower-cost and more accessible alternatives, potentially limiting the growth of the non-competitive rowing segment.
Strategic Opportunities
- Sustainable Material Integration:Developing high-performance hulls using bio-based resins, natural fibers like flax, or recyclable thermoplastic composites presents a major opportunity to attract environmentally conscious consumers and comply with future regulations.
- Emerging Market Penetration:Targeting affluent coastal communities in regions like the Middle East and Southeast Asia, where water sports infrastructure is developing, can open new revenue streams for touring and recreational boat models.
- Digital Customization and Direct Sales:Implementing online direct-to-consumer platforms allows manufacturers to engage directly with recreational buyers, offering customization options and capturing margin previously held by distributors or agents.
Industry Challenges
- Skilled Labor Scarcity:A persistent challenge is the shortage of technicians with expertise in advanced composite lamination, boat rigging, and hydrodynamic design, which can constrain production capacity and quality control.
- Dual-Standard Compliance Burden:Manufacturers face the complexity of designing boats that meet the stringent performance and weight specifications of World Rowing for competition while also adhering to separate maritime safety and stability standards like ISO 12217 for recreational sale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rowing Boats Market |
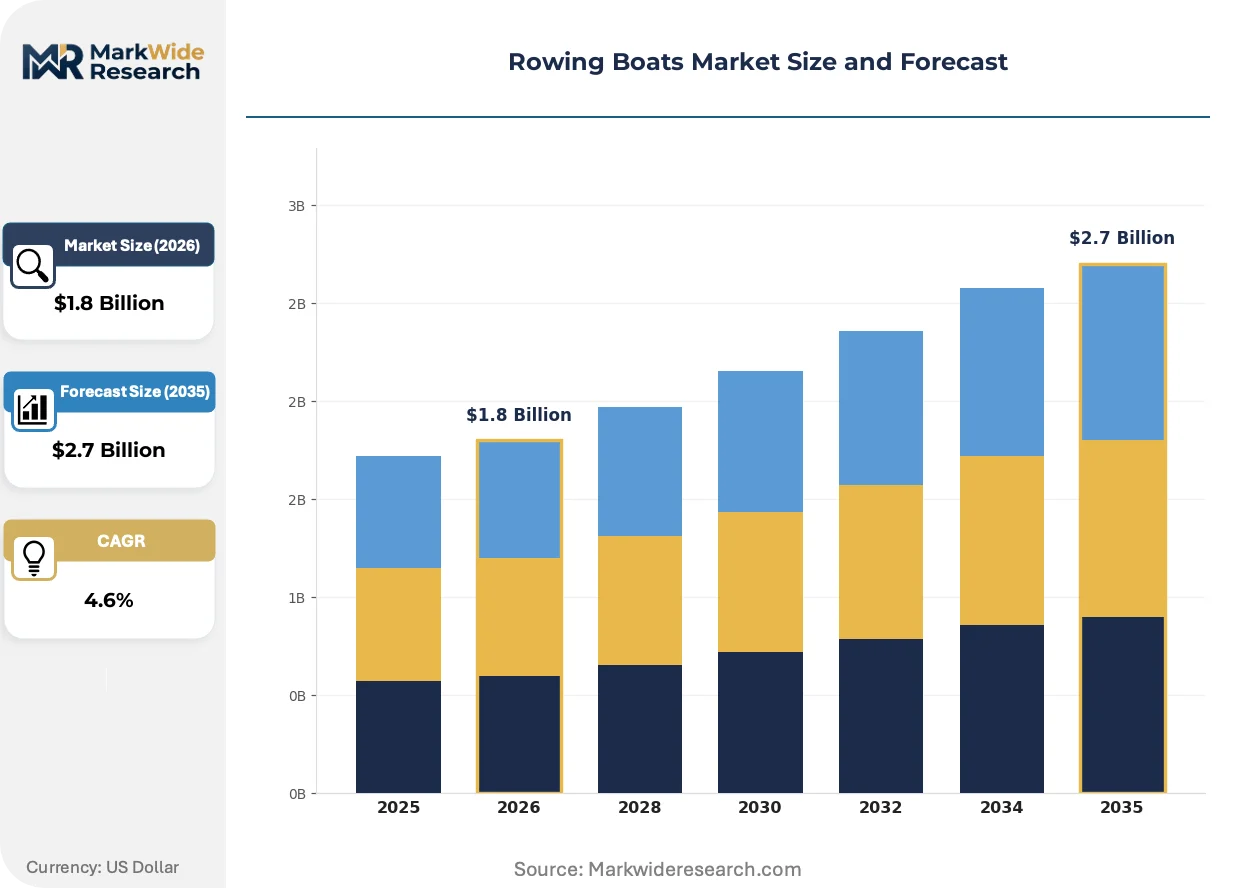
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Single Sculls, Double Sculls, Coxless Fours, Coxed Eights, Coastal Rowboats Material: Fiberglass, Carbon Fiber, Wood, Aluminum, Composite Materials End User: Competitive Rowers, Recreational Enthusiasts, Sports Academies, Fitness Centers, Rowing Clubs Distribution Channel: Specialty Retailers, Direct Manufacturer Sales, Online Platforms, Sports Equipment Dealers, Rental Services |
| Companies Covered | WinTech Racing, Swift Racing, Empacher, Stämpfli Racing Boats, Sykes, Filippi, Hudson Boat Works, Janousek, Concept2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rowing Boats Market Strategic Shifts & Innovations
The market is defined by a fundamental push-pull between material science advancements aimed at shaving seconds off race times and design adaptations catering to the durability and stability needs of the growing recreational user base. This dual evolution is forcing manufacturers to segment their engineering and production strategies more distinctly than ever before.
Advanced composite fabrication, particularly the use of autoclave-cured carbon fiber pre-pregs, delivers unparalleled stiffness-to-weight ratios for racing shells. Elite competitive teams and well-funded collegiate programs are the primary adopters of these technologies. This use of precision-engineered composites is supplanting traditional fiberglass and wood construction in every competitive category, establishing a new baseline for performance.
European sustainability mandates, including the EU Green Deal's emphasis on circularity, are influencing manufacturing choices. This regulatory pressure forces boat builders selling into the European Union to evaluate the lifecycle impact of their materials, from toxic resins to non-recyclable carbon fiber waste. Consequently, the most affected segment, small-to-mid-sized European builders, is actively researching bio-composites and thermoplastic alternatives.
A clear behavioral shift is the rise of individual purchasing for personal fitness and adventure, bypassing traditional club procurement channels. This trend disrupts the institutional sales model, compelling manufacturers to build direct-to-consumer capabilities, including e-commerce and logistics for oversized items. This direct purchasing pattern is most pronounced in the coastal and open-water rowing segments within the United Kingdom and Australia.
Rowing Boats Market Segmentation
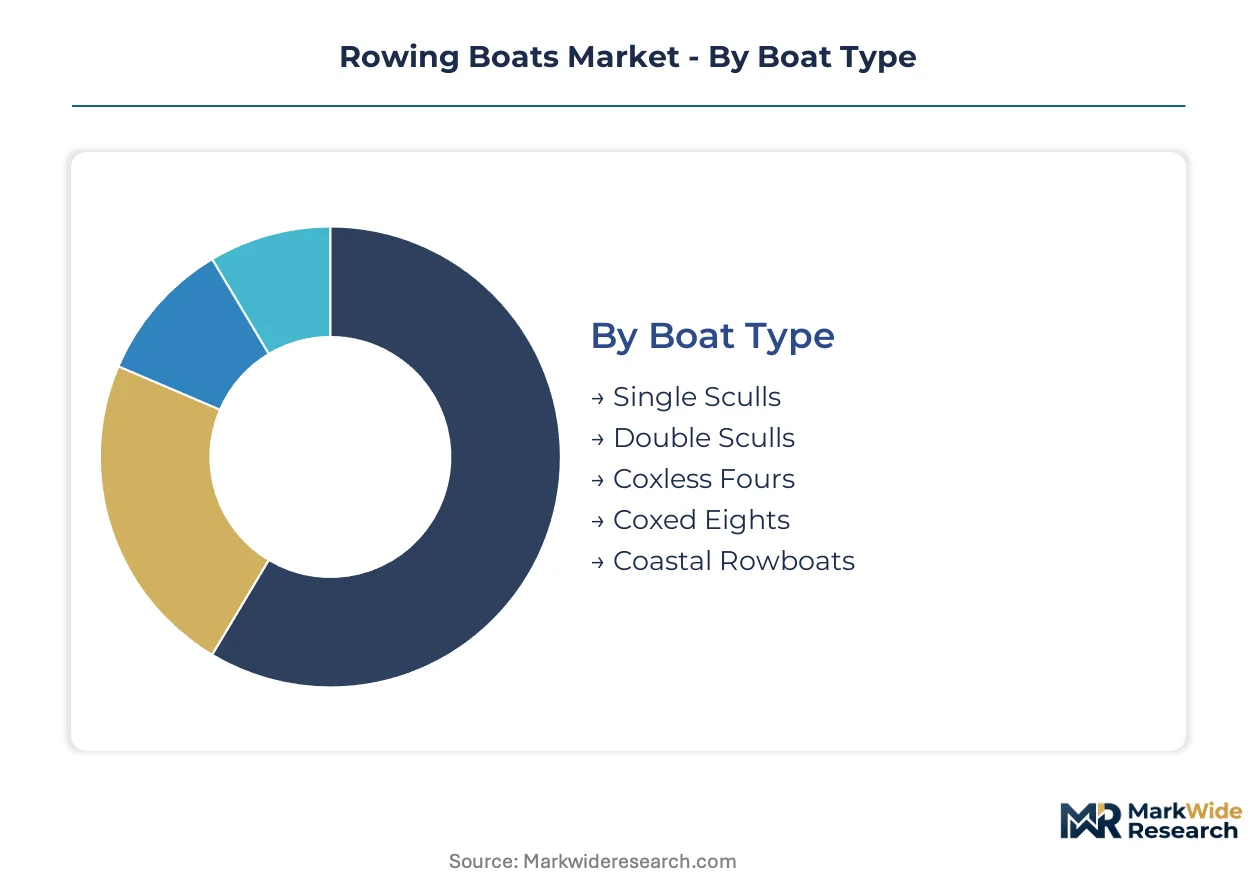
Market segmentation is critical for understanding the diverse needs shaping the rowing boats industry, from elite competitive performance to burgeoning recreational pursuits. This analysis delineates distinct user groups, material preferences, and distribution channels, enabling manufacturers to align product development and market strategies effectively.
Boat Type:
World Rowing specifications for competitive shells influence design, while maritime safety standards like ISO 12217 shape recreational boat construction.
- Coastal Rowboats:These robust and stable vessels are designed for open water and coastal environments. Demand from Australia and the United Kingdom drives innovation in stability and durability for diverse conditions.
- Coxed Eights:Representing the pinnacle of team competition, these long, narrow boats require precision engineering. Elite collegiate programs in Canada and the United States sustain demand for these high-performance, specialized vessels.
- Single Sculls:Individual racing shells designed for maximum hydrodynamic efficiency and minimal drag on flat water.
- Double Sculls:Two-person racing boats, popular in both competitive training and club-level regattas globally.
- Coxless Fours:Four-person racing boats without a coxswain, demanding synchronized power and technical skill from the crew.
Single Sculls handles the majority of throughput; Coastal Rowboats is the fastest mover on share.
Material:
Material choices directly correlate with boat performance and cost, creating distinct tiers for competitive and recreational markets.
- Carbon Fiber:Utilizes advanced pre-pregs cured in autoclaves to achieve exceptional stiffness-to-weight ratios. Elite racing segments and Olympic-class boats concentrate demand for this premium material.
- Fiberglass:Offers a balance of durability and affordability, making it a staple for sports academies and broader training markets. Its widespread use supports entry-level and club rowing.
- Wood:Traditional material primarily used for classic boats, bespoke constructions, or niche artisanal rowing craft.
- Aluminum:Favored for its robustness, lower cost, and minimal maintenance in utilitarian or smaller recreational craft.
- Composite Materials:Broad category encompassing various blends, often balancing performance with cost for specific applications beyond pure carbon fiber.
Pricing differentiation across these materials directly influences accessibility and market penetration.
End User:
End-user segments dictate design priorities, ranging from peak hydrodynamic performance to enhanced stability and comfort.
- Recreational Enthusiasts:Drive demand for stable, durable coastal and open-water boats suitable for leisure and fitness. This segment expands beyond traditional clubs in countries like Australia and the United Kingdom.
- Competitive Rowers:Focus on Olympic-class boats and elite racing shells that meet stringent World Rowing specifications. High-performance collegiate programs and national teams represent the core demand for these specialized craft.
- Sports Academies:Procure durable fiberglass boats for training, youth development programs, and interscholastic competitions.
- Fitness Centers:Offer rowing machines, with some potentially integrating on-water rowing programs for member engagement and cross-training.
- Rowing Clubs:Serve a mixed membership of competitive and recreational rowers, investing in a range of boat types to cater to diverse skill levels.
The shift in purchasing power towards individual recreational users is reshaping traditional sales channels.
Distribution Channel:
Distribution channels are evolving to meet the varied purchasing behaviors of institutional buyers and individual consumers.
- Direct Manufacturer Sales:Allows manufacturers to engage directly with high-performance collegiate programs and individual recreational buyers. This channel captures margin previously held by intermediaries.
- Online Platforms:Facilitate direct-to-consumer sales for smaller boats, accessories, and customization options. This channel is particularly appealing to individual purchasers in coastal rowing segments.
- Specialty Retailers:Provide expert advice, fitting services, and localized support for competitive and club rowers.
- Sports Equipment Dealers:Offer a broader range of water sports equipment, sometimes including entry-level rowing boats and accessories.
- Rental Services:Cater to tourists, casual users, and beginners, providing access to recreational rowing experiences without requiring boat ownership.
The market is witnessing a move towards more direct consumer engagement, bypassing traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Canadian manufacturers export high-performance rowing boats to collegiate programs in the United States. This trade flow supports elite competitive rowing demand. Meanwhile, recreational coastal rowing is expanding rapidly in Australia and the United Kingdom.
United Kingdom
Recreational health trends drive significant demand for coastal and touring rowing boats across the United Kingdom. Manufacturers must adhere to maritime safety regulations, such as ISO 12217, for recreational craft. Boating communities along the South Coast are seeing increased individual purchases and rental services for water sports.
Australia
Australia's extensive coastlines generate substantial demand for durable coastal and open-water rowing boats among recreational enthusiasts. Manufacturers selling into the country must comply with local maritime safety standards. Coastal regions around Sydney and Melbourne are experiencing a surge in individual purchasing for personal fitness activities.
United States
High-performance collegiate programs and dedicated club rowers sustain strong demand for top-tier racing shells across the United States. Builders must meet specific US Coast Guard requirements for recreational craft. Collegiate rowing hubs in the Northeast and Pacific Northwest drive significant innovation in elite boat design.
Canada
Collegiate programs and competitive club rowers in Canada create consistent demand for high-performance rowing boats. Manufacturers adhere to national maritime safety standards, including those aligned with ISO 12217. Rowing associations in Ontario and British Columbia are expanding their fleets to accommodate training and regattas.
Germany
Germany's market is characterized by strong demand for elite racing shells, driven by precision engineering and Olympic-class boat production. Manufacturers navigate the EU Green Deal's emphasis on circularity and CE marking requirements. Specialized boat-building centers in Northern Germany focus on advanced composite fabrication for competitive craft.
Rowing Boats Market Key Industry Players
Listed leaders compete with private specialists across performance tiers and end-user segments. The market structure exhibits a dual focus, with some manufacturers targeting elite competitive rowing and others catering to the expanding recreational user base. Strategic archetypes include high-performance composite fabricators, durable recreational boat builders, and niche artisanal producers. Companies often pursue capacity expansion in advanced composite manufacturing or form strategic partnerships to broaden distribution.
Within the elite racing segment, Empacher, a German-based manufacturer, exemplifies precision engineering for Olympic-class boats. Hudson Boat Works, a Canadian firm, occupies a position serving both high-performance collegiate programs and dedicated club rowers globally. WinTech Racing, with its international presence, anchors the competitive training market by offering a range of shells for various skill levels. These manufacturers represent distinct approaches to material use and market penetration, from ultra-premium carbon fiber for peak performance to more accessible composite options for broader club and academy use. Their offerings collectively address the varied demands of competitive and advanced recreational rowers.
| Leading Market Players |
|---|
| WinTech Racing |
| Swift Racing |
| Empacher |
| Stämpfli Racing Boats |
| Sykes |
| Filippi |
| Hudson Boat Works |
| Janousek |
| Concept2 |
| Others |
Cost & Logistics Intelligence
Long lead times for specialized carbon fiber components directly influence the pricing power of elite racing shell manufacturers, reflecting the concentrated supply chain for advanced materials.
Pricing Analysis
The significant technology-generation pricing gap exists between advanced carbon fiber hulls and more traditional fiberglass constructions, reflecting material and manufacturing cost differences. Per-unit transactional pricing dominates, with carbon fiber options commanding premium pricing due to exceptional stiffness-to-weight ratios and precision engineering. Pricing pressure stems from the affordability demands of the recreational segment and competition from alternative water sports. Sports academies and entry-level clubs represent the most price-sensitive buyers, while high-performance collegiate programs prioritize performance over cost.
Supply Chain Analysis
Germany and Canada anchor the production of high-performance rowing boats, supplying elite racing shells globally. The supply chain relies on specialized inputs like carbon fiber pre-pregs and advanced resins, primarily sourced from a limited number of composite material manufacturers. Skilled labor scarcity for composite lamination represents a structural risk, constraining production capacity. Distribution runs through direct manufacturer sales for high-performance collegiate programs and individual recreational buyers, supplemented by specialty retailers for broader club and training markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rowing Boats Market is experiencing a platform-economics inflection, driven by the shift towards direct-to-consumer online platforms that enable customization and broader market access.
For Market Incumbents: Shield established market share by investing in sustainable material R&D, addressing European sustainability mandates and attracting environmentally conscious consumers. Deepen vertical integration into advanced composite manufacturing to control quality and mitigate supply chain risks from skilled labor scarcity. Empacher and Hudson Boat Works can leverage brand prestige to counter the threat from lower-cost recreational alternatives. Expand direct-to-consumer capabilities to capture individual recreational purchasing power more effectively.
For New Entrants and Emerging Players: ISO 12217 certification fast-track provides a pathway for new entrants to validate stability and safety for recreational craft, particularly in the United Kingdom and Australia. Target the rapidly expanding coastal rowing segment with durable, stable, and affordable designs for leisure and fitness enthusiasts. Focus on bio-composite materials to attract environmentally conscious consumers, offering a clear differentiation from traditional carbon fiber. Implement online direct-to-consumer sales to reach individual buyers efficiently.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the high-performance racing shell segment due to advanced composite manufacturing requirements. The long-term viability of the market over a five-to-ten-year window hinges on balancing elite performance innovation with recreational accessibility. Seek acquisition targets that possess proprietary sustainable material technologies or established direct-to-consumer channels. The signal to watch is the adoption rate of bio-composites in mainstream recreational models.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Composite Hulls | Attracts environmentally conscious consumers and aligns with EU Green Deal mandates for European manufacturers. |
| Expand Direct-to-Consumer E-commerce | Captures individual recreational purchasing power, bypassing traditional club procurement channels in the UK and Australia. |
| Invest in Automated Composite Layup | Improves manufacturing efficiency for carbon fiber components and addresses skilled labor scarcity for high-performance boats. |
| Form Partnerships with Rental Services | Broadens market access for recreational models and introduces rowing to new user bases in coastal regions. |
| Acquire Coastal Rowing Specialists | Expands product portfolio and market penetration within the growing recreational segment in Australia and the United Kingdom. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholders included high-performance collegiate program coaches, competitive club managers, recreational enthusiasts, and advanced composite material suppliers. Secondary data sources comprised World Rowing specifications, ISO 12217 standards, and US Coast Guard requirements. This approach ensured robust bottom-up and top-down triangulation.
Across the analysis window, the analytical framework integrated historical performance data with future projections. Segmentation dimensions modeled included boat type, material, end user, and distribution channel, alongside regional adoption patterns. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included recreational health trend expansion and material science advancement rates.
Decision-makers should treat outputs as directional under current material science and regulatory assumptions; material deviation would warrant model refresh. Forecasts acknowledge potential shifts in composite material costs or maritime safety regulations. Recalibration cycles align with material shifts in sustainability mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Backboard Market
Sports Equipment
Surfboard Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Knee Pads Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Sports Eyewear Market