
 Ladderball Market | 2026-2036
Ladderball Market Size, Share, and Industry Trends Forecast 2026-2036
Ladderball Market Analytics
Asset-light leasing models for event equipment is rewriting competitive entry barriers in the ladderball space. GoSports leverages direct-to-consumer channel control to sustain margin capture across premium portable sets. Franklin Sports anchors its position through broad retail distribution partnerships with mass-market sporting goods chains.
Ladderball is a target-toss game employing two upright ladder frames with three rungs and weighted bolas, typically constructed from PVC tubing, powder-coated steel, or finished hardwood with rope-and-ball projectiles measuring 16-18 inches in length; manufacturers engineer rung spacing and frame geometry to standardize scoring zones for competitive consistency. Portable PVC sets lead volume shipments due to low freight costs and rapid assembly, while heavy-duty steel variants command higher unit economics through durability claims targeting institutional buyers. Distribution through sporting goods shops captures enthusiast purchasers seeking tactile evaluation, whereas e-commerce segments expand fastest among families prioritizing convenience and comparative pricing.
ASTM International governs recreational product safety specifications, while the Consumer Product Safety Commission monitors lead content and small-part hazards in youth-oriented ladderball sets; state-level camp licensing boards in Texas, California, and New York increasingly mandate equipment certification for insured recreational programming. Stakeholders must track evolving material disclosure rules and camp procurement centralization to anticipate which product tiers and certification levels will define supplier viability.
Market Dynamics
ASTM International safety tightening is collapsing the informal supplier tier, forcing manufacturers to absorb certification costs or exit camp procurement channels entirely. This regulatory compression is redistributing margin toward certified producers while eroding price-competitive imports.
Growth Catalysts
- Camp infrastructure mandates:Texas, California, and New York licensing boards now require equipment certification for insured recreational programming, converting compliance into a demand gatekeeper.
- Direct-to-consumer channel maturation:E-commerce platforms enable tactile-equivalent return policies and video assembly demonstrations, reducing purchase friction for family buyers.
- ASTM F2373 recreational product standards:Updated material disclosure rules for youth-oriented sets are accelerating replacement cycles among liability-conscious institutions.
Market Restraints
- PVC resin cost volatility:Feedstock price swings compress margins on volume-leading portable sets where manufacturers lack pricing power.
- Freight cost concentration:Container shipping from Asian molding centers exposes distributors to rate spikes that erode landed cost advantages.
- Substitution by disc golf and cornhole:Lower equipment cost and established tournament infrastructure pull discretionary outdoor spending from ladderball trial purchases.
Strategic Opportunities
- Asset-light event leasing:Party rental and corporate event verticals represent unserved demand where per-use economics outperform ownership for occasional users.
- Steel-frame institutional tier:Parks departments and university recreation centers seek decade-scale durability claims that justify premium positioning against disposable PVC alternatives.
- Consumer Product Safety Commission youth safety mandates:Lead-content testing and small-part hazard rules create compliance moats that certified suppliers can leverage for private-label partnerships.
Industry Challenges
- Certification timeline compression:ASTM revision cycles now outpace product development calendars, forcing simultaneous engineering and documentation workflows.
- Multi-channel inventory fragmentation:Sporting goods retail, e-commerce, and direct institutional sales require incompatible packaging and fulfillment specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ladderball Market |
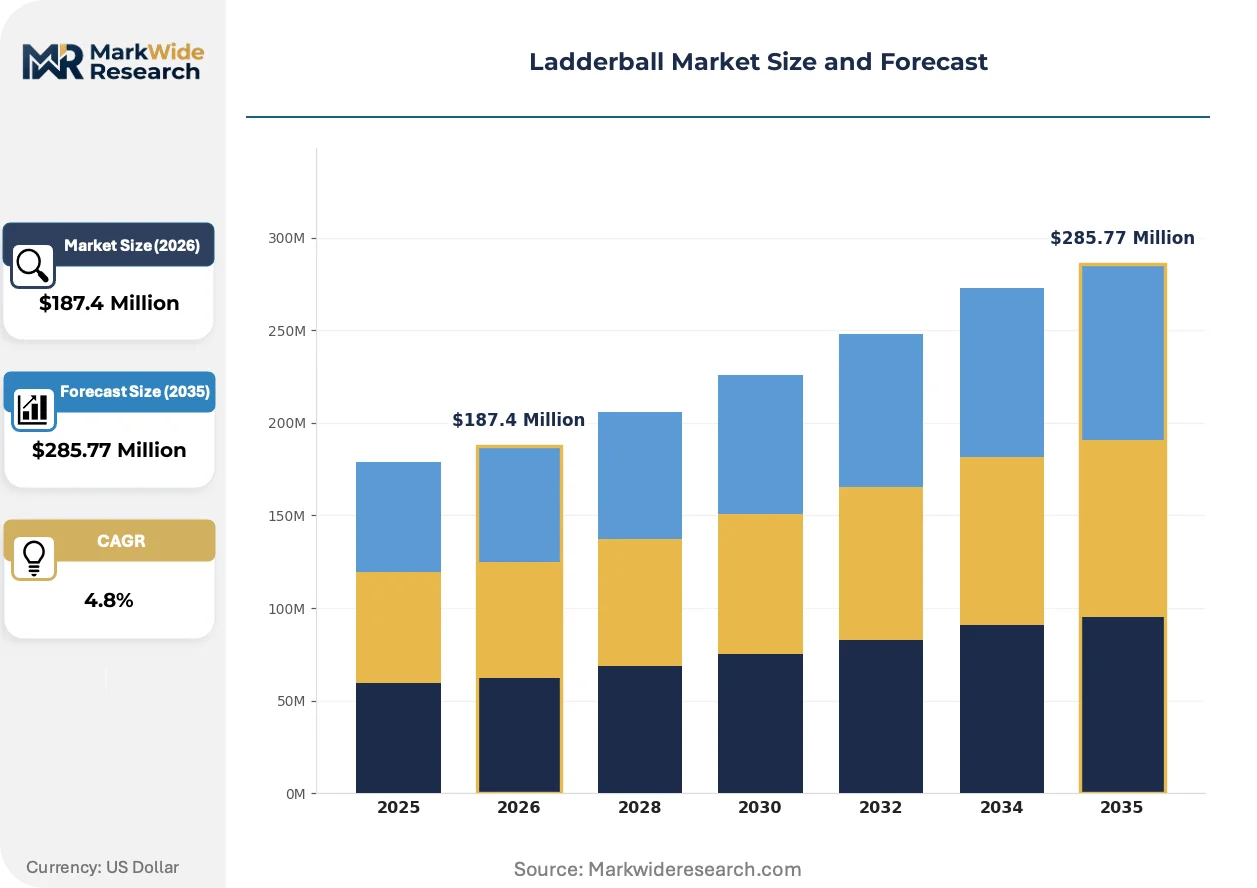
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden, Portable, Heavy-Duty, Economy Target Audience: Families, Schools, Camps, Recreational Leagues Distribution Channel: Retail Stores, E-commerce, Sporting Goods Shops, Outdoor Stores Performance Metric: Durability, Ease of Assembly, Weather Resistance, Aesthetic Appeal |
| Companies Covered | GoSports, Bolaball, Win SPORTS, Amazon Basics, Franklin Sports, Hathaway Games, Maranda Enterprises, Lifetime, Viva Sol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ladderball Market Evolving Landscape
Material substitution and channel disintermediation are converging to compress traditional supply chain tiers, while regulatory disclosure requirements are reshaping how manufacturers communicate product specifications to institutional buyers.
Modular quick-assembly PVC joint systems are collapsing the traditional seasonal sales window by enabling year-round indoor storage and rapid outdoor deployment. Family buyers in suburban United States markets are adopting these systems at accelerated rates, compressing the replacement cycle from five-year intervals to impulse-driven annual upgrades tied to social event planning.
ASTM International's updated recreational product safety specifications are mandating third-party structural load testing and material traceability documentation. Camp procurement officers now require batch-level compliance certificates, forcing manufacturers to integrate quality management systems that previously served only medical and aerospace verticals.
Recreational league formation is fragmenting demand across hyperlocal geographies while concentrating purchasing authority through centralized equipment coordinators. Tournament-standard steel sets are displacing casual PVC purchases in these channels, with league commissioners in Texas and California driving specification standardization that favors certified suppliers with documented durability testing.
Ladderball Market Segmentation
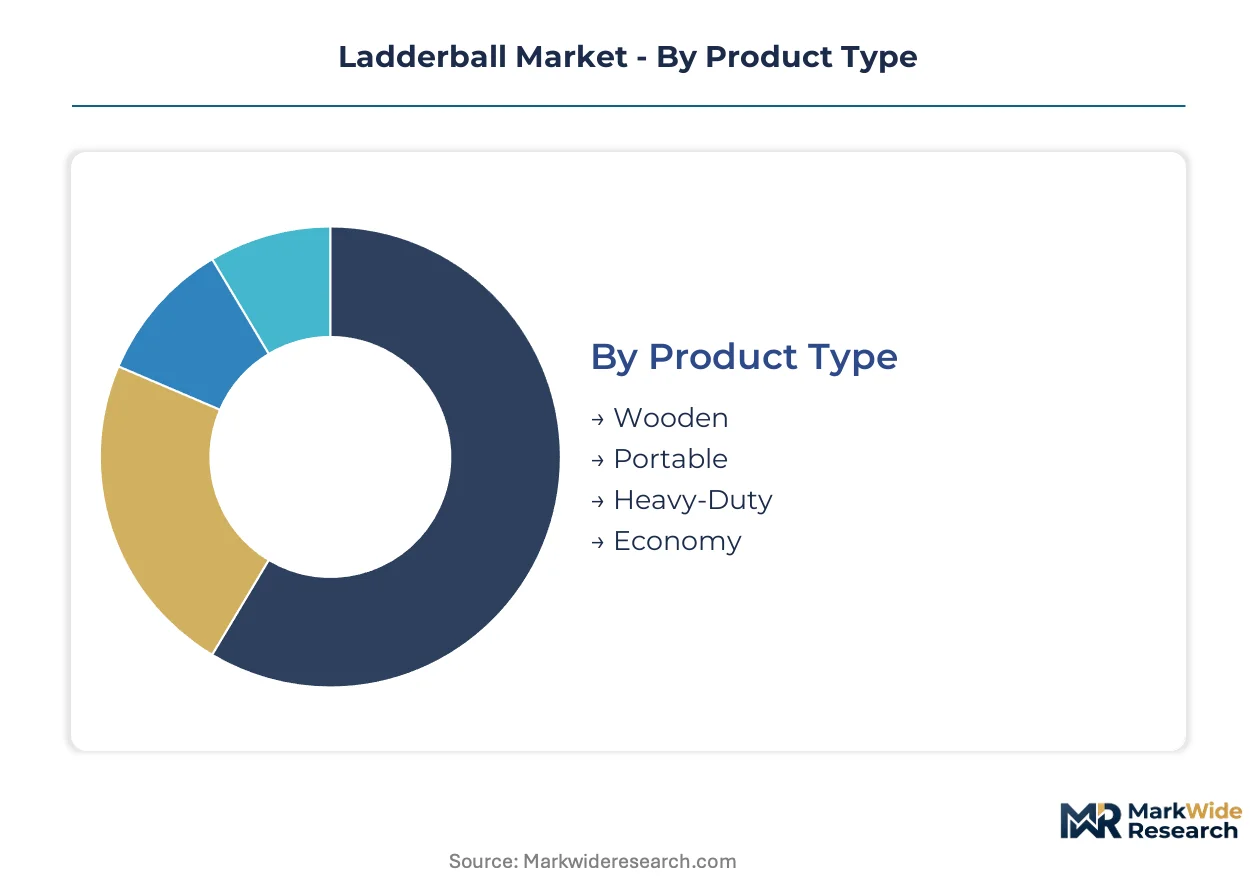
Segmentation in ladderball reveals how divergent use cases—from casual backyard gatherings to insured camp programming—create incompatible product requirements. Manufacturers must engineer for either portability and price or durability and certification, rarely both.
Product Type:
Mature PVC-based portable systems dominate unit economics, while emerging steel-frame variants capture institutional premium positioning.
- Portable:PVC tubing and quick-assembly joint systems minimize freight cube and enable impulse purchases through mass retail. Families in suburban United States markets favor these for seasonal storage and rapid deployment at social gatherings.
- Heavy-Duty:Powder-coated steel frames with welded joints withstand decade-scale outdoor exposure and satisfy ASTM structural load requirements. Texas and California camp licensing boards mandate this tier for insured recreational programming, concentrating procurement through certified suppliers.
- Wooden:Finished hardwood construction targets aesthetic-conscious backyard buyers seeking furniture-grade appearance. Limited weather resistance restricts deployment to covered patio environments.
- Economy:Thin-wall PVC and basic rope bolas serve single-season price-sensitive trial purchases. High replacement rates sustain volume but erode brand loyalty.
Portable handles the majority of throughput; Heavy-Duty is expanding most quickly on share.
Target Audience:
Cost tier separation runs deepest between liability-conscious institutions and discretionary household spenders.
- Camps:State-level licensing mandates in Texas, California, and New York require equipment certification and batch-level compliance documentation. Procurement centralization through regional equipment coordinators favors suppliers with integrated quality management systems.
- Families:Convenience-driven purchasing through e-commerce platforms with tactile-equivalent return policies dominates this segment. Video assembly demonstrations reduce purchase friction for first-time buyers.
- Recreational Leagues:Hyperlocal league formation fragments demand geographically while concentrating specification authority through tournament commissioners. Steel-frame standardization displaces casual PVC purchases as competitive play formalizes.
- Schools:District-level procurement cycles and storage constraints favor collapsible PVC sets for physical education inventory. Budget approval timelines extend replacement cycles beyond typical consumer patterns.
Families drive absolute volume; Camps deliver the steepest margin expansion trajectory.
Distribution Channel:
Volume concentrates through mass retail and digital channels, while margin capture favors tactile evaluation environments.
- E-commerce:Direct-to-consumer platforms enable comparative pricing and video content that substitutes for physical inspection. Return policy innovation reduces perceived purchase risk for family buyers prioritizing convenience.
- Sporting Goods Shops:Enthusiast purchasers seek hands-on frame stability assessment and bola weight evaluation. Staff expertise justifies price premiums unavailable through digital channels.
- Retail Stores:Mass-market seasonal displays capture impulse purchases during spring and summer merchandise resets. Limited shelf space compresses assortment to portable PVC variants.
- Outdoor Stores:Specialty camping and recreation retailers serve adventure-oriented buyers seeking ruggedized equipment specifications. Higher service levels sustain premium positioning against mass-market alternatives.
E-commerce handles the majority of throughput; Sporting Goods Shops deliver superior unit economics.
Performance Metric:
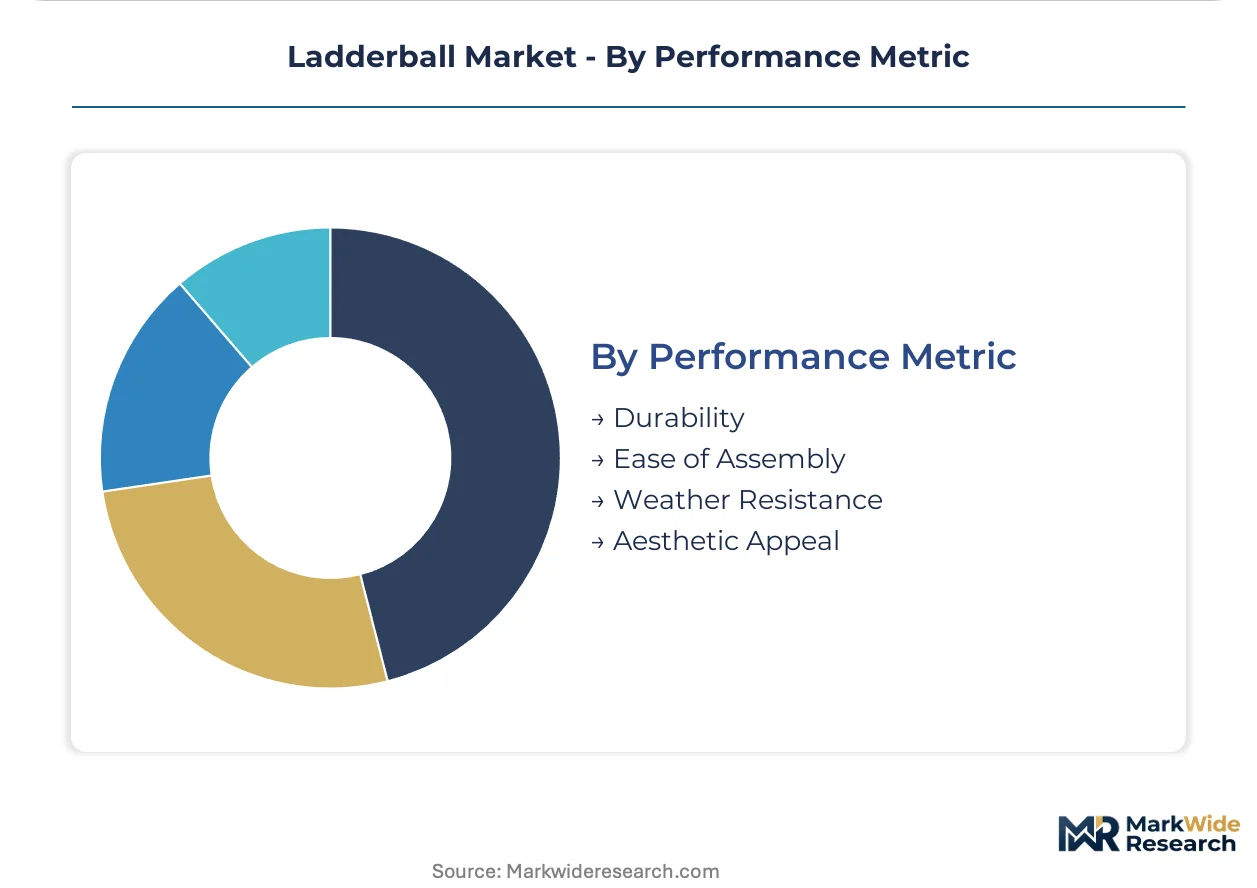
Customer type dictates which performance dimension dominates purchase decisions, creating product architecture trade-offs.
- Durability:Steel-frame construction and corrosion-resistant finishes satisfy decade-scale service life requirements for parks departments and university recreation centers. Load testing documentation supports institutional procurement compliance.
- Ease of Assembly:Tool-free joint systems and color-coded components enable rapid deployment by casual users without mechanical aptitude. Modular designs support indoor storage and seasonal rotation.
- Weather Resistance:UV-stabilized PVC and powder-coated steel finishes prevent degradation from prolonged outdoor exposure. Camp operators prioritize this dimension for reduced maintenance overhead.
- Aesthetic Appeal:Hardwood finishes and custom colorways serve backyard entertainment culture where visual integration with patio furniture influences selection. Limited functional differentiation shifts competition to design attributes.
Durability commands institutional priority; Ease of Assembly dominates consumer preference rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM International safety mandates and camp licensing requirements in key states are concentrating ladderball demand in North American markets where backyard entertainment culture and institutional procurement overlap. Regional variation reflects divergent enforcement timelines and recreational infrastructure investment patterns.
United States
Backyard entertainment culture in suburban Texas, California, and New York sustains consistent portable set purchases through mass retail and e-commerce channels. State-level camp licensing boards in these jurisdictions now mandate equipment certification for insured recreational programming, converting compliance into a procurement gatekeeper. Dallas-Fort Worth and Houston metropolitan clusters concentrate recreational league formation, with tournament commissioners driving steel-frame standardization that favors certified suppliers.
Canada
Summer camp infrastructure in Ontario and British Columbia generates institutional demand for weather-resistant equipment with documented durability testing. Health Canada monitors lead content and small-part hazards in youth-oriented recreational products, aligning enforcement with Consumer Product Safety Commission guidelines. Toronto-area sporting goods retailers serve enthusiast purchasers seeking hands-on frame stability assessment before acquisition.
Germany
Outdoor recreation associations in Bavaria and Baden-Württemberg promote standardized equipment specifications for club-level competitive play. CE marking requirements under EU recreational product directives govern material safety and structural load documentation for imported ladderball sets. Munich-based specialty retailers cater to aesthetic-conscious buyers seeking furniture-grade hardwood construction for integrated patio environments.
United Kingdom
Corporate event and party rental verticals in Greater London and Southeast England represent emerging demand for asset-light equipment leasing models. Trading Standards authorities enforce product safety regulations aligned with EU-derived frameworks for recreational equipment import and distribution. Birmingham manufacturing clusters produce powder-coated steel frames targeting institutional durability requirements.
Australia
Coastal camping and caravan park infrastructure in Queensland and New South Wales drives demand for rapid-assembly portable systems with UV-stabilized PVC construction. The Australian Competition and Consumer Commission monitors product safety standards for youth-oriented recreational equipment under mandatory reporting requirements. Sydney-based e-commerce platforms facilitate comparative pricing and video assembly demonstrations that reduce purchase friction for family buyers.
Ladderball Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures defined by distribution reach and certification depth. The vendor base spans direct-to-consumer platforms, mass-market retail partnerships, and institutional procurement channels with incompatible margin profiles. Three archetypes dominate: vertically integrated direct sellers, broad-line sporting goods conglomerates, and camp-specialist equipment fabricators. Competitive moves concentrate on backward integration into molding capacity and geographic expansion through regional equipment coordinator relationships.
Within the direct-to-consumer tier, GoSports exemplifies channel control through premium portable set positioning. Franklin Sports anchors mass-market presence through retail distribution partnerships with sporting goods chains. Hathaway Games occupies a position among specialty recreational equipment fabricators targeting enthusiast purchasers through tactile evaluation environments.
| Leading Market Players |
|---|
| GoSports |
| Bolaball |
| Win SPORTS |
| Amazon Basics |
| Franklin Sports |
| Hathaway Games |
| Maranda Enterprises |
| Lifetime |
| Viva Sol |
| Others |
Value Network & Pricing Analysis
Asian PVC molding clusters in Zhejiang and Guangdong provinces anchor upstream supply for portable ladderball sets, concentrating margin capture with distributors who control container allocation and camp certification channels in Texas and California.
Pricing Analysis
Certification level creates the primary spread between economy PVC sets and institutional steel-frame variants. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM compliance depth, freight absorption terms, and after-sales documentation bundles. Cost compression in portable PVC tiers is intensifying because resin feedstock volatility outpaces manufacturer pricing power. Families purchasing through e-commerce channels exhibit highest price sensitivity, whereas camp procurement officers prioritize batch-level compliance certificates over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for molded PVC components. Manufacturing concentrates in China, Vietnam, and domestic U.S. fabrication shops serving rush-order institutional buyers. Steel tubing and UV-stabilized PVC resin feed production, with rope-and-bola assemblies sourcing from Bangladesh textile clusters. Single-source vulnerability in container shipping from Ningbo and Shenzhen ports threatens landed cost predictability. Distribution runs through sporting goods retail, direct-to-consumer platforms, and regional equipment coordinator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hyperlocal recreational leagues and camp procurement centralization creates niche entry points for specialized suppliers who can bridge certification compliance with rapid fulfillment.
For Market Incumbents: Insulate margin pools by backward integration into PVC molding capacity in Vietnam to escape tariff exposure, while deepening ASTM documentation capabilities to capture camp procurement centralization in Texas and California. Disc golf and cornhole substitution threats demand defensive positioning through league sponsorship investments that lock in tournament-standard specifications.
For New Entrants and Emerging Players: Pursue asset-light event leasing models in corporate and party rental verticals where per-use economics outperform ownership for occasional users. Geographic white space concentrates in United Kingdom corporate event markets and Australian coastal camping infrastructure. Go-to-market traction requires video-centric digital platforms with tactile-equivalent return policies that reduce perceived purchase friction.
For Investors and Strategic Acquirers: Capital is best deployed toward camp-specialist fabricators with integrated quality management systems and documented ASTM compliance histories. Long-term viability over the coming decade hinges on regulatory moat depth rather than volume scale. Signal to monitor: state-level camp licensing mandate expansion beyond Texas, California, and New York into Florida and Illinois jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Investment | Batch-level compliance documentation unlocks camp procurement centralization in Texas and California. |
| Backward Integration into Molding | Captive PVC production in Vietnam insulates margin from tariff exposure and freight volatility. |
| Direct-to-Consumer Platform Launch | Video assembly demonstrations reduce purchase friction for family buyers prioritizing convenience. |
| Event Leasing Model Development | Per-use economics capture corporate and party rental verticals unserved by ownership models. |
| Steel-Frame Durability Repositioning | Decade-scale service claims satisfy parks departments and university recreation centers. |
Research Methodology
Initial hypotheses were tested against primary input from camp equipment procurement officers, recreational league commissioners, sporting goods retail buyers, and PVC molding plant managers, then refined through secondary validation. Primary fieldwork drew from ASTM committee participants, state licensing board administrators, and e-commerce platform category managers. Secondary sources encompassed customs trade records, SEC filings from sporting goods conglomerates, Consumer Product Safety Commission hazard databases, and camp industry association procurement surveys. Bottom-up shipment estimates from manufacturer channels were triangulated against top-down demand modeling from end-use segmentation.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, target audience archetype, distribution channel structure, and performance metric priority. CAGRs were derived from curve-fitting historical shipment trajectories against camp infrastructure investment cycles and recreational league formation patterns. Industry-specific forecast inputs incorporated PVC resin price elasticity coefficients and state-level licensing mandate diffusion timelines.
Sensitivities concentrate around ASTM revision cycle acceleration, container shipping rate spikes, and camp procurement budget contractions. Forecasts reflect assumptions regarding regulatory enforcement consistency and backyard entertainment culture persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Rowing Machine Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Quad Skate Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Premium Bicycle Market