
 Global Golf Training Aids Market | 2026-2036
Global Golf Training Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Golf Training Aids Market Analysis
The gap between premium sensor-integrated trainers and basic mechanical aids is recalibrating how manufacturers allocate engineering resources. Topgolf Callaway Brands leverages its entertainment venue network to embed trial opportunities for high-end systems. Acushnet Holdings Corp. anchors its position through Titleist-affiliated fitting protocols that mandate specific training tools. Mizuno USA, Inc. competes on forged-metal craftsmanship heritage translated into weighted swing trainers.
Golf training aids encompass physical devices and digital systems engineered to isolate, measure, or correct biomechanical elements of the golf swing, typically incorporating accelerometers, pressure sensors, or adjustable resistance mechanisms rated to specific torque tolerances. Their commercial purpose centers on accelerating motor-skill acquisition while providing quantifiable feedback loops that reduce instructor dependency. Swing trainers and ball flight monitors command the deepest margin pools due to sensor component costs and software subscription attach rates, while putting aids represent the most penetrated category among amateur players. Grip trainers show the fastest trajectory among junior development programs seeking foundational mechanics correction.
The US Consumer Product Safety Commission governs mechanical aid structural integrity, while the FCC regulates wireless transmission protocols in connected devices; ISO standards for sports equipment testing provide voluntary benchmarks that premium brands adopt for differentiation. The EU's REACH framework restricts certain polymer plasticizers, compelling reformulation of grip materials sold across member states. Stakeholders must monitor whether emerging AI-driven coaching algorithms trigger medical-device classification debates that would reshape compliance pathways.
Market Dynamics
Sensor-integrated training systems are fragmenting instruction authority away from certified professionals toward algorithm-driven self-coaching platforms, compressing the traditional golf instruction value chain while expanding addressable amateur participation.
Growth Catalysts
- EU Green Deal product sustainability mandates:Manufacturers reformulate polymer construction to meet recyclable material quotas, opening procurement pathways with municipal course systems across Germany, France, and the Netherlands.
- Amateur player density at municipal facilities:Swing analysis applications integrate with physical training tools, creating bundled purchase incentives for entry-level equipment at public-access venues in the United States.
- Pressure sensor miniaturization:Component cost curves for MEMS accelerometers enable sub-premium price tiers, expanding sensor-integrated trainer accessibility to junior development programs.
Market Restraints
- Semiconductor supply concentration:MEMS sensor fabrication concentrates in East Asian foundries, exposing manufacturers to single-source disruption risk for connected device production.
- REACH polymer plasticizer restrictions:ECHA-mandated reformulation of grip compounds raises R&D overhead for products distributed across EU member states.
- Simulator substitution threat:Indoor golf entertainment venues deploy full-swing simulation as training-adjacent experience, capturing practice-hour budgets that might otherwise flow to portable aids.
Strategic Opportunities
- India's emerging golf infrastructure:New course development in Delhi and Bangalore creates first-mover positioning for fitting-protocol training systems aligned with academy expansion.
- AI coaching algorithm integration:Convergence of computer vision and biomechanical modeling enables real-time swing correction without instructor presence, unlocking remote instruction markets.
- Subscription software attach rates:Cloud-based swing data analytics create recurring revenue streams that offset hardware margin compression in sensor-integrated categories.
Industry Challenges
- Biomechanical data interpretation skill gaps:Retail channel staff lack training to demonstrate sensor-integrated systems effectively, degrading conversion at point-of-sale.
- FCC wireless certification timelines:Connected device approval cycles delay product launches by four to six months, compressing seasonal selling windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Golf Training Aids Market |
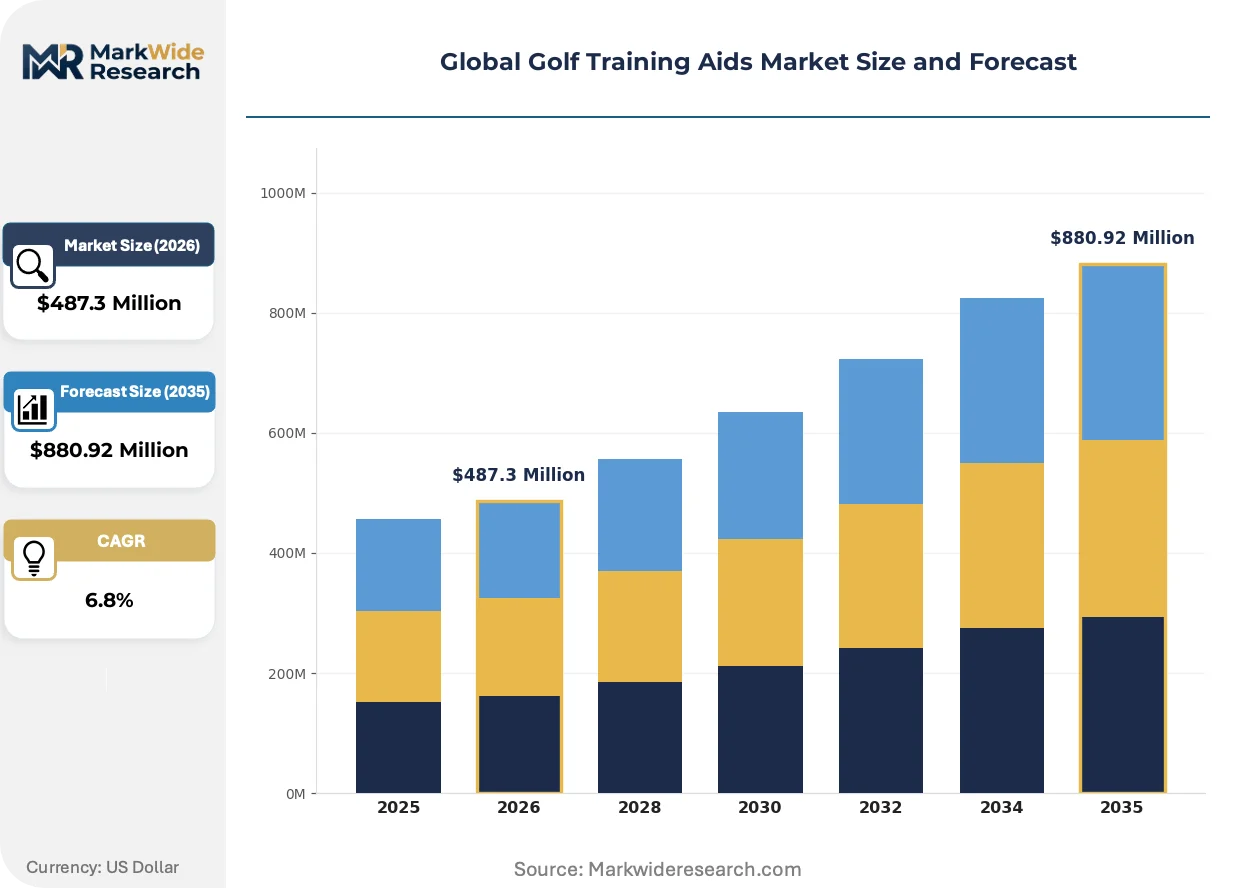
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swing Trainers, Putting Aids, Ball Flight Monitors, Grip Trainers Application: Skill Development, Performance Improvement, Coaching, Fitness End User: Amateur Players, Professional Players, Coaches, Golf Academies Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Outlets, Direct Sales |
| Companies Covered | Mizuno USA, Inc., EyeLine Golf, Topgolf Callaway Brands, Optishot Golf, Implus Footcare, LLC, Acushnet Holdings Corp., Saber Golf, GForce Golf, Honma Golf Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Golf Training Aids Market Emerging Trajectories
Portable launch monitor technology is compressing the performance gap between consumer-grade and professional-grade swing analysis, enabling self-directed practice protocols that bypass traditional instruction hierarchies.
Photometric and Doppler radar sensors packaged in smartphone-integrated form factors are decentralizing swing data capture from dedicated fitting bays to driving range stalls and home practice nets. Amateur players at municipal courses in the United States and United Kingdom are adopting these systems at replacement cycles of eighteen to twenty-four months. The shift is compressing demand for instructor-mediated feedback and expanding the addressable base of self-coaching equipment purchasers.
REACH framework restrictions on phthalate plasticizers are compelling grip material reformulation across products sold into EU member states. Manufacturers substituting bio-based polymer alternatives face eighteen-month validation timelines for torque tolerance certification. Weighted swing trainers with molded grips show the highest compliance friction, while wrapped-leather constructions bypass reformulation requirements entirely.
Academy chains in the United States are consolidating procurement around branded aid systems that standardize curriculum delivery across multi-location networks. Independent instructors and smaller regional academies face displacement as these chains negotiate exclusive supply arrangements. The concentration is most visible in Arizona, Florida, and Texas, where climate permits year-round outdoor instruction and academy density supports volume purchasing agreements.
Global Golf Training Aids Market Segmentation
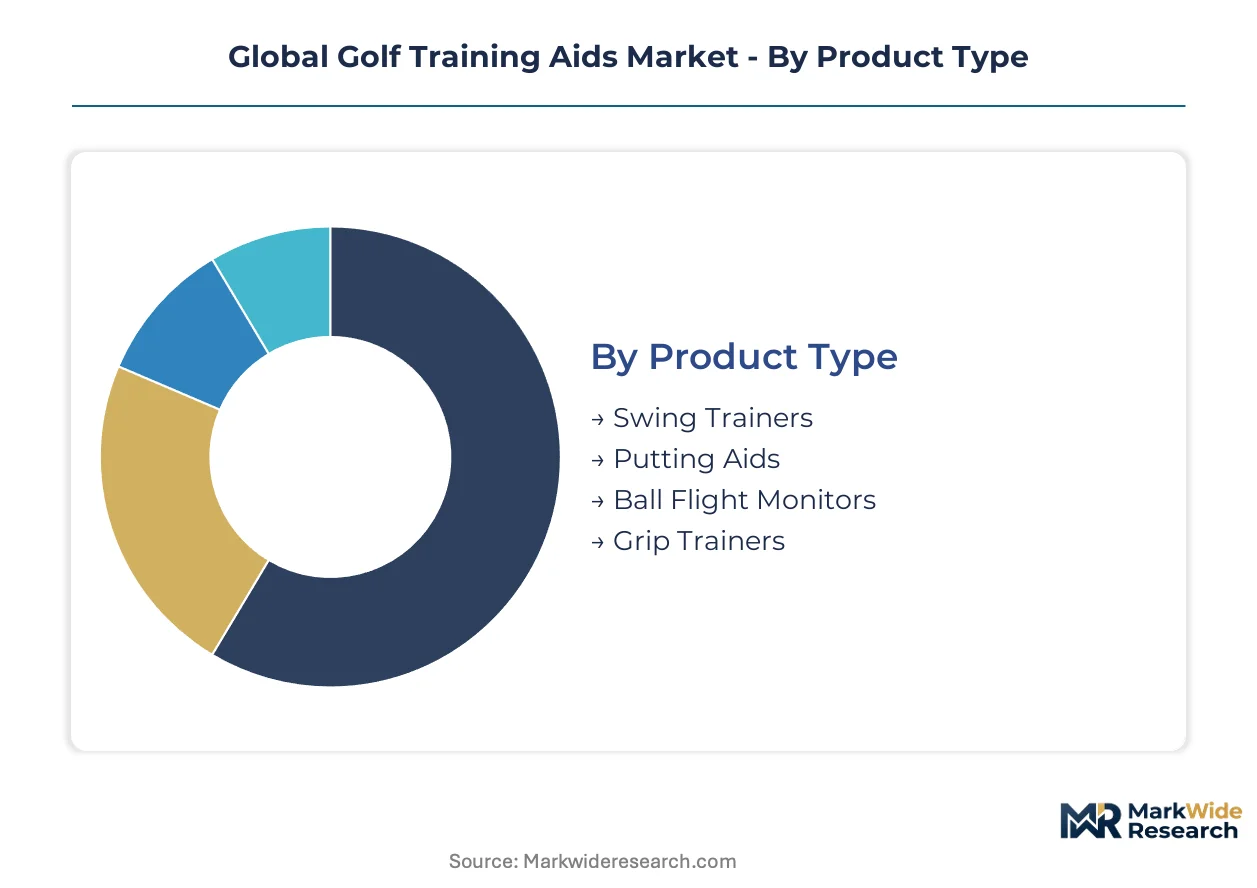
Golf training aids fragment across four distinct taxonomies that determine engineering specifications, margin profiles, and channel economics. Product type governs sensor component density and software attach rates. Application scope defines whether buyers seek diagnostic precision or motor-skill repetition. End-user segmentation separates volume-driven amateur purchases from specification-intensive professional procurement. Distribution channel selection shapes trial accessibility and post-sale support intensity.
Product Type:
Buyers in this category differentiate primarily by sensor integration depth and torque tolerance requirements rather than raw price point alone.
- Swing Trainers:Mechanical and sensor-integrated devices engineered to isolate swing plane, tempo, and release mechanics through adjustable resistance mechanisms rated to specific torque tolerances. Demand concentrates in the United States, where golf academy chains standardize curriculum around branded aid systems that mandate repeatable swing mechanics protocols. FCC wireless certification timelines for connected variants compress seasonal selling windows by four to six months.
- Ball Flight Monitors:Photometric and Doppler radar systems capturing launch angle, spin rate, and carry distance with professional-grade accuracy. Amateur players at municipal courses in the United Kingdom and United States are adopting smartphone-integrated form factors at eighteen to twenty-four month replacement cycles, bypassing traditional fitting bay hierarchies. MEMS sensor fabrication concentration in East Asian foundries exposes manufacturers to single-source disruption risk.
- Putting Aids:Alignment guides, stroke arc trainers, and green-reading tools emphasizing repetitive motor pattern reinforcement without electronic components. Municipal course pro shops in Germany and the Netherlands stock these as entry-level impulse purchases aligned with EU Green Deal recyclable material mandates.
- Grip Trainers:Molded and wrapped constructions correcting hand positioning and pressure distribution through tactile feedback. Junior development programs in Arizona, Florida, and Texas show the steepest adoption trajectory as foundational mechanics correction takes priority over distance optimization.
Swing trainers lead volumes today; grip trainers are gaining share fastest.
Application:
Application scope determines whether procurement prioritizes diagnostic data depth or repetitive movement patterning without feedback loops.
- Skill Development:Foundational mechanics instruction targeting junior players and adult beginners seeking motor-skill acquisition pathways. Golf academies in India—specifically Delhi and Bangalore—are expanding procurement of fitting-protocol training systems as new course infrastructure creates first-mover positioning opportunities.
- Performance Improvement:Quantified feedback systems enabling self-directed handicap reduction through measurable swing parameter changes. Algorithm-driven platforms are fragmenting instruction authority away from certified professionals toward self-coaching protocols.
- Coaching:Instructor-mediated deployment where training aids function as curriculum standardization tools across multi-location academy networks. Independent instructors face displacement as chains negotiate exclusive supply arrangements in climate-favorable US states.
- Fitness:Weighted trainers and resistance devices addressing swing speed, flexibility, and injury prevention through biomechanical conditioning. Physical therapy clinics affiliated with municipal courses in France are expanding referral-based distribution.
Skill development commands the broadest installed base; performance improvement shows the steepest expansion trajectory.
End User:
End-user segmentation separates specification-intensive professional procurement from volume-driven amateur purchases with divergent replacement cycles.
- Amateur Players:Individual consumers practicing at municipal courses, driving ranges, and home practice nets. Swing analysis applications integrating with physical training tools are creating bundled purchase incentives at public-access venues across the United States.
- Professional Players:Tour professionals and elite amateurs requiring torque-tolerance certification and custom fitting protocols. Titleist-affiliated fitting mandates specific training tools, anchoring supplier relationships through specification lock-in.
- Coaches:Independent instructors and academy staff deploying aids as curriculum delivery mechanisms. Biomechanical data interpretation skill gaps among retail channel staff degrade conversion effectiveness at point-of-sale.
- Golf Academies:Multi-location instruction networks standardizing equipment procurement across geographic footprints. Consolidation around branded aid systems is most visible in Arizona, Florida, and Texas where year-round instruction supports volume purchasing agreements.
Amateur players dominate unit volumes; golf academies are consolidating procurement fastest.
Distribution Channel:
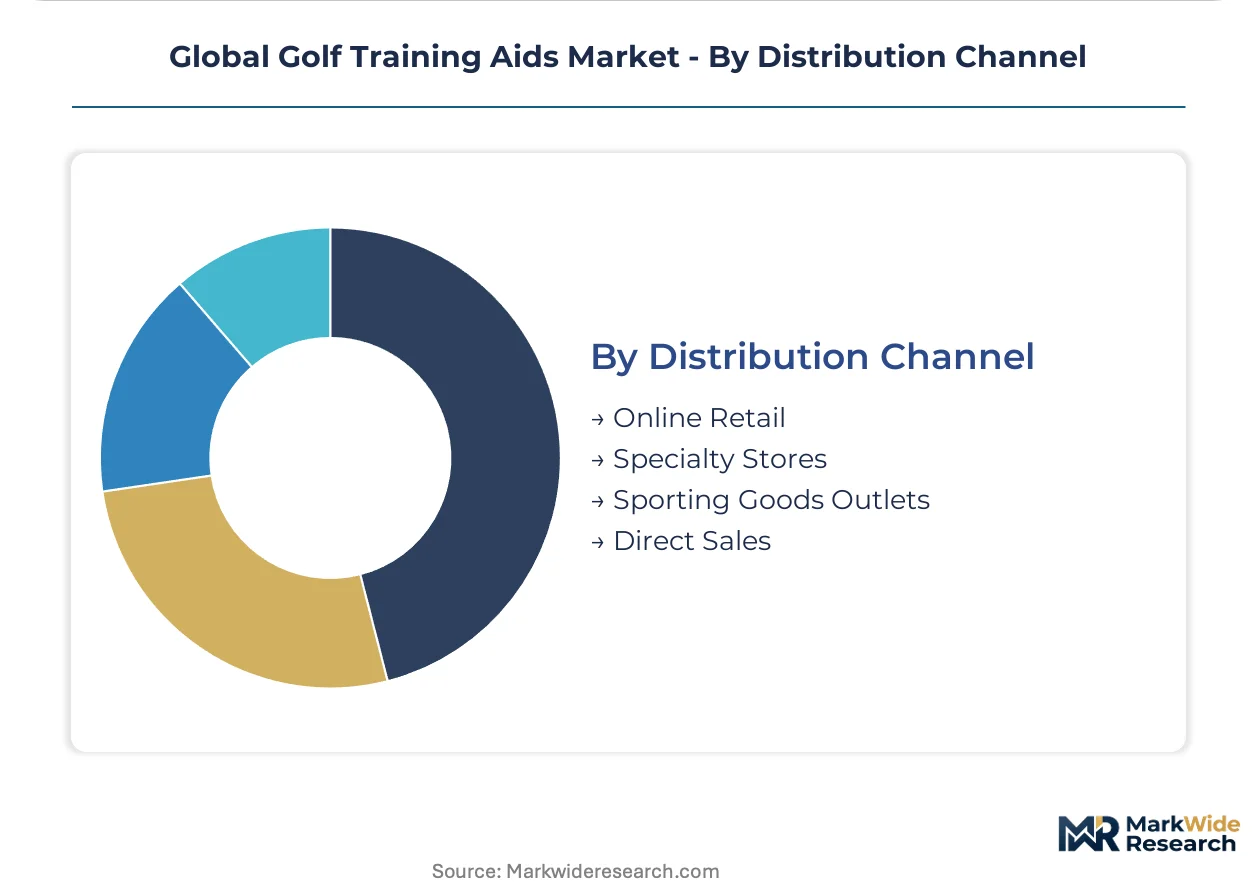
Channel selection governs trial accessibility, demonstration depth, and recurring software revenue attachment.
- Online Retail:E-commerce platforms enabling direct-to-consumer sensor-integrated system sales with subscription software attach rates. Cloud-based swing data analytics create recurring revenue streams that offset hardware margin compression.
- Specialty Stores:Dedicated golf retailers offering fitting bay demonstrations and instructor referral networks. Staff training gaps on sensor-integrated systems limit conversion effectiveness despite premium positioning.
- Sporting Goods Outlets:Mass-market retailers stocking entry-level mechanical aids for impulse purchase. REACH polymer plasticizer restrictions raise R&D overhead for grip materials distributed through this channel across EU member states.
- Direct Sales:Manufacturer-controlled fitting protocols and academy chain exclusive arrangements. Topgolf Callaway Brands leverages entertainment venue networks to embed trial opportunities for high-end systems outside traditional retail.
Specialty stores anchor premium system volumes; online retail is climbing fastest for sensor-integrated categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified golf instructors in the United States anchor the largest professional coaching workforce, while municipal course density in Germany and Japan creates parallel demand clusters for entry-level training systems.
United States
Golf academy chains in Arizona, Florida, and Texas consolidate procurement around branded aid systems that standardize curriculum delivery across multi-location networks. The FCC regulates wireless transmission protocols in connected training devices, extending product launch timelines by four to six months. Swing analysis applications integrating with physical training tools create bundled purchase incentives at municipal courses in California and the Southeast.
Germany
Municipal course pro shops in Bavaria and North Rhine-Westphalia stock putting aids as entry-level impulse purchases aligned with EU Green Deal recyclable material mandates. The ECHA REACH framework restricts phthalate plasticizers in grip compounds, compelling eighteen-month validation timelines for torque tolerance certification. Physical therapy clinics affiliated with Frankfurt and Munich municipal facilities expand referral-based distribution of weighted fitness trainers.
United Kingdom
Amateur players at municipal courses adopt smartphone-integrated ball flight monitors at eighteen to twenty-four month replacement cycles, bypassing traditional fitting bay hierarchies. ISO standards for sports equipment testing provide voluntary benchmarks that premium brands adopt for differentiation in London and Southeast retail channels. Edinburgh and Glasgow academy networks negotiate volume purchasing agreements for sensor-integrated systems.
Japan
Junior development programs in Tokyo and Osaka prefectures prioritize foundational mechanics correction through grip trainers over distance optimization tools. METI industrial standards influence domestic manufacturing specifications for forged-metal weighted swing trainers. Nagoya-area fitting centers mandate torque-tolerance certification for professional-grade equipment distributed to elite amateur circuits.
India
New course development in Delhi and Bangalore creates first-mover positioning for fitting-protocol training systems aligned with academy expansion. BIS certification requirements for imported sports equipment extend market entry timelines for sensor-integrated categories. Hyderabad and Chennai municipal facilities drive adoption of entry-level mechanical aids among first-generation golfers.
Global Golf Training Aids Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the golf training aids sector, with sensor-integrated systems requiring semiconductor fabrication partnerships while mechanical aid specialists maintain in-house molding capabilities. The vendor base separates into three tiers: entertainment-venue operators with embedded trial networks, heritage equipment manufacturers leveraging fitting protocol lock-in, and specialty designers focused on single-swing-mechanic isolation. Consolidation pressure concentrates among academy-chain procurement departments, while independent instructors face displacement from standardized curriculum mandates. Dominant competitive moves include exclusive supply arrangements with multi-location instruction networks and backward integration into MEMS sensor sourcing.
Within the heritage manufacturer tier, Acushnet Holdings Corp. and Honma Golf Co., Ltd. exemplify specification-intensive positioning through affiliated fitting mandates and forged-metal craftsmanship lineage. Topgolf Callaway Brands occupies a position bridging entertainment-venue distribution with premium system trial accessibility. Mizuno USA, Inc. anchors the weighted trainer segment through torque-tolerance engineering protocols translated from club manufacturing heritage.
| Leading Market Players |
|---|
| Mizuno USA, Inc. |
| EyeLine Golf |
| Topgolf Callaway Brands |
| Optishot Golf |
| Implus Footcare, LLC |
| Acushnet Holdings Corp. |
| Saber Golf |
| GForce Golf |
| Honma Golf Co., Ltd |
| Others |
Supply Flow & Price Mechanics
MEMS sensor engineering talent concentration in Taiwan and South Korea generates labor-cost differentials that widen pricing-tier spreads between sensor-integrated swing trainers and basic mechanical aids. Foundry proximity to design centers compresses R&D overhead for premium tiers while offshore molding operations in Vietnam sustain economy-tier mechanical aid margins.
Pricing Analysis
Bundled hardware-subscription splits versus unbundled transactional sales define the dominant pricing structure across sensor-integrated categories. Three-tier pricing structure across premium, standard, and economy levels separates torque-certified professional systems from municipal-course entry aids. Price differentiation rests on FCC wireless certification status and ISO sports-equipment testing tier. Cost compression in MEMS component sourcing is intensifying because East Asian foundry competition accelerates sensor price erosion. Amateur players at municipal facilities exhibit highest price sensitivity; golf academy chains demonstrate lowest sensitivity due to volume procurement agreements.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and domestic-content thresholds are reshaping sourcing patterns for assembly operations serving South Asian markets. MEMS sensor fabrication concentrates in Taiwan, South Korea, and Japan; polymer resin compounding for grip materials draws from Germany, the Netherlands, and China. Raw material dependencies span lithium for portable power systems, rare-earth elements for precision motors, and bio-based polymer alternatives for EU REACH compliance. Single-source vulnerability in East Asian foundry networks exposes connected-device production to geopolitical disruption. Distribution runs through academy-chain direct procurement, specialty retail fitting bays, and online direct-to-consumer platforms with software attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH polymer reformulation costs in Germany and France run 40% above Southeast Asian manufacturing baselines, creating arbitrage incentives for regional production footprints that bypass ECHA-mandated validation timelines.
For Market Incumbents: Extend sensor-integrated system roadmaps into AI coaching algorithm integration to defend against simulator-substitution threats from indoor entertainment venues. Deepen backward integration into MEMS sensor sourcing to reduce single-foundry exposure. Lock academy-chain procurement through exclusive curriculum-standardization agreements in Arizona, Florida, and Texas climate corridors. For New Entrants and Emerging Players: Independent instructors displaced by branded academy consolidation represent an underserved buyer archetype requiring portable, instructor-mediated diagnostic tools without chain-mandated system lock-in. White-space targets include junior development programs in India seeking foundational mechanics correction and physical therapy clinics at French municipal courses prescribing fitness-oriented weighted trainers. A direct-to-instructor go-to-market angle bypasses retail channel biomechanical-data skill gaps. For Investors and Strategic Acquirers: Entertainment-venue operators are the most active acquirer in this space, seeking embedded trial networks that bypass traditional retail conversion friction. Long-term viability hinges on recurring software revenue attachment rates offsetting hardware margin compression. Acquisition target archetypes include specialty designers with single-swing-mechanic isolation IP and cloud-analytics platforms with existing amateur user bases. Monitor FCC wireless certification timeline extensions as inflection indicator for connected-device launch delays compressing seasonal selling windows.| Strategic Initiative | Industry Significance |
|---|---|
| AI Coaching Algorithm Integration | Computer-vision swing correction unlocks remote instruction markets without certified professional presence. |
| Backward Integration into MEMS Sourcing | Captive sensor supply mitigates Taiwan foundry concentration risk for connected trainer production. |
| Academy Chain Exclusive Arrangements | Curriculum standardization across Arizona, Florida, and Texas networks locks out independent instructor competition. |
| Bio-Based Polymer Reformulation | ECHA REACH compliance for EU Green Deal mandates opens German and Dutch municipal procurement pathways. |
| Subscription Software Platform Launch | Cloud swing analytics create recurring revenue streams offsetting hardware margin compression in sensor categories. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary data collection engaged golf academy chain procurement directors, MEMS sensor foundry account managers, municipal course pro shop operators, and FCC regulatory compliance consultants. Secondary validation drew from SEC 10-K filings of listed equipment manufacturers, ECHA REACH substance restriction updates, FCC equipment authorization databases, and ISO sports equipment testing protocols. Bottom-up demand modeling across amateur player segments and top-down supply-side capacity assessments were cross-referenced for convergence.
Segment-weighting approaches applied differential growth assumptions across product type, application scope, end-user category, and distribution channel dimensions. Swing trainers, ball flight monitors, putting aids, and grip trainers carried distinct sensor component cost curves and software attach rate profiles. End-user splits between amateur players, professionals, coaches, and academy networks informed replacement cycle assumptions. CAGRs were derived from installed base expansion rates and average selling price trajectory modeling. MEMS sensor miniaturization cost curves and EU Green Deal material compliance timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; sensor-integrated categories carry tighter precision than mechanical aids due to transparent component cost data. Forecasts reflect documented assumptions regarding semiconductor supply continuity, regulatory certification timeline stability, and academy chain consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Knee Pads Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Diving Board Market