
 Global Basketball Shoes Market | 2026-2036
Global Basketball Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Basketball Shoes Market Analysis
Chinese manufacturing clusters in Fujian and Guangdong are hardening their grip on mid-sole component supply. Nike, Inc. leverages vertical integration into proprietary foam chemistry to sustain margin control at premium tiers. ANTA Sports Products Limited anchors its expansion through deep partnerships with China's professional basketball league. Adidas AG differentiates via recycled ocean plastic integration across signature lines.
Basketball shoes are performance athletic footwear engineered with reinforced ankle collars, responsive cushioning systems, and herringbone-pattern outsoles designed for lateral stability and shock absorption during high-impact court movements. High-Top constructions retain dominant share among injury-conscious recreational players, while Low-Top variants are capturing fastest growth through guard-position specialization and lifestyle crossover appeal. Online Retailers command accelerating volume as direct-to-consumer platforms collapse traditional wholesale markups, though Specialty Stores still capture margin-rich fitting services for competitive athletes.
FDA oversight of latex and synthetic rubber biocompatibility affects domestic US production sourcing decisions, while REACH chemical restrictions in Europe constrain certain solvent-based adhesives used in upper construction. China's GB standards for volatile organic compound emissions from synthetic leathers are forcing material reformulation across Asian supply chains. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and regional chemical disclosure regimes reshape cost structures and supplier qualification timelines.
Market Dynamics
Chinese manufacturing clusters in Fujian and Guangdong now control mid-sole component supply, while proprietary foam chemistry investments by premium brands are compressing margin capture for non-integrated competitors. This supply-side concentration collides with tightening chemical disclosure mandates across California, the European Union, and China.
Growth Catalysts
- Amateur youth league expansion:Recreational training programs in Greater China and the United States are shortening footwear refresh cycles through organized competition structures.
- GB standards compliance infrastructure:China's synthetic material safety certification pathways are accelerating domestic brand qualification timelines for export markets.
- Guard-position specialization:Low-Top technical specifications for speed-oriented players are capturing lifestyle crossover demand beyond court use.
Market Restraints
- Ethylene-vinyl acetate price volatility:Petrochemical feedstock fluctuations compress mid-sole margin predictability for non-captive producers.
- Fujian-Guangdong supply concentration:Geographic clustering of TPU injection molding capacity creates single-point vulnerability for global brand sourcing.
- California Proposition 65 enforcement:Chemical disclosure litigation risk elevates compliance insurance costs for US distribution.
Strategic Opportunities
- India organized sports infrastructure:National basketball federation partnerships offer first-mover positioning in underdeveloped competitive footwear channels.
- Direct-to-consumer platform penetration:Brand-owned digital storefronts collapse wholesale markups while capturing biometric fitting data.
- EU Green Deal material mandates:Recycled content thresholds for synthetic textiles create premium positioning for ocean plastic integration.
Industry Challenges
- Biomechanical engineering talent scarcity:Computational modeling expertise for cushioning system optimization commands compensation premiums that strain mid-cap R&D budgets.
- Multi-jurisdiction certification sequencing:Parallel GB standard, REACH, and FDA biocompatibility testing extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Basketball Shoes Market |
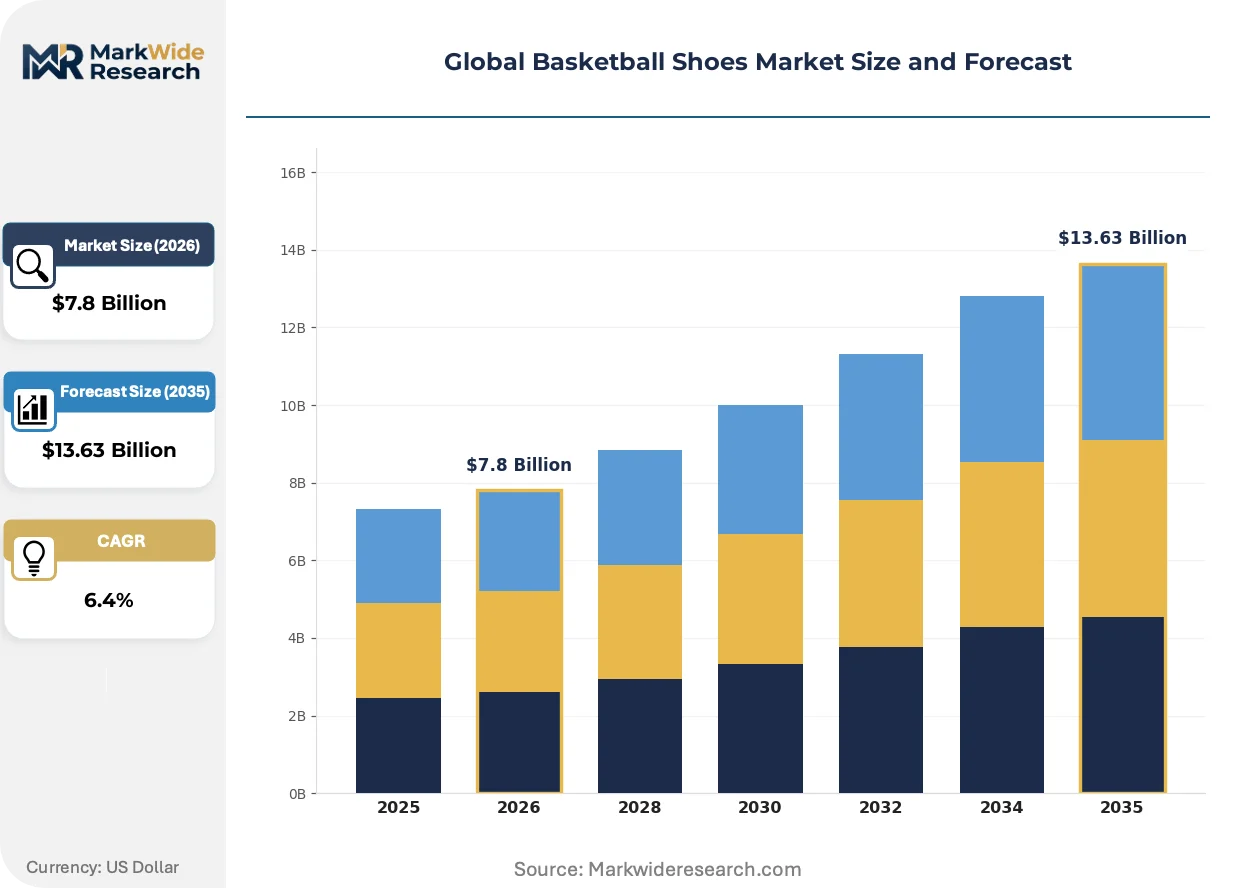
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Top, Low-Top, Mid-Top, Performance End User: Men, Women, Children, Athletes Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Wholesale Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Under Armour, Inc., ANTA Sports Products Limited, Nike, Inc., ASICS Corporation, Li-Ning Company Limited, Adidas AG, New Balance Athletics, Inc., Skechers USA, Inc., PUMA SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Basketball Shoes Market Emerging Trajectories
Digital manufacturing workflows and material science advances are compressing product development cycles while fragmenting competitive advantage sources. Three developments are actively restructuring how value is created and captured.
Generative design software for lattice-structured mid-soles is decentralizing cushioning innovation away from centralized brand laboratories toward specialized component suppliers. Tier-two manufacturers in Dongguan now prototype energy-return geometries independently, then license specifications to multiple brand customers. This capability diffusion erodes the historical R&D moat of vertically integrated market leaders.
REACH chemical restrictions on solvent-based adhesives are forcing upper construction reformulation across European-bound production lines. Manufacturers are shifting toward water-based bonding agents and heat-activated films, which extend curing times but eliminate hazardous substance registration liabilities. Italian and Portuguese suppliers serving premium heritage brands have been fastest to requalify alternative chemistries.
Specialty Store fitting services are unbundling from product transactions as standalone biomechanical assessment clinics emerge. These facilities sell motion-capture analysis and personalized insole prescriptions, then direct consumers to online channels for actual footwear purchase. Germany's specialist running retail sector has pioneered this service separation, with basketball-specific variants now appearing in basketball-dense US metropolitan markets.
Global Basketball Shoes Market Segmentation
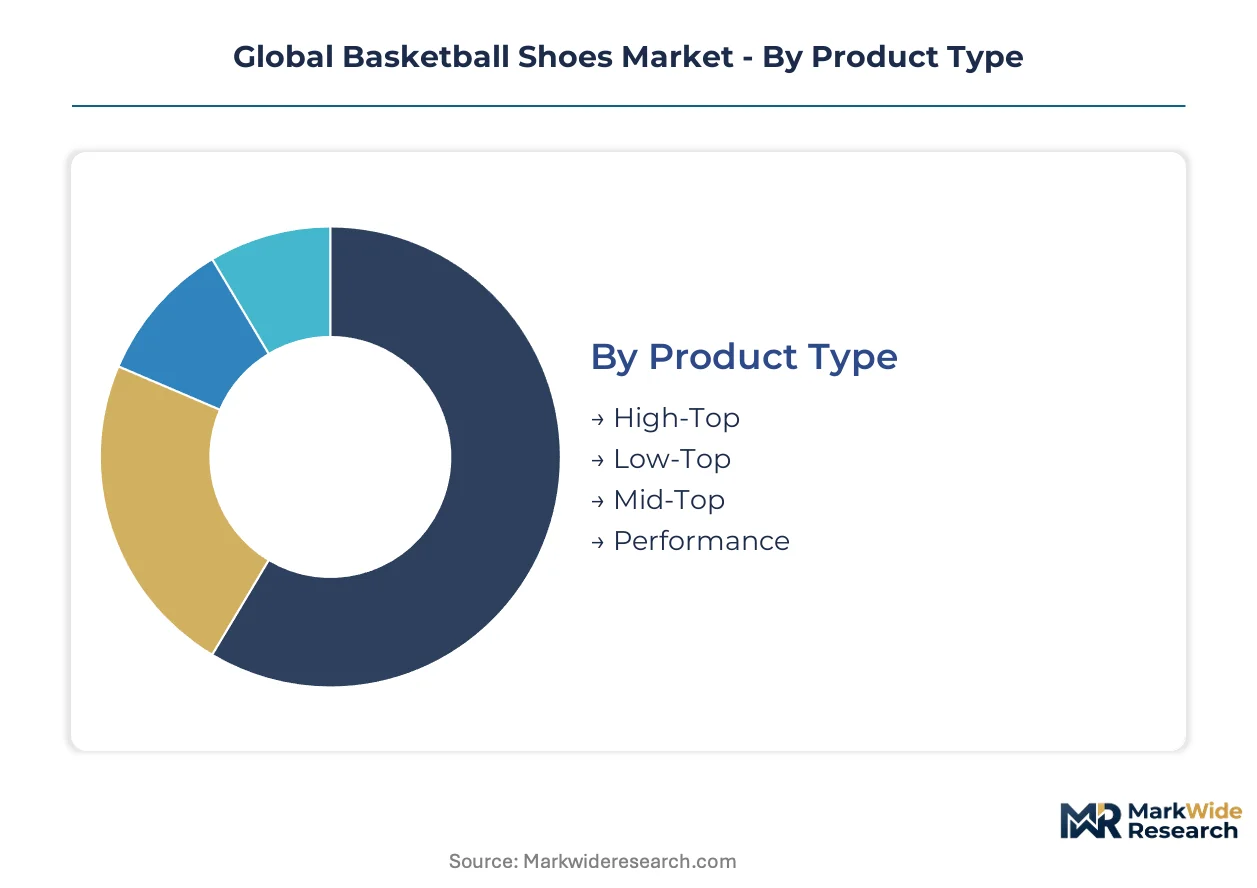
Basketball shoe purchasing decisions hinge on ankle support requirements, competitive intensity, and channel accessibility. Segmentation reveals how technical specifications, user demographics, and retail formats allocate margin capture across the value chain.
Product Type:
Ankle injury risk and positional specialization drive construction preferences among recreational and competitive buyers.
- High-Top:Extended collar construction stabilizes the ankle joint through reinforced upper materials and structured heel counters. Recreational players in the United States prioritize this configuration for injury prevention during weekend league play, though added weight constrains adoption among speed-oriented athletes.
- Low-Top:Streamlined silhouette eliminates collar restriction to maximize court feel and transition speed. Guard-position specialization in Greater China amateur leagues accelerates refresh cycles for this variant, with lifestyle crossover extending demand beyond competitive use.
- Mid-Top:Hybrid construction balances mobility and support for versatile positional players.
- Performance:Competition-grade specifications incorporate carbon fiber shanks and proprietary foam stacks for elite athletic deployment.
Volume sits with High-Top construction; growth tilts toward Low-Top specialization and lifestyle crossover appeal.
End User:
Demographic purchasing power and organized sports participation rates shape product tier allocation and marketing investment.
- Men:Established competitive infrastructure and professional league viewership sustain the deepest product line investments and signature athlete partnerships.
- Women:Expanding collegiate and professional league structures in the United States and Australia are narrowing the historical product development gap, with last-specific lasts and cushioning tuning gaining technical priority.
- Children:Rapid foot growth drives replacement frequency, with parents prioritizing durability and value positioning over technical performance features.
- Athletes:Federated competition requirements mandate certified non-marking outsoles and standardized color restrictions for league eligibility.
Revenue concentration remains with Men; steepest expansion trajectory belongs to Women as competitive infrastructure matures.
Distribution Channel:
Margin capture and customer acquisition costs diverge sharply between experiential retail and digital efficiency.
- Online Retailers:Direct-to-consumer platforms collapse wholesale markups while capturing biometric fitting data for personalization algorithms. California-based fulfillment networks face elevated Proposition 65 compliance insurance costs that pressure net margins.
- Specialty Stores:Motion-capture fitting services and expert consultation sustain premium pricing for competitive athletes seeking precise last matching and orthotic integration.
- Department Stores:Mass-market accessibility prioritizes brand recognition and impulse purchasing over technical consultation.
- Wholesale:Volume commitments from sporting goods chains secure production slotting but compress per-unit profitability.
Transaction volume is concentrating in Online Retailers; margin preservation depends on Specialty Store service differentiation.
Price Tier:
Material specification and certification grade stratify accessible entry points from premium positioning.
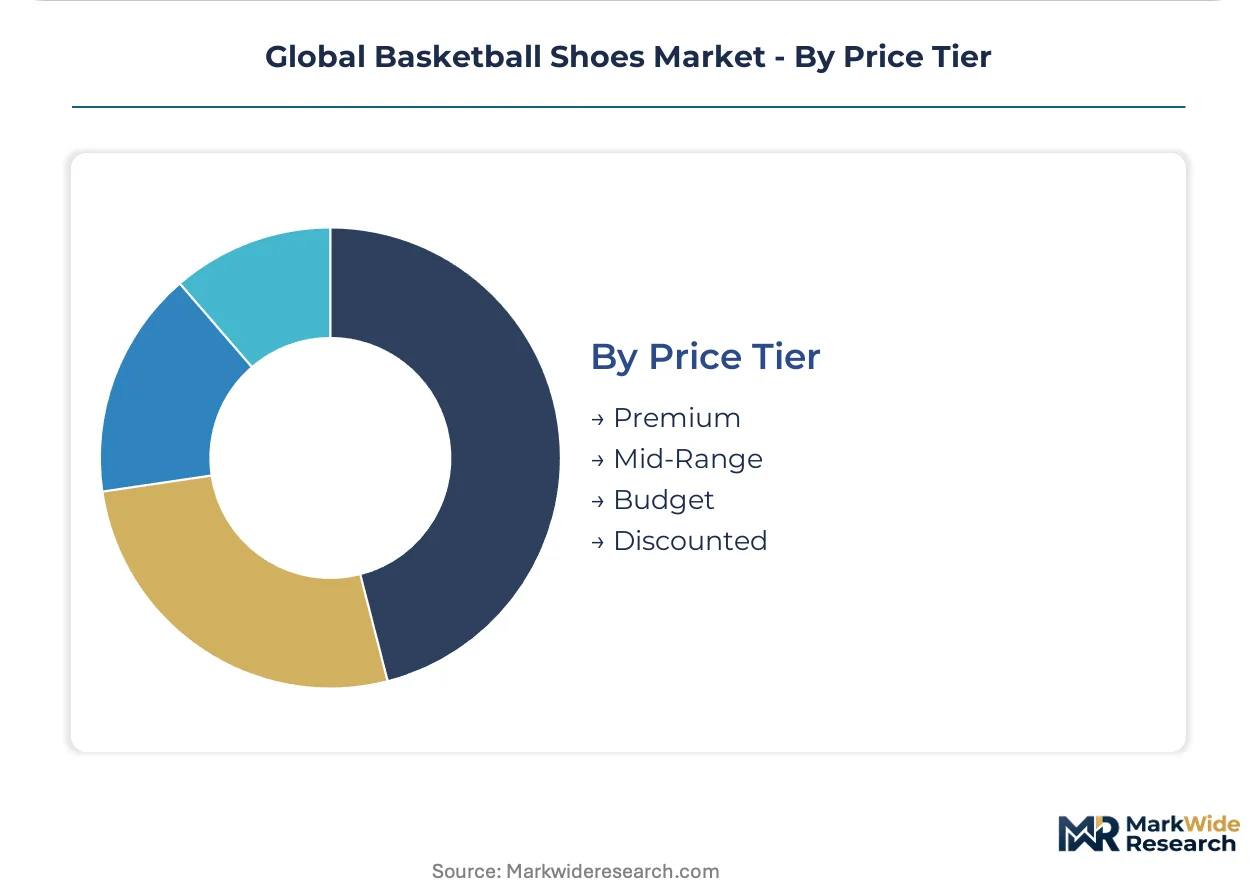
- Premium:Proprietary foam chemistry, athlete co-development, and limited production runs justify three-figure price positioning. Nike and ANTA Sports Products Limited anchor this tier through vertical control of mid-sole innovation.
- Mid-Range:Balanced specification packages target serious recreational players seeking durability and performance without signature pricing.
- Budget:Simplified upper constructions and standardized cushioning platforms serve price-sensitive youth league participants.
- Discounted:Prior-season inventory clearance and factory outlet channels liquidate excess stock without brand dilution.
Unit volume flows through Budget and Mid-Range tiers; brand equity and margin accrue to Premium positioning through proprietary technology control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene-vinyl acetate feedstock availability in the US Gulf Coast anchors North American mid-sole production economics. Chinese manufacturing clusters in Fujian and Guangdong provinces control global TPU injection molding capacity for energy-return components. European REACH chemical restrictions reshape upper construction supply chains around solvent-free bonding technologies.
United States
Amateur youth league expansion in California and Texas accelerates footwear refresh cycles through organized competition structures. FDA oversight of latex and synthetic rubber biocompatibility affects domestic production sourcing decisions for brands serving medical-adjacent distribution channels. Los Angeles-based fulfillment networks face elevated Proposition 65 compliance insurance costs that pressure direct-to-consumer margins.
China
Domestic brands leverage deep partnerships with the Chinese Basketball Association to accelerate category penetration across tier-two and tier-three cities. GB standards for volatile organic compound emissions from synthetic leathers force material reformulation across Asian supply chains. Dongguan and Quanzhou manufacturing clusters now prototype lattice-structured mid-soles independently, licensing energy-return geometries to multiple brand customers.
Germany
Specialty retail unbundling advances as standalone biomechanical assessment clinics emerge in Berlin and Munich metropolitan markets. EU Green Deal recycled content thresholds for synthetic textiles create premium positioning opportunities for ocean plastic integration. Bavaria-based suppliers serving heritage brands have been fastest to requalify water-based bonding chemistries under REACH solvent restrictions.
India
National basketball federation partnerships offer first-mover positioning in underdeveloped competitive footwear channels across Maharashtra and Karnataka. Bureau of Indian Standards certification pathways for synthetic material safety remain nascent compared to GB standard infrastructure. Mumbai and Bengaluru retail corridors concentrate early direct-to-consumer platform experiments targeting guard-position specialization demand.
Japan
Collegiate and professional league maturation narrows the historical product development gap for women-specific last engineering. METI industrial standards for performance footwear durability exceed baseline ISO specifications, elevating quality premiums for export-bound production. Osaka-Kobe manufacturing heritage clusters retain specialized cushioning system optimization expertise that commands compensation premiums.
Global Basketball Shoes Market Vendor Landscape
Global majors compete with regional champions across proprietary foam chemistry and athlete partnership dimensions. Market structure tilts toward oligopoly at premium tiers while mid-range and budget segments fragment across manufacturing specialists and private-label operators. Three archetypes dominate: vertically integrated innovators controlling captive mid-sole supply, federation-anchored domestic champions leveraging league partnerships, and sustainability-positioned heritage brands differentiating through material storylines. Competitive moves concentrate on direct-to-consumer platform buildout and multi-jurisdiction certification sequencing acceleration.
Within the vertically integrated tier, Nike, Inc. and ANTA Sports Products Limited exemplify contrasting geographic anchors. The Beaverton, Oregon-based operator and the Jinjiang, Fujian-based sportswear group occupy positions defined by upstream control over proprietary foam chemistry and deep federation partnerships respectively. Adidas AG represents the sustainability-differentiated heritage archetype through recycled ocean plastic integration across signature lines. These three entities illustrate how competitive positioning fragments across technology control, domestic market access, and material narrative dimensions.
| Leading Market Players |
|---|
| Under Armour, Inc. |
| ANTA Sports Products Limited |
| Nike, Inc. |
| ASICS Corporation |
| Li-Ning Company Limited |
| Adidas AG |
| New Balance Athletics, Inc. |
| Skechers USA, Inc. |
| PUMA SE |
| Others |
Supply Flow & Price Mechanics
Ethylene-vinyl acetate feedstock volatility in the US Gulf Coast propagates through mid-sole component costs to stratify final pricing across premium, standard, and economy tiers. Petrochemical price swings compress margin predictability for non-integrated brands while captive foam chemistry operators sustain pricing power through upstream control.
Pricing Analysis
Warranty and after-sales service bundling separates premium positioning from unbundled economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects proprietary foam chemistry control, certification grade under GB standards and REACH, and volume scale commitments. Pricing pressure stems from Fujian-Guangdong supply concentration and ethylene-vinyl acetate cost compression. Amateur youth league participants in budget tiers exhibit highest price sensitivity; elite athletes seeking biomechanical fitting services show lowest sensitivity.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Quanzhou manufacturing clusters tether production capacity to regional labor migration patterns. TPU injection molding concentrates in China's Fujian and Guangdong provinces, with secondary capacity in Vietnam and Indonesia. Raw material dependencies span synthetic rubber, ethylene-vinyl acetate, and recycled ocean plastic feedstocks. Single-source vulnerability in mid-sole component supply creates chokepoint risk. Distribution runs through direct-to-consumer platforms and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vertically integrated innovators as multi-jurisdiction certification sequencing and proprietary foam chemistry investments force weaker competitors toward private-label manufacturing.
For Market Incumbents: Cement upstream control over mid-sole component supply through captive TPU injection molding capacity in Fujian-Guangdong clusters. Accelerate GB standards and REACH certification sequencing to compress product launch timelines against emerging domestic brands. Biomechanical engineering talent scarcity threatens R&D velocity; secure computational modeling expertise through compensation premiums or specialist acquisitions.
For New Entrants and Emerging Players: EU Green Deal recycled content thresholds in Europe open a window for ocean plastic integration positioning against heritage sustainability narratives. Target India's underdeveloped competitive footwear channels through national basketball federation partnerships. Guard-position specialization demand in Greater China amateur leagues offers segment entry with lower certification burden than premium tiers.
For Investors and Strategic Acquirers: Standalone biomechanical assessment clinic proliferation is the leading indicator that service unbundling from product transactions will reshape margin capture. Long-term viability favors vertically integrated mid-cap specialists with captive mid-sole supply and direct-to-consumer platform penetration. Watch for Dongguan-Quanzhou manufacturing cluster labor cost inflection as signal for supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Foam Chemistry Investment | Captive mid-sole supply secures margin control against Fujian-Guangdong component pricing volatility. |
| Direct-to-Consumer Platform Buildout | Biometric fitting data capture enables personalization algorithms that collapse wholesale markup structures. |
| Multi-Jurisdiction Certification Acceleration | Parallel GB standard, REACH, and FDA testing compression shortens product launch timelines against competitors. |
| Recycled Ocean Plastic Integration | EU Green Deal compliance creates premium positioning differentiation in European distribution channels. |
| Biomechanical Assessment Clinic Partnership | Service unbundling from transactions captures margin-rich fitting revenue before online purchase redirection. |
Methodological Framework
Trade databases, customs records, and federation partnership disclosures formed the secondary backbone, supplemented by primary interviews with mid-sole component suppliers, brand R&D directors, specialty retail buyers, and amateur league organizers. Bottom-up and top-down triangulation validated volume estimates across product type, end user demographic, distribution channel, and price tier segmentation.
Bottom-up modeling anchored projections in unit economics by segment, while top-down cross-checks against aggregate market sizing ensured consistency across the analysis window. Modeled dimensions span ankle support construction, competitive intensity tier, channel accessibility, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for material science innovation cycles and youth league infrastructure buildout rates.
The model assumes a particular technology adoption path; alternative pathways for generative design software and lattice-structured mid-soles would alter the outlook. Forecasts reflect assumptions around ethylene-vinyl acetate feedstock stability, GB standards enforcement intensity, and direct-to-consumer platform penetration velocity. Material deviation in synthetic material safety certification timelines or carbon-border adjustment mechanism implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Baseball Equipment Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Sports Devices Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market