
 Solar Powered Cold Storage Market | 2026-2036
Solar Powered Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Cold Storage Market Outlook
The performance gap between premium solar-battery hybrid cold storage and commodity direct-drive units is hardening. Koolboks Incorporated leverages pay-as-you-go financing to anchor last-mile deployment across West African markets. Godrej & Boyce Manufacturing Company Limited sustains its position through deep refrigeration engineering heritage and domestic manufacturing scale in India. Viking Cold Solutions, Inc. differentiates via proprietary phase-change thermal storage that extends cooling autonomy during low-irradiance periods.
Solar powered cold storage integrates photovoltaic generation with vapor-compression or absorption refrigeration to preserve perishables without grid dependency, typically operating at minus 20 to 4 degrees Celsius depending on cargo. Systems range from 50-liter vaccine carriers to 500-ton warehouse installations with lithium-ion or ice-battery backup. Container and warehouse formats dominate capital deployment due to scalability for agricultural aggregators and pharmaceutical distributors. Solar PV technology leads installed base while hybrid systems capture the fastest growth as battery costs decline and reliability expectations rise.
India's Ministry of New and Renewable Energy coordinates with BIS certification mandates for solar cold chain equipment under national cold chain expansion programs. Kenya's Energy Regulatory Authority and Nigeria's Rural Electrification Agency shape market access through import duty waivers and quality standards for off-grid refrigeration. Stakeholders must monitor how evolving refrigerant regulations under the Kigali Amendment intersect with national solar subsidy programs to determine total cost of ownership trajectories.
Market Dynamics
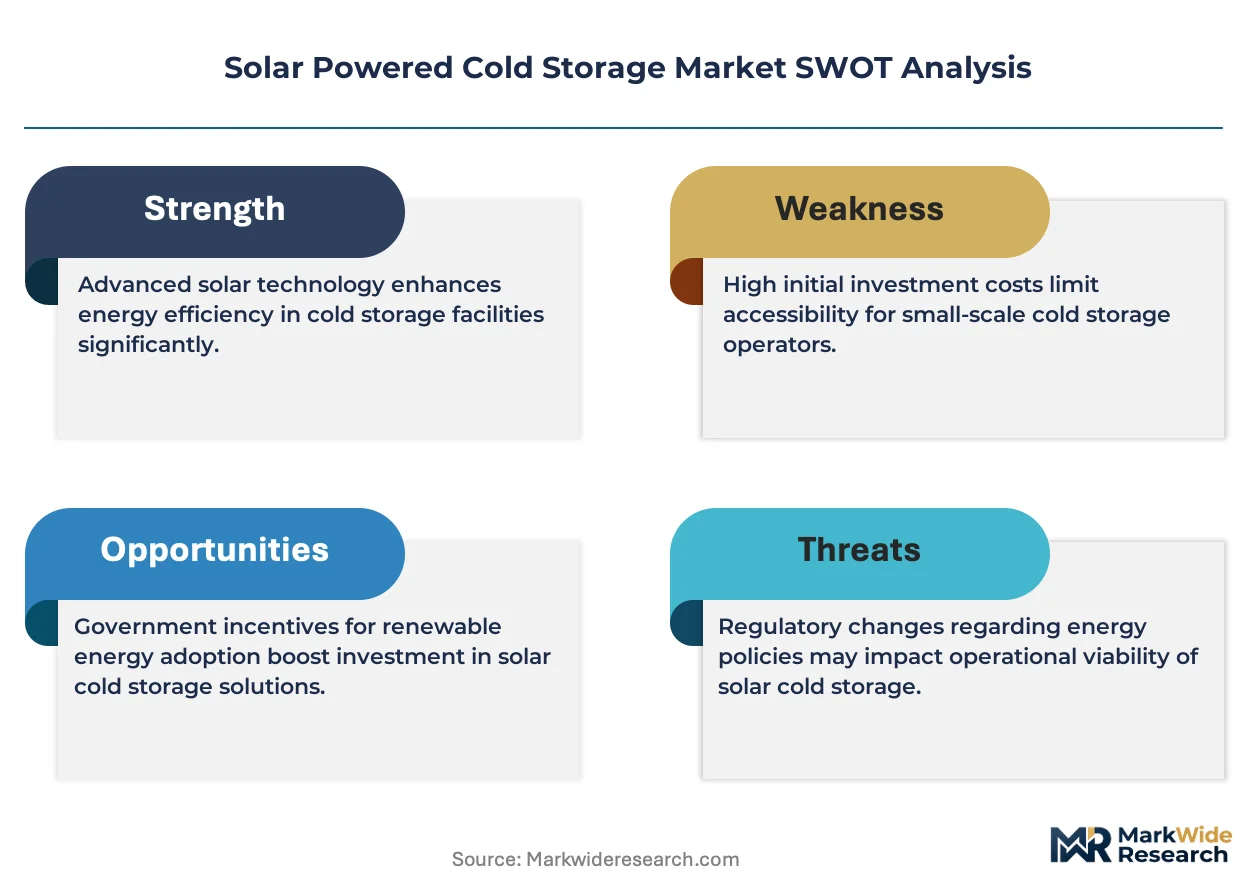
India's PLI scheme for solar PV manufacturing is compressing panel costs for cold chain integrators while Kenya's Rural Electrification Agency and Nigeria's import duty waivers reshape deployment economics across sub-Saharan agricultural corridors.
Growth Catalysts
- India's PLI scheme:Domestic solar panel manufacturing subsidies reduce capital costs for cold room installations serving horticultural cooperatives in Maharashtra and Karnataka.
- Kenya's Energy Regulatory Authority:Quality standards and import duty waivers accelerate off-grid refrigeration penetration among tea and flower export aggregators.
- Phase-change thermal storage:Ice-battery backup systems extend cooling autonomy during monsoon cloud cover, enabling reliable vaccine distribution in rural health networks.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in China create input cost volatility and geopolitical exposure for African cold chain operators.
- Kigali Amendment refrigerant phase-down:Hydrofluorocarbon restrictions force premature equipment retrofit costs for existing vapor-compression installations.
- Direct-drive solar thermal:Absorption refrigeration units without battery backup threaten hybrid system pricing power in price-sensitive West African markets.
Strategic Opportunities
- Nigerian pharmaceutical corridors:Last-mile vaccine distribution networks remain underpenetrated by temperature-assured logistics outside Lagos and Abuja.
- Pay-as-you-go financing:Mobile-money-integrated leasing models unlock smallholder farmer access to 50-500 liter solar cold boxes.
- Convergence of solar PV and IoT monitoring:Real-time temperature logging meets WHO prequalification standards for international health procurement.
Industry Challenges
- Refrigeration technician scarcity:Vapor-compression maintenance expertise concentrates in urban centers, leaving rural installations with 72-hour repair windows.
- BIS certification timelines:India's mandatory testing protocols for solar cold chain equipment extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Cold Storage Market |
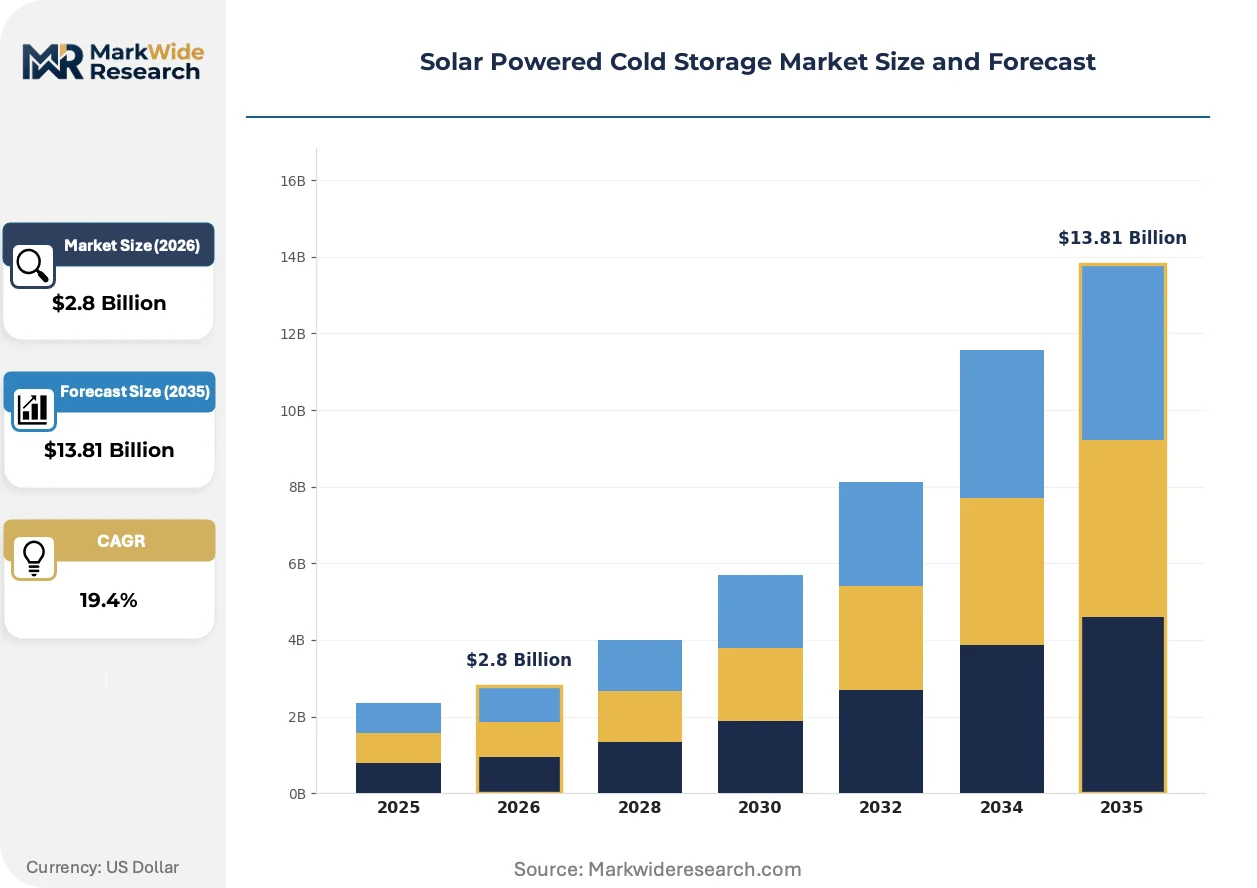
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freezer, Refrigerator, Warehouse, Container End User: Agriculture, Pharmaceuticals, Fisheries, Food & Beverage Technology: Solar PV, Thermal Storage, Hybrid Systems, Refrigerant Systems Capacity: Small Scale, Medium Scale, Large Scale, Custom Solutions |
| Companies Covered | Koolboks Incorporated, Viking Cold Solutions, Inc., Haier Group Corporation, Promethean Power Systems, Godrej & Boyce Manufacturing Company Limited, Energy Efficiency Services Limited (EESL), SunDanzer Refrigeration Incorporated, Carrier Global Corporation, Ecozen Solutions Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Cold Storage Market Strategic Shifts
Technology convergence between photovoltaic generation and thermal storage architectures is compressing total cost of ownership curves while regulatory refrigerant mandates force equipment refresh cycles.
Phase-change material thermal batteries are integrating with lithium-ion hybrid systems to extend cooling autonomy from 4 hours to 72 hours during low-irradiance periods. Pharmaceutical distributors in Nigeria and Kenya are adopting these configurations for vaccine cold rooms where grid reliability falls below 40%. The technology is integrating backup redundancy into capital planning, reducing diesel generator dependency and enabling WHO prequalification for international tender participation.
Kenya's Energy Regulatory Authority and Nigeria's Rural Electrification Agency have harmonized quality standards for off-grid refrigeration equipment under ECOWAS and EAC technical regulations. These frameworks mandate minimum energy efficiency ratios and solar array sizing protocols. Agricultural cooperatives in both countries now face consolidated compliance pathways, reducing certification duplication costs for equipment vendors seeking multi-country deployment.
Smallholder farmer aggregators are consolidating procurement through cooperative buying platforms that bypass traditional equipment distributors. These digital marketplaces bundle financing, installation, and maintenance contracts into single-service agreements. The shift is most visible in India's Maharashtra horticulture belt and Kenya's Rift Valley flower cooperatives, where 200-500 member farmer groups negotiate containerized cold room deployments at 15-20% below spot market capital costs.
Solar Powered Cold Storage Market Segmentation
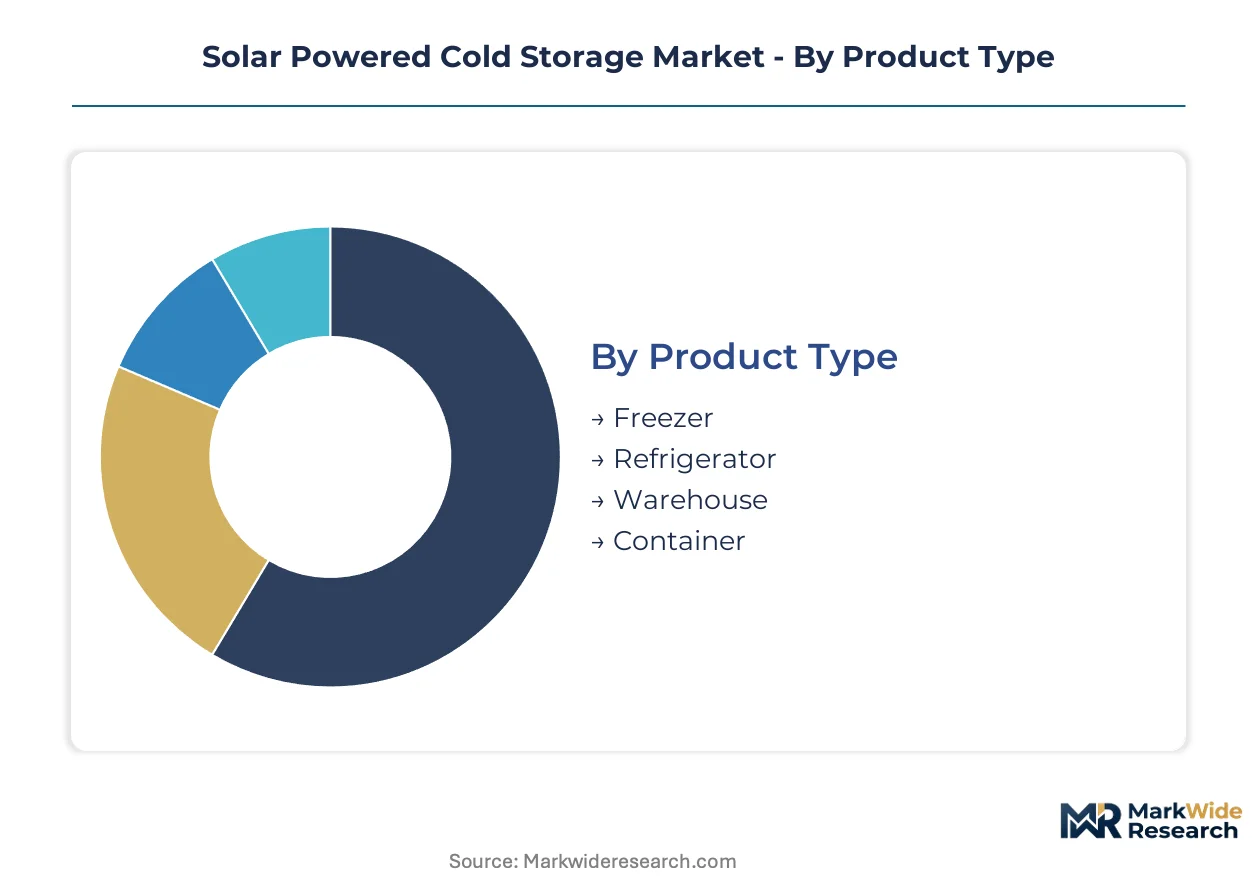
Segmentation in solar powered cold storage reveals how deployment economics shift across thermal loads, power architectures, and operational scales. Procurement patterns diverge sharply between pharmaceutical distributors demanding WHO-compliant temperature logging and agricultural cooperatives optimizing for capital recovery on seasonal harvests.
Product Type:
Standardization dominates freezer and refrigerator formats while warehouse and container systems demand site-specific engineering for solar array sizing and insulation specifications.
- Freezer:Vapor-compression units operating at minus 20 degrees Celsius serve vaccine distribution networks in Nigeria's rural health corridors. Kenya's flower export aggregators deploy these for pre-cooling rose harvests where grid reliability falls below 40%.
- Refrigerator:Units maintaining 2-8 degrees Celsius preserve horticultural produce across India's Maharashtra and Karnataka belts. Smallholder cooperatives favor 50-500 liter formats with pay-as-you-go financing integration through mobile money platforms.
- Warehouse:Fixed installations exceeding 100 tons capacity serve regional agricultural aggregation hubs with custom photovoltaic array sizing.
- Container:Modular 20-foot and 40-foot formats enable rapid deployment for pharmaceutical distributors requiring WHO prequalification compliance.
Leading the category by volume: Container. Growing fastest: Warehouse.
End User:
Margin structures vary dramatically across end-use verticals, with pharmaceutical cold chains commanding 3-4x capital premiums over agricultural deployments for equivalent thermal capacity.
- Agriculture:Horticultural cooperatives in sub-Saharan Africa deploy solar cold rooms to cut post-harvest losses exceeding 40% for temperature-sensitive crops. India's PLI scheme for solar PV manufacturing compresses panel costs for Maharashtra and Karnataka farmer groups.
- Pharmaceuticals:Vaccine distributors in Nigeria and Kenya require uninterrupted cooling autonomy with lithium-ion or phase-change backup meeting WHO temperature logging standards. Real-time IoT monitoring integration is becoming mandatory for international tender participation.
- Fisheries:Coastal communities in West Africa utilize direct-drive absorption units without battery backup for ice production and catch preservation.
- Food & Beverage:Dairy processors and beverage distributors deploy hybrid systems with thermal storage to bridge grid intermittency in peri-urban markets.
Agriculture dominates installed base. Pharmaceuticals climbs fastest on regulatory compliance spending.
Technology:
Technology selection hinges on irradiance patterns and backup duration requirements, with hybrid architectures gaining share as battery costs decline.
- Solar PV:Photovoltaic generation paired with vapor-compression refrigeration constitutes the dominant installed base across India and East Africa. India's BIS certification mandates extend product launch cycles by 8-14 months for equipment vendors.
- Thermal Storage:Phase-change material batteries extend cooling autonomy from 4 hours to 72 hours during monsoon cloud cover. Viking Cold Solutions' proprietary ice-battery configurations enable diesel generator elimination in Nigerian vaccine corridors.
- Hybrid Systems:Lithium-ion and thermal storage combinations capture steepest expansion trajectory as reliability expectations rise and battery supply constraints ease.
- Refrigerant Systems:Absorption refrigeration without electrical backup threatens hybrid pricing power in price-sensitive West African markets through lower capital outlay.
Solar PV leads by deployment count. Hybrid systems gain share fastest on reliability premiums.
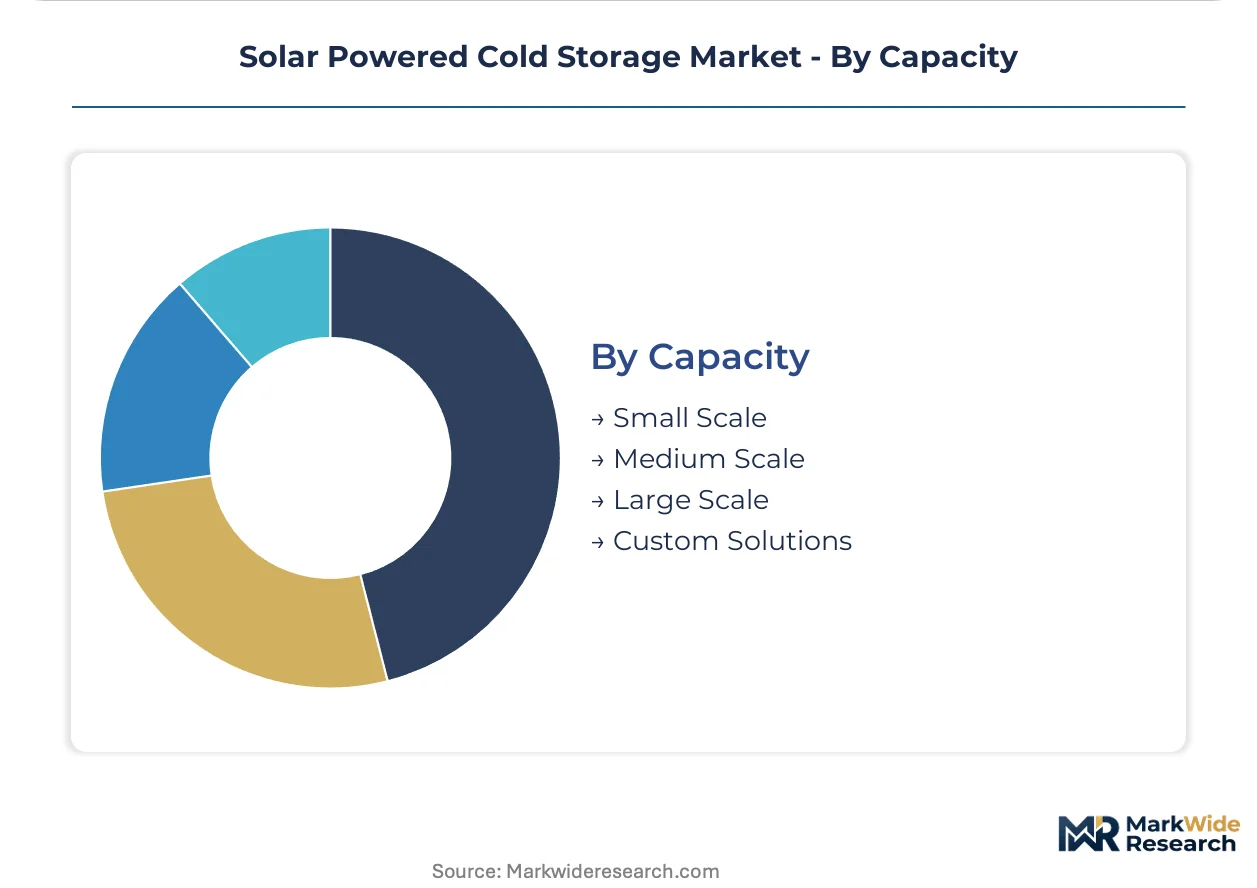
Capacity:
Scale selection correlates with customer type and financing access, with small formats unlocking pay-as-you-go models and large installations requiring cooperative procurement aggregation.
- Small Scale:50-500 liter units serve individual smallholders and rural health posts with mobile-money-integrated leasing. Koolboks Incorporated anchors West African last-mile deployment through this format.
- Medium Scale:2-20 ton containerized systems serve agricultural cooperatives of 200-500 members negotiating bundled installation and maintenance contracts at 15-20% below spot market pricing.
- Large Scale:Installations exceeding 100 tons serve regional pharmaceutical distribution hubs and export-oriented flower operations requiring continuous temperature assurance.
- Custom Solutions:Site-engineered warehouse formats address non-standard cargo profiles and extreme ambient temperature conditions in desert-edge agricultural zones.
Medium scale dominates capital deployment. Small scale expands most quickly on financing innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors deployment velocity across Nigerian pharmaceutical corridors, where rural vaccine distribution networks drive containerized cold room installations. Kenya's Rift Valley and India's Maharashtra horticulture belt concentrate agricultural cooperative procurement. Regulatory harmonization under ECOWAS and EAC technical standards is compressing multi-country certification costs for equipment vendors.
India
Maharashtra and Karnataka horticultural cooperatives deploy solar cold rooms to cut post-harvest losses exceeding 40% for temperature-sensitive crops. BIS certification mandates extend product launch cycles by 8-14 months for equipment vendors serving domestic cold chain expansion programs. The PLI scheme for solar PV manufacturing compresses panel costs for cold room integrators across western and southern agricultural belts.
Kenya
Tea and flower export aggregators in the Rift Valley accelerate off-grid refrigeration penetration where grid reliability falls below 40%. The Energy Regulatory Authority enforces quality standards and import duty waivers that reshape deployment economics for agricultural cooperatives. Nairobi-based pharmaceutical distributors adopt phase-change thermal storage configurations to extend cooling autonomy during monsoon cloud cover.
Nigeria
Last-mile vaccine distribution networks outside Lagos and Abuja remain underpenetrated by temperature-assured logistics, creating deployment gaps for 50-500 liter solar cold boxes. The Rural Electrification Agency shapes market access through import duty waivers and quality standards for off-grid refrigeration. Kano and Kaduna agricultural corridors see rising adoption of pay-as-you-go financed units among smallholder farmer aggregators.
United States
California's Central Valley and Arizona's desert-edge agricultural zones deploy hybrid solar-battery systems to bridge grid intermittency for perishable commodity storage. FDA cold chain regulations intersect with state-level renewable energy incentives to shape total cost of ownership calculations for pharmaceutical distributors. Texas and Florida peri-urban markets see concentrated adoption among dairy processors seeking diesel generator elimination.
Solar Powered Cold Storage Market Competitive Environment
Premium-margin players sit above commodity-margin players across thermal storage sophistication and financing integration depth. The vendor base stratifies between engineering-heritage refrigeration specialists, solar-native equipment fabricators, and pay-as-you-go financing platforms. Three archetypes dominate: domestic manufacturing scale players leveraging PLI subsidies, phase-change thermal storage specialists, and mobile-money-integrated leasing operators. Geographic expansion and technology licensing constitute the dominant competitive moves, with M&A activity concentrated in African last-mile distribution capabilities.
Within the engineering-heritage tier, Godrej & Boyce Manufacturing Company Limited and Carrier Global Corporation exemplify domestic manufacturing scale and deep refrigeration expertise. Koolboks Incorporated occupies a position among financing-integrated operators, while Viking Cold Solutions, Inc. anchors the thermal storage specialization vector. These three represent distinct strategic postures: captive supply chain control, mobile-money platform leverage, and proprietary phase-change material innovation.
| Leading Market Players |
|---|
| Koolboks Incorporated |
| Viking Cold Solutions, Inc. |
| Haier Group Corporation |
| Promethean Power Systems |
| Godrej & Boyce Manufacturing Company Limited |
| Energy Efficiency Services Limited (EESL) |
| SunDanzer Refrigeration Incorporated |
| Carrier Global Corporation |
| Ecozen Solutions Private Limited |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion cell costs cascade through three pricing tiers for solar cold storage equipment, compressing margins for hybrid system assemblers while amplifying returns for phase-change thermal storage specialists who bypass battery supply exposure. India's PLI-scheme panel subsidies and Kenya's import duty waivers reshape landed cost structures across agricultural procurement corridors.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for pharmaceutical cold rooms serving Nigerian vaccine distributors, with WHO-prequalified installations commanding 3-4x premiums over agricultural equivalents. Three-tier pricing structure across premium, standard, and economy levels separates lithium-ion hybrid configurations from direct-drive absorption units and basic solar PV vapor-compression systems. Cost compression in battery-dependent tiers is intensifying because Chinese cell supply concentration exposes African operators to input volatility. Smallholder cooperatives purchasing 50-500 liter formats through pay-as-you-go platforms exhibit highest price sensitivity, while pharmaceutical distributors prioritize reliability over capital outlay.
Supply Chain Analysis
Refrigeration technician scarcity in Indian and Nigerian manufacturing zones constrains assembly capacity expansion despite rising order backlogs. Solar PV module supply concentrates in China, India, and Vietnam, while vapor-compression compressors draw from Japanese and German component specialists. Phase-change materials and lithium-ion cells feed from Chinese chemical processors and South Korean cell manufacturers. Single-source vulnerability in battery cell supply creates geopolitical exposure for hybrid system integrators. Distribution runs through agricultural cooperative buying platforms in Maharashtra and Kenya's Rift Valley, bypassing traditional equipment distributors for 15-20% cost savings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around thermal storage sophistication and financing integration depth, with BIS certification timelines and lithium-ion cost volatility forcing sub-scale assemblers toward acquisition or exit.
For Market Incumbents: Anticipate margin compression in commodity solar PV segments by securing captive supply of phase-change materials or lithium-ion cells through backward integration into Indian or South Korean battery partnerships. Deepen WHO prequalification investments to defend pharmaceutical pricing premiums against emerging thermal storage specialists. For New Entrants and Emerging Players: Capture last-mile vaccine distribution gaps in Nigeria's Kano and Kaduna corridors where temperature-assured logistics remain underpenetrated outside Lagos. Deploy mobile-money-integrated leasing for 50-500 liter solar cold boxes targeting smallholder aggregators, leveraging cooperative procurement platforms to bypass distributor markups. For Investors and Strategic Acquirers: Kenya's Rural Electrification Agency harmonizing quality standards with Nigeria's under ECOWAS-EAC technical regulations is the leading indicator that multi-country deployment capabilities will command acquisition premiums. Target thermal storage specialists with proprietary ice-battery configurations and established African service networks, watching for BIS certification acceleration in India as signal that domestic manufacturing scale players are consolidating procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-ion sourcing insulates margins from Chinese cell price volatility for hybrid system assemblers. |
| Phase-Change Material Licensing | Proprietary thermal storage IP enables diesel generator elimination in Nigerian vaccine corridors. |
| Mobile-Money Platform Partnership | Pay-as-you-go financing integration unlocks smallholder access across West African agricultural markets. |
| WHO Prequalification Investment | International health procurement compliance commands 3-4x pricing premiums over agricultural deployments. |
| Cooperative Procurement Consolidation | 200-500 member farmer group negotiations compress capital costs 15-20% below spot market pricing. |
Study Parameters
Multi-period observation of solar PV panel pricing, battery cell supply contracts, and cold chain equipment procurement patterns anchored the trend analysis, supplemented by interviews with cold room equipment manufacturers, agricultural cooperative procurement managers, pharmaceutical distribution executives, and rural electrification agency officials. Secondary validation drew from India's BIS certification databases, Kenya's Energy Regulatory Authority filings, Nigeria's Rural Electrification Agency reports, and WHO prequalification registries. Bottom-up aggregation of country-level deployment data triangulated against top-down market sizing from solar PV manufacturing disclosures and cold chain investment flows.
Input-output matrices mapped photovoltaic generation capacity, thermal storage configurations, and end-use vertical demand across product type, technology architecture, capacity scale, and geographic deployment clusters. Segmentation modeling incorporated freezer versus refrigerator formats, hybrid versus direct-drive systems, smallholder versus pharmaceutical end-use patterns, and state-level agricultural belt concentration. CAGRs were derived from installed base trajectory analysis and capital expenditure pipeline tracking, with lithium-ion cost curves and refrigerant phase-down schedules as primary forecast sensitivities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Kigali Amendment refrigerant restrictions, ECOWAS-EAC regulatory harmonization pace, and Chinese battery supply chain resilience. Forecasts reflect documented assumptions regarding PLI scheme extension, mobile-money platform penetration rates, and WHO prequalification timeline acceleration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Cold Trap Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Heat Pump (>100°C) Market