
 Electric Radiators Market | 2026-2036
Electric Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Radiators Market Analysis
Software-defined energy management is restructuring how electric radiator vendors monetize hardware. Subscription-based heating optimization platforms now accompany core unit sales, shifting revenue toward recurring models. Glen Dimplex leverages its IoT infrastructure to anchor this transition across European installations. Rointe competes through proprietary control ecosystems that extend customer lifetime value beyond the initial hardware purchase.
Electric radiators convert electrical energy into thermal output through resistive heating elements, ceramic plates, or infrared panels, typically operating at voltages between 220-240V with output ratings from 400W to 2500W depending on space requirements. These units serve residential, commercial, and industrial environments where centralized boiler systems prove impractical or where decarbonization targets require fossil-fuel displacement. Panel and infrared product types dominate premium positioning due to faster response times and wall-mount flexibility, while oil-filled units sustain volume leadership in cost-sensitive residential retrofits. Smart technology integration commands widening margin pools as programmable and hybrid control systems displace manual thermostatic offerings across new construction specifications.
The EU Ecodesign Directive and F-Gas Regulation collectively mandate minimum efficiency thresholds and accelerate phase-out schedules for gas-dependent heating across member states. CE marking requirements under the MDR framework govern electrical safety compliance for residential deployment, while national building codes in Germany, France, and Italy specify permissible energy consumption limits for space heating appliances. Stakeholders must monitor how pending revisions to the EU Green Deal building performance standards reshape product certification pathways and installation eligibility criteria.
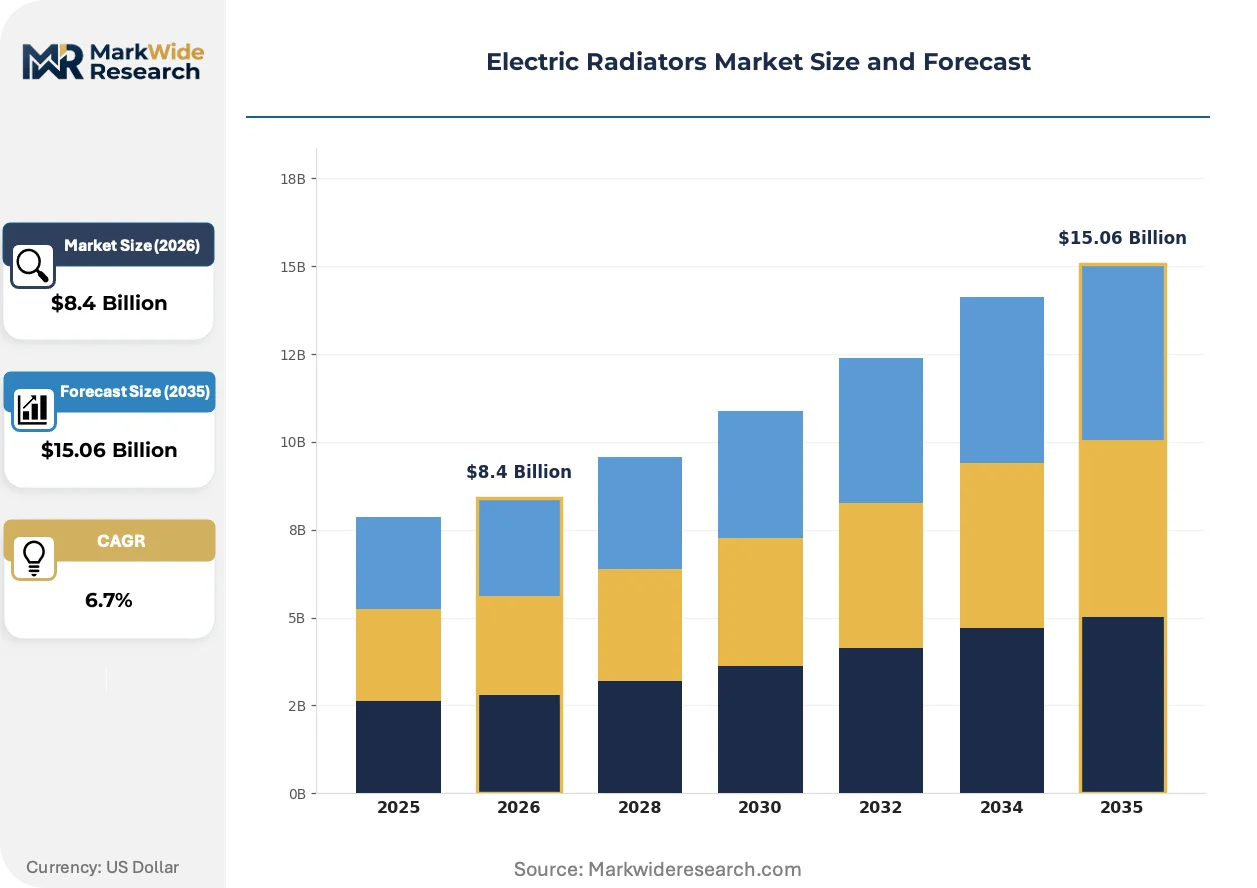
Market Dynamics
EU Ecodesign regulations and the F-Gas Regulation are systematically dismantling fossil-fuel heating alternatives across member states, forcing residential and commercial building owners toward electric radiator retrofits. This regulatory compression is accelerating replacement cycles in aging European housing stock while reshaping vendor revenue models toward software-defined energy management subscriptions.
Growth Catalysts
- Electrification mandates:The EU Green Deal building performance standards are tightening installation eligibility criteria for gas-dependent systems across Germany, France, and Italy.
- Residential retrofit demand:Aging housing stock in the United Kingdom requires immediate heating system replacement as boiler phase-out deadlines approach.
- Smart control integration:Programmable and hybrid control systems are displacing manual thermostatic offerings in new construction specifications.
Market Restraints
- Electricity price volatility:Input cost fluctuations in European wholesale electricity markets compress operating cost advantages versus gas alternatives.
- Ceramic element supply concentration:Sourcing of high-grade resistive heating materials clusters in East Asian manufacturing hubs, exposing vendors to logistics friction.
- Grid capacity constraints:Local distribution network limitations in rural French and German municipalities restrict simultaneous multi-unit deployment.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway present whitespace for panel radiator adoption as district heating networks face decarbonization pressure.
- Commercial building automation convergence:Integration of infrared panels with BACnet and Modbus protocols opens BMS-connected specification channels.
- France's MaPrimeRénov incentive:This national renovation subsidy scheme is expanding eligibility to electric heating replacements in multi-family housing.
Industry Challenges
- CE marking timeline compression:Pending MDR framework revisions are extending electrical safety certification pathways for connected radiator models.
- Legacy hydronic system integration:Retrofit installers face complexity marrying electric units with existing wet radiator pipework in British Victorian housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Radiators Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection, Infrared, Oil-Filled, Panel Application: Residential, Commercial, Industrial, Modular Technology: Smart, Manual, Programmable, Hybrid Size: Small, Medium, Large, Extra Large |
| Companies Covered | Rointe, ELNUR, IRSAP S.p.A., Glen Dimplex, Zehnder Group, Haverland, Stelrad, De’Longhi, Ferroli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Radiators Market Emerging Trajectories
Software-defined thermal management is unifying hardware sales with recurring revenue streams across European electric heating markets. Vendors now embed IoT infrastructure directly into panel and infrared units, enabling remote optimization and predictive maintenance services.
Machine learning algorithms embedded in ceramic plate controllers are unifying temperature modulation with occupancy detection and weather forecasting. Residential developers in the Netherlands and Belgium are specifying these systems at accelerating rates. The technology is unifying hardware margins with subscription-based heating optimization platforms that extend customer lifetime value beyond initial purchase.
The EU F-Gas Regulation is accelerating phase-out schedules for hydrofluorocarbon-dependent heat pump alternatives, redirecting specification toward electric resistance heating in smaller residential units. Building code revisions in Germany's KfW efficiency standards now explicitly favor direct electric heating in buildings below specific energy demand thresholds. Multi-family housing developers in Berlin and Hamburg are responding by standardizing infrared panel specifications in new construction.
Facility managers in British commercial real estate are consolidating heating procurement under integrated energy service contracts rather than capital equipment purchases. Landlord-tenant arrangements in London office retrofits are shifting toward all-inclusive utility models that bundle electric radiator operation with maintenance. This pattern is most visible in Grade B office conversions where capital constraints favor operational expenditure structures over upfront hardware investment.
Electric Radiators Market Segmentation
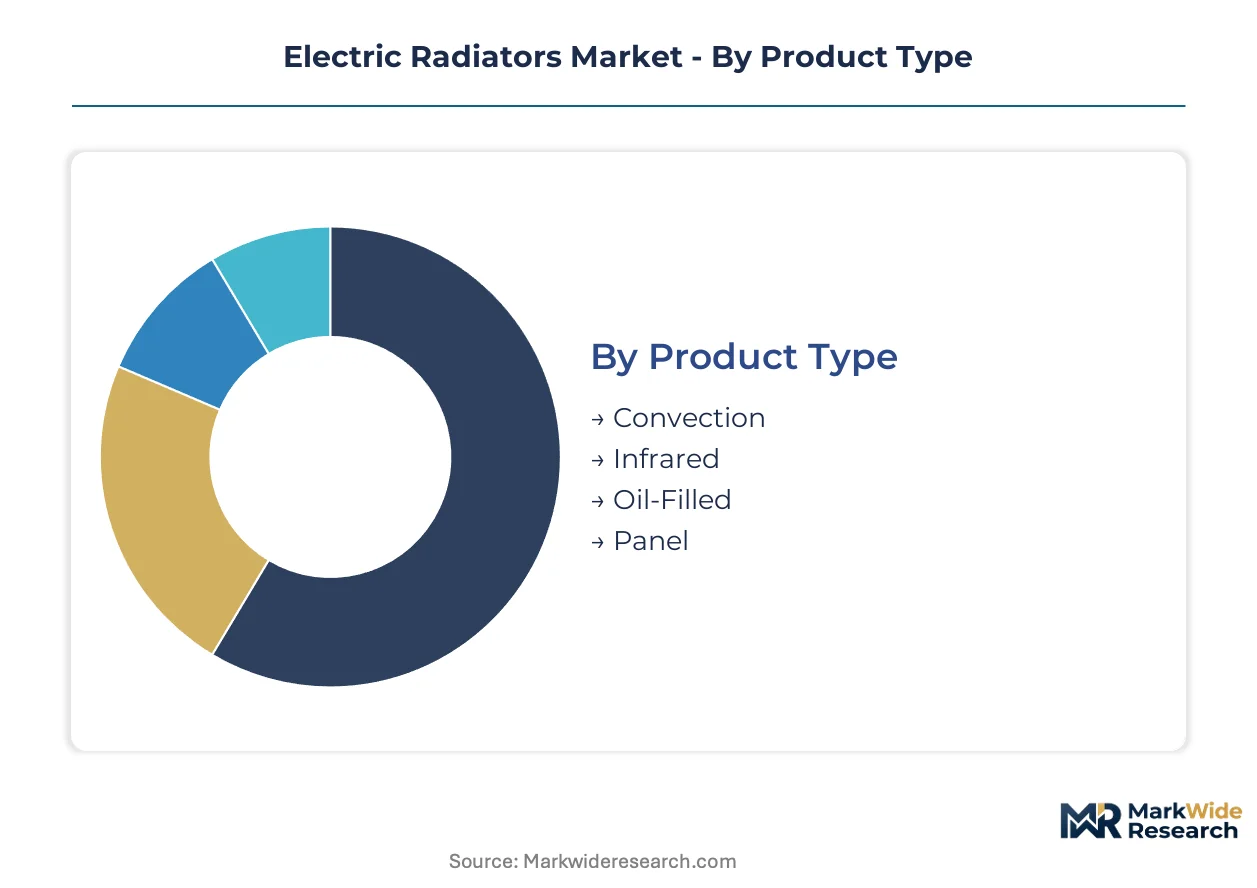
Segmentation in the Electric Radiators Market reveals how product architecture, control sophistication, and installation context determine margin capture. Vendors must align R&D investment with the specific thermal output mechanisms and building integration requirements that dominate each category.
Product Type:
Volume leadership sits with convection and oil-filled units, while infrared and panel formats command premium positioning through faster thermal response and architectural flexibility.
- Convection:These units heat air through resistive elements and natural circulation, typically wall-mounted or freestanding. Demand concentrates in German and British social housing retrofits where capital cost minimization overrides efficiency optimization. The EU Ecodesign Directive's minimum efficiency thresholds are forcing ceramic element upgrades across budget installations.
- Infrared:Radiant heat emission through carbon fiber or quartz elements delivers instantaneous warmth without air circulation. French multi-family developers in Paris and Lyon are specifying these systems under MaPrimeRénov subsidy eligibility, prioritizing wall-mount flexibility in space-constrained apartments.
- Oil-Filled:Thermal mass from diathermic oil extends heat release after power interruption. Italian residential replacements favor this format for perceived safety in aging wiring infrastructure.
- Panel:Flat-profile aluminum construction enables discreet integration with contemporary interiors. Dutch new construction specifications are accelerating adoption of connected panel systems with embedded IoT controllers.
Mature deployment sits with oil-filled radiators in cost-sensitive retrofits. Newer deployment is concentrated in infrared panels as electrification mandates tighten across premium residential segments.
Application:
Residential retrofits dominate unit volume, while commercial and modular applications are expanding most quickly through energy service contract structures.
- Residential:Single-family and multi-family heating replacements across aging European housing stock. British Victorian-era properties require specialized retrofit adapters to marry electric units with legacy wet radiator pipework.
- Commercial:Office, retail, and hospitality space heating where centralized boiler systems prove impractical. London Grade B office conversions are shifting toward all-inclusive utility models that bundle electric radiator operation with maintenance.
- Industrial:Supplementary zone heating in warehouses, workshops, and manufacturing facilities with intermittent occupancy patterns. German Mittelstand manufacturing facilities favor high-output convection units for rapid thermal recovery.
- Modular:Prefabricated building units and temporary structures requiring rapid deployment heating solutions. Swedish construction site regulations are mandating electric heating for environmental compliance in remote locations.
Residential applications anchor current installed base. Commercial deployments are gaining share fastest through landlord-tenant arrangement restructuring.
Technology:
Control sophistication determines margin stratification, with smart and programmable systems displacing manual thermostatic offerings in new construction specifications.
- Smart:IoT-enabled units with machine learning algorithms unifying temperature modulation, occupancy detection, and weather forecasting. Belgian residential developers are specifying these systems at accelerating rates to meet KfW-aligned efficiency standards.
- Manual:Basic thermostatic control without connectivity or scheduling capability. Remains prevalent in Italian rental properties where tenant turnover discourages technology investment.
- Programmable:Time-based temperature scheduling without remote connectivity or learning functions. French social housing operators favor this mid-tier option for balance of efficiency and capital constraint.
- Hybrid:Combined local and remote control with optional cloud connectivity upgrade paths. German building automation integrators are specifying hybrid systems to preserve future connectivity without immediate infrastructure commitment.
Manual controls dominate legacy installed base. Smart technology deployments are climbing the fastest as software-defined thermal management restructures vendor revenue models toward recurring optimization subscriptions.
Size:
Physical dimensions correlate directly with thermal output ratings and installation context, from supplementary zone heating to whole-room primary systems.
- Small:Units rated 400W-800W for bathrooms, hallways, and supplementary zone heating. British conservatory retrofits favor compact infrared panels for discrete wall placement.
- Medium:1000W-1500W output for standard residential rooms and small commercial spaces. German EnerPHit renovation standards specify medium panel radiators for balanced load distribution.
- Large:2000W-2500W capacity for open-plan living areas, retail floors, and industrial workshops. French commercial real estate specifications cluster in this range for cost-optimized coverage.
- Extra Large:Multi-element systems exceeding 2500W for atrium spaces, warehouses, and high-ceiling industrial environments. Nordic district heating transition projects are piloting extra-large infrared arrays for agricultural and logistics facilities.
Medium and large formats anchor replacement cycles in residential retrofits. Extra-large systems represent the steepest expansion trajectory as industrial electrification mandates extend beyond building heating into process applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian ceramic component foundries, while European markets absorb the majority of finished electric radiator output. This production-consumption divide shapes vendor supply chain configurations and margin structures across the forecast window.
Germany
KfW efficiency standards now explicitly favor direct electric heating in buildings below specific energy demand thresholds. Berlin and Hamburg developers are standardizing infrared panel specifications in new multi-family construction. The EU Green Deal building performance standards are tightening installation eligibility criteria for gas-dependent systems nationwide.
France
MaPrimeRénov subsidy expansion is accelerating electric heating replacements in multi-family housing across Paris and Lyon. The F-Gas Regulation is accelerating phase-out schedules for hydrofluorocarbon-dependent heat pump alternatives. French commercial real estate specifications cluster in large-format units for cost-optimized coverage of retail floors.
United Kingdom
Boiler phase-out deadlines are forcing immediate heating system replacement in aging Victorian-era housing stock. British conservatory retrofits favor compact infrared panels for discrete wall placement. London Grade B office conversions are shifting toward all-inclusive utility models bundling electric radiator operation with maintenance.
Italy
Residential replacements favor oil-filled formats for perceived safety in aging wiring infrastructure. National building codes specify permissible energy consumption limits for space heating appliances. Milan and Rome social housing operators favor programmable mid-tier options balancing efficiency against capital constraints.
Netherlands
Belgian and Dutch residential developers are specifying machine-learning-enabled smart systems at accelerating rates. CE marking requirements under the MDR framework govern electrical safety compliance for connected radiator models. Rotterdam and Amsterdam new construction specifications are accelerating adoption of connected panel systems with embedded IoT controllers.
Electric Radiators Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct manufacturing configurations. The vendor landscape organizes around three strategic archetypes: integrated heating conglomerates with captive ceramic foundries, specialized panel fabricators sourcing resistive elements externally, and software-native entrants monetizing thermal optimization subscriptions. Consolidation pressure is intensifying as EU Ecodesign regulations force ceramic element upgrades across budget installations. Dominant competitive moves include strategic partnerships for IoT platform integration and geographic expansion into underpenetrated Nordic markets.
Within the integrated conglomerate tier, Glen Dimplex anchors software-defined thermal management transitions through embedded IoT infrastructure across European installations. Rointe occupies a position exemplifying proprietary control ecosystem specialization that extends customer lifetime value beyond initial hardware purchase. Zehnder Group represents the architectural-integration archetype, leveraging flat-profile aluminum construction expertise to capture premium positioning in Dutch and Belgian new construction specifications.
| Leading Market Players |
|---|
| Rointe |
| ELNUR |
| IRSAP S.p.A. |
| Glen Dimplex |
| Zehnder Group |
| Haverland |
| Stelrad |
| De’Longhi |
| Ferroli |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign efficiency mandates and F-Gas Regulation phase-outs are forcing ceramic element upgrades across budget electric radiator installations, compelling East Asian foundries to retool production lines and European vendors to absorb input cost volatility through tiered margin structures.
Pricing Analysis
Margin tightening in economy-tier convection units reflects ceramic element sourcing bottlenecks from concentrated East Asian supply. Three-tier pricing structure across premium smart-connected, standard programmable, and economy manual systems stratifies by control sophistication and CE marking tier. Price differentiation hinges on IoT integration depth and after-sales service bundling. Social housing operators in Italy exhibit highest price sensitivity, while Dutch commercial developers prioritize efficiency certification over upfront cost.
Supply Chain Analysis
Direct-to-installer channels handle residential retrofit demand across Germany, France, and the United Kingdom, while distributor networks serve commercial specification markets. Manufacturing of resistive heating elements concentrates in China, South Korea, and Japan, with aluminum panel fabrication anchored in Germany and the Netherlands. Ceramic plate controllers and carbon fiber infrared elements feed from East Asian electronics clusters. Single-source vulnerability in high-grade resistive alloys exposes vendors to logistics friction. Distribution runs through HVAC wholesalers, electrical contractors, and building automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric radiator markets are becoming a vertical-integration race where captive control over ceramic element supply and embedded IoT software stacks determine margin capture.
For Market Incumbents: Lock in ceramic foundry partnerships or backward integration into resistive element production to defend against East Asian supply concentration. Acquire machine-learning control specialists to anchor subscription revenue streams before software-native entrants capture heating optimization platforms. For New Entrants and Emerging Players: Launch via energy service contract structures in London Grade B office conversions and French MaPrimeRénov-subsidized multi-family housing. Target underpenetrated Nordic district heating transition markets with extra-large infrared arrays for agricultural facilities. For Investors and Strategic Acquirers: The window for entry favors panel fabricators with proprietary aluminum construction expertise and embedded IoT infrastructure. Watch for CE marking timeline compression under pending MDR revisions as inflection indicator for regulatory compliance moats.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Foundry Backward Integration | Captive resistive element supply insulates margin from East Asian logistics friction. |
| IoT Platform Acquisition | Machine-learning control stacks enable recurring subscription revenue beyond hardware sales. |
| Nordic Market Expansion | Swedish and Norwegian district heating decarbonization creates whitespace for panel radiator adoption. |
| CE Marking Pre-Compliance Investment | Early MDR framework alignment secures certification pathways before timeline compression. |
| Energy Service Contract Launch | Operational expenditure models match landlord-tenant restructuring in British commercial real estate. |
Methodological Framework
Independent corroboration across product engineering directors at heating manufacturers, procurement leads at German and French social housing operators, building automation integrators in the Netherlands, and regulatory affairs specialists at EU notified bodies underwrites the qualitative findings. Secondary validation draws from EU Ecodesign Directive implementation reports, F-Gas Regulation phase-out schedules, KfW efficiency standard documentation, and national building code revisions across member states. Bottom-up unit shipment analysis triangulates with top-down energy demand modeling.
Historical reference periods anchor the projection horizon through verified replacement cycle data and retrofit installation rates. Segmentation modeling spans product architecture, control technology tier, application context, and thermal output rating. CAGRs derive from regression analysis against electrification mandate timelines and subsidy program trajectories. Forecast inputs incorporate EU Green Deal building performance standard revisions and MaPrimeRénov eligibility expansion patterns.
Electricity price volatility, ceramic element supply disruption, and grid capacity constraint enforcement are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory phase-out schedules and subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market