
 Air Cooling Corona Discharge Ozone Generator Market | 2026-2036
Air Cooling Corona Discharge Ozone Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cooling Corona Discharge Ozone Generator Market Analytics
China is tilting toward expanded domestic production of corona discharge ozone generators to serve its municipal water upgrade programs. Mitsubishi Electric Corporation leverages its plasma technology heritage to anchor premium industrial system sales across East Asian utilities. De Nora Group sustains electrode and cell manufacturing scale that differentiates its supply reliability for large desalination and wastewater contracts. Faraday Ozone competes on cost-engineered portable and stationary units for mid-sized commercial buyers in South Asia and the Middle East.
Air cooling corona discharge ozone generators produce ozone gas by applying high-voltage alternating current across a dielectric gap with ambient air as the feed gas, typically achieving concentrations of one to three percent by weight with operating temperatures managed through forced air convection rather than liquid cooling loops. These systems serve primarily as oxidation and disinfection tools in water treatment plants, food processing facilities, and air handling installations where capital simplicity and maintenance access outweigh the efficiency advantages of oxygen-fed alternatives. Industrial Solutions and Stationary Systems command the dominant share of value given their integration into continuous municipal and manufacturing processes, while Portable Units represent the fastest-expanding category as field remediation and temporary disinfection applications multiply across healthcare and disaster response contexts. Water Treatment applications concentrate the largest installed base and replacement revenue pool, though Surface Disinfection is gaining structural importance in pharmaceutical cleanroom and hospital settings post-pandemic.
The EPA regulates ozone generator emissions and application concentrations under the Safe Drinking Water Act and Clean Air Act, while the EU F-Gas Regulation and Drinking Water Directive shape product design and deployment standards across European member states. China's MEE enforces effluent discharge standards that directly mandate advanced oxidation for specific industrial categories, creating compliance-driven procurement cycles. Stakeholders must monitor evolving national ozone exposure limits and cooling efficiency benchmarks, as these will determine which air-cooled architectures retain market access against emerging plasma and UV-hybrid alternatives.
Market Dynamics
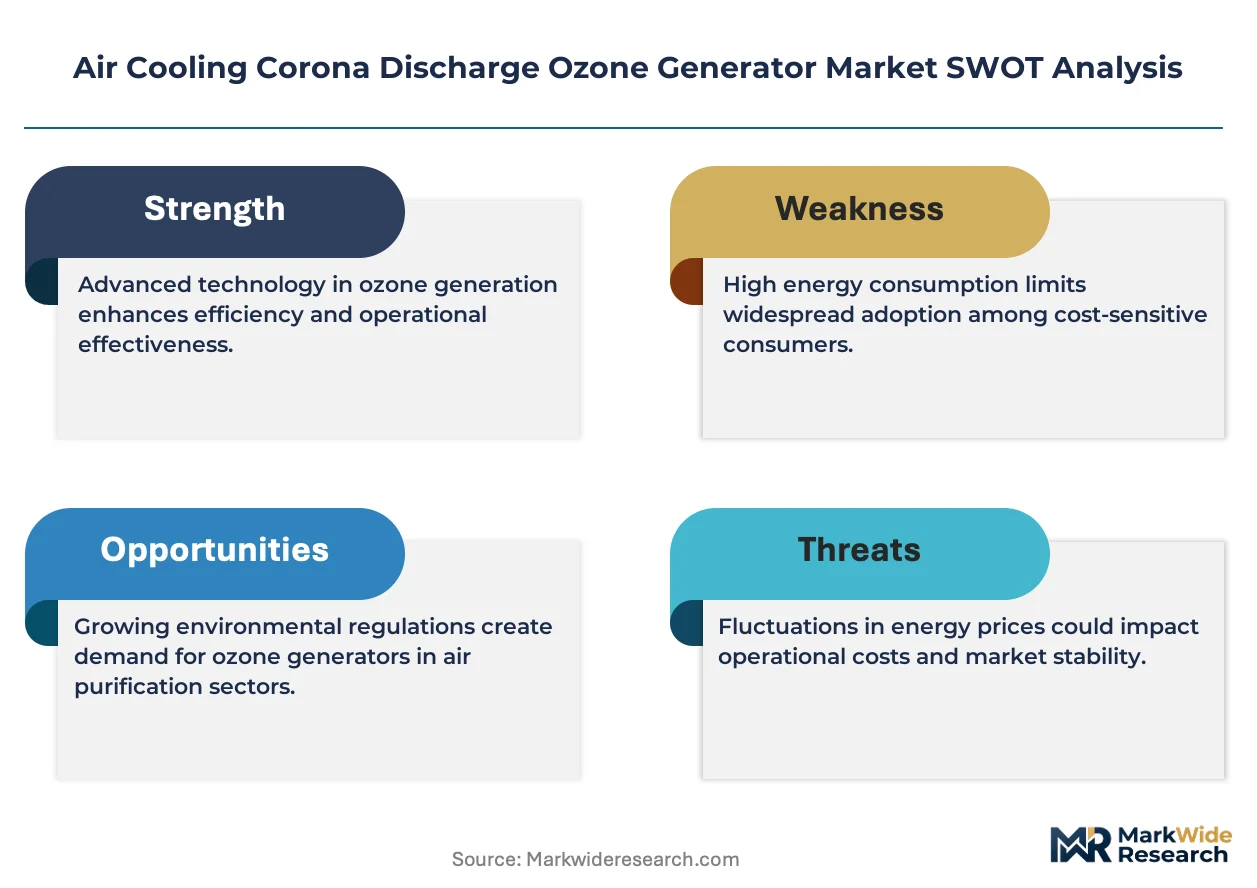
Air cooling corona discharge ozone generators face intensifying pressure from oxygen-fed alternatives as energy costs rise and EPA ozone concentration limits tighten for municipal water treatment facilities. The technology's capital simplicity advantage erodes where efficiency mandates dominate procurement criteria.
Growth Catalysts
- EPA Safe Drinking Water Act Amendments:Municipal utilities in the United States must upgrade disinfection infrastructure, accelerating replacement cycles for aging chlorination systems with ozone-based oxidation.
- China's MEE Industrial Effluent Standards:Textile and pharmaceutical manufacturing corridors face mandatory advanced oxidation requirements, concentrating procurement of stationary industrial units.
- Plasma electrode durability improvements:Dielectric materials with extended service intervals reduce maintenance downtime, improving total cost of ownership calculations for continuous-process buyers.
Market Restraints
- Oxygen-fed system cost compression:PSA oxygen concentrator prices declined substantially, narrowing the capital gap with air-cooled alternatives and threatening displacement in efficiency-sensitive segments.
- Electrode supply concentration:High-purity alumina dielectric substrates source predominantly from East Asian ceramic manufacturers, exposing procurement to geopolitical friction and shipping volatility.
- REACH substance restrictions:ECHA candidate list reviews threaten certain electrode coatings and cooling fan materials, forcing reformulation cycles that delay EU market access.
Strategic Opportunities
- India's Ganga River Basin municipal upgrades:Central government funding for 100+ sewage treatment plants creates procurement windows for mid-capacity stationary systems in secondary cities.
- UV-ozone hybrid integration:Combination systems addressing pharmaceutical cleanroom validation requirements command premium positioning in FDA-regulated manufacturing.
- Equipment-as-a-service models:Rental and performance-contract channels penetrate disaster response and temporary healthcare facilities where capital budgets are constrained.
Industry Challenges
- High-voltage power electronics specialization:Corona discharge system design requires rare expertise in resonant inverter topology and dielectric barrier physics, constraining engineering talent pools.
- Legacy SCADA integration complexity:Municipal water utilities operate decades-old distributed control architectures, forcing costly protocol bridging for ozone generator telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cooling Corona Discharge Ozone Generator Market |
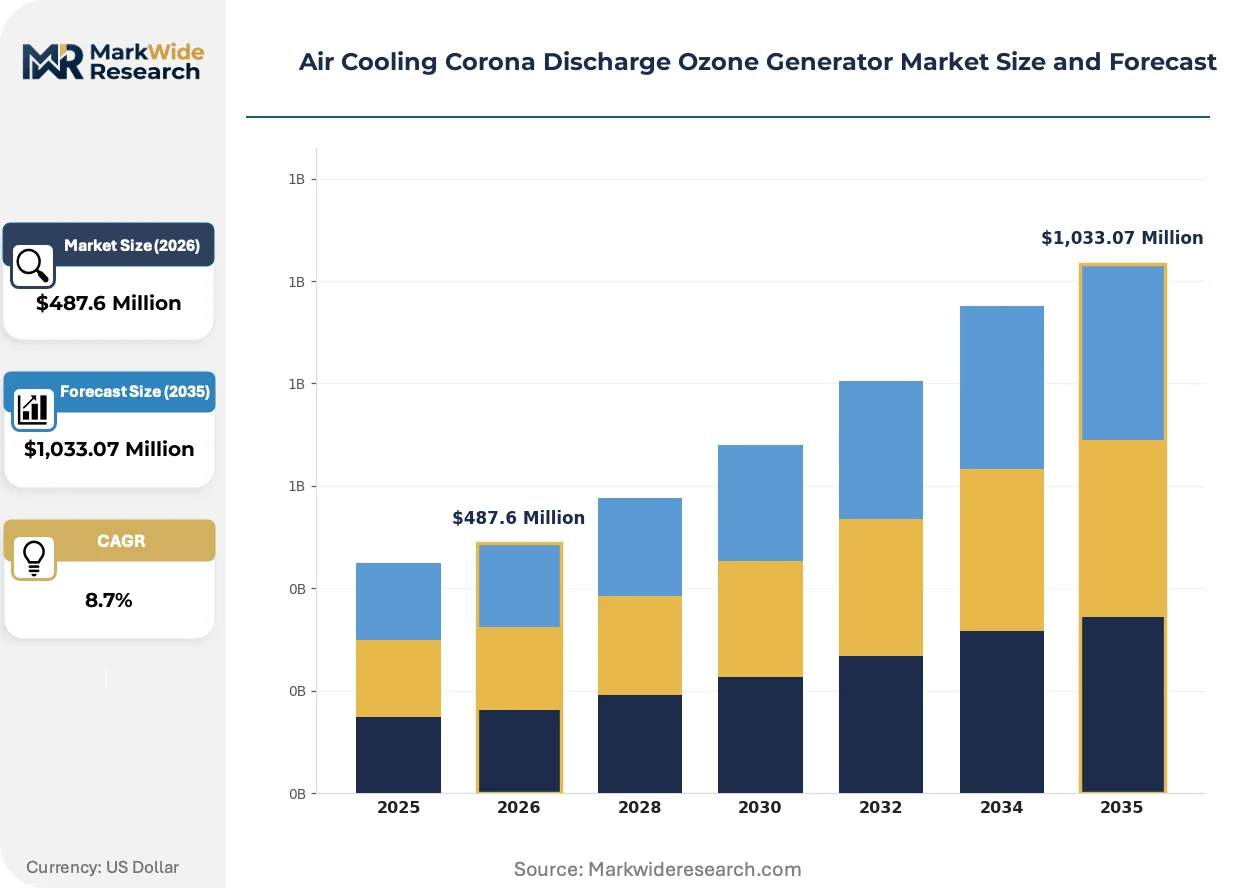
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Stationary Systems, Industrial Solutions, Residential Models Application: Water Treatment, Air Purification, Waste Management, Surface Disinfection End User: Municipal Facilities, Manufacturing Plants, Residential Customers, Healthcare Institutions Technology: Advanced Oxidation Process, Plasma Technology, Chemical Injection, Traditional Systems |
| Companies Covered | Mitsubishi Electric Corporation, SUEZ Water Technologies & Solutions, De Nora Group, Faraday Ozone, Chemtronics Technologies Pvt. Ltd., Eltech Ozone, Enaly Ozone Generator, Ozonetech Systems OTS AB, Oxidation Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cooling Corona Discharge Ozone Generator Market Evolving Landscape
Digital power control and ceramic dielectric advances are compressing efficiency gaps between air-cooled and oxygen-fed architectures. Equipment manufacturers must now differentiate through service integration and application-specific engineering rather than hardware specifications alone.
Silicon carbide MOSFET-based resonant inverters are rendering obsolete traditional IGBT power supplies in mid-capacity ozone generators. Pharmaceutical cleanroom operators in Germany and Switzerland adopted these systems first, seeking reduced electromagnetic interference for sensitive process controls. The technology is rendering obsolete established supplier relationships where incumbents lack wide-bandgap semiconductor design capabilities.
The EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants indirectly elevates air cooling's competitive position against liquid-cooled alternatives dependent on synthetic coolants. Industrial system designers face forced architectural pivots as conventional chiller-based cooling loops lose regulatory viability. Water treatment OEMs in France and Italy accelerated air-cooled platform development to preempt compliance-driven procurement exclusions.
Hospital infection control departments now specify ozone surface disinfection systems with validated cycle documentation rather than portable units sold through general medical distributors. The shift compresses margins for undifferentiated hardware vendors while elevating application engineering and regulatory submission capabilities. This pattern concentrates most visibly in tertiary care networks across the United States and United Kingdom post-pandemic capital refresh cycles.
Air Cooling Corona Discharge Ozone Generator Market Segmentation
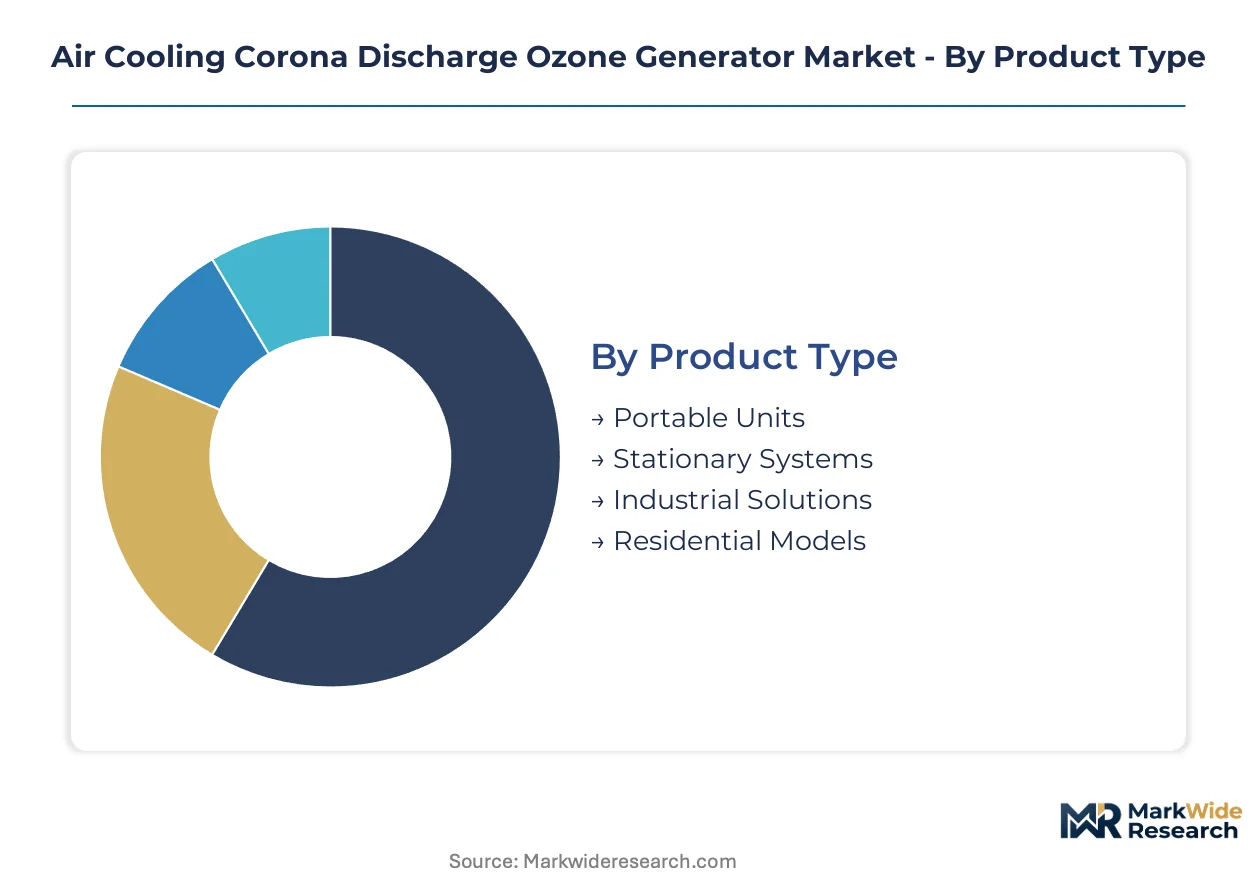
Product architecture and cooling methodology define competitive positioning in air-cooled corona discharge systems. Application-specific oxidation requirements and end-user procurement sophistication determine where manufacturers concentrate engineering investment and distribution resources.
Product Type:
Cost tier differentiation separates capital-intensive continuous-process installations from intermittent-use equipment and consumer-grade alternatives.
- Industrial Solutions:These systems integrate high-capacity corona cells with forced-air convection arrays rated for 24/7 municipal water treatment duty cycles. Procurement concentrates in Germany and the United States where EPA and EU Drinking Water Directive upgrades mandate ozone-based primary disinfection for large-scale facilities.
- Stationary Systems:Mid-capacity fixed installations serve manufacturing process water loops and commercial building air handling with dielectric barrier configurations optimized for 500-5000 gram/hour output ranges. China's industrial manufacturing corridors account for concentrated demand as MEE effluent standards tighten for textile and pharmaceutical categories.
- Portable Units:Field-deployable generators with compact air-cooled architectures address temporary disinfection, disaster response, and healthcare remediation where infrastructure is absent or compromised.
- Residential Models:Small-scale units target swimming pool sanitation and home air purification with simplified electrode configurations and reduced ozone output specifications.
Industrial Solutions commands the established base. The steepest expansion runs through Portable Units.
Application:
Functional use case determines oxidation load profiles, regulatory validation requirements, and replacement cycle timing.
- Water Treatment:Municipal and industrial process water systems deploy air-cooled generators for primary disinfection, iron/manganese oxidation, and taste/odor control with continuous-duty dielectric cell arrays. Germany's expanding Ruhr Valley treatment infrastructure and India's Ganga River Basin municipal upgrades concentrate replacement demand.
- Surface Disinfection:Validated ozone cycles replace chemical wipe-down protocols in pharmaceutical cleanrooms and hospital operating suites post-pandemic, requiring documented concentration-time profiles and electromagnetic interference shielding for sensitive equipment zones.
- Air Purification:HVAC-integrated systems address commercial building indoor air quality with intermittent ozone injection controlled by ambient concentration sensors.
- Waste Management:Leachate treatment and odor control applications in landfill and composting operations employ robust air-cooled architectures resistant to corrosive off-gas exposure.
Water Treatment anchors installed value. Surface Disinfection is climbing the fastest as validation requirements professionalize procurement.
End User:
Customer type dictates specification complexity, service contract attachment rates, and channel access requirements.
- Municipal Facilities:Water and wastewater utilities operate under Safe Drinking Water Act and EU Drinking Water Directive compliance frameworks with decade-long capital planning horizons and SCADA integration mandates.
- Healthcare Institutions:Hospital infection control departments specify validated surface disinfection systems with cycle documentation rather than portable hardware, elevating application engineering capabilities over distributor relationships.
- Manufacturing Plants:Food processing, pharmaceutical, and electronics fabrication facilities integrate ozone into process water loops and cleanroom protocols with FDA and EMA quality system requirements.
- Residential Customers:Pool owners and home air quality purchasers drive low-specification volume through retail and e-commerce channels with minimal service attachment.
Municipal Facilities concentrate replacement revenue. Healthcare Institutions are gaining share fastest as validation standards displace undifferentiated hardware.
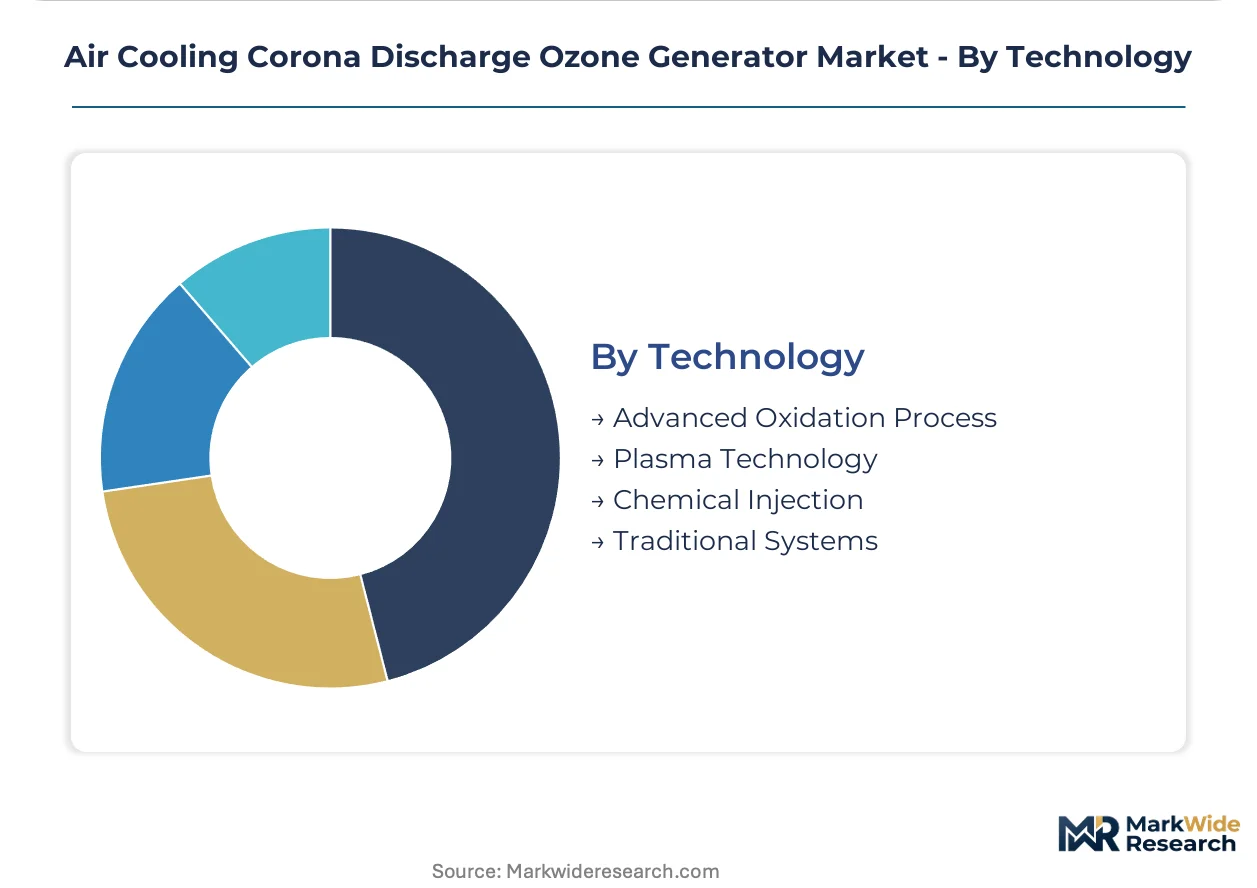
Technology:
Process integration methodology distinguishes standalone oxidation from combined treatment architectures and legacy chemical alternatives.
- Advanced Oxidation Process:Combined ozone-UV or ozone-peroxide systems generate hydroxyl radicals for refractory contaminant destruction in pharmaceutical manufacturing effluent and emerging contaminant removal.
- Plasma Technology:Dielectric barrier discharge configurations with silicon carbide MOSFET power electronics achieve improved efficiency and reduced electromagnetic interference for cleanroom-sensitive installations in Switzerland and Germany.
- Traditional Systems:Established corona discharge architectures with IGBT power supplies and alumina dielectric substrates serve cost-sensitive applications where efficiency gains do not justify premium positioning.
- Chemical Injection:Hybrid configurations combining ozone with coagulant or pH adjustment chemicals for integrated treatment trains in industrial wastewater applications.
Traditional Systems retains the largest installed base. Plasma Technology is expanding most quickly as wide-bandgap semiconductors render legacy power electronics obsolete.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safe Drinking Water Act amendments anchor municipal procurement cycles in the United States. Germany's Ruhr Valley treatment corridor and India's Ganga River Basin upgrades concentrate replacement demand for stationary industrial systems.
United States
Municipal utilities in the Great Lakes and Southwest regions replace aging chlorination infrastructure under tightening EPA ozone concentration limits. The Safe Drinking Water Act drives capital planning cycles toward ozone-based primary disinfection. California's Central Valley water districts and Texas municipal authorities concentrate procurement of mid-capacity air-cooled systems for taste and odor control.
Germany
Ruhr Valley water treatment facilities expand ozone oxidation capacity to meet EU Drinking Water Directive microbial standards. The F-Gas Regulation phasedown elevates air-cooled architectures against liquid-cooled alternatives dependent on synthetic refrigerants. Bavarian and North Rhine-Westphalia utilities anchor premium industrial system demand with decade-long service contract attachments.
China
Textile and pharmaceutical manufacturing corridors in Jiangsu and Zhejiang provinces face mandatory advanced oxidation under MEE industrial effluent standards. Domestic production of corona discharge cells accelerates to serve municipal water upgrade programs in the Yangtze River Delta. Shanghai and Suzhou industrial zones concentrate procurement of stationary systems for process water loops.
India
Central government funding for 100-plus sewage treatment plants in the Ganga River Basin creates procurement windows for mid-capacity stationary systems. BIS water quality standards tighten disinfection requirements for secondary cities. Gujarat and Maharashtra industrial corridors drive demand for cost-engineered units in textile dyeing and pharmaceutical effluent applications.
Switzerland
Pharmaceutical cleanroom operators in Basel and Geneva adopt silicon carbide MOSFET-based systems for reduced electromagnetic interference. Swissmedic validation requirements professionalize procurement toward documented cycle performance rather than hardware specifications alone. The country's precision manufacturing heritage anchors premium positioning for plasma technology deployments.
Air Cooling Corona Discharge Ozone Generator Market Competitive Landscape
Capability concentration sits with plasma technology specialists and dielectric material fabricators; scale advantage sits with diversified industrial conglomerates and regional system integrators. The vendor base organizes into three tiers: premium technology licensors with semiconductor power electronics expertise, mid-market fabricators competing on total cost of ownership, and cost-optimized assemblers serving price-sensitive procurement. Dominant competitive moves include strategic partnerships between electrode suppliers and power electronics designers, plus geographic expansion through equipment-as-a-service rental channels.
Within the premium technology tier, Mitsubishi Electric Corporation and De Nora Group exemplify divergent strategic positions. Mitsubishi Electric, a Japanese diversified industrial conglomerate, occupies a position anchored in plasma technology heritage and wide-bandgap semiconductor capabilities. De Nora Group, an Italian electrochemical specialist, represents electrode and cell manufacturing scale that differentiates supply reliability for large infrastructure contracts. Faraday Ozone, an Indian company, sits within the cost-engineered tier competing on portable and stationary unit accessibility for mid-sized commercial buyers in South Asia and the Middle East.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| SUEZ Water Technologies & Solutions |
| De Nora Group |
| Faraday Ozone |
| Chemtronics Technologies Pvt. Ltd. |
| Eltech Ozone |
| Enaly Ozone Generator |
| Ozonetech Systems OTS AB |
| Oxidation Technologies |
| Others |
Value Network & Pricing Analysis
Single-source dependency on East Asian alumina dielectric substrates compresses pricing tier spreads while forcing dual-sourcing investments among European and North American system integrators. This concentration dynamic simultaneously elevates premium pricing for supply-guaranteed contracts and erodes margins in cost-engineered segments where buyers tolerate longer lead times.
Pricing Analysis
Price spreads between German and Indian procurement markets exceed threefold for equivalent capacity ratings. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide MOSFET-equipped systems from IGBT-based alternatives and refurbished legacy units. Cost compression in mid-capacity stationary systems intensifies as Chinese domestic manufacturers expand output. Municipal utilities in Germany and Switzerland demonstrate lowest price sensitivity given decade-long service contract frameworks; mid-sized commercial buyers in India and Southeast Asia drive hardest bargain hunting.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electrode and dielectric substrate procurement. High-purity alumina ceramic manufacturing concentrates in China and Japan; resonant inverter power electronics fabrication centers on Taiwan and South Korea. The supply chain draws from rare-earth magnet suppliers for cooling fan assemblies and copper winding specialists for transformer components. Distribution runs through authorized system integrators in municipal water markets and direct OEM relationships in pharmaceutical cleanroom segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service platform economics are displacing transactional hardware sales as municipal utilities and disaster response agencies prioritize operational expenditure flexibility over capital ownership. Interoperability with legacy SCADA architectures and validated cycle documentation systems determines platform stickiness.
For Market Incumbents: Insulate premium positioning by securing captive supply agreements with Japanese alumina substrate specialists before REACH substance reviews restrict alternative coating materials. Accelerate silicon carbide MOSFET design capabilities to render obsolete IGBT-dependent competitors lacking wide-bandgap semiconductor expertise. Defend against oxygen-fed system displacement by embedding air-cooled generators into integrated advanced oxidation process trains with documented performance guarantees.
For New Entrants and Emerging Players: Pursue rental and performance-contract channels in India's Ganga River Basin municipal upgrades where capital budget constraints exclude established premium vendors. Target mid-capacity stationary system white space in secondary Chinese cities where domestic production gaps persist for validated pharmaceutical-grade installations. Lead with equipment-as-a-service go-to-market models that convert upfront hardware margins into recurring revenue streams with higher lifetime customer value.
For Investors and Strategic Acquirers: EPA Safe Drinking Water Act amendments and EU F-Gas Regulation phasedowns reshape the acquisition landscape toward air-cooled platform specialists with regulatory submission capabilities and service contract backlogs. Long-term viability hinges on exposure to compliance-driven replacement cycles rather than discretionary capital expenditure markets. Target acquisition candidates combining plasma electrode durability IP with established municipal utility relationships. Monitor silicon carbide MOSFET adoption rates in Swiss and German pharmaceutical installations as inflection indicator for technology obsolescence timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Substrate Manufacturing | Captive alumina ceramic supply secures margin protection against East Asian shipping volatility and REACH reformulation delays. |
| Silicon Carbide MOSFET Power Electronics Transition | Wide-bandgap semiconductor adoption renders IGBT-based competitors obsolete in electromagnetic interference-sensitive cleanroom deployments. |
| Equipment-as-a-Service Platform Launch | Rental models penetrate India's municipal upgrade programs and disaster response agencies with constrained capital budgets. |
| Validated Cycle Documentation System Development | FDA and Swissmedic-compliant performance logging elevates procurement positioning in tertiary care networks post-pandemic. |
| Legacy SCADA Protocol Bridging Investment | Integration compatibility with decades-old municipal control architectures removes deployment friction in US Great Lakes replacement cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, EU F-Gas Regulation implementation reports, and MEE effluent standard compliance filings. Primary interviews engaged municipal water utility planning officers, pharmaceutical cleanroom engineering directors, industrial ozone system procurement managers, and aftermarket service heads at regional system integrators. Secondary validation drew from customs trade data on alumina ceramic substrate flows, SEC 10-K disclosures from diversified industrial conglomerates, and BIS water quality standard draft notifications. Bottom-up capacity installation tracking triangulates against top-down expenditure estimates from central government funding announcements.
Forecast inputs include segmented modeling across product architecture, cooling methodology, application oxidation load profiles, and end-user procurement sophistication dimensions. The analytical framework projects value expansion across the analysis window by correlating regulatory amendment timelines with capital planning cycle phasing. CAGR derivation incorporates replacement demand elasticity for aging chlorination infrastructure, MEE-mandated advanced oxidation procurement deadlines, and plasma electrode durability improvement adoption curves. Industry-specific inputs capture F-Gas Regulation phasedown impacts on liquid-cooled competitive alternatives and silicon carbide MOSFET cost reduction trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers or oxygen-fed system specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Process Chillers Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Seawater Cooling System Market