
 Microchannel Heat Exchanger Market | 2026-2036
Microchannel Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Microchannel Heat Exchanger Market Analysis
Electric vehicle thermal management is hardening as the dominant demand vertical, displacing traditional internal-combustion cooling architectures. Denso Corporation leverages its captive supply of precision aluminum microchannel coils to anchor Japanese OEM relationships. MAHLE GmbH competes through R&D intensity in low-GWP refrigerant-compatible designs. Sanhua extends its manufacturing scale across Chinese EV battery pack cooling lines.
A microchannel heat exchanger is a compact thermal transfer device fabricated from aluminum or copper alloys, featuring hydraulic diameters below one millimeter and channel counts exceeding fifty per flat tube, designed to maximize surface-area-to-volume ratios for refrigerant-to-air or liquid-to-liquid heat rejection. The device serves primarily to reduce refrigerant charge volumes and improve coefficient-of-performance ratings in climate-control and industrial process systems. Liquid coolers lead product-type revenue pools due to datacenter and power-electronics cooling contracts, while heat pumps represent the fastest-growing application segment as building decarbonization mandates expand. Aluminum dominates material selection for cost-sensitive automotive and HVAC volumes, though copper microchannel designs sustain premium positioning in corrosive industrial process environments.
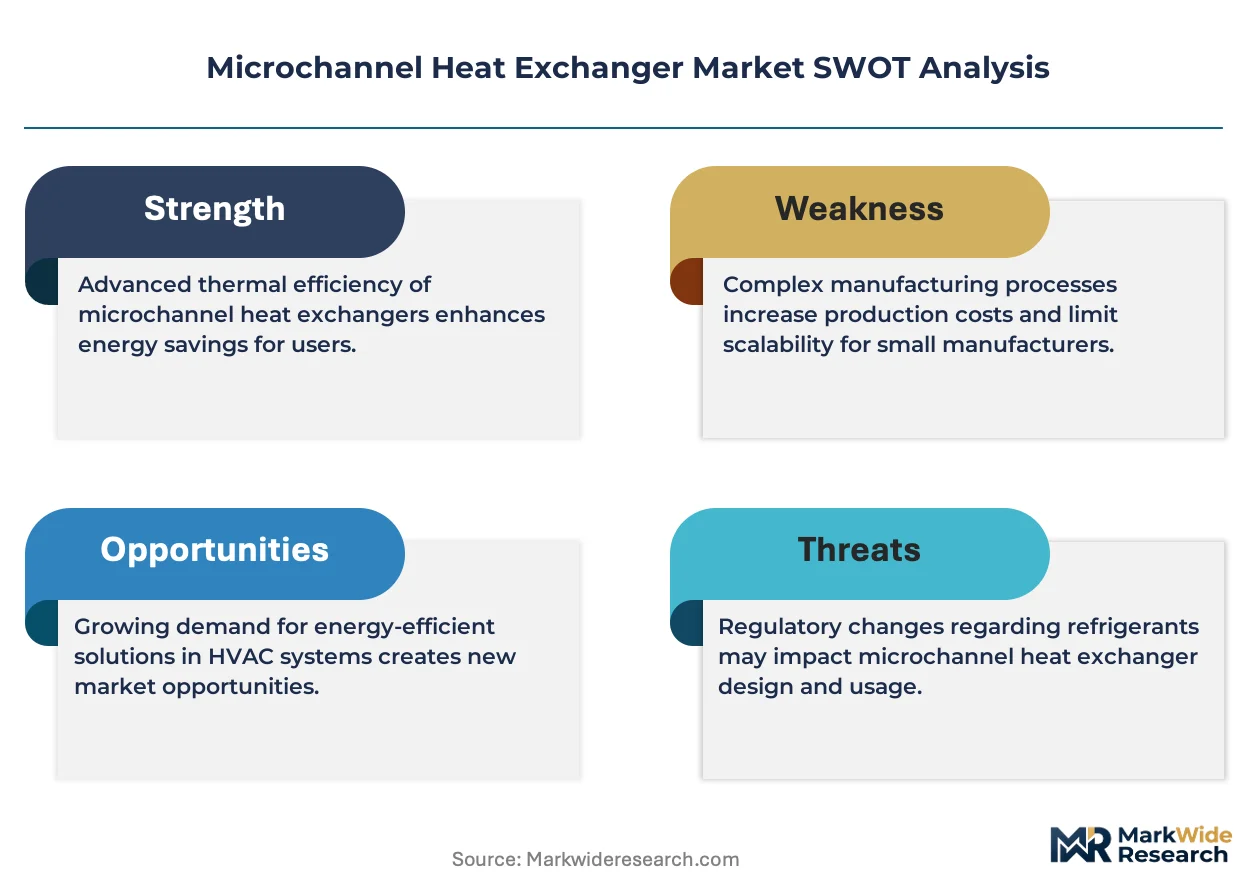
The EPA enforces refrigerant phase-down timelines under SNAP rules that directly shape product development cycles for North American suppliers. The EU F-Gas Regulation and Ecodesign directives mandate minimum seasonal efficiency thresholds, forcing redesigns of commercial refrigeration and residential heating architectures. China's GB standards and dual carbon goals accelerate domestic OEM adoption of high-efficiency microchannel coils. Stakeholders must monitor refrigerant chemistry transitions and regional certification lead times to avoid stranded inventory in evolving compliance environments.
Market Dynamics
The transition from internal-combustion engines to battery-electric powertrains is fundamentally restructuring thermal management architectures. This shift demands entirely new cooling circuit designs, refrigerant chemistries, and manufacturing competencies that favor microchannel geometries over traditional tube-and-fin constructions.
Growth Catalysts
- EPA SNAP refrigerant phase-down:The mandated transition to low-GWP alternatives requires heat exchangers with reduced internal volumes and enhanced corrosion resistance. Microchannel designs directly address both requirements.
- EV battery pack cooling:Lithium-ion cells demand precise temperature uniformity across large-format modules. Liquid-cooled microchannel cold plates have become the default architecture for premium battery electric vehicles.
- China's dual carbon policy framework:GB energy-efficiency standards for commercial HVAC equipment now specify minimum performance thresholds that only microchannel coils reliably achieve at competitive cost structures.
Market Restraints
- Aluminum price volatility:Raw material input costs for coil stock fluctuate with LME trading patterns, compressing margin predictability for contract manufacturers serving automotive OEMs.
- Brazing furnace concentration:Controlled atmosphere brazing capacity clusters in Germany, Japan, and select US industrial corridors, creating geographic supply risk for regional fabricators.
- Flammability constraints:A2L refrigerant classifications under ASHRAE safety standards impose design limitations on channel geometries and manifold configurations that increase engineering complexity.
Strategic Opportunities
- India automotive HVAC localization:The PLI scheme for advanced automotive components creates tariff-protected demand for domestic microchannel coil production serving Maruti Suzuki and Hyundai Motor India.
- Datacenter liquid cooling:Direct-to-chip thermal management for AI training clusters represents an emerging application segment with performance requirements distinct from automotive specifications.
- EU Ecodesign heat pump mandates:Seasonal performance factor regulations for residential heating equipment are accelerating specification of microchannel condensers across European HVAC supply chains.
Industry Challenges
- Multi-material joining expertise:The shift toward copper-aluminum hybrid designs for corrosive refrigerant environments requires specialized brazing process control that exceeds legacy workforce capabilities.
- Homologation timeline compression:OEM thermal system validation cycles now overlap with refrigerant chemistry transitions, forcing simultaneous redesign of fluid circuits and heat exchanger hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microchannel Heat Exchanger Market |
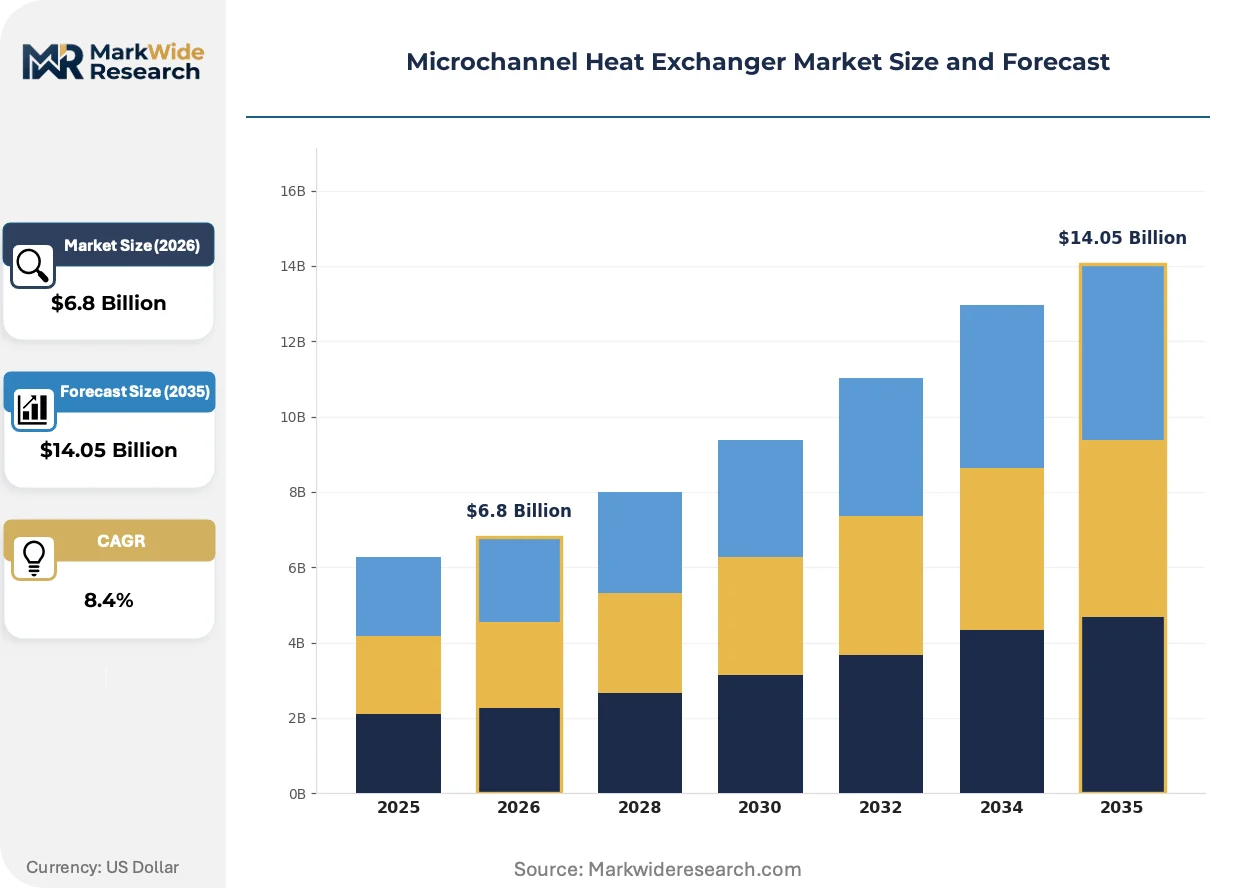
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coolers, Gas Coolers, Refrigeration Units, Heat Pumps Application: Automotive HVAC, Commercial Refrigeration, Industrial Processes, Residential Heating Material: Aluminum, Copper, Stainless Steel, Composite Materials End User: OEMs, Aftermarket Providers, HVAC Contractors, Industrial Manufacturers |
| Companies Covered | Danfoss, Sanhua, Modine Manufacturing Company, Kaltra, MAHLE GmbH, Hanon Systems, Johnson Controls, Denso Corporation, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microchannel Heat Exchanger Market Emerging Trajectories
Refrigerant chemistry transitions and electrification imperatives are converging to reshape heat exchanger design priorities. Manufacturers now optimize for reduced charge volume, multi-fluid compatibility, and manufacturing automation rather than incremental efficiency gains.
Additive manufacturing of aluminum manifold components is expanding into prototype and low-volume production workflows. Tier-1 suppliers serving Formula E and hypercar programs now print complex internal flow distributors that would require impossible machining operations. This capability is expanding into mainstream motorsport and limited-series production, compressing development cycles from months to weeks.
The EU F-Gas Regulation's stepped reduction in HFC quota allocations is forcing refrigerant portfolio consolidation across European HVAC manufacturers. Equipment OEMs now specify heat exchangers compatible with both R-32 and R-454B across single platform architectures. This regulatory pressure most acutely affects commercial refrigeration contractors in Germany and Italy, who face stranded inventory risk from misaligned component certification timelines.
Direct contracting between automotive OEMs and aluminum extruders is consolidating tier-2 supply relationships. Battery manufacturers now specify cold plate geometries and surface treatments directly, bypassing traditional thermal module integrators. This pattern is most visible in China, where CATL and BYD maintain approved supplier lists for microchannel tube stock that dictate downstream procurement decisions.
Microchannel Heat Exchanger Market Segmentation
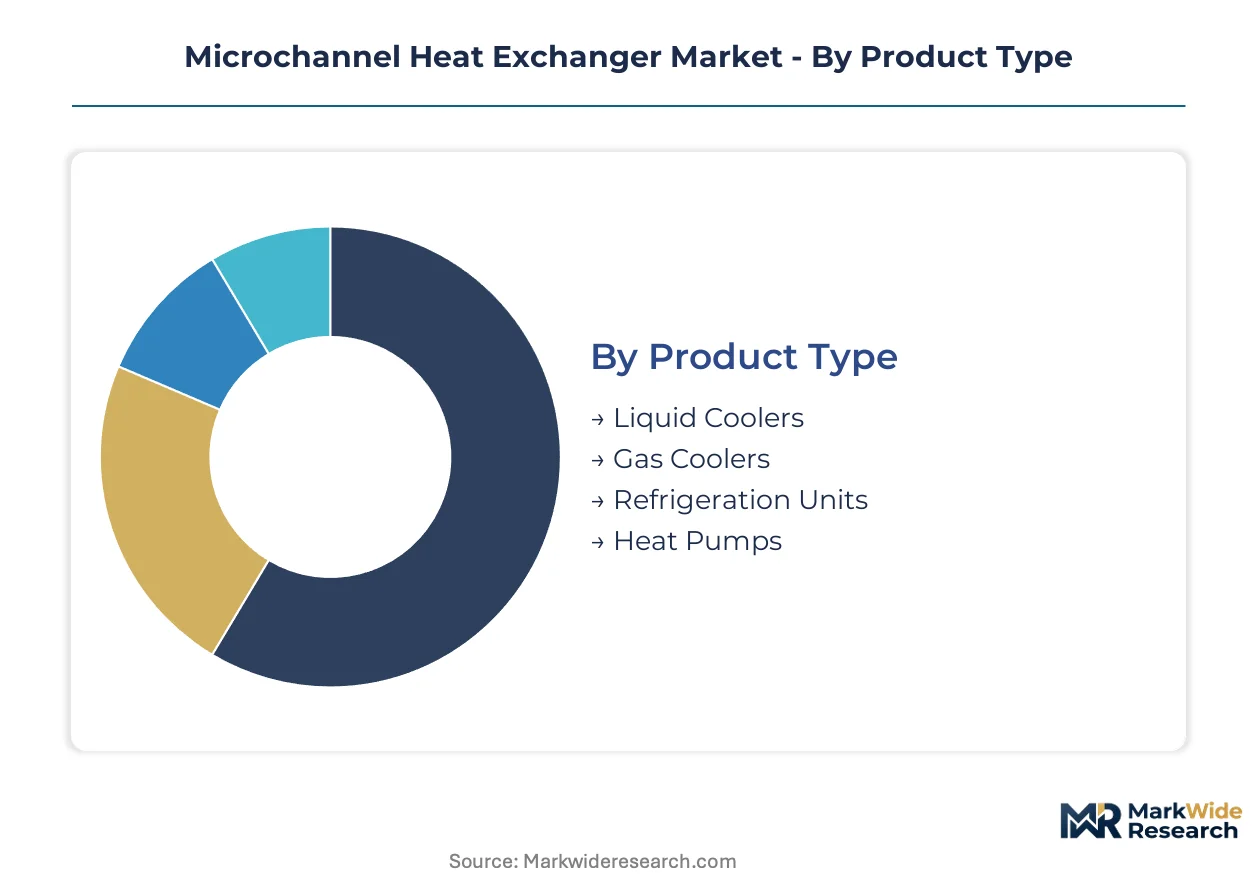
Microchannel heat exchanger procurement patterns diverge sharply between integrated system builds and standalone component sales. Understanding these structural splits reveals where margin pools concentrate and which specifications command premium positioning across automotive, HVAC, and industrial verticals.
Product Type:
Integration depth varies substantially — liquid coolers and heat pumps typically embed within larger thermal management systems, while gas coolers and refrigeration units often ship as discrete subassemblies for field installation.
- Liquid Coolers:Aluminum microchannel cold plates with sub-millimeter hydraulic diameters dominate EV battery pack architectures. CATL and BYD procurement specifications in China now mandate surface treatments and manifold geometries that exceed legacy HVAC standards.
- Heat Pumps:These systems integrate microchannel condensers and evaporators within monolithic outdoor units for residential heating. EU Ecodesign seasonal performance factor regulations in Germany and France are forcing rapid specification upgrades across European HVAC supply chains.
- Gas Coolers:Standalone units serving industrial process gas cooling.
- Refrigeration Units:Self-contained systems for commercial cold chain applications.
Liquid coolers lead volumes today; heat pumps are gaining share fastest.
Application:
Cost tier stratification separates high-specification automotive contracts from price-sensitive commercial refrigeration procurement.
- Automotive HVAC:Battery-electric powertrains demand entirely new cooling circuit designs with precise temperature uniformity across large-format lithium-ion modules. EPA SNAP refrigerant phase-down timelines compress homologation cycles for North American OEMs.
- Commercial Refrigeration:Supermarket display cases and cold storage facilities prioritize refrigerant charge reduction. EU F-Gas Regulation quota allocations force German and Italian contractors toward low-GWP compatible microchannel architectures.
- Industrial Processes:Corrosive environments sustain copper microchannel positioning despite aluminum cost advantages.
- Residential Heating:Heat pump condensers compete on seasonal efficiency metrics under tightening GB standards in China.
Automotive HVAC commands premium pricing; commercial refrigeration moves the highest unit volumes.
Material:
Supply concentration for coil stock and brazing capacity shapes material selection economics across geographies.
- Aluminum:Cost-sensitive automotive and HVAC volumes rely on precision-extruded microchannel tube stock. LME price volatility compresses margin predictability for contract manufacturers serving Japanese and German OEMs.
- Copper:Corrosive refrigerant environments and hybrid aluminum-copper joining requirements sustain premium positioning. Multi-material brazing expertise concentrates in controlled atmosphere furnace clusters across Germany and Japan.
- Stainless Steel:Aggressive chemical process applications requiring extreme corrosion resistance.
- Composite Materials:Emerging formulations for weight-critical aerospace and motorsport thermal management.
Aluminum dominates absolute production; copper holds the steepest expansion trajectory in corrosive applications.
End User:
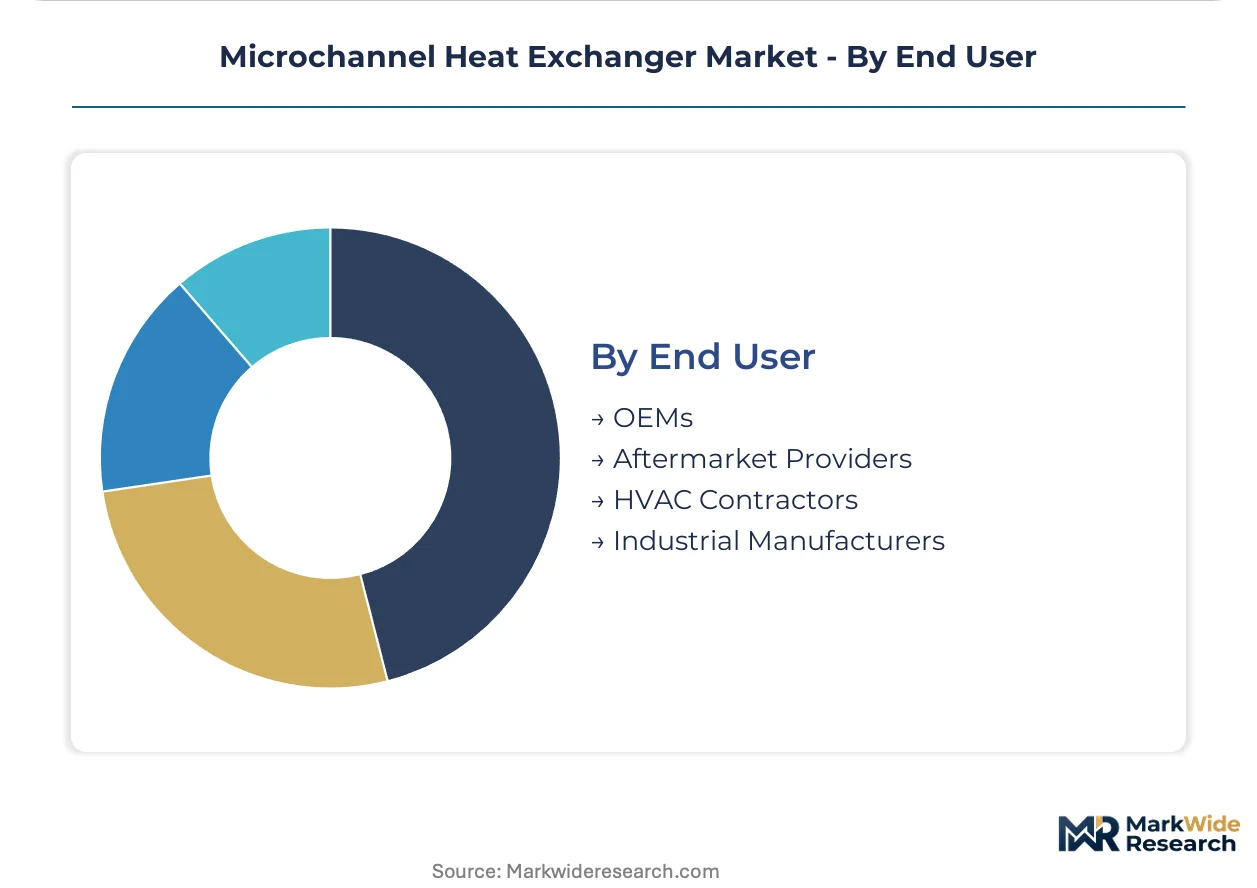
Procurement authority is shifting from traditional tier-1 integrators toward direct OEM specification of component geometries and surface treatments.
- OEMs:Automotive and battery manufacturers now specify cold plate designs directly, bypassing thermal module integrators. This pattern is most pronounced in China where CATL maintains approved supplier lists for microchannel tube stock.
- Aftermarket Providers:Replacement coil demand tracks installed base aging in North American and European commercial HVAC fleets.
- HVAC Contractors:Installation and maintenance procurement for commercial and residential systems.
- Industrial Manufacturers:Process equipment builders specifying custom thermal management solutions.
OEM direct procurement leads volume concentration; aftermarket channels deliver the most stable margin profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where microchannel coil fabrication migrates, as compliance cost gaps between jurisdictions widen under divergent refrigerant phase-down schedules and carbon border adjustment mechanisms.
China
CATL and BYD procurement specifications for EV battery cold plates now mandate surface treatments exceeding legacy HVAC standards. The country's dual carbon goals and GB energy-efficiency standards for commercial HVAC equipment accelerate domestic OEM adoption of high-efficiency microchannel coils. Manufacturing gravity concentrates in the Yangtze River Delta, where precision aluminum extruders serve both automotive and industrial cooling verticals.
Germany
Commercial refrigeration contractors face stranded inventory risk from EU F-Gas Regulation quota allocations and misaligned component certification timelines. The Ecodesign directive's seasonal performance factor regulations force rapid specification of microchannel condensers across residential heating supply chains. Controlled atmosphere brazing capacity clusters in Baden-Württemberg and Bavaria, creating geographic supply risk for regional fabricators serving heat pump OEMs.
United States
EPA SNAP refrigerant phase-down timelines compress homologation cycles for automotive thermal system validation. North American OEMs now demand heat exchangers with reduced internal volumes and enhanced corrosion resistance for low-GWP alternatives. Industrial corridors in Michigan and Ohio concentrate brazing furnace capacity serving contract manufacturers supplying Detroit-area automotive programs.
Japan
Denso Corporation leverages captive supply of precision aluminum microchannel coils to anchor relationships with domestic OEMs transitioning to battery-electric architectures. METI efficiency standards and JIS certification requirements sustain premium positioning for domestic fabricators. The Chubu region around Nagoya maintains concentrated extrusion and brazing expertise serving both automotive and industrial process cooling segments.
India
The PLI scheme for advanced automotive components creates tariff-protected demand for domestic microchannel coil production serving Maruti Suzuki and Hyundai Motor India operations. BIS energy-efficiency labeling requirements for commercial refrigeration equipment accelerate specification upgrades. Manufacturing investments concentrate in Gujarat and Tamil Nadu, where component suppliers localize to meet domestic content thresholds for automotive HVAC contracts.
Microchannel Heat Exchanger Market Vendor Landscape
Capacity expansion dominates the current landscape as tier-1 suppliers race to secure controlled atmosphere brazing furnace slots ahead of refrigerant chemistry transitions. The vendor base stratifies across three tiers: integrated thermal module suppliers with captive coil production, specialized microchannel fabricators serving multiple OEMs, and regional contract manufacturers dependent on spot aluminum pricing. Strategic archetypes include scale-driven aluminum extruders, multi-material joining specialists, and vertically integrated automotive suppliers. Competitive intensity centers on geographic proximity to OEM assembly plants and backward integration into precision tube stock production.
Among Asia-Pacific-based fabricators, Sanhua Co., Ltd. exemplifies the scale-driven archetype serving Chinese EV battery pack cooling lines, while Denso Corporation anchors the vertically integrated tier with captive aluminum microchannel coil supply. MAHLE GmbH occupies a position within the European specialist tier, competing through R&D intensity in low-GWP refrigerant-compatible designs. These three companies represent distinct strategic postures: geographic scale concentration, upstream supply control, and regulatory-driven product development respectively.
| Leading Market Players |
|---|
| Danfoss |
| Sanhua |
| Modine Manufacturing Company |
| Kaltra |
| MAHLE GmbH |
| Hanon Systems |
| Johnson Controls |
| Denso Corporation |
| Alfa Laval |
| Others |
Supply Flow & Price Mechanics
LME aluminum price volatility cascades through coil stock procurement into three-tier pricing stratification across premium, standard, and economy levels, with automotive OEMs commanding volume discounts that compress contract manufacturer margins while HVAC contractors absorb spot-market exposure.
Pricing Analysis
Distributor margins on replacement coils for commercial HVAC fleets run 18-25 points above direct-to-OEM contract pricing for EV battery cold plates. Price differentiation hinges on GB certification tier for Chinese domestic sales and UL corrosion-resistance ratings for North American automotive programs. Cost compression in standard-grade aluminum microchannel tubes is intensifying because CATL and BYD procurement specifications now mandate surface treatments previously reserved for premium tiers. Aftermarket providers serving aging European commercial refrigeration fleets exhibit the highest price sensitivity, while battery manufacturers with approved supplier lists show the least.
Supply Chain Analysis
Single-source vulnerability sits with controlled atmosphere brazing furnace capacity clustered in Germany, Japan, and Michigan industrial corridors. Precision-extruded microchannel tube stock draws from Yangtze River Delta aluminum mills, Chubu-region Japanese extruders, and Baden-Württemberg specialty metal suppliers. Raw material dependencies center on high-purity aluminum ingot, copper coil stock for hybrid designs, and nickel-based brazing alloys. Tariff exposure on Chinese aluminum extrusions threatens margin stability for North American contract manufacturers. Distribution runs through tier-1 thermal module integrators for automotive volumes and HVAC wholesale distributors for commercial replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microchannel heat exchanger market compounds steadily as refrigerant chemistry transitions and EV thermal management architectures force recurring redesign cycles across installed equipment bases.
For Market Incumbents: To counter direct OEM procurement bypassing traditional tier-1 integrators, Denso Corporation and MAHLE GmbH should deepen captive supply of precision aluminum microchannel coils and secure controlled atmosphere brazing furnace slots ahead of R-454B refrigerant qualification deadlines. Backward integration into tube stock extrusion in Yangtze River Delta and Chubu-region clusters anchors volume commitments from CATL and domestic Japanese OEMs transitioning to battery-electric platforms.
For New Entrants and Emerging Players: India's PLI scheme for advanced automotive components opens a window for domestic microchannel coil production serving Maruti Suzuki and Hyundai Motor India operations with tariff-protected local content thresholds. White-space targets include datacenter direct-to-chip liquid cooling for AI training clusters and A2L-compatible manifold designs for EU residential heat pump OEMs facing Ecodesign seasonal performance factor mandates. A go-to-market angle through BIS-certified commercial refrigeration contracts builds referenceability before automotive HVAC qualification.
For Investors and Strategic Acquirers: Asymmetric upside sits with multi-material joining specialists possessing copper-aluminum hybrid brazing expertise for corrosive low-GWP refrigerant environments. Long-term viability over a 5-10 year window rests on regulatory tailwinds from EPA SNAP phase-downs and EU F-Gas quota reductions that force equipment replacement cycles. The signal to watch is homologation timeline compression where OEM thermal system validation overlaps with refrigerant transitions, favoring suppliers with simultaneous fluid circuit and heat exchanger redesign capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Extrusion | Captive aluminum microchannel tube supply secures CATL and BYD procurement specifications in Yangtze River Delta. |
| Multi-Material Brazing Capability Expansion | Copper-aluminum hybrid joining expertise commands premium positioning under A2L refrigerant safety standards. |
| Controlled Atmosphere Furnace Capacity Addition | Brazing furnace slots in Baden-Württemberg and Michigan corridors lock in automotive OEM qualification timelines. |
| Low-GWP Refrigerant Compatibility Certification | R-454B and R-32 platform architectures future-proof order books against EPA SNAP and EU F-Gas phase-downs. |
| Datacenter Liquid Cooling Product Line | Direct-to-chip thermal management for AI training clusters opens performance-specification segment distinct from automotive. |
Methodological Framework
Bottom-up EV battery pack and HVAC equipment modeling reconciled against top-down aluminum extrusion capacity and brazing furnace installation tracking forms the analytical core. Primary interviews with thermal management engineers at automotive OEMs, procurement leads at CATL and BYD, HVAC contractor operations managers, and controlled atmosphere brazing furnace operators cross-validated secondary sources including EPA SNAP rulemaking dockets, EU F-Gas Regulation quota allocation records, GB energy-efficiency standard filings, and LME aluminum price series. Trade flow data from customs authorities and SEC 10-K disclosures from listed thermal component suppliers provided supply-side triangulation.
Input-output matrices mapped microchannel coil fabrication capacity against OEM thermal system procurement schedules across the projection horizon. Segmentation dimensions modeled include product type integration depth, refrigerant chemistry compatibility tier, material specification grade, and end-user procurement authority structure. CAGRs derived from equipment replacement cycle analysis, refrigerant phase-down compliance deadlines, and EV production ramp assumptions. Forecast inputs incorporated aluminum price scenario bands and homologation timeline compression factors specific to overlapping refrigerant and thermal architecture transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions or accelerated refrigerant chemistry shifts beyond EPA SNAP announced schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Process Chillers Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Plate and Frame Heat Exchangers Market