
 Portable Chiller Market | 2026-2036
Portable Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Chiller Market Analytics
Aluminum microchannel heat exchangers are broadening the efficiency envelope for portable chiller designs, trimming weight and refrigerant charge simultaneously. Carrier Corporation leverages its integrated compressor manufacturing to sustain cost advantages across air-cooled portable units. Trane Technologies anchors its position through deep controls expertise, embedding IoT-enabled diagnostics into rental fleets. Johnson Controls competes on energy efficiency certifications, positioning its portable chillers for pharmaceutical cleanroom specifications where temperature stability commands premium pricing.
Portable chillers are self-contained refrigeration systems that circulate chilled water, glycol solution, or air through a closed loop to remove process heat, typically rated from one ton to above fifteen tons of cooling capacity. These units deploy casters or skid mounting for rapid repositioning across construction sites, food processing lines, and temporary event infrastructure. Air-cooled portable chillers dominate rental fleets due to eliminated cooling tower infrastructure, while water-cooled variants retain efficiency advantages in fixed industrial installations where condenser water is available. The six-to-ten-ton capacity band captures the densest margin pool, serving mid-scale pharmaceutical batch processes and commercial kitchen central plants where uptime requirements justify premium service contracts.
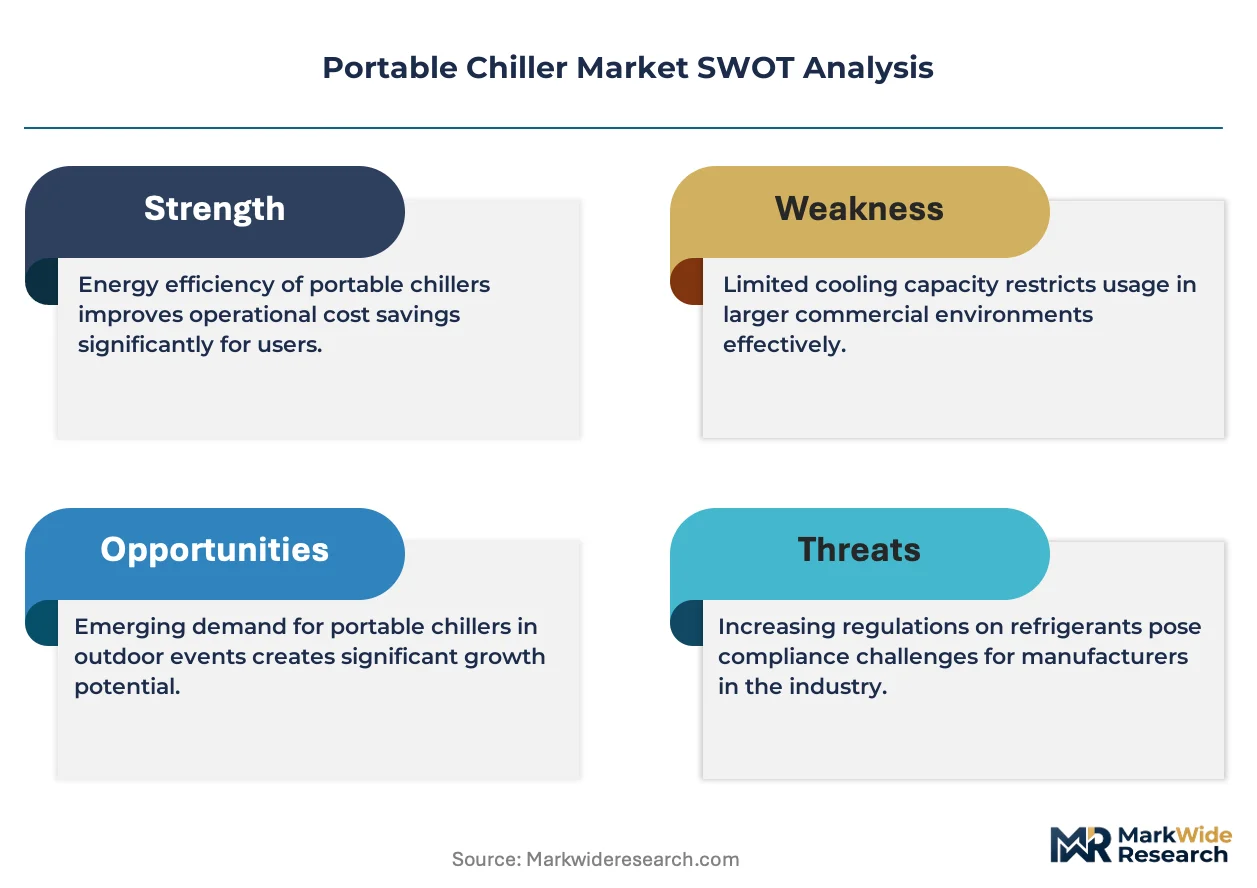
The EPA enforces refrigerant management under Section 608 of the Clean Air Act, compelling chiller OEMs to validate leak detection systems and transition to A2L-class lower-flammability refrigerants. OSHA's process safety management standards govern ammonia-based portable chillers in food processing, restricting deployment near populated event spaces without engineered mitigation. California's Title 24 building efficiency code extends to temporary cooling loads on large construction projects, creating compliance-driven specification tiers. Stakeholders must monitor refrigerant phase-in timelines and state-level efficiency mandates to avoid stranded inventory in rental fleets and specify equipment with adaptable compressor architectures.
Market Dynamics
Aluminum microchannel heat exchangers are compressing refrigerant charges and unit weights simultaneously, forcing OEMs to redesign chassis architectures around lighter thermal cores while EPA's AIM Act phases down hydrofluorocarbon refrigerants.
Growth Catalysts
- Food processing expansion:Seasonal harvest peaks across California's Central Valley and Florida's citrus belt are driving rental fleet deployments for temporary process cooling.
- F-Gas Regulation:Europe's phasedown of high-GWP refrigerants is accelerating A2L-class equipment certification and retrofit demand across German pharmaceutical plants.
- Precision manufacturing clustering:Stuttgart's automotive tooling sector and Munich's semiconductor fabrication facilities are specifying portable chillers for tight temperature control during production ramp-ups.
Market Restraints
- Copper price volatility:Coil and tubing input costs swing with commodity markets, compressing margin stability for air-cooled unit producers.
- Compressor supply concentration:Scroll and rotary compressor manufacturing clusters in East Asia create single-source vulnerability for mid-capacity chiller assemblers.
- Water-cooled efficiency gap:Cooling tower infrastructure requirements limit water-cooled portable deployment to fixed industrial sites with existing condenser water loops.
Strategic Opportunities
- India's pharmaceutical corridor:Hyderabad and Bangalore bulk drug manufacturing clusters lack adequate process cooling infrastructure, opening rental fleet penetration.
- Data center edge computing:Modular server deployments at cell towers and retail edge nodes require compact, rapid-deploy thermal management.
- California Title 24 compliance:Temporary cooling loads on large construction projects face mandated efficiency tiers, creating specification-driven upgrade cycles.
Industry Challenges
- A2L refrigerant technician certification:Lower-flammability refrigerant handling requires retrained service workforces, slowing fleet turnover timelines.
- Controls integration complexity:IoT-enabled diagnostic platforms must interface with legacy building management systems across heterogeneous installed bases.
- OSHA ammonia proximity restrictions:Food processing deployments near populated event spaces require engineered mitigation systems, adding project engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Chiller Market |
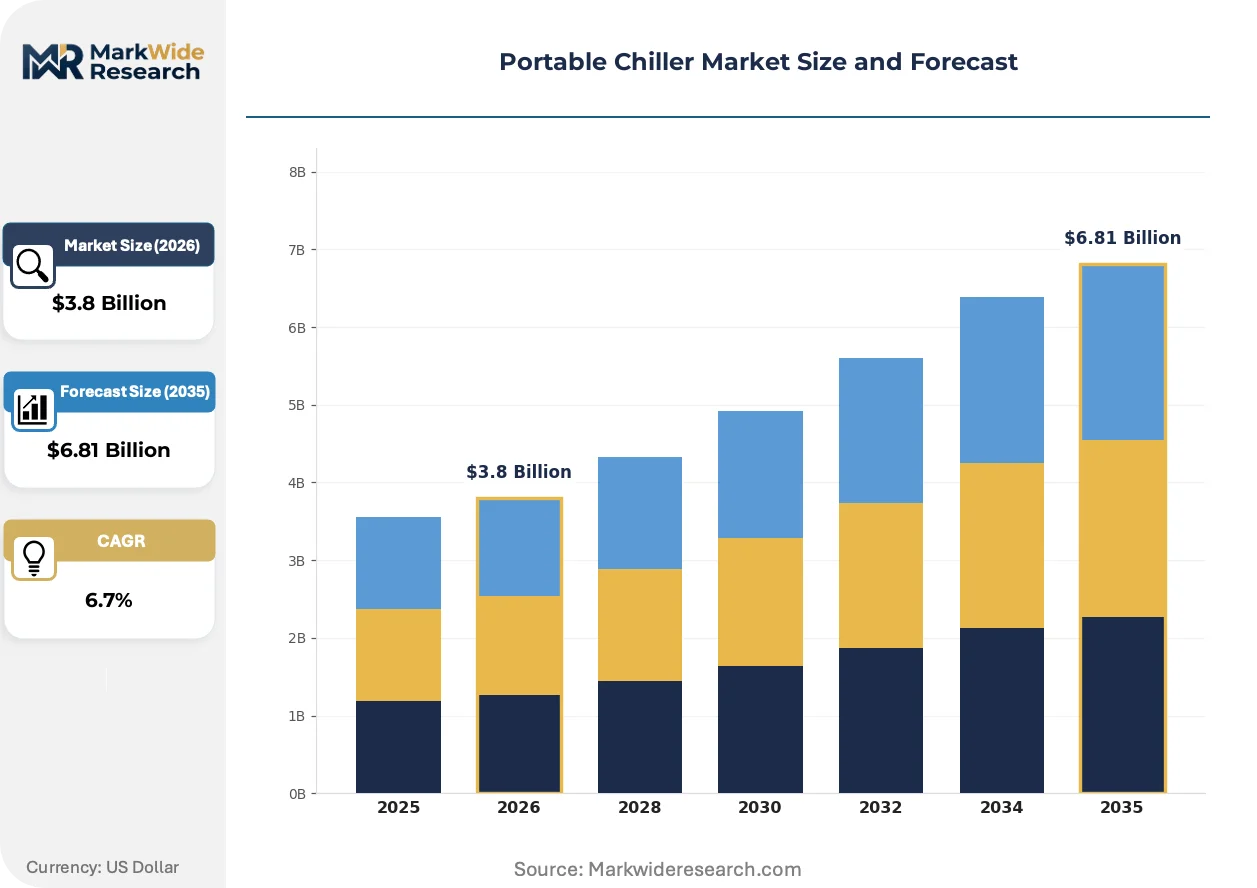
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled Chilllers, Water-Cooled Chilllers, Glycol Chilllers, Solar-Powered Chilllers Industry Vertical: Food Processing, Pharmaceuticals, Events, Hospitality End User: Restaurants, Warehouses, Construction, Laboratories Capacity: 1-5 Tons, 6-10 Tons, 11-15 Tons, Above 15 Tons |
| Companies Covered | Carrier Corporation, Trane Technologies, Johnson Controls, Daikin Industries, Mitsubishi Electric Corporation, Honeywell International, Portable Air, Berg Chilling Systems, OptiTemp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Chiller Market Evolving Landscape
Portable chiller engineering is pivoting toward refrigerant chemistry adaptation and connected service architectures, with thermal efficiency gains now inseparable from regulatory compliance and fleet telemetry capabilities.
Variable-speed scroll compressors paired with electronic expansion valves are rewriting the efficiency-performance tradeoff for mid-capacity units. Pharmaceutical batch processors in Germany and food packaging lines in the Netherlands are specifying these packages for part-load optimization. The technology is rewriting rental fleet economics by cutting energy penalties during low-demand periods.
EPA's Section 608 enforcement is tightening leak detection and repair documentation requirements for existing refrigerant stocks. Chiller OEMs must validate automated leak detection systems and transition service infrastructure toward A2L-compatible handling protocols. California's Air Resources Board is extending these timelines to stationary refrigeration, accelerating equipment replacement decisions in the state's construction and agriculture sectors.
Equipment-as-a-service contracting is displacing traditional capital purchase models for seasonal users. Food processors in Florida and event infrastructure operators in Texas are prioritizing uptime-guaranteed rental agreements with bundled maintenance over ownership. This shift is most visible in the six-to-ten-ton capacity band where utilization volatility makes fixed asset ownership economically unfavorable.
Portable Chiller Market Segmentation
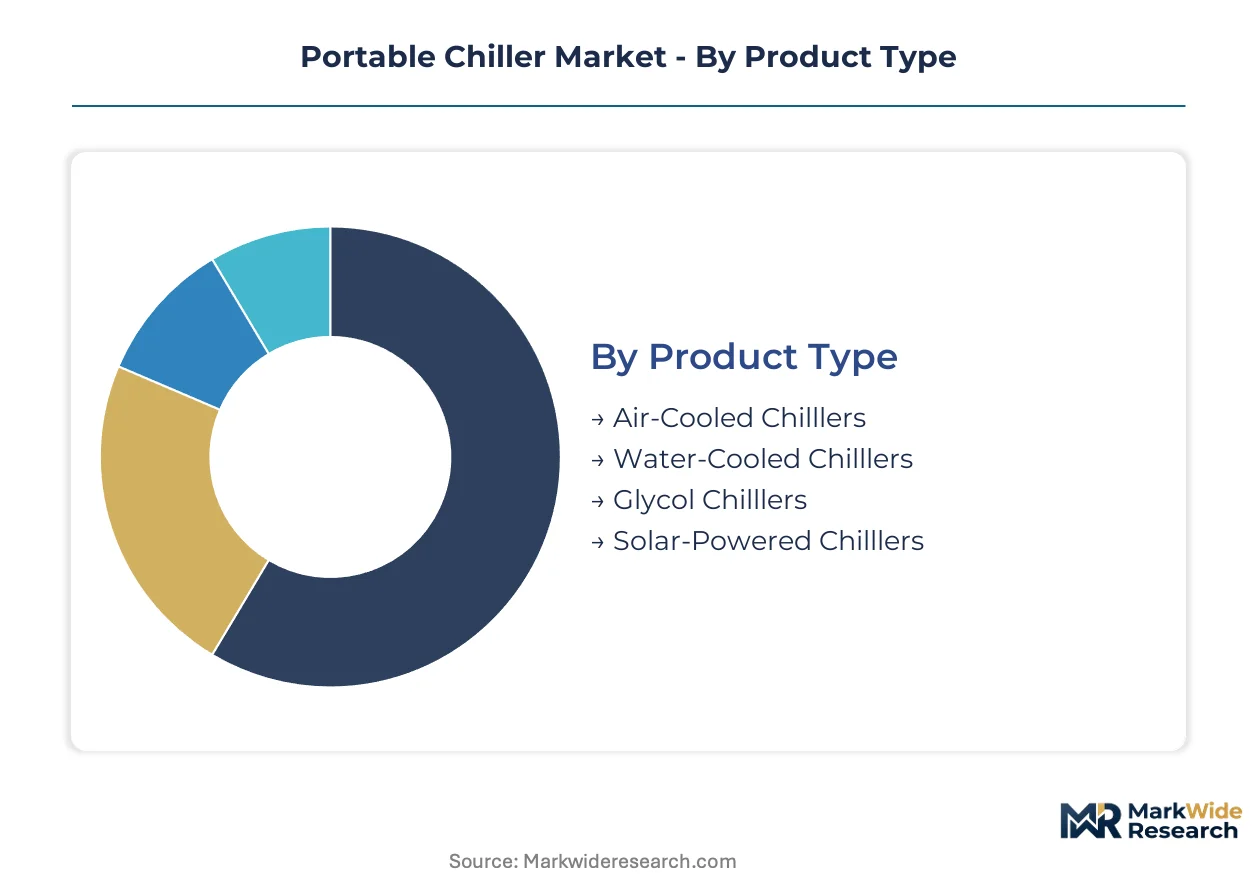
Portable chiller segmentation reveals how equipment specifications align with deployment economics. Each dimension—cooling medium, end-use environment, operator type, and thermal load—creates distinct procurement patterns and service requirements.
Product Type:
Supply concentration for heat exchanger cores and compressor modules varies sharply across cooling architectures, with air-cooled units commanding the broadest supplier base.
- Air-Cooled Chillers:These units reject heat directly to ambient air through finned coils, eliminating cooling tower infrastructure. Rental fleets across Texas and Florida favor air-cooled designs for rapid deployment at construction sites and outdoor events where water access is limited.
- Water-Cooled Chillers:Condenser water loops deliver superior efficiency in fixed industrial settings. German pharmaceutical plants in Ludwigshafen specify water-cooled portable units for batch process cooling where condenser water infrastructure already exists.
- Glycol Chillers:Propylene glycol solutions enable sub-freezing temperatures for beverage dispensing and ice rink applications.
- Solar-Powered Chillers:Photovoltaic-driven compression suits off-grid deployments in remote agricultural processing.
Today's leader: Air-Cooled Chillers. Tomorrow's challenger: Solar-Powered Chillers.
Industry Vertical:
Application-driven specification intensity separates verticals, with pharmaceutical and food processing demanding redundant capacity and precision controls.
- Food Processing:Seasonal harvest peaks in California's Central Valley drive rental demand for temporary process cooling during tomato and stone fruit campaigns. USDA inspection requirements mandate stainless steel construction and washdown-rated electrical enclosures.
- Pharmaceuticals:cGMP compliance and batch record validation require temperature stability within narrow bands. Stuttgart-area contract manufacturers specify portable chillers with redundant compressors for API synthesis campaigns.
- Events:Temporary cooling for outdoor festivals and sporting venues prioritizes rapid setup and low noise signatures.
- Hospitality:Hotel kitchen central plants and banquet facilities use portable units for emergency backup during main chiller maintenance.
Food Processing anchors current procurement volumes; Pharmaceuticals is climbing the fastest on regulatory compliance spending.
End User:
Operator sophistication and maintenance access determine whether purchase or rental models dominate.
- Restaurants:Independent operators lack in-house refrigeration expertise, favoring rental agreements with bundled service.
- Warehouses:Cold storage facilities deploy portable units for blast cooling and redundancy during peak inventory periods.
- Construction:General contractors on California Title 24 projects specify compliant temporary cooling for worker safety and concrete curing.
- Laboratories:Research institutions require precise temperature control for analytical equipment and sample storage.
Construction currently dominates unit deployments; Laboratories command the steepest premium pricing.
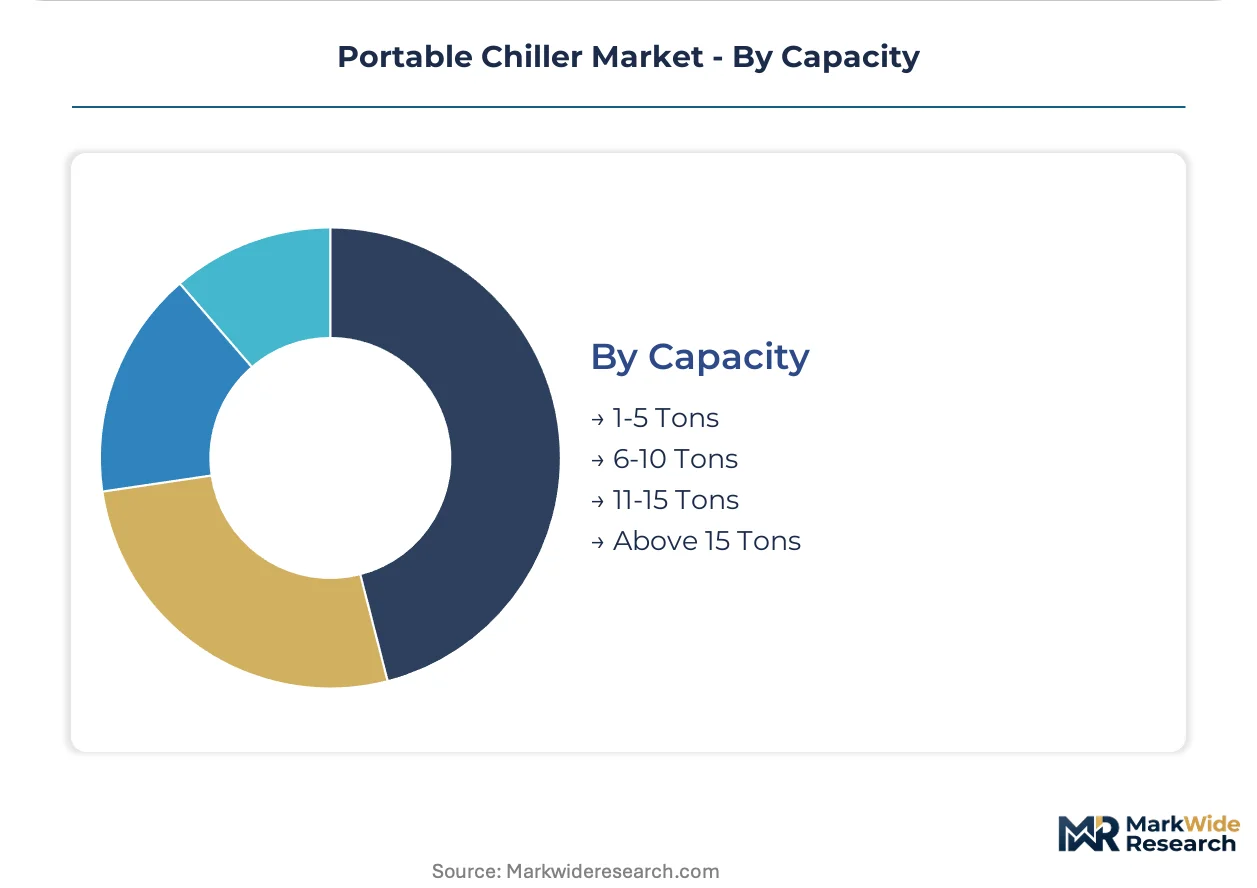
Capacity:
Manufacturing scale economies concentrate in the mid-capacity band where component sourcing and assembly efficiency peak.
- 6-10 Tons:This range captures the densest margin pool, serving mid-scale pharmaceutical batch processes and commercial kitchen central plants. Component suppliers optimize scroll compressor production for this capacity band, delivering cost advantages that smaller or larger units cannot match.
- 1-5 Tons:Compact units suit restaurants, laboratories, and small event infrastructure. German precision tooling shops specify these for machine tool cooling during prototype production runs.
- 11-15 Tons:Industrial food processing lines and mid-sized data halls require this capacity tier.
- Above 15 Tons:Large-scale temporary cooling for major construction projects and industrial process peaks.
6-10 Tons holds manufacturing scale advantages; Above 15 Tons faces the steepest supply chain constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor drives the densest concentration of portable chiller demand in Europe, with pharmaceutical and automotive tooling clusters requiring tight temperature control for batch processes and production ramp-ups.
United States
Food processing expansion across California's Central Valley and Florida's citrus belt fuels seasonal rental demand for temporary process cooling during harvest peaks. EPA's Section 608 refrigerant management enforcement compels OEMs to validate leak detection systems and transition service infrastructure. Construction sites in Texas and Arizona deploy air-cooled units for worker safety and concrete curing under California Title 24 efficiency mandates.
Germany
Stuttgart's automotive tooling sector and Munich's semiconductor fabrication facilities specify portable chillers for tight temperature control during production ramp-ups. The EU F-Gas Regulation accelerates A2L-class equipment certification and retrofit demand across pharmaceutical plants. Ludwigshafen's chemical corridor anchors water-cooled unit deployment where condenser water infrastructure already exists.
China
Guangdong's electronics manufacturing belt and Jiangsu's pharmaceutical clusters drive demand for mid-capacity units with precision controls. The country's national environmental regulator enforces dual carbon goals that pressure industrial cooling efficiency standards. Shanghai's biopharma contract manufacturers specify redundant compressor configurations for API synthesis campaigns.
India
Hyderabad and Bangalore's bulk drug manufacturing clusters lack adequate process cooling infrastructure, opening rental fleet penetration opportunities. The country's national pharmaceutical regulator mandates cGMP compliance that elevates temperature stability requirements. Gujarat's specialty chemical sector deploys portable units during capacity expansions and maintenance turnarounds.
Japan
Osaka's precision machinery sector and Tokyo's pharmaceutical R&D facilities require compact units for prototype production and analytical equipment cooling. METI's energy efficiency standards drive specification of variable-speed compressor packages. Yokohama's biotech incubators specify portable chillers for temporary cleanroom thermal management during facility upgrades.
Portable Chiller Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and service network density. The vendor base organizes around three strategic archetypes: diversified HVAC conglomerates with captive compressor manufacturing, specialized chilling equipment fabricators with deep process cooling expertise, and rental fleet operators with IoT-enabled service platforms. Consolidation pressure concentrates among mid-capacity specialists seeking scale advantages in component sourcing. Dominant competitive moves include backward integration into heat exchanger core production and geographic expansion through distributor partnerships.
Within the diversified conglomerate tier, Carrier Corporation, Trane Technologies, and Johnson Controls anchor competitive positioning through integrated manufacturing depth and controls expertise. Carrier leverages its compressor manufacturing footprint to sustain cost advantages across air-cooled portable units. Trane embeds IoT-enabled diagnostics into rental fleet architectures. Johnson Controls competes on energy efficiency certifications for pharmaceutical cleanroom specifications. These three represent how scale and vertical integration define the premium tier.
| Leading Market Players |
|---|
| Carrier Corporation |
| Trane Technologies |
| Johnson Controls |
| Daikin Industries |
| Mitsubishi Electric Corporation |
| Honeywell International |
| Portable Air |
| Berg Chilling Systems |
| OptiTemp |
| Others |
Value Network & Pricing Analysis
EPA's AIM Act phasedown of hydrofluorocarbon refrigerants gates qualified supply and premium-tier pricing access, compressing margins for OEMs lacking A2L-compatible production lines while rewarding certified manufacturers with pricing power in pharmaceutical and food processing segments.
Pricing Analysis
Copper coil and aluminum microchannel input costs pass through directly to air-cooled unit pricing, with commodity volatility compressing margin stability for mid-capacity assemblers. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-certified pharmaceutical units from construction-grade rentals and basic event infrastructure models. Pricing pressure stems from scroll compressor supply concentration in East Asia, forcing OEMs to absorb tariff exposure or surrender share. Food processors and independent restaurant operators exhibit highest price sensitivity, while pharmaceutical cleanroom specifications command least elasticity due to batch validation requirements.
Supply Chain Analysis
Scroll and rotary compressor manufacturing rests on production clusters in China, Japan, and South Korea, creating single-source vulnerability for mid-capacity chiller assemblers. Aluminum microchannel heat exchanger cores, copper tubing, and electronic expansion valves constitute critical input dependencies. Supply chain risk centers on logistics chokepoints through East Asian port congestion and semiconductor shortages for IoT-enabled control boards. Distribution runs through rental fleet operators with national service networks, OEM-direct sales for permanent installations, and regional distributors serving construction and event infrastructure markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable chiller market reads as a late-cycle quality story, with EPA refrigerant mandates and EU F-Gas Regulation shifting procurement toward premium-tier, A2L-certified equipment with embedded diagnostics and guaranteed uptime contracting.
For Market Incumbents: To counter compressor supply concentration in East Asia, secure dual-source agreements with secondary manufacturers in Mexico and Eastern Europe while backward integrating into heat exchanger core production. Invest in A2L refrigerant handling certification infrastructure ahead of fleet turnover timelines to defend service revenue streams against emerging rental operators. For New Entrants and Emerging Players: California's Title 24 building efficiency code opens a window for specification-compliant, rapid-deploy units targeting construction sector temporary cooling mandates. Penetrate India's pharmaceutical corridor through rental fleet partnerships with Hyderabad and Bangalore bulk drug manufacturers, leveraging equipment-as-a-service contracting to bypass capital purchase barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet operators with dense service networks because utilization volatility and seasonal demand patterns favor consolidated fleet management platforms. Target mid-cap specialists with captive heat exchanger fabrication capabilities and established A2L technician training infrastructure. Watch EPA enforcement intensity and state-level refrigerant phase-in timelines as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Core Production | Carrier Corporation's captive aluminum microchannel manufacturing insulates margin stability from commodity volatility. |
| A2L Refrigerant Certification Infrastructure Investment | Trane Technologies' technician training platforms accelerate fleet turnover compliance with EPA Section 608 mandates. |
| Equipment-as-a-Service Contracting Expansion | Johnson Controls' uptime-guaranteed rental agreements displace capital purchases in Florida food processing seasonal peaks. |
| Geographic Expansion through Distributor Partnerships | Daikin Industries' channel partnerships in Gujarat specialty chemical sector extend service reach during maintenance turnarounds. |
| IoT-Enabled Diagnostic Platform Integration | Mitsubishi Electric's connected service architectures reduce downtime penalties for Stuttgart automotive tooling precision requirements. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each combining structured interviews with plant engineers, rental fleet operations directors, pharmaceutical facilities managers, and aftermarket service heads alongside secondary validation. Sources include EPA Section 608 enforcement databases, EU F-Gas Regulation compliance filings, customs trade data for compressor and heat exchanger imports, and SEC 10-K disclosures from diversified HVAC conglomerates. Bottom-up unit deployment estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition separates volume expansion from pricing mix shifts across the analysis window, with CAGRs derived from segment-level growth trajectories weighted by capacity band and cooling architecture penetration. Segmentation dimensions modeled include product type, industry vertical, end-user sophistication, and capacity tier alongside regional regulatory cluster intensity. Forecast inputs incorporate refrigerant phase-in timelines, seasonal harvest patterns in California and Florida, and pharmaceutical cGMP compliance spending trajectories.
Revisions become necessary when EPA accelerates A2L refrigerant mandates, copper and aluminum commodity prices spike beyond historical bands, or East Asian compressor manufacturing faces sustained disruption. Forecasts reflect documented assumptions regarding technician certification rates, rental fleet utilization patterns, and state-level efficiency code adoption. A small set of named triggers—regulatory enforcement intensity, commodity volatility, and supply chain geopolitical exposure—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Solar-Assisted Heat Pump Market