
 North America Evaporative Cooling Market | 2026-2036
North America Evaporative Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Evaporative Cooling Market Foresight
Data center thermal management is restructuring demand patterns across the North America evaporative cooling landscape. Baltimore Aircoil Company leverages its closed-circuit cooling tower expertise to anchor large-scale hyperscale contracts in Arizona and Nevada. SPX Cooling Technologies competes through extensive distributor networks serving industrial process cooling across the Great Lakes basin. Munters specializes in adiabatic and evaporative hybrid systems for agricultural greenhouse operations in California's Central Valley.
Evaporative cooling systems utilize water evaporation to absorb sensible heat from air streams, typically achieving supply temperatures within several degrees of ambient wet-bulb conditions through direct, indirect, or hybrid contact configurations. These systems serve commercial and industrial facilities where mechanical refrigeration costs prove prohibitive, particularly in climates with low wet-bulb depression. Direct evaporative coolers occupy the residential and light commercial entry tier where simplicity and first-cost sensitivity dominate procurement decisions. Indirect and hybrid configurations capture margin pools in data center and precision manufacturing applications where humidity control requirements exclude direct wet-bulb approaches. Portable evaporative coolers extend into seasonal agricultural labor housing and outdoor event infrastructure across the southwestern United States and northern Mexico.
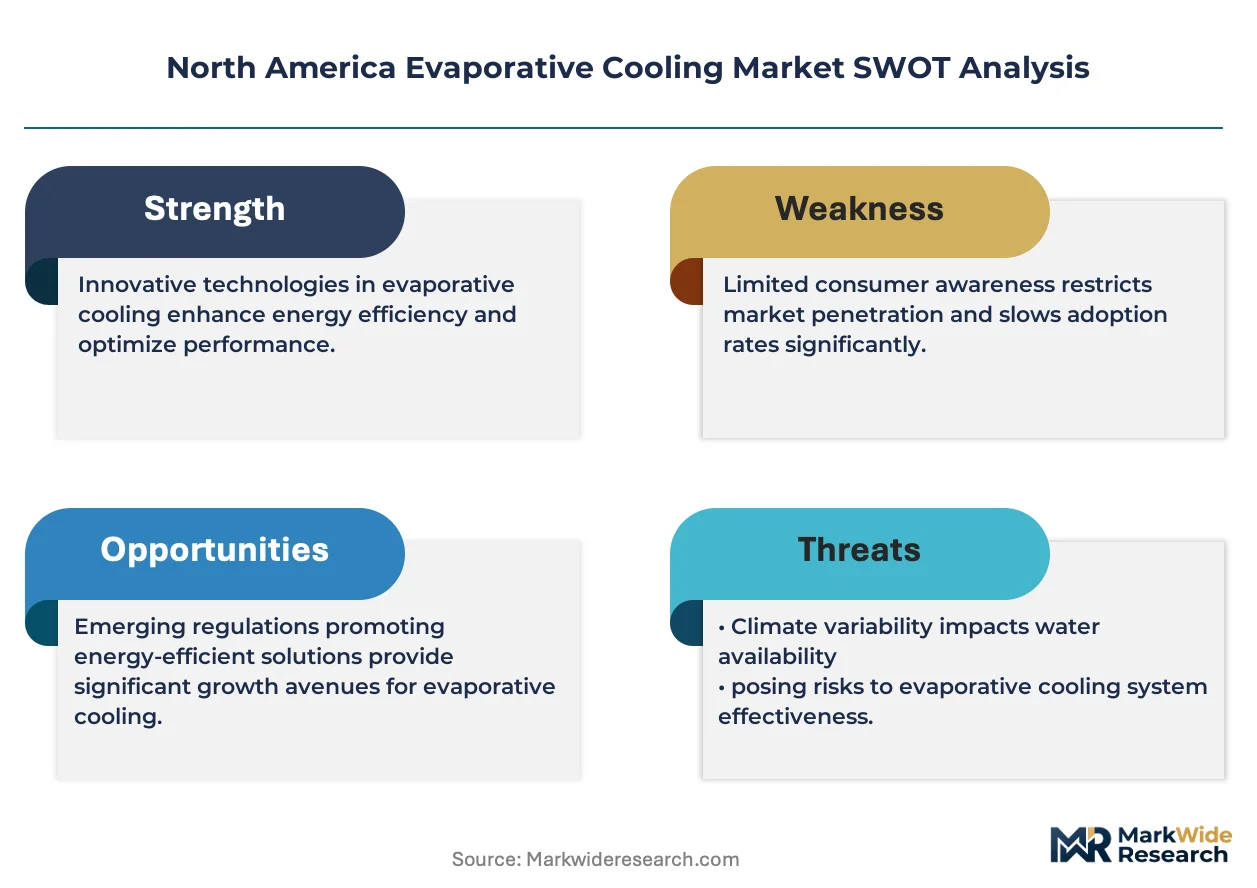
The U.S. Department of Energy enforces minimum efficiency standards under 10 CFR Part 431 for commercial evaporative coolers, while California's Title 24 Building Energy Efficiency Standards mandate economizer integration that favors indirect evaporative pre-cooling in large facilities. EPA WaterSense specifications and regional utility rebate programs shape product development priorities for water consumption rates and seasonal energy efficiency ratios. Stakeholders must monitor evolving state-level water restrictions and carbon disclosure requirements that could restructure total cost-of-ownership calculations for facility managers evaluating cooling infrastructure investments.
Market Dynamics
Data center thermal loads are restructuring procurement patterns across the North America evaporative cooling landscape, as hyperscale operators in Arizona and Nevada prioritize indirect evaporative systems to reduce mechanical refrigeration dependency.
Growth Catalysts
- 10 CFR Part 431 efficiency mandates:The U.S. Department of Energy's appliance standards are forcing manufacturers toward higher seasonal energy efficiency ratios, accelerating replacement cycles in commercial facilities.
- Utility rebate programs:Southwestern U.S. utilities are offering substantial incentives for evaporative cooling retrofits, compressing payback periods for industrial end-users in arid climate zones.
- Indirect evaporative technology:Hybrid adiabatic systems are capturing precision manufacturing and pharmaceutical cleanroom applications where humidity control excludes direct wet-bulb approaches.
Market Restraints
- Water scarcity constraints:Colorado River basin allocation disputes and municipal water restrictions in California and Arizona are limiting deployment feasibility in otherwise optimal climate conditions.
- Mechanical refrigeration substitution:Falling heat pump efficiency costs and vapor compression reliability are retaining market share in mixed-humidity zones where evaporative performance degrades.
- Supply concentration in cooling media:Celdek and Kuul Comfort pad manufacturing concentrates in Mexico and Southeast Asia, exposing distributors to cross-border tariff volatility and extended lead times.
Strategic Opportunities
- Agricultural greenhouse expansion:California's Central Valley controlled-environment agriculture operators are retrofitting hybrid evaporative-dehumidification systems to manage crop-specific microclimates.
- Title 24 economizer integration:California's building energy standards mandate indirect evaporative pre-cooling in large facilities, creating regulatory tailwinds for packaged hybrid system sales.
- Portable seasonal housing:Northern Mexico agricultural labor camps and southwestern U.S. outdoor event infrastructure represent underpenetrated channels for mobile evaporative unit deployment.
Industry Challenges
- Controls integration complexity:Facility management software interoperability with Building Automation Systems requires specialized commissioning expertise that HVAC contractors in secondary markets often lack.
- Water treatment chemistry:Scale inhibition and biological control protocols vary by municipal water hardness, forcing distributors to maintain localized chemical formulation inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Evaporative Cooling Market |
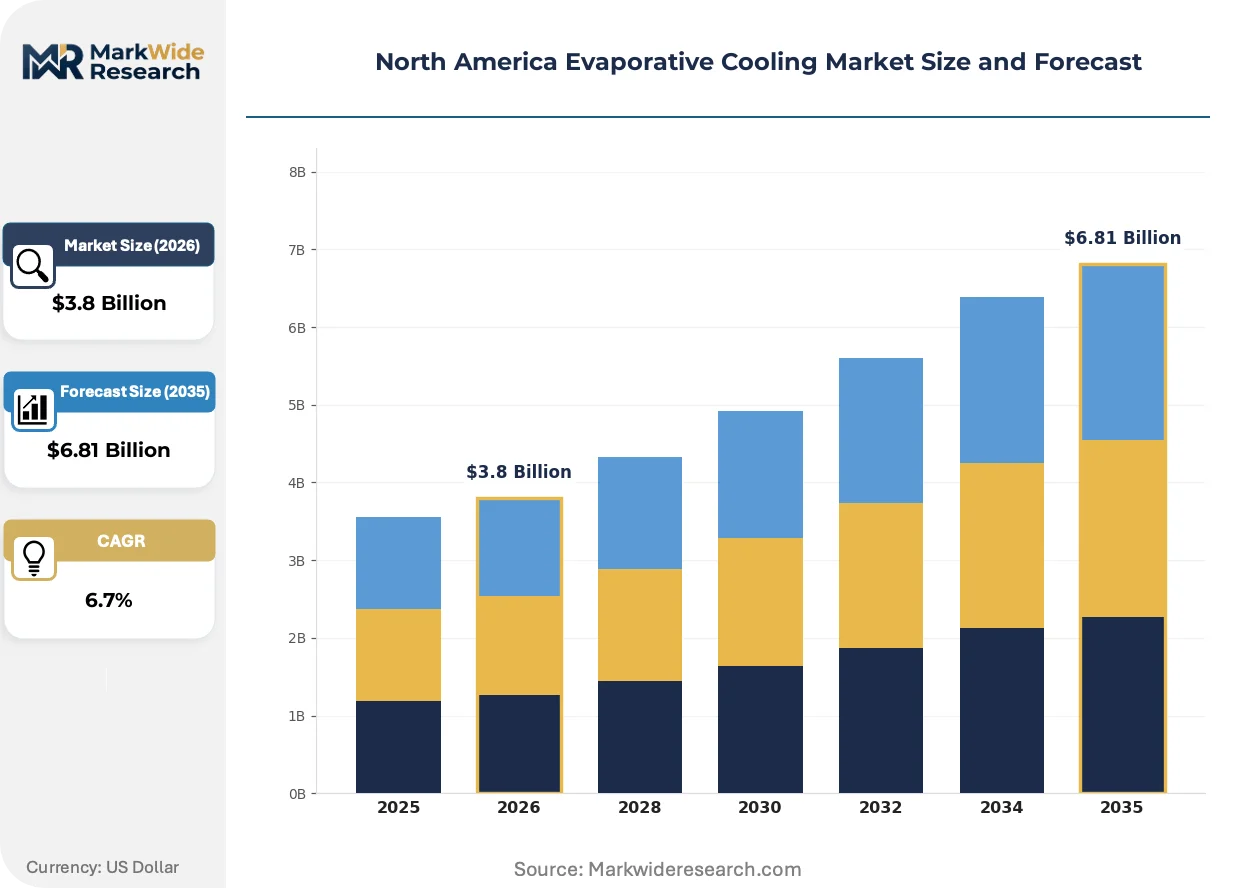
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Evaporative Cooler, Indirect Evaporative Cooler, Hybrid Evaporative Cooler, Portable Evaporative Cooler Application: Residential, Commercial, Industrial, Agriculture Technology: Open-Circuit, Closed-Circuit, Adiabatic Cooling, Advanced Control Systems End User: Building Owners, Facility Managers, HVAC Contractors, Farmers |
| Companies Covered | Honeywell International Inc., Baltimore Aircoil Company, Portacool LLC, SPX Cooling Technologies, Munters, Hessaire Products Inc., Phoenix Manufacturing Inc., Evapco Group, Delta T LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Evaporative Cooling Market Shifts & Advancements
Intelligent control architectures and water treatment automation are compressing operational cost structures while regulatory pressure on refrigerant-based systems opens substitution pathways for advanced evaporative configurations.
Machine learning-enabled variable-speed fan arrays and adaptive water distribution nozzles are automating real-time wet-bulb depression optimization in data center installations. Hyperscale operators in Phoenix and Las Vegas are deploying these systems at full-facility scale within eighteen-month procurement cycles. This automation is compressing energy consumption variance and reducing manual calibration labor requirements.
The U.S. Department of Energy's pending updates to 10 CFR Part 431 test procedures are tightening efficiency measurement protocols for commercial evaporative coolers. Manufacturers must redesign airflow configurations and media geometries to maintain compliance eligibility for federal procurement contracts. Large facility segments in Texas and New Mexico are pre-positioning specification documents to align with anticipated 2025-2026 enforcement timelines.
Facility managers are unbundling after-sales service contracts from initial equipment procurement, treating water treatment and media replacement as separate operational expenditures. This behavior is fragmenting traditional distributor revenue streams and enabling specialized water chemistry service providers to capture recurring revenue in industrial process cooling verticals. The pattern is most visible across Great Lakes basin manufacturing corridors where legacy mechanical refrigeration service networks resist evaporative technology training investments.
North America Evaporative Cooling Market Segmentation
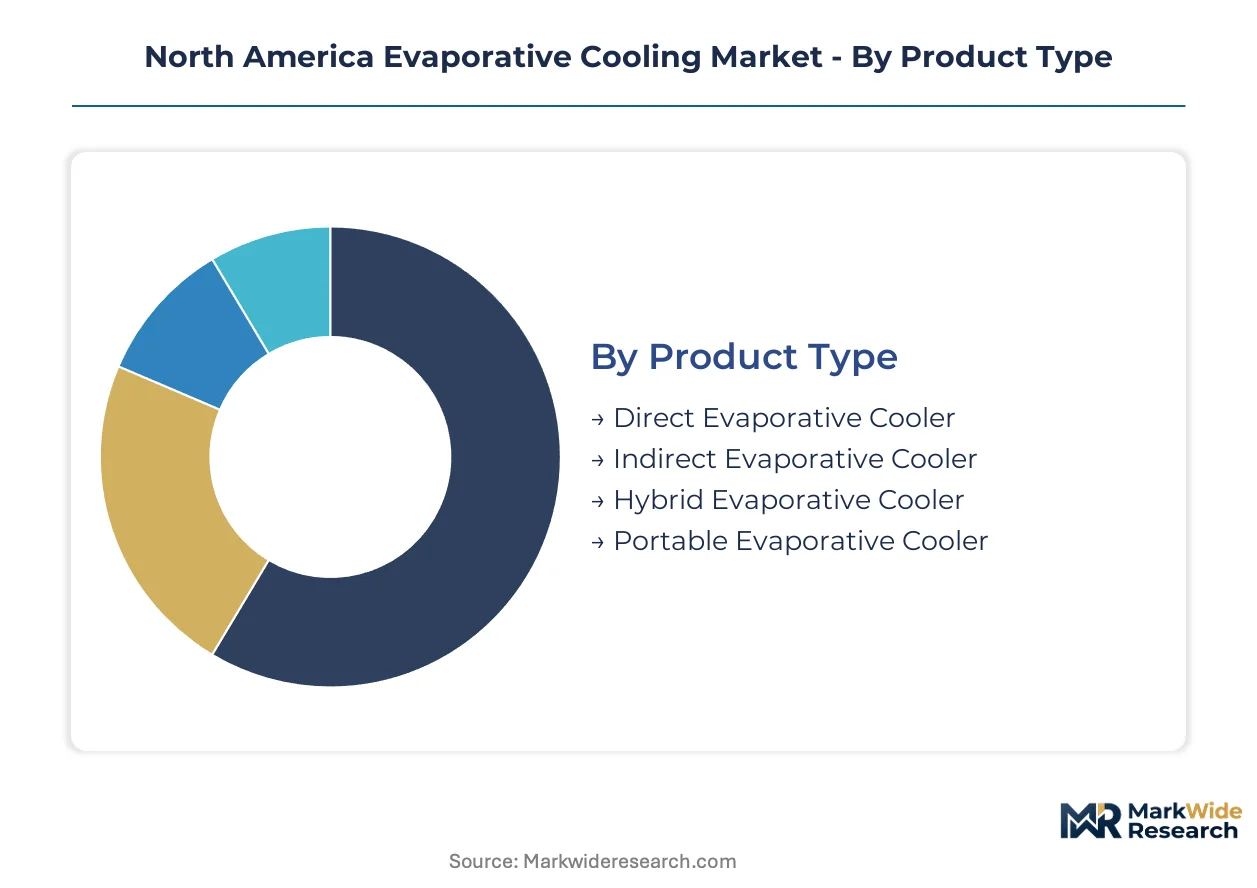
Evaporative cooling procurement in North America diverges sharply across climate zones, regulatory environments, and operational scale. Facility managers, data center operators, and agricultural producers each weight first-cost, water availability, and humidity control differently when specifying system architecture.
Product Type:
Capital intensity and climate suitability drive product selection, with arid southwestern conditions favoring simpler configurations while precision applications demand humidity-isolated designs.
- Direct Evaporative Cooler:Simple wetted-media designs pass air directly through water-saturated pads, achieving supply temperatures approaching ambient wet-bulb conditions. Residential installations across Arizona, Nevada, and New Mexico dominate procurement volumes, accelerated by utility rebate programs that compress payback periods below three years.
- Indirect Evaporative Cooler:Heat exchanger configurations isolate process air from evaporative water streams, delivering cooled air without humidity addition. Hyperscale data center operators in Phoenix and Las Vegas are standardizing on these systems to reduce mechanical refrigeration dependency while maintaining server rack humidity specifications.
- Hybrid Evaporative Cooler:Integrated mechanical refrigeration backup addresses wet-bulb conditions that exceed design thresholds. Pharmaceutical cleanrooms and precision manufacturing facilities in California's Central Valley specify these systems where process control tolerances exclude pure evaporative approaches.
- Portable Evaporative Cooler:Mobile units with integrated water reservoirs and fan arrays serve seasonal agricultural labor housing and outdoor event infrastructure. Northern Mexico agricultural camps and southwestern U.S. construction sites represent underpenetrated deployment channels.
Volume sits with Direct Evaporative Cooler; growth tilts toward Indirect Evaporative Cooler.
Application:
End-use scale determines system complexity, with single-family residential favoring unitary products and industrial process cooling requiring engineered central plant configurations.
- Residential:Single-family and multi-family dwellings in arid climate zones specify rooftop or window-mounted direct evaporative units. The southwestern United States maintains replacement cycles of seven to ten years, shorter than mechanical refrigeration equivalents due to lower first-cost sensitivity.
- Commercial:Retail, office, and hospitality facilities deploy packaged indirect and hybrid systems to meet California Title 24 economizer mandates. Large facility segments in Texas and New Mexico are pre-positioning specifications to align with anticipated federal efficiency enforcement timelines.
- Industrial:Process cooling for manufacturing, power generation, and petrochemical applications employs closed-circuit cooling towers and adiabatic pre-cooling. Great Lakes basin manufacturing corridors show persistent specification inertia toward mechanical refrigeration, fragmenting distributor service revenue streams.
- Agriculture:Controlled-environment agriculture operators in California's Central Valley retrofit hybrid evaporative-dehumidification systems to manage crop-specific microclimates. Greenhouse expansion is driving demand for integrated humidity control that pure evaporative configurations cannot provide.
Commercial applications command the largest installed base; Agriculture is expanding most quickly.
Technology:
Water exposure architecture and control sophistication separate commodity products from premium system categories.
- Open-Circuit:Direct water-to-air contact designs spray or cascade water through fill media, maximizing heat rejection efficiency at lowest capital cost. Cooling tower applications in power generation and heavy industry favor this approach where water quality permits.
- Closed-Circuit:Isolated coil configurations protect process fluids from atmospheric contamination and evaporation losses. Data center operators in water-scarce regions specify these systems to reduce makeup water consumption and comply with municipal restriction protocols.
- Adiabatic Cooling:Pre-cooling of ambient air through evaporative stages reduces mechanical refrigeration load without direct humidity addition. Hybrid adiabatic-mechanical systems are capturing precision manufacturing applications where humidity control excludes direct wet-bulb approaches.
- Advanced Control Systems:Machine learning-enabled variable-speed fan arrays and adaptive water distribution nozzles automate real-time wet-bulb depression optimization. Hyperscale operators deploy these architectures at full-facility scale within compressed procurement cycles.
Open-Circuit maintains volume leadership; Advanced Control Systems show the steepest expansion trajectory.
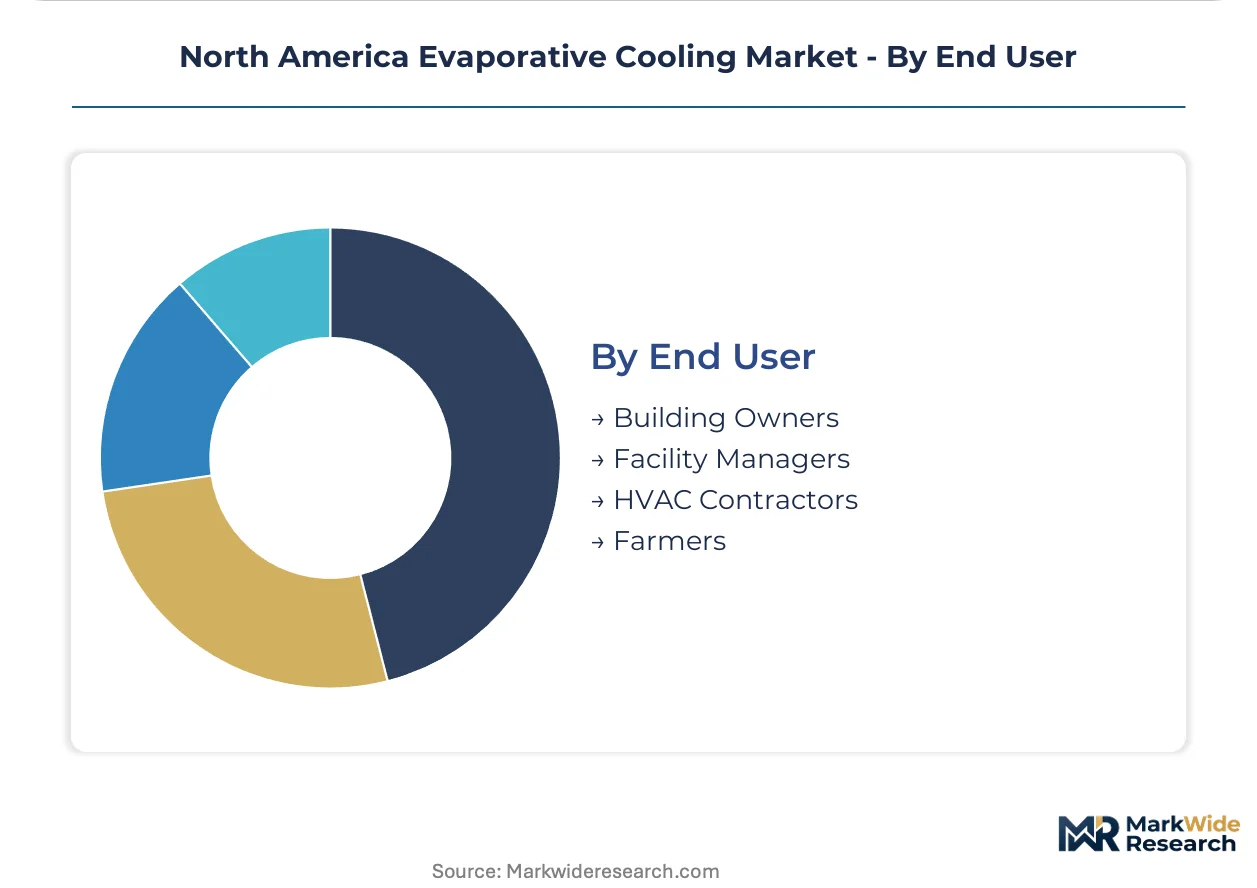
End User:
Technical sophistication and procurement authority shape specification behavior across buyer categories.
- Building Owners:Commercial real estate developers and owner-occupants prioritize first-cost and operating expense predictability. Title 24 compliance requirements in California are forcing specification upgrades toward indirect evaporative pre-cooling in large facilities.
- Facility Managers:Corporate and institutional operators unbundle after-sales service contracts from initial equipment procurement, treating water treatment and media replacement as separate operational expenditures. This behavior fragments traditional distributor revenue streams.
- HVAC Contractors:Installation and maintenance providers in secondary markets often lack specialized commissioning expertise for controls integration with Building Automation Systems. Capability gaps slow penetration of advanced evaporative configurations outside major metropolitan corridors.
- Farmers:Agricultural producers in California's Central Valley and southwestern U.S. regions specify systems based on crop-specific microclimate requirements and utility rebate availability. Water scarcity constraints in the Colorado River basin are limiting deployment feasibility despite optimal climate conditions.
Facility Managers represent the largest specification authority; Farmers are gaining share fastest as agricultural automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in the southwestern United States concentrate evaporative cooling procurement through tariff-advantaged assembly operations serving data center clusters. State-level water restrictions and utility rebate programs create divergent deployment economics across sub-regional markets.
Southwestern United States
Hyperscale data center operators in Phoenix and Las Vegas drive demand for indirect evaporative systems to reduce mechanical refrigeration loads. The U.S. Department of Energy's 10 CFR Part 431 efficiency mandates accelerate replacement cycles in commercial facilities across Arizona and Nevada. Arizona's Foreign Trade Zone No. 60 near Mesa anchors assembly operations for cooling media distribution into Nevada and California markets.
California
Title 24 Building Energy Efficiency Standards mandate economizer integration favoring indirect evaporative pre-cooling in large facilities. The California Energy Commission enforces water consumption disclosure requirements that reshape total cost-of-ownership calculations for facility managers. Controlled-environment agriculture operators in Fresno and Kern counties retrofit hybrid evaporative-dehumidification systems for crop-specific microclimate management.
Texas
Industrial process cooling in petrochemical corridors along the Gulf Coast sustains demand for closed-circuit cooling tower configurations. The Public Utility Commission of Texas oversees intermittent renewable energy pricing that affects operating cost comparisons against mechanical refrigeration. Houston and Dallas-Fort Worth metropolitan areas concentrate procurement authority for large facility upgrades ahead of anticipated federal efficiency enforcement timelines.
Great Lakes Basin
Manufacturing corridors in Michigan and Ohio show persistent specification inertia toward mechanical refrigeration despite evaporative cooling suitability during shoulder seasons. The U.S. Environmental Protection Agency administers Clean Water Act permitting that affects cooling tower blowdown discharge protocols. Detroit and Cleveland industrial clusters fragment distributor service revenue streams as facility managers unbundle after-sales contracts from initial equipment procurement.
Canada
Seasonal agricultural labor housing in southern Ontario and greenhouse operations in British Columbia's Fraser Valley represent emerging deployment channels for portable evaporative units. Natural Resources Canada administers energy efficiency regulations under the Energy Efficiency Act that parallel U.S. Department of Energy appliance standards. Toronto and Vancouver metropolitan areas concentrate commercial building stock where Title 24-equivalent economizer mandates face slower provincial adoption timelines.
North America Evaporative Cooling Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers capturing data center contracts while component fabricators serve residential replacement markets. The vendor base organizes around three archetypes: full-system integrators with controls expertise, cooling media specialists with captive pad manufacturing, and regional assembly operations serving utility rebate program specifications. Consolidation pressures concentrate among distributors lacking water chemistry service capabilities. Competitive moves center on vertical integration into cooling media production and geographic expansion through Foreign Trade Zone assembly operations.
Among integrated system providers, Baltimore Aircoil Company and SPX Cooling Technologies occupy positions anchoring large-scale industrial and hyperscale data center contracts. Munters exemplifies the hybrid adiabatic specialist archetype serving agricultural greenhouse and precision manufacturing applications where humidity control requirements exclude direct wet-bulb approaches. Portacool LLC represents the portable equipment fabricator tier addressing seasonal agricultural labor housing and outdoor event infrastructure across underpenetrated deployment channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Baltimore Aircoil Company |
| Portacool LLC |
| SPX Cooling Technologies |
| Munters |
| Hessaire Products Inc. |
| Phoenix Manufacturing Inc. |
| Evapco Group |
| Delta T LLC |
| Others |
Supply & Pricing Matrix
Cooling media pad materials originating from Mexico and Southeast Asian manufacturing clusters cascade through distributor markups into three distinct pricing tiers across the North American evaporative cooling market. Celdek and Kuul Comfort pad imports feed into regional assembly operations near Phoenix and Las Vegas, where Foreign Trade Zone advantages compress landed costs for hyperscale data center contractors while secondary market distributors absorb tariff volatility through inventory buffers.
Pricing Analysis
Short lead-time premiums compress procurement economics for data center operators facing eighteen-month facility commissioning deadlines, while spot inventory discounts attract residential replacement contractors in Arizona and Nevada. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale indirect systems with integrated controls from commodity direct evaporative units and portable seasonal equipment. Cost compression in the standard tier is intensifying because cooling media manufacturing concentrates in tariff-exposed geographies. Residential contractors show highest price sensitivity, while pharmaceutical cleanroom operators prioritize humidity control certification over first-cost considerations.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators mandate multi-supplier qualification for cooling media pads across Mexico, Malaysia, and Thailand production facilities. Manufacturing draws from cellulose-based media substrates, galvanized steel housings, and variable-speed fan motor assemblies as core inputs. Single-source vulnerability concentrates in Celdek pad chemistry formulations, exposing distributors to cross-border tariff volatility and extended replenishment cycles. Distribution runs through regional HVAC wholesalers serving utility rebate program specifications, with direct OEM relationships capturing data center and industrial process cooling verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. Department of Energy's 10 CFR Part 431 efficiency mandates construct a cost-of-compliance barrier that favors incumbent manufacturers with established test procedure expertise and federal procurement contract eligibility.
For Market Incumbents: Extend controls integration capabilities to capture facility management software interoperability contracts, defending against emerging HVAC-as-a-service entrants. Backward integration into cooling media production in Mexico-based Foreign Trade Zones reduces tariff exposure while accelerating lead times for Arizona and Nevada data center clusters. Certification investment in California Title 24 economizer pre-qualification locks out smaller competitors lacking commissioning expertise. For New Entrants and Emerging Players: E-commerce direct-to-contractor channels bypass established distributor networks in the portable evaporative cooler segment, capturing seasonal agricultural labor housing demand across northern Mexico and southwestern U.S. construction sites. Agricultural greenhouse retrofit applications in California's Central Valley represent the most penetrable white-space target, where hybrid evaporative-dehumidification system knowledge gaps fragment incumbent service capabilities. Target water chemistry service unbundling as the go-to-market angle, treating media replacement and scale inhibition as recurring revenue subscriptions rather than bundled after-sales add-ons. For Investors and Strategic Acquirers: Utility rebate program expansion announcements in Colorado River basin states are the leading indicator that replacement cycle acceleration will concentrate market share among compliant manufacturers. Five-to-ten year viability favors vertically integrated specialists with captive cooling media production and Foreign Trade Zone assembly positioning. Acquisition target archetype: regional distributors with water chemistry formulation expertise and established municipal utility relationships. The signal to watch is Arizona and Nevada municipal water restriction severity escalations that force closed-circuit system specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cooling Media Manufacturing Scale-Up | Mexico-based pad production captures Foreign Trade Zone advantages for Arizona data center supply. |
| Controls Integration Partnership | Building Automation System interoperability locks in hyperscale facility management software contracts. |
| Water Chemistry Service Unbundling | Recurring revenue subscriptions for scale inhibition separate from equipment procurement. |
| California Title 24 Pre-Qualification | Economizer mandate compliance creates specification gatekeeping for large facility segments. |
| Agricultural Greenhouse Retrofit Expansion | Hybrid evaporative-dehumidification addresses crop-specific microclimate requirements in Central Valley. |
Research Methodology
EPA WaterSense specifications, U.S. Department of Energy 10 CFR Part 431 filings, and California Energy Commission Title 24 compliance databases formed the secondary backbone, cross-referenced with utility rebate program documentation from Arizona Public Service, NV Energy, and Pacific Gas and Electric. Primary interviews with data center thermal management directors, HVAC contractor purchasing managers, and agricultural greenhouse operations supervisors validated equipment specification trends and procurement cycle timing. Bottom-up triangulation against top-down sectoral spending estimates anchored volume and value projections.
Historical trendline analysis across direct, indirect, hybrid, and portable product categories informed the analytical framework, with technology type, application vertical, and climate zone suitability driving segmentation dimensions. CAGRs derived from replacement cycle acceleration patterns in utility rebate territories and efficiency mandate compliance timelines. Forecast inputs incorporated Colorado River basin water allocation dispute resolutions and municipal restriction protocol escalations as scenario variables.
The model holds under stable utility rebate program funding and moderate tariff regimes; deviation in cooling media import duty structures or severe drought-driven water restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Cryosystem Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Middle East and Africa Cooling Systems Market