
 Middle East and Africa Cooling Systems Market | 2026-2036
Middle East and Africa Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cooling Systems Market Foresight
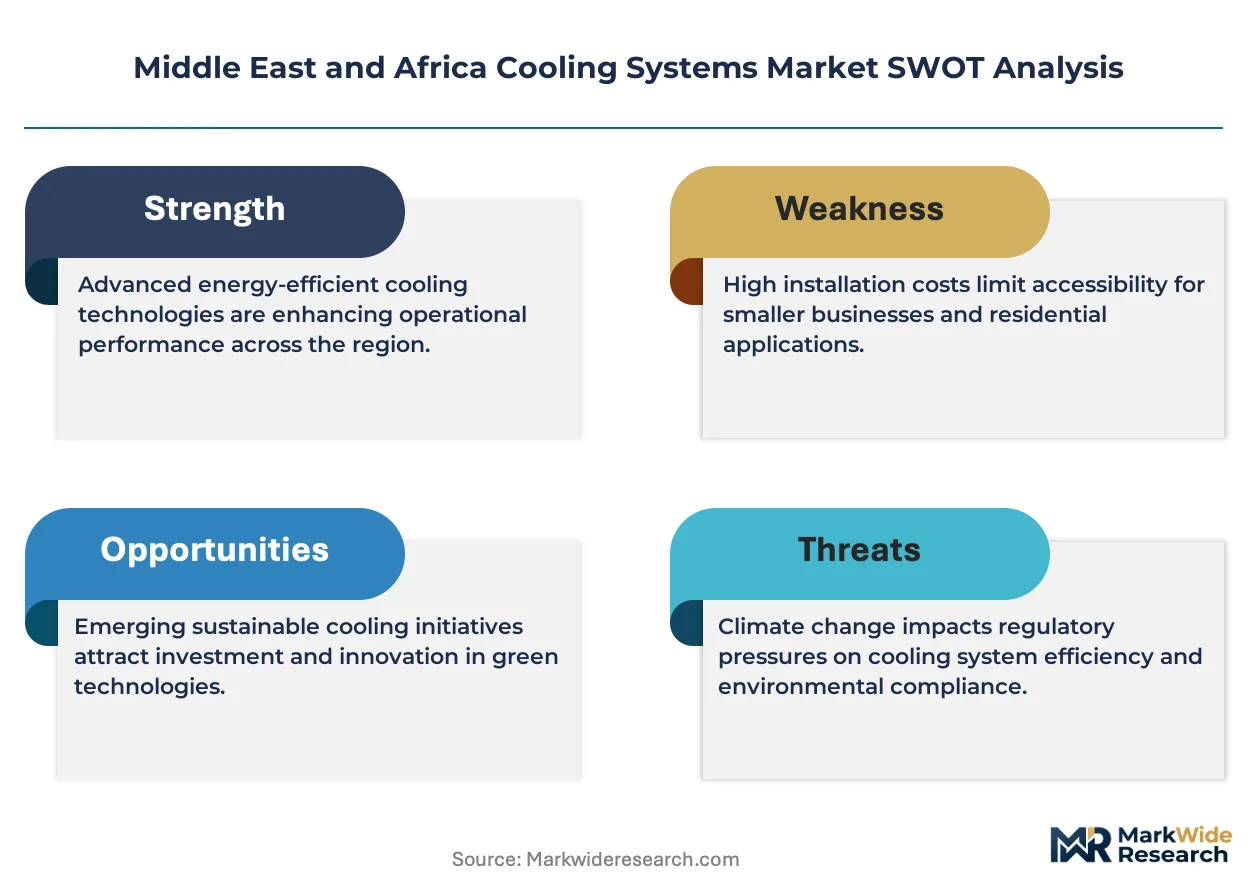
REACH compliance is repositioning equipment import requirements across North African trade corridors, compelling manufacturers to certify refrigerant containment and material safety before market entry. Carrier Global leverages its packaged chiller expertise to anchor large commercial projects in Saudi Arabia's giga-developments. Daikin Industries competes on inverter-driven compressor technology, while Thermax Limited sustains its industrial absorption chiller footprint across Nigeria's food processing corridors.
Middle East and Africa cooling systems comprise engineered heat rejection and temperature control equipment utilizing vapor-compression, absorption, or evaporative thermodynamic cycles to maintain specified thermal envelopes in built environments and industrial processes. These systems typically operate with refrigerants at saturated pressures between 1.5 and 30 bar, achieving coefficient of performance ratings from 2.5 to 6.0 depending on technology class and ambient design conditions. Air conditioners dominate residential and light commercial penetration across high-humidity coastal zones, while chillers command margin pools in district cooling and hospital applications where centralized plant economics outweigh distributed alternatives. Data centers represent the fastest-growing end user segment, with evaporative and water-cooled technologies displacing air-cooled configurations where water availability permits.
Saudi Arabia's SFDA and the UAE's MOHAP enforce equipment safety standards for hospital-grade cooling, while Egypt's national standards body aligns commercial HVAC efficiency benchmarks with regional energy transition commitments. South Africa's NRCS administers mandatory performance labeling that filters substandard imports from SADC distribution channels. Stakeholders must monitor how Gulf carbon neutrality pledges recalibrate district cooling procurement criteria and refrigerant phase-down timelines.
Market Dynamics
Data center thermal loads across Gulf Cooperation Council states are compressing equipment replacement cycles and forcing absorption chiller manufacturers to retool for higher-capacity vapor-compression alternatives. This demand surge from hyperscale facilities is restructuring supplier priorities across the Middle East and Africa cooling systems landscape.
Growth Catalysts
- Saudi Arabia's building energy codes:The national sustainability framework mandates minimum efficiency thresholds for commercial chillers, accelerating retrofit demand in Riyadh and Jeddah commercial stock.
- Data center liquid cooling:Direct-to-chip and immersion architectures are displacing traditional air-cooled configurations in Dubai's hyperscale facilities where power density exceeds 30 kW per rack.
- Egypt's healthcare infrastructure expansion:New hospital construction under the Universal Health Insurance scheme requires centralized chiller plants with redundancy protocols, concentrating procurement in Cairo and Alexandria corridors.
Market Restraints
- Refrigerant supply concentration:Hydrofluorocarbon feedstock availability depends on concentrated Chinese and Indian chemical manufacturing, exposing regional assemblers to input cost volatility and quota restrictions.
- Water scarcity in inland zones:Evaporative cooling technologies face deployment limits across Saudi Arabia's Najd plateau and South Africa's Karoo basin, constraining technology selection for industrial applications.
- REACH alignment costs:North African manufacturers serving EU-bound equipment must certify refrigerant containment systems and material safety documentation, extending compliance timelines by 8-14 months.
Strategic Opportunities
- Nigeria's food processing corridors:Absorption chiller deployment for cold chain preservation remains underpenetrated outside Lagos and Kano, offering first-mover positioning for industrial-scale thermal management.
- UAE district cooling privatization:Emirates District Cooling and Tabreed procurement frameworks now permit independent power producer-style concessions, opening asset ownership models to specialized operators.
- Solar-thermal absorption hybridization:Concentrated solar thermal integration with lithium bromide chillers is expanding into Morocco's Ouarzazate solar complex and Jordan's Ma'an development zone.
Industry Challenges
- Refrigerant handling certification:SFDA and MOHAP enforcement of technician licensing for hospital-grade systems has created qualified installer shortages across Riyadh and Abu Dhabi, extending commissioning timelines.
- Legacy control system integration:Building management system protocols from 1990s-era chiller plants in Dubai's commercial stock require middleware development for IoT-enabled predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cooling Systems Market |
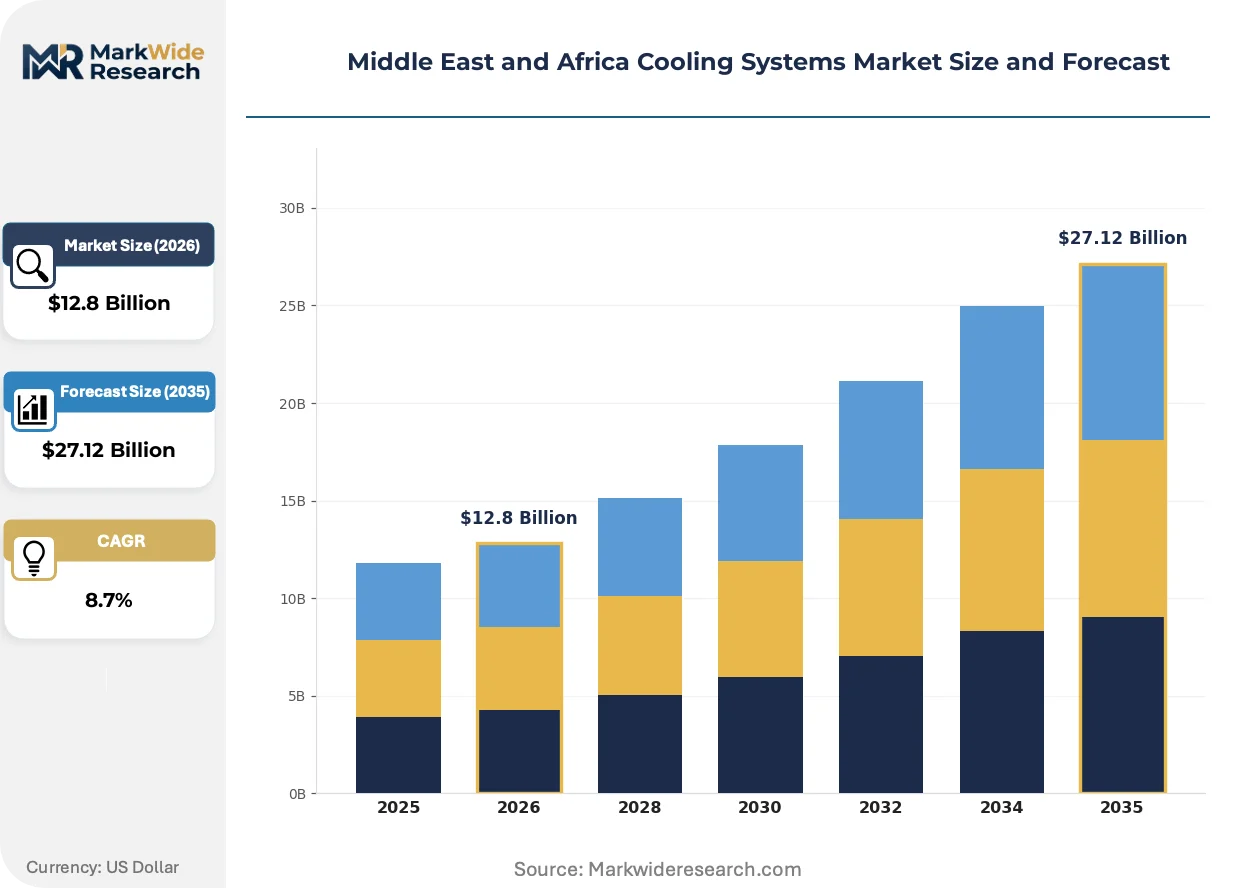
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Chillers, Heat Pumps, Refrigerators Application: Commercial, Residential, Industrial, Automotive Technology: Evaporative Cooling, Air Cooled, Water Cooled, Thermoelectric End User: Hospitals, Data Centers, Manufacturing Facilities, Retail Stores |
| Companies Covered | Alfa Laval AB, Thermax Limited, Danfoss AS, Xylem Inc., Parker Hannifin Corp., Daikin Industries, Mitsubishi Electric, Carrier Global, Schneider Electric, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cooling Systems Market Shifts & Advancements
Equipment manufacturers across the Middle East and Africa cooling systems market are reconfiguring product architectures around three converging pressures: refrigerant phase-down mandates, data center power density escalation, and district cooling asset privatization. These forces are compressing development cycles and redrawing competitive boundaries.
Magnetic bearing centrifugal compressors are eliminating oil-lubricated mechanical seals in large-tonnage chiller applications. Dubai's district cooling operators are specifying oil-free designs for new megaproject connections to reduce maintenance intervals. This technology is expanding into Saudi Arabia's giga-development central plants where 5,000-ton-plus capacity requirements dominate procurement specifications.
The UAE's F-Gas Regulation alignment and Saudi Arabia's national refrigerant management framework are accelerating hydrofluoroolefin adoption in new equipment. Chiller manufacturers must redesign heat exchanger circuits and compressor displacement volumes to accommodate lower-global-warming-potential working fluids. Hospital and pharmaceutical cold chain applications face the most stringent containment verification requirements under SFDA and MOHAP enforcement protocols.
Performance-based service contracting is displacing traditional preventive maintenance agreements in commercial and industrial segments. Equipment suppliers now guarantee energy consumption thresholds and uptime availability, transferring operational risk from facility managers to OEM service organizations. This model concentrates most visibly in Dubai and Abu Dhabi district cooling networks where Emirates District Cooling and Tabreed have standardized outcome-based procurement templates.
Middle East and Africa Cooling Systems Market Segmentation
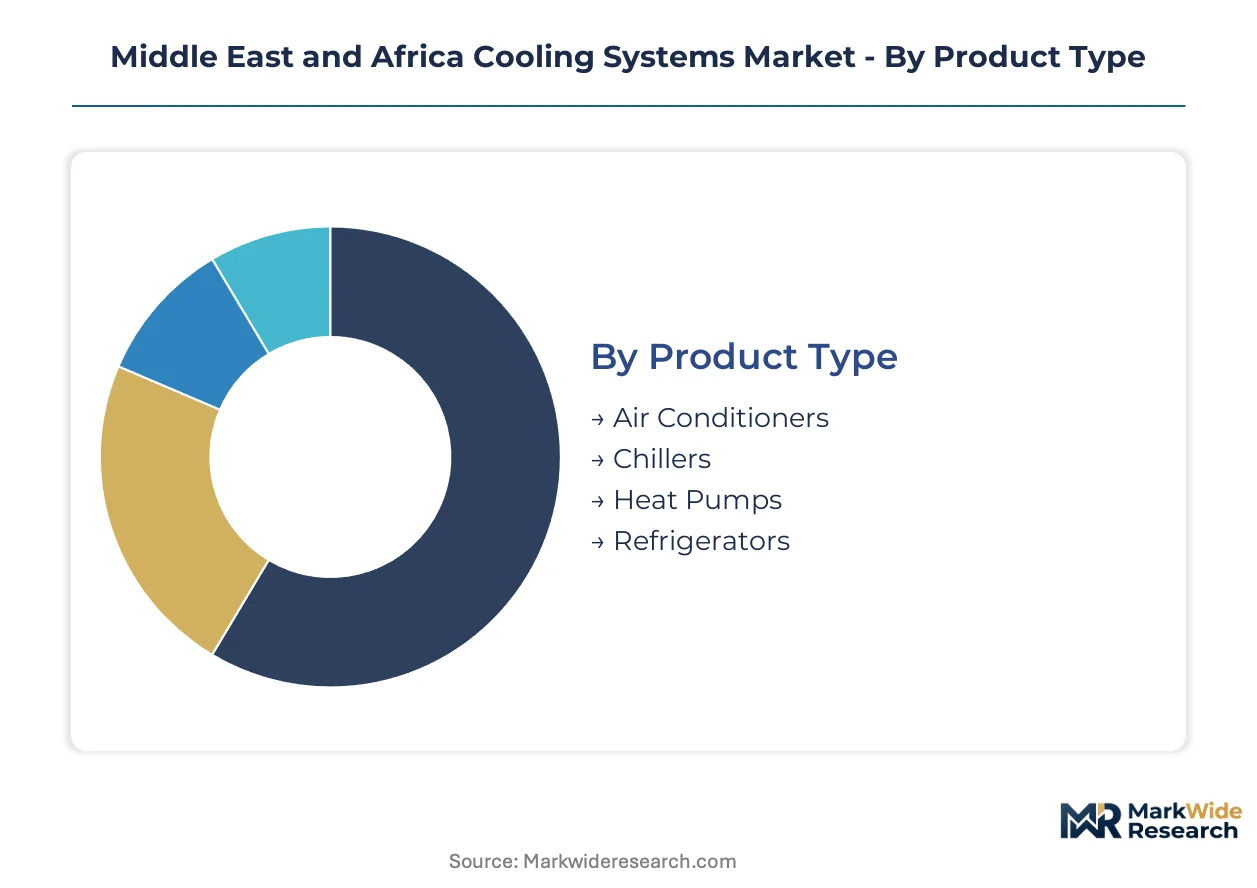
Cooling system procurement across the Middle East and Africa fragments sharply by thermal load profile, infrastructure maturity, and regulatory exposure. Equipment specification varies dramatically between Saudi Arabia's giga-developments and Nigeria's distributed industrial corridors.
Product Type:
Supply concentration tilts toward chiller manufacturers with district cooling relationships, while air conditioner assemblers compete on import logistics and distribution reach.
- Chillers:Centralized vapor-compression and absorption plants handle tonnage requirements above 500 kW for district cooling networks and hospital central plants. Demand concentrates in Dubai and Abu Dhabi megaproject developments where Emirates District Cooling and Tabreed specify oil-free magnetic bearing designs for reduced maintenance intervals.
- Air Conditioners:Distributed split and packaged units dominate residential and light commercial penetration across high-humidity coastal zones from Jeddah to Lagos. Saudi Arabia's building energy code enforcement is accelerating demand for inverter-driven compressor technology in Riyadh and Jeddah commercial retrofits.
- Heat Pumps:Reversible heating-cooling units gain traction in South Africa's NRCS-regulated commercial stock and Morocco's solar-thermal hybrid installations.
- Refrigerators:Cold chain preservation equipment serves Nigeria's food processing corridors and pharmaceutical distribution networks under SFDA and MOHAP cold chain protocols.
Today's leader: Chillers. Tomorrow's challenger: Heat Pumps.
Application:
Cost tier differentiation separates premium-specification commercial installations from price-sensitive residential volume plays.
- Commercial:Office towers, hotels, and retail complexes require centralized chiller plants with building management system integration. Dubai's commercial stock drives demand for IoT-enabled predictive maintenance platforms and middleware solutions for legacy 1990s-era control system retrofits.
- Industrial:Process cooling and cold chain infrastructure command absorption chiller deployments where waste heat recovery economics justify capital intensity. Nigeria's food processing corridors outside Lagos and Kano remain underpenetrated for industrial-scale thermal management.
- Residential:High-ambient split system penetration dominates across Gulf Cooperation Council states with seasonal cooling degree-day profiles exceeding 3,000 annually.
- Automotive:Mobile air conditioning systems face refrigerant phase-down pressures under Saudi Arabia's national refrigerant management framework and UAE F-Gas Regulation alignment.
Commercial applications anchor current revenue. Industrial segments are climbing the fastest as manufacturing reshoring accelerates across Egypt and Morocco.
Technology:
Volume deployment favors air-cooled configurations where water scarcity constrains evaporative alternatives.
- Water Cooled:Shell-and-tube and plate heat exchanger configurations achieve coefficient of performance ratings above 5.0 in Dubai's hyperscale data centers where power density exceeds 30 kW per rack and direct-to-chip liquid cooling displaces traditional air-cooled architectures.
- Evaporative Cooling:Adiabatic and cooling tower technologies face deployment limits across Saudi Arabia's Najd plateau and South Africa's Karoo basin due to water availability constraints, though they dominate where Gulf seawater access permits.
- Air Cooled:Condenser fan-driven rejection systems prevail in distributed commercial and residential applications with lower tonnage requirements and maintenance access limitations.
- Thermoelectric:Solid-state Peltier cooling occupies niche medical and precision instrumentation applications with modest thermal loads and extreme reliability requirements.
Water cooled technology commands premium margins. Air cooled configurations are gaining share fastest through residential volume expansion.
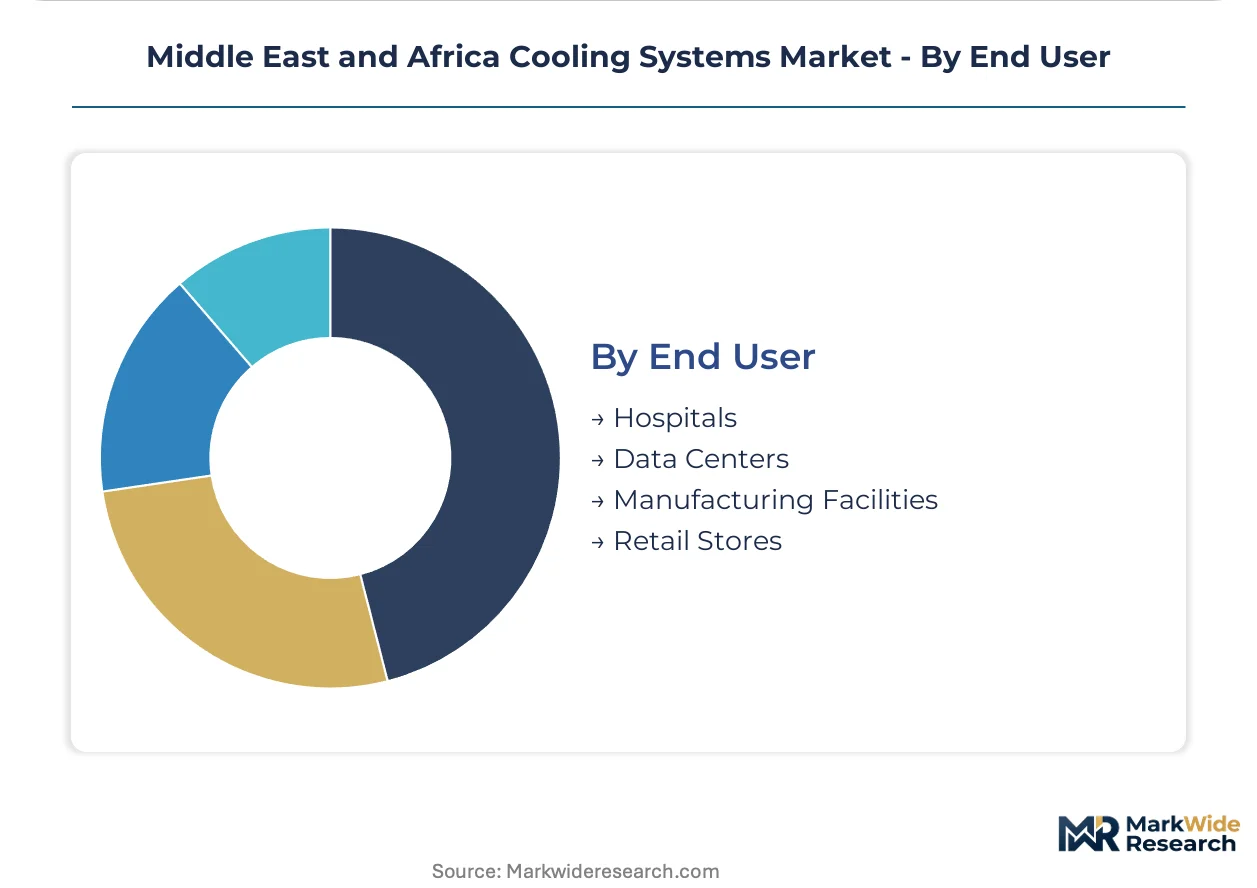
End User:
Customer type determines specification stringency, with hospital and pharmaceutical applications facing containment verification requirements that filter supplier eligibility.
- Data Centers:Hyperscale facilities across Gulf Cooperation Council states compress equipment replacement cycles and force absorption chiller manufacturers to retool for higher-capacity vapor-compression alternatives. Dubai's facilities specify evaporative and water-cooled technologies where water availability permits.
- Hospitals:Centralized chiller plants with N+1 redundancy protocols serve Egypt's Universal Health Insurance scheme expansion in Cairo and Alexandria corridors. SFDA and MOHAP enforcement of technician licensing for hospital-grade systems has created qualified installer shortages across Riyadh and Abu Dhabi.
- Manufacturing Facilities:Process cooling loads vary from food processing hygiene requirements to plastics injection molding thermal stability needs across Nigeria's industrial zones.
- Retail Stores:Distributed split systems and packaged rooftop units serve shopping mall and supermarket applications with standardized maintenance protocols and shorter equipment lifecycles.
Data centers represent the steepest expansion trajectory. Hospital infrastructure offers the most defensible margin pools through regulatory compliance barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa cooling systems industry traces its commercial scale to the 1970s oil boom, when Gulf states imported American and European chiller technology for the first generation of air-conditioned office towers and residential compounds.
United Arab Emirates
District cooling networks in Dubai and Abu Dhabi serve megaproject developments including Expo City and Saadiyat Island. The UAE's F-Gas Regulation alignment mandates hydrofluoroolefin transition timelines for new equipment. Emirates District Cooling and Tabreed procurement frameworks now permit independent power producer-style concessions, opening asset ownership to specialized operators.
Saudi Arabia
Giga-developments including NEOM and the Red Sea Project are driving centralized chiller plant specifications above 5,000-ton capacity. The national sustainability framework enforces minimum efficiency thresholds for commercial chillers under stricter building energy codes. Riyadh and Jeddah commercial stock is accelerating retrofit demand as retrofit deadlines approach.
Egypt
New hospital construction under the Universal Health Insurance scheme requires centralized chiller plants with N+1 redundancy protocols. The national standards body aligns commercial HVAC efficiency benchmarks with regional energy transition commitments. Cairo and Alexandria corridors concentrate procurement for healthcare infrastructure expansion.
South Africa
The NRCS administers mandatory performance labeling that filters substandard imports from SADC distribution channels. Cold chain preservation for pharmaceutical distribution networks operates under stringent containment verification. The Karoo basin faces deployment limits for evaporative cooling technologies due to water availability constraints.
Nigeria
Absorption chiller deployment for food processing cold chain preservation remains underpenetrated outside Lagos and Kano industrial zones. The country's national standards body is developing alignment with REACH-equivalent material safety documentation requirements. First-mover positioning for industrial-scale thermal management is available across northern food processing corridors.
Middle East and Africa Cooling Systems Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with packaged equipment expertise. Market concentration is moderate, with global HVAC specialists competing against regional system integrators and local assembly operations. Three archetypes dominate: full-system OEMs with district cooling relationships, component suppliers with heat exchanger specialization, and regional fabricators serving price-sensitive retrofit segments. Strategic moves center on technology licensing partnerships for magnetic bearing compressor deployment and outcome-based service contracting that transfers operational risk to OEM service organizations.
Within the full-system OEM tier, Carrier Global and Daikin Industries exemplify contrasting technology strategies, while Thermax Limited anchors industrial absorption chiller positioning across African food processing corridors. Component specialists including Alfa Laval AB and Danfoss AS occupy positions upstream of final equipment assembly. The competitive dynamic pits European and Japanese technology licensors against Gulf-based system integrators seeking localized production credentials under Saudi Arabia's national sustainability framework procurement preferences.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Thermax Limited |
| Danfoss AS |
| Xylem Inc. |
| Parker Hannifin Corp. |
| Daikin Industries |
| Mitsubishi Electric |
| Carrier Global |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Captive compressor manufacturing by Gulf-based system integrators anchors both supply security and pricing power for large-tonnage chiller contracts. This backward integration shields regional assemblers from hydrofluorocarbon feedstock volatility while enabling aggressive positioning on Saudi giga-development tenders.
Pricing Analysis
Equipment-plus-service bundles dominate district cooling procurement, while unbundled transactional sales prevail in residential split-system channels. Price differentiation rests on magnetic bearing certification and N+1 redundancy guarantees, with hospital-grade specifications commanding substantial premiums over commercial equivalents. Cost compression in standard-efficiency air-cooled segments is intensifying because Chinese component imports face quota restrictions. Small residential installers exhibit highest price sensitivity; hyperscale data center operators prioritize uptime availability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for customized chiller plants above 5,000-ton capacity. Manufacturing concentrates in China, India, and South Korea for compressor castings, brazed heat exchangers, and electronic expansion valves. Component sourcing draws from concentrated refrigerant feedstock production and rare-earth magnet suppliers. Single-source vulnerability in magnetic bearing assemblies poses structural risk. Distribution runs through authorized dealer networks for commercial retrofit and district cooling operator direct contracts for greenfield megaprojects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa cooling systems market functions as a stable compounder, with data center thermal load escalation driving sustained equipment replacement demand across Gulf Cooperation Council states.
For Market Incumbents: To counter refrigerant phase-down compliance cost escalation, deepen backward integration into heat exchanger fabrication and secure long-term hydrofluoroolefin supply agreements. Prioritize certification investment for SFDA and MOHAP hospital-grade containment protocols to filter mid-tier competitors from premium procurement pools. For New Entrants and Emerging Players: Nigeria's food processing corridors outside Lagos and Kano represent the most penetrable white-space target for absorption chiller deployment. Solar-thermal hybrid installations in Morocco's Ouarzazate complex offer technology differentiation entry. Pursue joint-venture structures with established Gulf system integrators to bypass distributor channel control. For Investors and Strategic Acquirers: Roll-up economics work for regional service organizations with predictive maintenance platform capabilities because district cooling privatization transfers long-term operational risk to specialized operators. The five-to-ten-year viability thesis rests on recurring revenue streams from outcome-based contracting. Target mid-cap specialists with Tabreed or Emirates District Cooling framework approvals. Monitor F-Gas Regulation enforcement timelines as inflection indicator for refrigerant transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Eliminates oil-lubricated seals for Dubai district cooling maintenance reduction. |
| Hydrofluoroolefin Heat Exchanger Redesign | Accommodates lower-GWP working fluids under UAE F-Gas alignment mandates. |
| Outcome-Based Service Contracting | Transfers operational risk from facility managers to OEM service organizations. |
| Solar-Thermal Absorption Hybridization | Integrates concentrated solar thermal with lithium bromide chillers in Morocco. |
| Hospital-Grade Containment Certification | Meets SFDA and MOHAP enforcement protocols for pharmaceutical cold chain. |
Research Methodology
Coverage spans Gulf Cooperation Council states, North Africa, and sub-Saharan Africa, with primary inputs from each regional cluster. The approach combines interviews with district cooling procurement directors, hospital facilities managers, data center engineering leads, and industrial plant operators with secondary validation from customs trade data, national standards body filings, and equipment manufacturer technical documentation. Bottom-up and top-down triangulation cross-checks regional volume estimates against aggregate demand indicators.
Rate-of-change decomposition separates equipment replacement cycles from net capacity additions across the projection horizon. The analytical framework models product type, application, technology, and end-user dimensions alongside regulatory compliance tier. CAGRs were synthesized from equipment shipment trajectories and megaproject development pipelines. Forecast inputs include hyperscale data center power density specifications and building energy code enforcement schedules.
Underlying measurement precision varies by segment; district cooling and hospital infrastructure carry tighter precision than distributed residential channels. Forecasts reflect assumptions regarding refrigerant quota availability and solar-thermal subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Solar Fan Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Solar Cooling Market