
 Global Condensing Unit Market | 2026-2036
Global Condensing Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Condensing Unit Market Foresight
Wholesale distribution is fragmenting as direct OEM-to-contractor relationships erode traditional distributor roles. Carrier Global Corporation leverages its service network to sustain aftermarket revenue. Daikin Industries anchors volume in Asia through localized manufacturing platforms.
A condensing unit integrates compressor, condenser, and controls into a single enclosure that liquefies high-pressure refrigerant vapor through heat rejection, typically operating between -40°C and 15°C saturated suction temperature depending on application. Scroll compressor technology dominates commercial refrigeration installations for its part-load efficiency. Air-cooled configurations lead unit shipments in data center cooling due to lower water treatment burdens. Microchannel condensers gain share in food processing where charge reduction and corrosion resistance justify premium positioning.
EPA SNAP rules and EU F-Gas Regulation restrict hydrofluorocarbon refrigerants, forcing redesigns toward CO2 and hydrocarbon architectures. ISO 5149 and ASHRAE 15 safety standards govern machinery room ventilation and charge limits, adding compliance cost that favors integrated system suppliers. Stakeholders must track refrigerant-phase-down schedules against compressor platform development timelines to avoid stranded inventory.
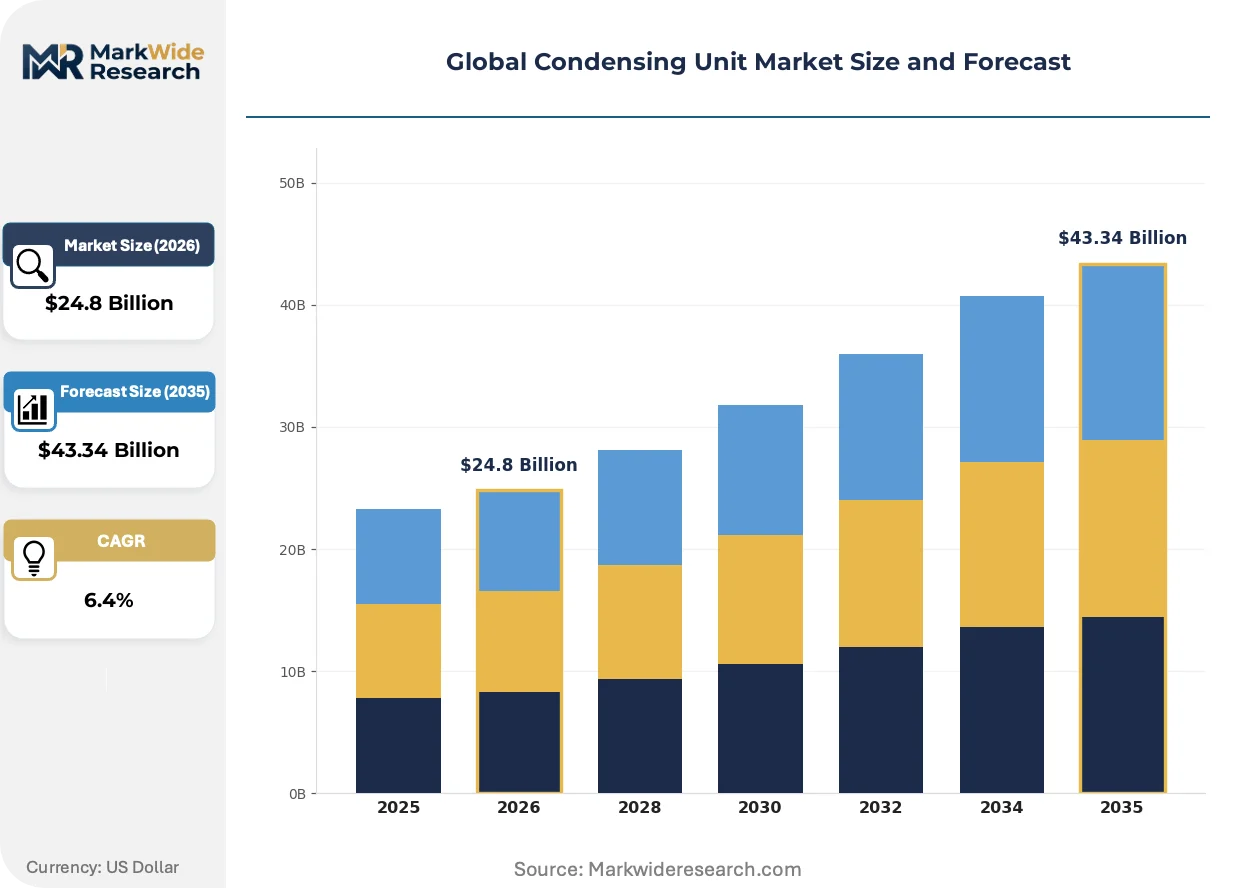
Market Dynamics
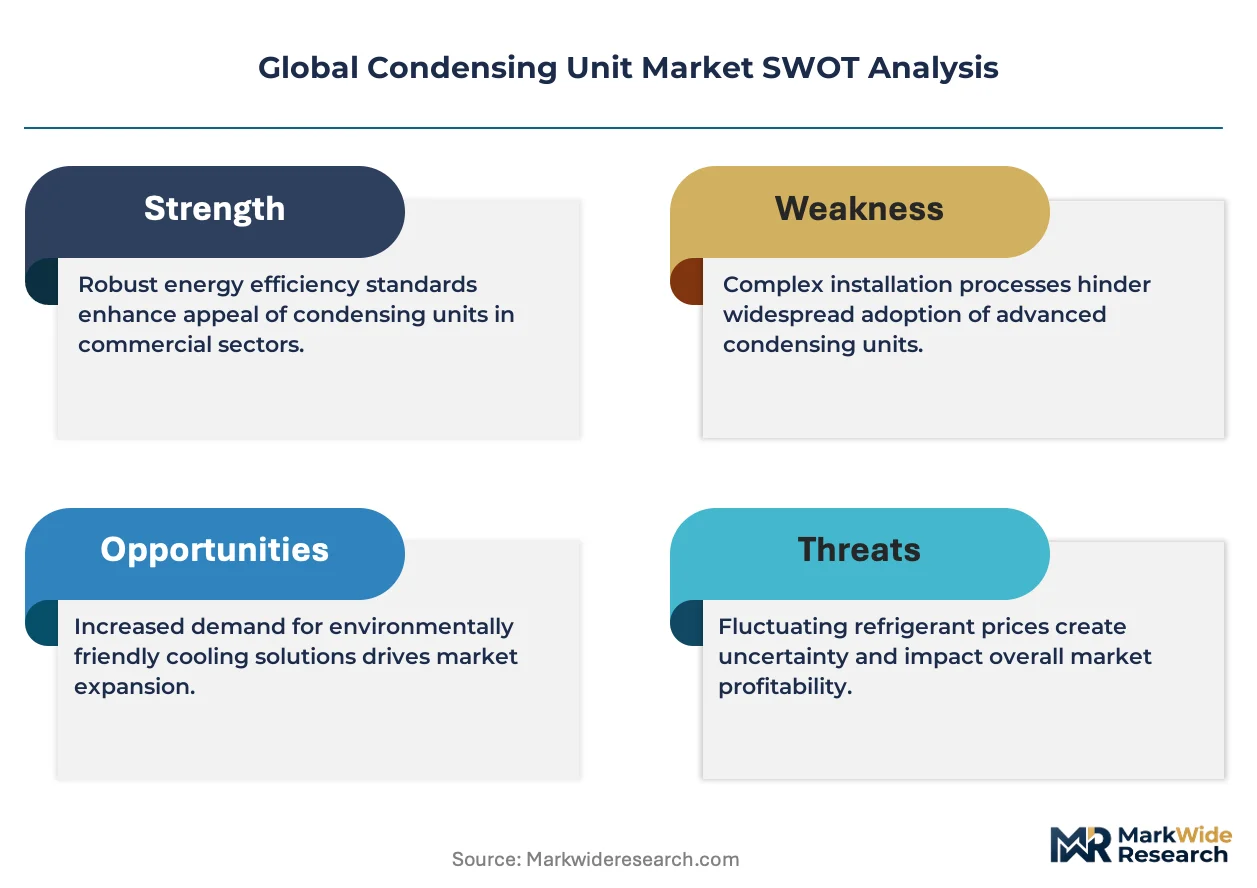
Refrigerant-phase-down mandates under EPA SNAP and EU F-Gas Regulation are forcing compressor platform redesigns, compressing development timelines while cold storage operators accelerate equipment replacement ahead of compliance deadlines.
Growth Catalysts
- Pharmaceutical Cold Chain:Vaccine distribution networks in Germany and Japan require ultra-low-temperature condensing units with charge-optimized CO2 architectures.
- EPA SNAP Rules:Hydrofluorocarbon restrictions in the United States trigger retrofit demand across existing supermarket refrigeration infrastructure.
- Microchannel Condensers:Food processors in the Netherlands adopt aluminum microchannel coils to reduce refrigerant charge and extend corrosion resistance in washdown environments.
Market Restraints
- Copper Price Volatility:Raw material swings in condenser coil production compress margin visibility for equipment manufacturers sourcing from Chilean and Peruvian concentrate.
- Compressor Supply Concentration:Scroll compressor manufacturing clusters in China and Thailand create geographic single-point vulnerability for OEM assembly lines.
- Charge Limit Constraints:ASHRAE 15 safety standards cap hydrocarbon refrigerant quantities per machinery room, restricting unit capacity in dense urban installations.
Strategic Opportunities
- Indian Cold Storage Buildout:FSSAI enforcement of temperature-controlled food distribution creates procurement windows for transcritical CO2 units in Mumbai and Delhi logistics corridors.
- Data Center Liquid Cooling Hybridization:Air-cooled condensing units paired with rear-door heat exchangers capture edge computing deployments seeking water-free rejection.
- EU Green Deal Incentives:Renovation wave subsidies in France and Italy accelerate replacement of R404A systems with low-GWP alternatives in hospitality and retail.
Industry Challenges
- Refrigerant Transition Talent Gap:Service technician certification for flammable refrigerant handling lags equipment deployment in markets with compressed phase-down schedules.
- Legacy Control Integration:Building management system protocols in existing commercial refrigeration infrastructure resist seamless integration with IoT-enabled condensing unit controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Condensing Unit Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Evaporative-Cooled, Remote Condensing Units, Microchannel Condensers Technology: Scroll Compressors, Reciprocating Compressors, Screw Compressors, Centrifugal Compressors, Magnetic Bearing Compressors Application: Commercial Refrigeration, Industrial Cooling, Data Center Cooling, Pharmaceutical Storage, Food Processing End User: Cold Storage Facilities, Food & Beverage Companies, Data Management Centers, Pharmaceutical Manufacturers, Hospitality Establishments |
| Companies Covered | Emerson Electric Co., Carrier Global Corporation, Daikin Industries, Ltd., Danfoss, GEA Group Aktiengesellschaft, BITZER SE, Johnson Controls International plc, Mitsubishi Electric Corporation, Trane Technologies plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Condensing Unit Market Shifts & Advancements
Equipment architecture is converging around charge reduction and connectivity, with refrigerant chemistry and control intelligence advancing in parallel rather than sequentially.
Variable-speed scroll compressors with integrated inverter drives are collapsing the efficiency penalty between part-load and full-load operation in supermarket rack systems. Retail chains in California and Texas specify these packages to meet utility demand-response incentives while maintaining case temperature stability. The technology is collapsing the historical trade-off between first cost and lifecycle energy performance that favored fixed-speed units in budget-constrained bids.
The EU F-Gas Regulation's 2030 phase-down steps are compressing allowable global-warming-potential thresholds for new equipment placed on the market. OEM engineering teams in Italy and Germany accelerate transcritical CO2 platform development while maintaining R290 hydrocarbon options for smaller capacity points. Commercial refrigeration contractors face compressed retraining timelines to certify on flammable refrigerant safety protocols before the 2027 step-change.
Direct OEM-to-contractor digital procurement platforms are eroding traditional wholesale distributor margins in commercial HVAC and refrigeration equipment. Large mechanical contractors in Texas and Florida negotiate frame agreements with Carrier and Daikin for condensing unit skids, bypassing regional distribution inventory. This channel compression is most visible in retrofit-heavy markets where specification authority rests with national service accounts rather than local design-build firms.
Global Condensing Unit Market Segmentation
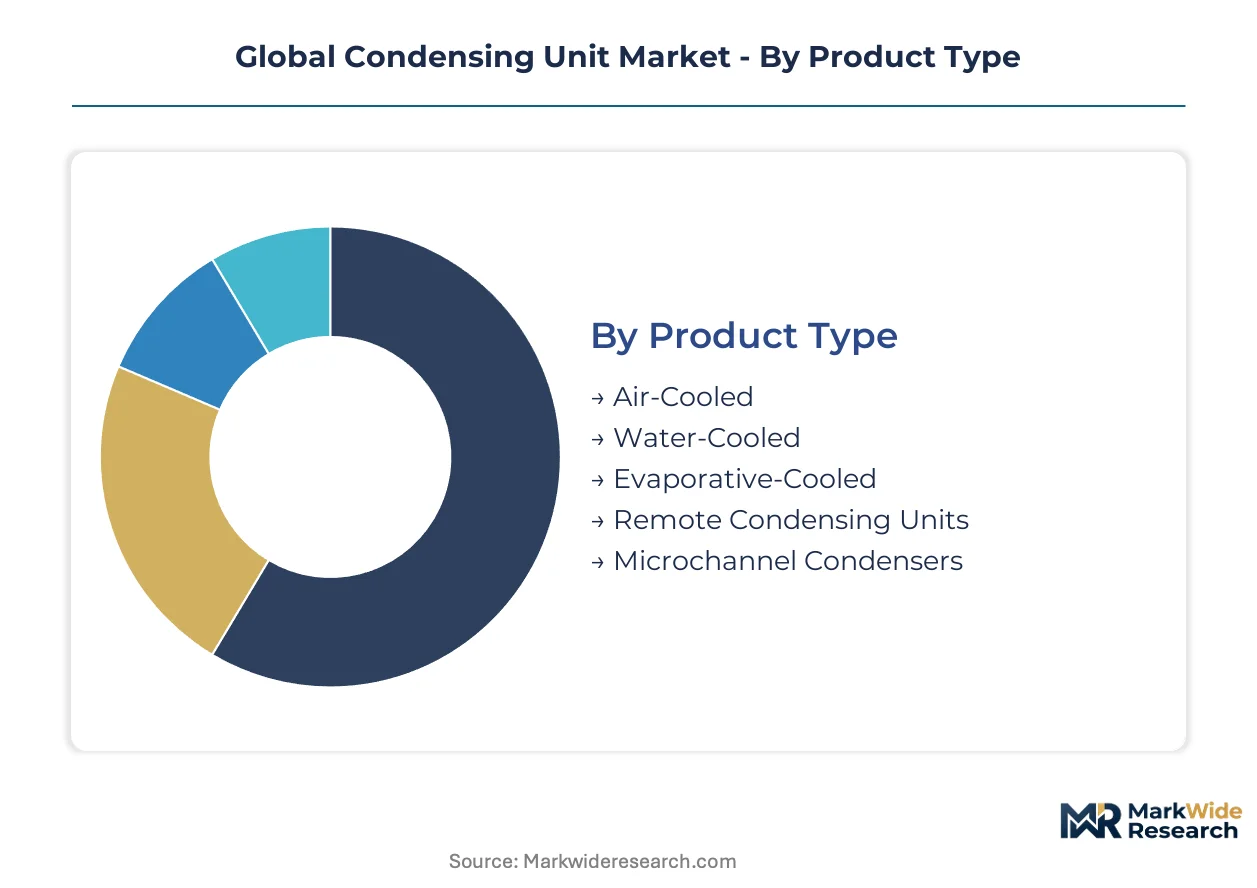
Condensing unit procurement patterns diverge sharply across cooling architectures, compressor technologies, and end-use thermal loads. Specification authority sits with distinct stakeholder groups in each slice—facility engineers, refrigeration contractors, or HVAC consultants—shaping how OEMs configure product portfolios and channel strategy.
Product Type:
Mature air-cooled designs dominate installed base volumes while emerging microchannel architectures capture specification authority in charge-constrained applications.
- Air-Cooled:Fin-and-tube coils reject heat directly to ambient air through propeller or centrifugal fans, eliminating water treatment infrastructure. Data centers in Texas and Arizona specify these units for edge computing nodes where municipal water availability is unreliable. ASHRAE 90.1 efficiency thresholds are compressing allowable energy use ratios for new installations.
- Microchannel Condensers:Aluminum multiport tubes with louvered fins reduce internal volume by 40-60% versus round-tube designs, slashing refrigerant charge requirements. Dutch food processors deploy these in washdown environments where corrosion resistance extends coil life. EU F-Gas phase-down schedules accelerate substitution for conventional copper-aluminum coils.
- Water-Cooled:Shell-and-tube or plate heat exchangers achieve higher condensing pressures in high-ambient conditions through cooling tower integration.
- Evaporative-Cooled:Adiabatic pre-cooling of condenser air reduces peak power draw in desert climates with moderate wet-bulb depression.
- Remote Condensing Units:Split configurations separate compressor/condenser assemblies from evaporator loads, enabling machinery room consolidation.
Air-cooled configurations handle the majority of throughput; microchannel condensers are gaining share fastest on regulatory pressure.
Technology:
Cost tier segmentation separates premium magnetic-bearing platforms from standard scroll offerings, with screw compressors occupying the mid-range industrial position.
- Scroll Compressors:Orbiting and fixed scrolls compress refrigerant vapor with minimal re-expansion losses, delivering superior part-load efficiency. Supermarket chains in California retrofit existing racks with variable-speed scroll packages to capture utility demand-response incentives. Integrated inverter drives are collapsing the first-cost premium versus fixed-speed alternatives.
- Screw Compressors:Twin helical rotors handle large refrigerant volumes across wide pressure ratios, suited to industrial process cooling above 100 kW. Cold storage facilities in Germany specify these for transcritical CO2 booster systems operating at 80-120 bar discharge pressures. Oil management complexity adds maintenance overhead that favors integrated system suppliers.
- Reciprocating Compressors:Piston-cylinder architectures persist in small-capacity commercial units where capital constraints dominate lifecycle economics.
- Centrifugal Compressors:Dynamic compression stages serve district cooling and large industrial loads above 500 kW with high isentropic efficiency.
- Magnetic Bearing Compressors:Oil-free operation eliminates friction losses and maintenance intervals, commanding specification in mission-critical pharmaceutical storage.
Scroll technology anchors volume across commercial applications; magnetic-bearing systems are expanding most quickly in ultra-low-temperature pharmaceutical distribution.
Application:
Customer type segmentation distinguishes facility-owner procurement from contractor-specified projects, with divergent emphasis on first cost versus lifecycle performance.
- Commercial Refrigeration:Display case and walk-in cooler loads require condensing units operating between -25°C and 10°C saturated suction temperature. EPA SNAP restrictions on R404A and R507A force equipment replacement cycles in US supermarket infrastructure. Contractors in Florida and Texas negotiate national service agreements bypassing traditional distribution channels.
- Data Center Cooling:Precision air conditioning and liquid-cooling rejection loops demand high reliability with minimal water use. Air-cooled condensing units paired with rear-door heat exchangers capture edge computing deployments in water-stressed regions. PUE optimization pressures favor variable-capacity compressor modulation.
- Industrial Cooling:Process refrigeration for chemical and petrochemical plants requires robust construction for continuous duty cycles.
- Pharmaceutical Storage:Ultra-low-temperature distribution networks for vaccines and biologics mandate charge-optimized CO2 architectures with redundant capacity.
- Food Processing:Blast freezing and chilled water loads combine aggressive temperature pull-down with corrosion-resistant coil specifications.
Commercial refrigeration handles the majority of installed base; data center cooling is climbing the fastest on digital infrastructure expansion.
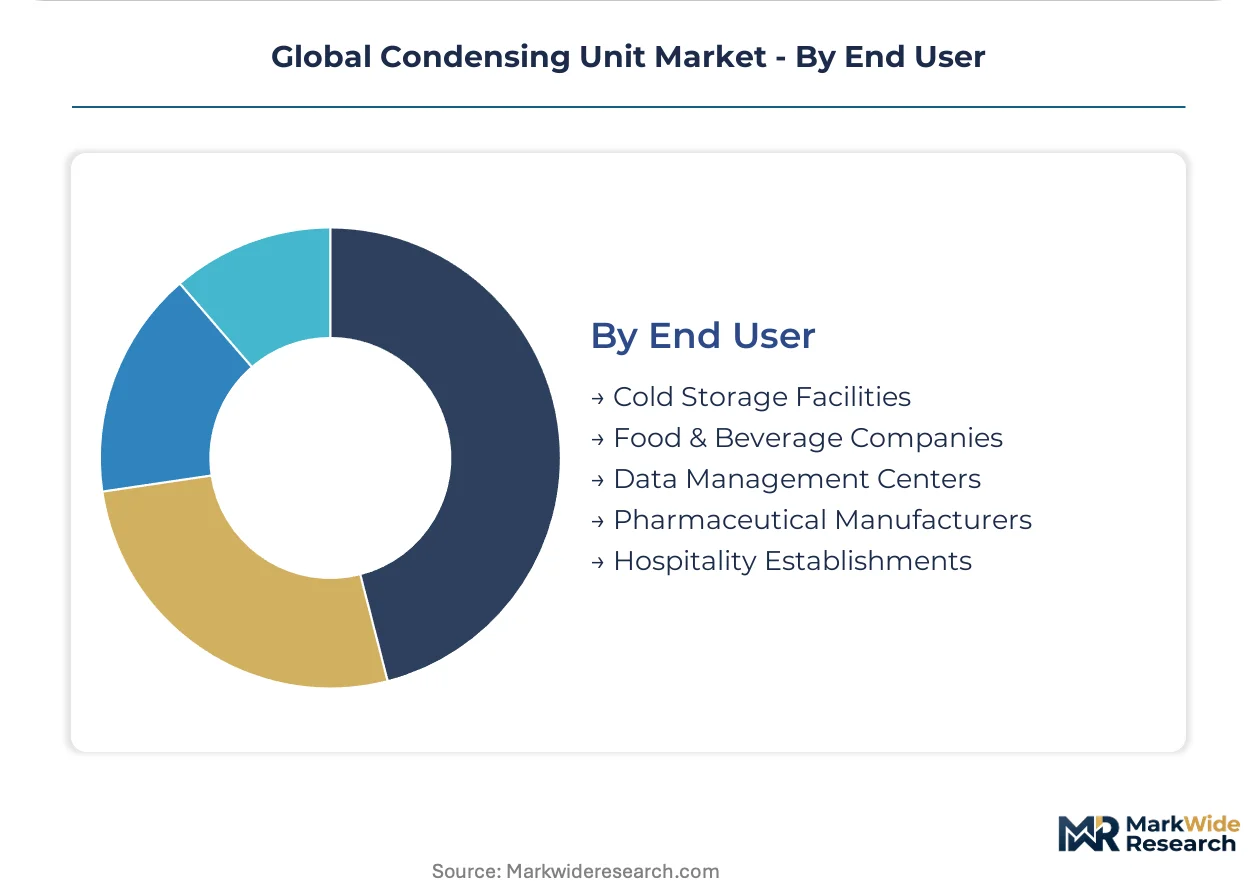
End User:
Volume concentration clusters with cold storage developers and food service operators, while pharmaceutical manufacturers drive premium specification for compliance-critical applications.
- Cold Storage Facilities:Third-party logistics operators build temperature-controlled warehouse capacity to serve pharmaceutical and food distribution networks. FSSAI enforcement in India creates procurement windows for transcritical CO2 units in Mumbai and Delhi logistics corridors. Specifiers prioritize charge reduction to minimize machinery room footprint and safety compliance costs.
- Pharmaceutical Manufacturers:Vaccine producers require validated cold chain infrastructure with continuous temperature monitoring and redundant compressor capacity. Distribution networks in Germany and Japan specify ultra-low-temperature condensing units with cascade or transcritical CO2 architectures. Regulatory scrutiny from FDA and EMA elevates documentation and qualification requirements.
- Food & Beverage Companies:Processors and retailers balance capital constraints against energy efficiency in refrigeration infrastructure decisions.
- Data Management Centers:Hyperscale and colocation operators specify cooling equipment with standardized form factors for rapid deployment.
- Hospitality Establishments:Hotels and restaurants prioritize acoustic performance and compact footprints for rooftop or mechanical room installation.
Cold storage facilities anchor procurement volume; pharmaceutical manufacturers are expanding most quickly on vaccine distribution network buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SNAP rules and EU F-Gas Regulation anchor regulatory pressure in the United States and Germany, compressing equipment replacement cycles as cold storage operators race compliance deadlines. Japan's METI efficiency mandates and India's FSSAI enforcement create parallel procurement windows across distinct climate zones.
United States
Supermarket retrofit demand surges as R404A phase-out deadlines approach. EPA SNAP restrictions trigger equipment replacement across Florida and Texas logistics corridors. Contractors in Dallas-Fort Worth negotiate direct OEM frame agreements, bypassing traditional distribution channels for condensing unit skids.
Germany
Vaccine distribution networks require ultra-low-temperature CO2 architectures with redundant compressor capacity. EU F-Gas Regulation compresses allowable GWP thresholds for new equipment placed on the market. Engineering teams in Stuttgart accelerate transcritical platform development while maintaining hydrocarbon options for smaller capacity points.
Japan
Pharmaceutical cold chain buildouts demand validated infrastructure with continuous temperature monitoring. METI energy-efficiency mandates reshape replacement cycles in Tokyo-Osaka logistics corridors. Localized manufacturing platforms anchor volume for Asia-Pacific supply.
India
FSSAI enforcement of temperature-controlled food distribution creates procurement windows for transcritical CO2 units. Cold storage developers in Mumbai and Delhi logistics corridors prioritize charge reduction to minimize machinery room footprint. Third-party logistics operators build warehouse capacity to serve pharmaceutical networks.
Netherlands
Food processors deploy aluminum microchannel coils to reduce refrigerant charge and extend corrosion resistance in washdown environments. EU F-Gas phase-down schedules accelerate substitution for conventional copper-aluminum coils. Rotterdam port logistics clusters specify charge-optimized architectures for import cold chain infrastructure.
Global Condensing Unit Market Competitive Landscape
Integrated system suppliers and component specialists split the market based on compliance complexity and service network depth. Consolidation pressure favors suppliers with captive compressor technology and machinery room integration capability. Three archetypes dominate: full-stack refrigeration OEMs, compressor-centric platform suppliers, and regional assembly specialists. Competitive moves center on transcritical CO2 platform licensing and direct-to-contractor digital procurement channels.
Within the full-stack tier, Carrier Global Corporation and Daikin Industries occupy positions defined by service network reach and localized manufacturing scale. Emerson Electric Co. exemplifies the compressor-centric archetype, anchoring technology supply to downstream OEM assembly lines. These three entities represent distinct strategic postures: aftermarket revenue capture through service infrastructure, volume leadership through geographic production platforms, and core technology licensing to fragmented fabricators.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Carrier Global Corporation |
| Daikin Industries, Ltd. |
| Danfoss |
| GEA Group Aktiengesellschaft |
| BITZER SE |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| Trane Technologies plc |
| Others |
Supply & Pricing Matrix
Copper price volatility from Chilean and Peruvian concentrate markets compresses margin visibility for coil manufacturers, forcing equipment OEMs to widen pricing spreads between configured-to-order transcritical CO2 systems and standard air-cooled units while accelerating aluminum microchannel substitution to hedge raw material exposure.
Pricing Analysis
Configured-to-order transcritical CO2 platforms command substantial premiums over standard air-cooled scroll packages due to engineering complexity and flammable refrigerant certification requirements. Pricing stratifies across premium, standard, and economy tiers based on compressor technology tier and after-sales service bundling. Cost compression in standard scroll units is intensifying because Chinese manufacturing scale and direct OEM-to-contractor procurement bypass traditional distributor markups. Cold storage developers in India exhibit highest price sensitivity, while pharmaceutical manufacturers in Germany prioritize validated redundancy over first cost.
Supply Chain Analysis
Copper cathode and aluminum extrusion feedstock draws from Chile, Peru, and Chinese smelter capacity, with refrigerant chemical production anchored in Chinese and US Gulf Coast petrochemical corridors. Scroll compressor manufacturing clusters in Thailand and China create geographic single-point vulnerability for OEM assembly lines. Tariff exposure on aluminum microchannel coils from Chinese suppliers threatens margin stability for European food processor procurement. Distribution runs through direct OEM frame agreements with national mechanical contractors, eroding traditional wholesale inventory positions in Texas and Florida retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The condensing unit market sits in early-cycle expansion as transcritical CO2 platform adoption accelerates ahead of EU F-Gas phase-down deadlines, creating procurement windows for charge-optimized architectures across pharmaceutical and food distribution networks.
For Market Incumbents: Insulate aftermarket revenue streams by deepening service network density in California and Texas supermarket retrofit corridors, while securing captive compressor technology through backward integration into scroll manufacturing platforms to offset emerging Chinese OEM price competition. For New Entrants and Emerging Players: Build out transcritical CO2 system integration capability targeting Indian cold storage buildout in Mumbai and Delhi logistics corridors, where FSSAI enforcement creates specification authority vacuums for contractors lacking flammable refrigerant certification infrastructure. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down milestones reshape the acquisition landscape toward integrated system suppliers with machinery room design capability and transcritical CO2 platform licensing portfolios. Target mid-tier refrigeration OEMs with established contractor relationships but underdeveloped low-GWP product pipelines. Watch EPA SNAP enforcement intensity in Florida and Texas as inflection indicator for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Transcritical CO2 Platform Licensing | Enables OEMs to meet EU F-Gas thresholds without captive R&D investment in Stuttgart engineering clusters. |
| Direct-to-Contractor Digital Procurement | Carrier and Daikin frame agreements in Texas bypass distributor margins and capture national service account specification authority. |
| Aluminum Microchannel Coil Manufacturing Scale-Up | Dutch food processor demand for corrosion-resistant washdown equipment accelerates substitution from copper-aluminum designs. |
| Flammable Refrigerant Technician Certification Programs | Contractor retraining infrastructure addresses talent gaps compressed by EU 2027 step-change deadlines. |
| Variable-Speed Scroll Compressor Integration | California utility demand-response incentives collapse first-cost premiums versus fixed-speed alternatives in supermarket rack retrofits. |
Research Methodology
Initial hypotheses were tested against primary input from refrigeration contractors, cold storage facility engineers, pharmaceutical quality assurance directors, OEM procurement managers, and aftermarket service heads, and refined through secondary validation against EPA SNAP rulemaking dockets, EU F-Gas Regulation implementation reports, ASHRAE standards documentation, and customs trade data on compressor and coil imports. Bottom-up equipment shipment analysis triangulated against top-down cold storage capacity buildout projections across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling condensing unit procurement by cooling architecture, compressor technology, end-use thermal load, and regional regulatory cluster. CAGRs were derived from segment-level volume buildups cross-referenced against cold chain infrastructure investment disclosures and pharmaceutical distribution network expansion announcements.
Stress conditions across copper price bands, refrigerant phase-down acceleration scenarios, and compressor supply disruption events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement timing and technology substitution elasticities. Cross-checking against EIA commercial refrigeration energy consumption data and EU F-Gas quota allocation records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Three Phase Cooling Fans Market