
 Italy Electric Vehicle Charging Equipment Market | 2026-2036
Italy Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Charging Equipment Market Insights
Vehicle-to-grid bidirectional charging is tilting the hardware stack toward interoperability and grid-integration capabilities. Enel X Way S.r.l. leverages its nationwide roaming network to dominate public charging access across Italian motorways. Be Charge (Plenitude) anchors its position through aggressive DC fast-charging corridor buildouts linking northern industrial zones. Atlante (NHOA Group) specializes in battery-integrated charging stations that buffer grid demand during peak hours.
Electric vehicle charging equipment comprises electrical apparatus designed to transfer energy from grid infrastructure to onboard battery systems, typically operating across power levels from 3.7 kW residential AC units to 350 kW DC fast-charging terminals with integrated power conversion, cooling, and communication protocols. Its primary commercial purpose is enabling safe, metered, and network-managed energy delivery that aligns vehicle dwell time with driver mobility patterns. Floor-standing chargers and fast chargers command the dominant share of capital deployment as highway corridors and urban hubs prioritize throughput over residential convenience. AC charging retains volume leadership in residential buildings and hospitality settings where dwell times naturally extend overnight, while DC charging captures the fastest expansion in fleet depots where commercial vehicle uptime directly affects operational economics.
Italy's Ministry of Infrastructure and Transport coordinates PNRR funding disbursement tied to AFIR-equivalent charging density targets, while the Italian Regulatory Authority for Energy, Networks and Environment (ARERA) shapes tariff structures that determine operator revenue stability. CE marking under the EU Low Voltage Directive and EMC Directive governs product market access, with additional conformity assessment required for grid connection codes issued by Terna. Stakeholders must weigh the trade-off between standardized hardware procurement and software differentiation as roaming interoperability mandates from European regulators tighten.
Market Dynamics
The National Recovery and Resilience Plan (PNRR) is forcing capital allocation decisions across charging infrastructure deployment, with AFIR-equivalent density targets dictating site selection priorities and hardware procurement timelines for operators.
Growth Catalysts
- PNRR Funding Allocation:Public capital disbursement tied to charging point density mandates accelerates corridor buildouts along A1 and A14 motorways.
- Fleet Electrification Mandates:Municipal transit operators in Milan, Rome, and Turin trigger depot-scale DC fast-charging procurement for bus and light commercial vehicle conversion.
- Vehicle-to-Grid Integration:Bidirectional power flow protocols unlock grid services revenue streams, reshaping hardware specifications toward interoperability.
Market Restraints
- Grid Connection Queues:Terna's technical verification timelines for medium-voltage hookups extend deployment schedules by 8-14 months in congested northern regions.
- Copper and Silicon Carbide Volatility:Power electronics input costs swing with commodity markets, compressing margin visibility for charging station manufacturers.
- Roaming Protocol Fragmentation:Incomplete OCPI implementation across Italian operators creates billing reconciliation friction that deters cross-network usage.
Strategic Opportunities
- Southern Corridor Underpenetration:Calabria and Sicily maintain charging density below one-fifth of Lombardy levels, presenting greenfield site acquisition potential.
- Battery-Integrated Buffering:Station-mounted storage paired with solar canopies reduces grid upgrade dependency while capturing peak shaving revenues.
- ARERA Tariff Reform:Proposed capacity-based pricing structures reward flexible charging profiles, incentivizing smart load management software deployment.
Industry Challenges
- Power Electronics Talent Scarcity:Shortage of engineers with combined grid integration and embedded systems expertise constrains R&D velocity for domestic manufacturers.
- CE-Plus-Terna Dual Certification:Parallel conformity assessment under EU Low Voltage Directive and national grid codes extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Charging Equipment Market |
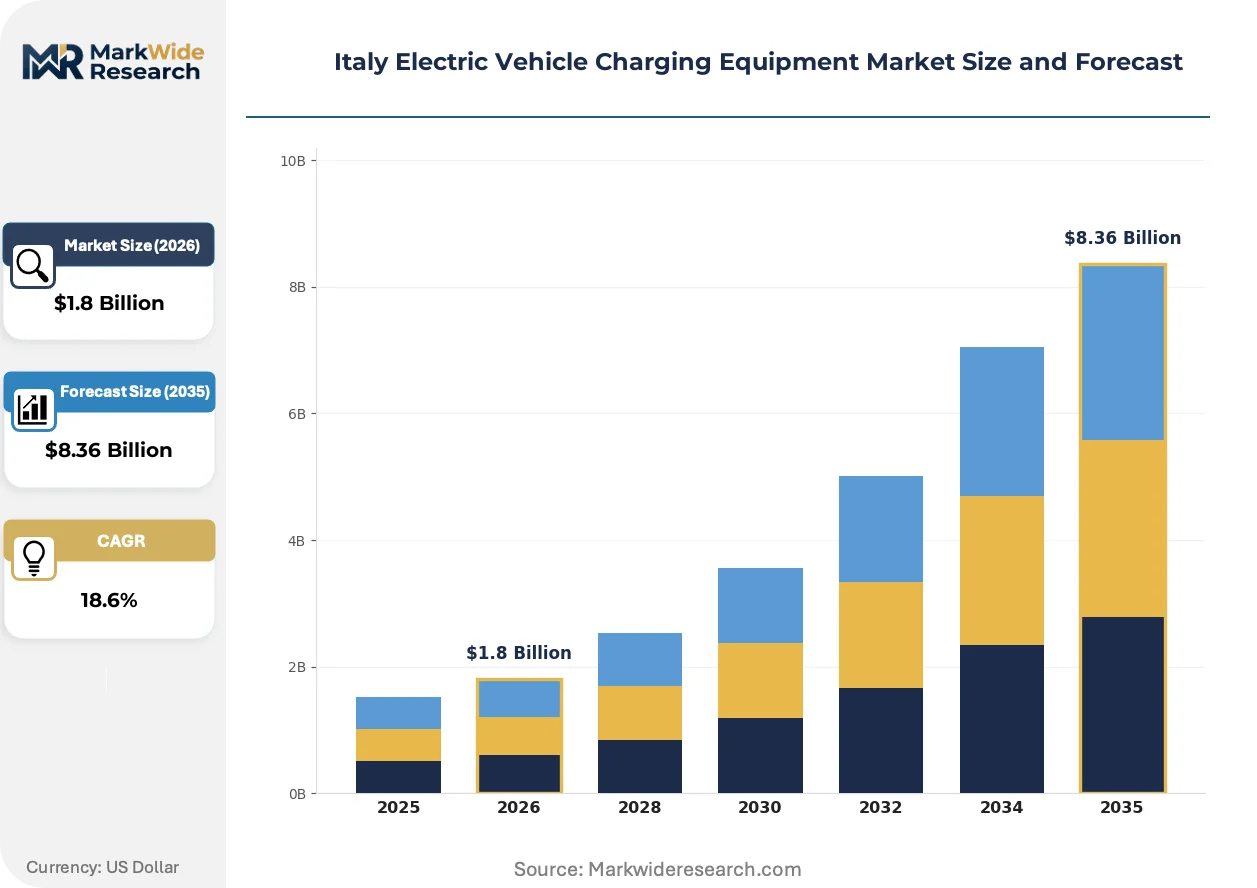
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Chargers, Floor-Standing Chargers, Mobile Chargers, Fast Chargers, Wireless Chargers Charging Technology: AC Charging, DC Charging, Inductive Charging, Conductive Charging, Solar-Powered Chargers Application: Commercial Complexes, Public Parking Lots, Residential Buildings, Fleet Depots, Hospitality Sector End User: Utility Providers, Fleet Operators, Property Managers, Retail Outlets, Transport Agencies |
| Companies Covered | Enel X Way S.r.l., Be Charge (Plenitude), Atlante (NHOA Group), Fimer S.p.A., Scame Parre S.p.A., GIGIEFFE S.p.A., Acea S.p.A., IPlanet S.p.A., ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware architectures are virtualizing control layers while physical infrastructure hardens against grid instability, creating a bifurcation between commodity power electronics and software-defined energy management.
Dynamic load management software is virtualizing the charging station control stack, replacing fixed power allocation with real-time optimization algorithms. Fleet operators deploying 150 kW+ hubs adopt these systems to minimize demand charges and coordinate vehicle-to-grid dispatch. The technology is virtualizing capital deployment decisions by deferring transformer upgrades through software-mediated peak shaving.
ARERA's capacity tariff consultations are reshaping operator business models toward energy-as-a-service structures. Industrial consequence includes mandatory smart meter integration and time-of-use rate exposure for all public charging above 22 kW. Fast-charging corridor operators face the steepest compliance curves as their utilization profiles concentrate during system peak hours.
Fleet procurement is consolidating around outcome-based uptime guarantees rather than hardware ownership. Logistics operators in Emilia-Romagna now contract charging availability per kilometer rather than purchasing stations outright. This shift concentrates vendor selection criteria on software reliability and maintenance response velocity across northern industrial zones.
Italy Electric Vehicle Charging Equipment Market Segmentation
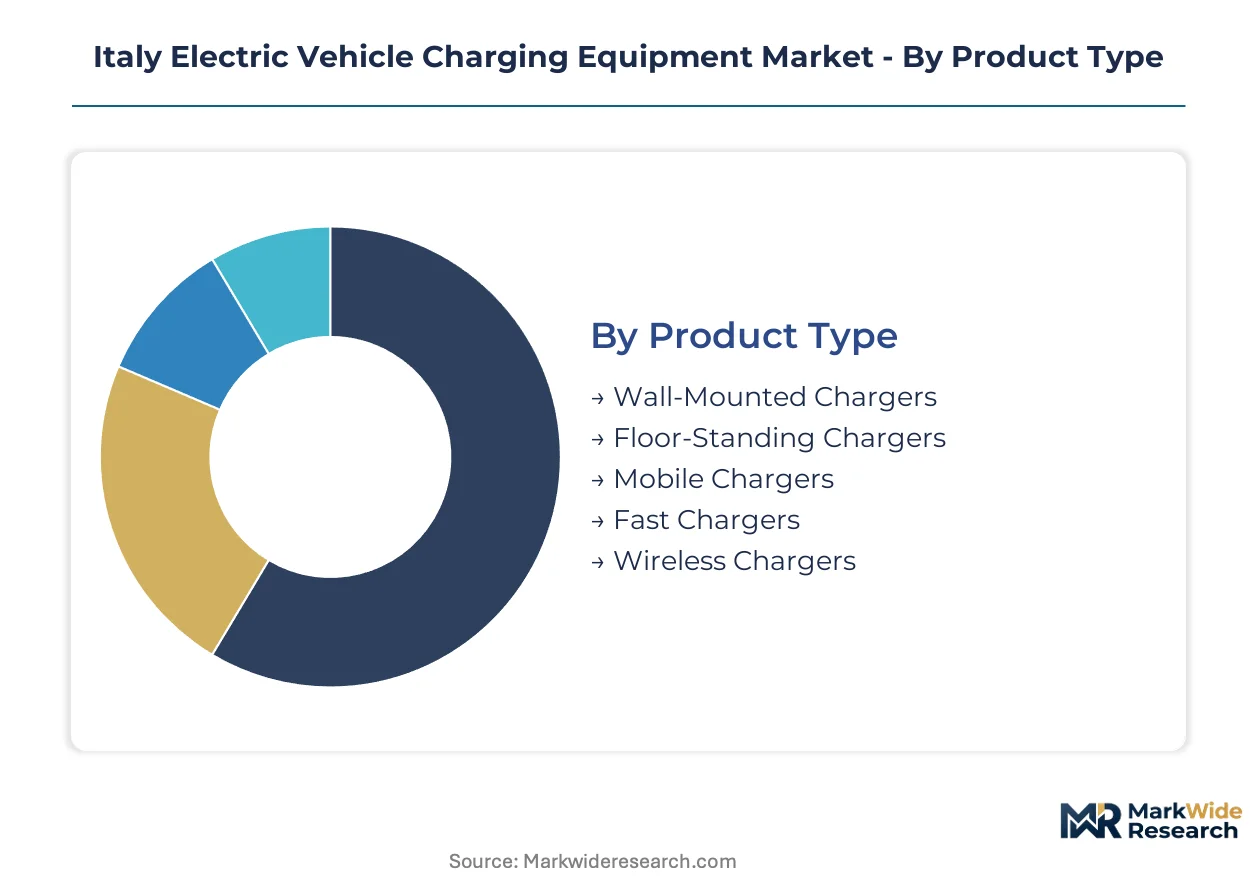
Segmentation in Italy's EV charging market reveals divergent hardware requirements across power levels and installation contexts. Equipment specifications vary sharply between overnight residential deployments and high-throughput fleet depots where uptime economics dominate procurement decisions.
Product Type:
Mature form factors anchor current deployment volumes while emerging configurations address mobility and interoperability gaps.
- Wall-Mounted Chargers:Compact AC units rated 3.7-22 kW attach directly to building infrastructure. Demand clusters in Lombardy condominium retrofits where space constraints and aesthetic requirements override power specifications.
- Floor-Standing Chargers:Pedestal-mounted hardware supports dual-port configurations up to 350 kW DC output. Milan and Turin motorway service areas prioritize these units for corridor density targets under PNRR funding timelines.
- Mobile Chargers:Portable emergency units with onboard storage address rural coverage gaps in Calabria and Sicily where fixed infrastructure economics fail.
- Fast Chargers:High-power DC terminals enable sub-30-minute charging cycles. Fleet operators in Emilia-Romagna logistics hubs specify these for commercial vehicle turnaround requirements.
- Wireless Chargers:Inductive pad systems eliminate connector wear in automated depot environments. Pilot deployments concentrate around Turin municipal transit facilities testing opportunity charging for electric buses.
Floor-standing chargers retain volume leadership; wireless chargers hold the steepest expansion curve.
Charging Technology:
Cost tier stratification separates proven AC architectures from premium DC systems with active cooling and power electronics.
- AC Charging:Alternating current delivery through onboard vehicle rectifiers dominates residential and workplace installations. Property managers across Rome apartment blocks favor these units for their compatibility with existing electrical distribution without transformer upgrades.
- DC Charging:Direct current systems with external power conversion enable 50-350 kW output. Highway corridor operators along A1 and A14 motorways deploy these to meet AFIR-equivalent density mandates and capture long-distance mobility demand.
- Inductive Charging:Electromagnetic field transfer eliminates physical connectors. Limited deployments target premium hospitality settings in Milan where aesthetic integration commands price premiums.
- Conductive Charging:Pantograph and overhead contact systems serve heavy-duty fleet applications. Turin and Rome transit agencies evaluate these for electric bus rapid charging at route termini.
- Solar-Powered Chargers:PV-integrated stations with battery buffering reduce grid dependency. Southern regions with high irradiance and weak grid infrastructure present the primary addressable market.
AC charging retains volume leadership; DC charging captures the steepest expansion trajectory.
Application:
Customer type determines dwell time economics and power level requirements across installation environments.
- Commercial Complexes:Mixed-use retail and office installations balance customer convenience with parking revenue. Shopping centers around Milan deploy 22-50 kW units to capture dwell times of 2-4 hours.
- Public Parking Lots:Municipal and private off-street facilities serve unpredictable user patterns. ARERA tariff structures shape operator revenue models for these high-visibility deployments.
- Residential Buildings:Multi-unit dwellings and single-family homes dominate overnight charging volume. Condominium governance complexity in northern Italy constrains installation velocity despite pent-up demand.
- Fleet Depots:Centralized charging for logistics and transit fleets requires 150 kW+ hub configurations. Emilia-Romagna distribution centers specify guaranteed uptime contracts rather than hardware ownership.
- Hospitality Sector:Hotels and resorts leverage charging as guest amenity and retention tool. Premium properties in Rome and Florence integrate 11-22 kW units with valet-managed scheduling.
Residential buildings retain volume leadership; fleet depots hold the steepest expansion curve.
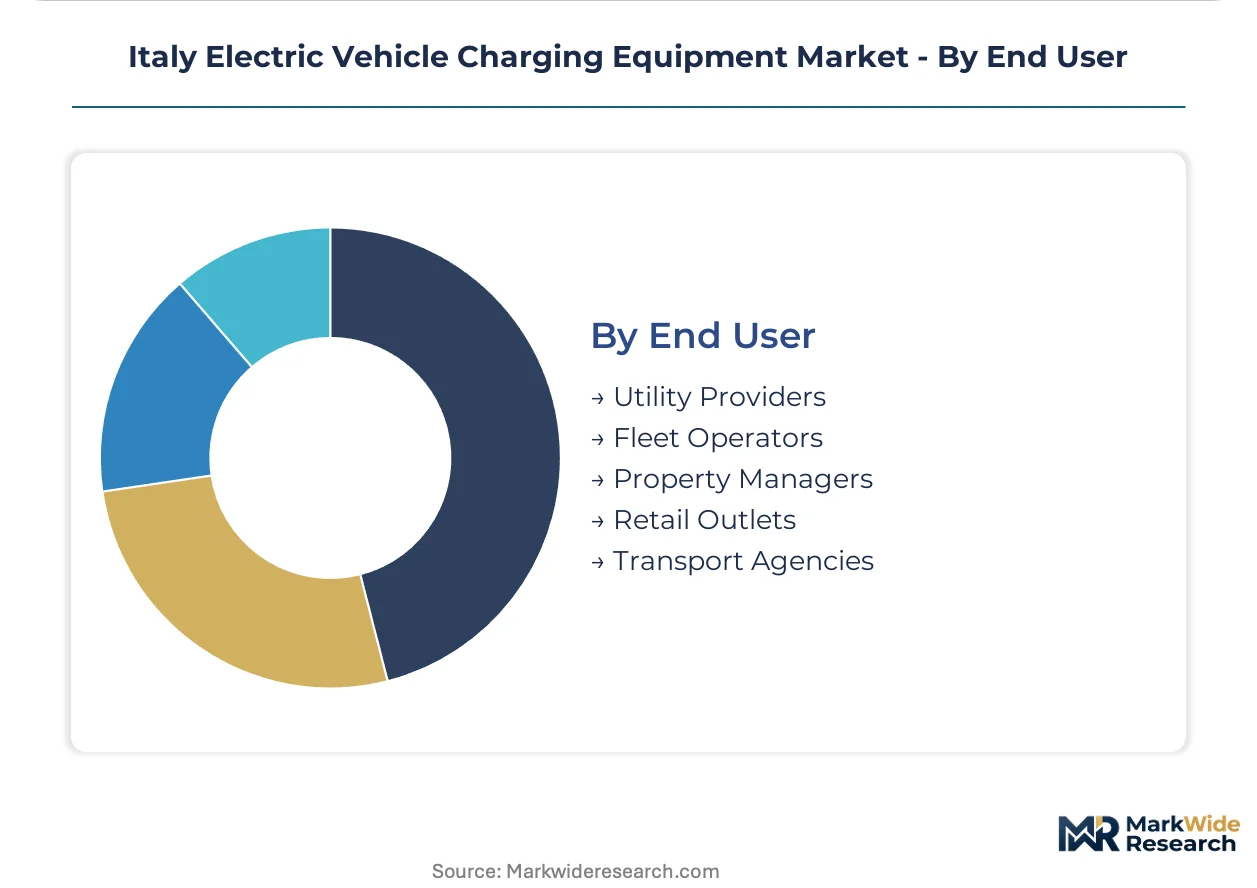
End User:
Procurement authority and capital allocation timelines vary sharply across stakeholder categories with divergent technical capabilities.
- Utility Providers:Grid operators and energy retailers deploy charging as customer acquisition and load management infrastructure. Enel X Way leverages its Terna grid relationships to accelerate connection timelines.
- Fleet Operators:Logistics and transit companies electrify vehicle assets with charging as operational necessity. Municipal operators in Milan, Rome, and Turin trigger depot-scale procurement through bus fleet conversion mandates.
- Property Managers:Residential and commercial building operators navigate condominium governance and tenant billing complexity. Technical expertise gaps slow decision cycles for multi-unit residential retrofits.
- Retail Outlets:Fuel retailers and grocery chains deploy charging to extend dwell time and capture ancillary revenue. Highway service area operators prioritize throughput over residential-style convenience.
- Transport Agencies:Public transit authorities coordinate corridor charging with route planning and vehicle procurement. PNRR funding disbursement flows through these entities for municipal electrification programs.
Property managers retain volume leadership; fleet operators hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports EV charging hardware and power electronics to Italian operators seeking CE-certified DC fast-charging systems. This trade corridor supplies critical components for PNRR-funded corridor buildouts along the A1 motorway.
Lombardy
Milan's municipal transit electrification and corporate fleet conversion drive depot-scale charging procurement. ARERA capacity tariff consultations reshape operator business models toward flexible load management. The Milan metropolitan area concentrates Italy's densest public charging network with motorway service area priority deployment.
Piedmont
Turin's automotive heritage accelerates commercial vehicle charging hub development for logistics operators. PNRR funding disbursement flows through regional transport agencies for bus fleet conversion programs. The Turin-Alessandria corridor anchors battery-integrated charging pilots with grid-buffering capabilities.
Emilia-Romagna
Distribution centers and logistics parks trigger 150 kW+ hub procurement with uptime guarantee contracts. The region's industrial density supports outcome-based charging service models rather than hardware ownership. Bologna and Modena logistics clusters specify guaranteed availability per kilometer for commercial vehicle electrification.
Lazio
Rome's municipal transit authority coordinates corridor charging with route planning and electric bus procurement. CE marking under EU Low Voltage Directive governs product market access for station deployments. The Rome metropolitan area prioritizes public parking lot installations with ARERA-shaped tariff structures.
Veneto
Verona and Padua industrial zones drive fleet depot electrification with centralized charging requirements. Terna's grid connection codes extend product launch timelines for medium-voltage hookups in congested areas. The region maintains charging density below Lombardy levels, presenting infrastructure gap opportunities.
Italy Electric Vehicle Charging Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around utility-affiliated operators with grid access advantages and independent specialists with hardware differentiation capabilities. Tier-one players leverage Terna relationships to accelerate connection timelines, while mid-tier vendors compete on software-defined load management. Two strategic archetypes dominate: roaming-network operators maximizing access density and battery-integrated station developers capturing grid services revenue. Competitive moves concentrate on corridor site acquisition and smart tariff compliance software deployment.
Within the utility-affiliated tier, Enel X Way S.r.l. occupies a position exemplifying nationwide roaming network dominance, while Be Charge (Plenitude) represents aggressive DC fast-charging corridor buildouts. Atlante (NHOA Group) anchors the battery-integrated specialist archetype with station-mounted storage capabilities. These three S.r.l.-structured operators collectively illustrate the market's bifurcation between access-scale players and grid-integration specialists competing for PNRR-funded deployment slots.
| Leading Market Players |
|---|
| Enel X Way S.r.l. |
| Be Charge (Plenitude) |
| Atlante (NHOA Group) |
| Fimer S.p.A. |
| Scame Parre S.p.A. |
| GIGIEFFE S.p.A. |
| Acea S.p.A. |
| IPlanet S.p.A. |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in silicon carbide wafer fabrication across European foundries is compressing margins for power electronics suppliers while simultaneously elevating pricing power for integrated manufacturers with captive semiconductor capacity. This utilization asymmetry bifurcates the hardware market between premium DC fast-charging systems with supply security and commodity AC units exposed to spot-market volatility.
Pricing Analysis
Current-generation 350 kW DC hardware commands substantial premiums over prior-generation 150 kW systems, while next-generation silicon carbide architectures threaten further price erosion for legacy IGBT-based inventory. The dominant pricing structure stratifies across premium, standard, and economy tiers differentiated by cooling system sophistication and grid-code certification grade. Price compression in the standard tier intensifies as Chinese power module imports displace European sourcing. Fleet operators exhibit the highest price sensitivity due to depot-scale procurement volumes, while hospitality sector buyers prioritize aesthetic integration over unit economics.
Supply Chain Analysis
Contract manufacturing for power electronics concentrates at Foxconn, Jabil, and Benchmark Electronics facilities across Poland, Hungary, and Mexico. Geographic supply concentration centers on Germany for precision power conversion components, China for silicon carbide substrates and magnetic components, and Taiwan for high-voltage control ICs. Raw material dependencies rest on copper busbar stock, rare-earth magnets, and liquid cooling fluids. Single-source vulnerability in silicon carbide substrate supply from Wolfspeed and Coherent operations presents structural risk. Distribution runs through direct OEM relationships for large fleet deployments and electrical wholesale channels for residential and small commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PNRR funding disbursement timelines and AFIR-equivalent density mandates are compressing deployment windows, creating a high-growth disruption where capital allocation speed determines competitive position. Vehicle-to-grid protocol maturation represents the decisive technological inflection reshaping hardware specifications and revenue models.
For Market Incumbents: Insulate roaming network dominance through accelerated Terna grid connection queue management and exclusive corridor site acquisition along A1 and A14 motorway service areas. Prioritize backward integration into power electronics assembly to offset silicon carbide wafer cost volatility. Defensive consolidation through software-defined load management acquisition protects against emerging energy-as-a-service entrants. For New Entrants and Emerging Players: Establish a beachhead in southern corridor underpenetration across Calabria and Sicily where charging density gaps exceed four-fifths of northern levels. Target battery-integrated buffering configurations for weak-grid rural deployments as the most penetrable application segment. Pursue outcome-based uptime guarantee contracts with Emilia-Romagna logistics operators as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined load management providers with fleet operator relationships, positioning these archetypes for superior long-term viability across the 5-10 year electrification horizon. Acquisition priority targets vertically integrated specialists combining power electronics manufacturing with grid services software capabilities. Monitor ARERA capacity tariff implementation velocity as the critical inflection signal for business model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Corridor Site Acquisition | PNRR funding eligibility requires AFIR-equivalent density deployment along designated motorway corridors before disbursement deadlines. |
| Battery-Integrated Buffering | Station-mounted storage reduces Terna grid upgrade dependency while capturing ARERA peak shaving revenue streams. |
| Software-Defined Load Management | Dynamic power allocation algorithms defer transformer investments and enable vehicle-to-grid dispatch revenue. |
| Roaming Interoperability Certification | OCPI protocol compliance ensures billing reconciliation across Enel X Way and Be Charge network access. |
| Silicon Carbide Vertical Integration | Captive power module production insulates margin compression from substrate supply volatility. |
Research Methodology
Operator-level perspectives from charging network planners, fleet procurement directors, ARERA regulatory affairs specialists, and Terna grid integration engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with infrastructure deployment decision-makers across Lombardy, Emilia-Romagna, and Lazio with secondary validation from CE marking documentation, Terna grid connection code filings, and PNRR funding disbursement records. Bottom-up equipment shipment analysis triangulated against top-down energy demand projections derived from vehicle registration databases and municipal transit electrification schedules.
Scenario-bracketing around PNRR funding execution timelines, AFIR implementation stringency, and silicon carbide supply elasticity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include power level tier, charging technology architecture, installation context, and regional grid infrastructure maturity. CAGRs were synthesized from equipment deployment trajectories, vehicle fleet conversion schedules, and regulatory milestone achievement curves. Forecast inputs incorporated Terna medium-voltage connection queue dynamics and ARERA tariff reform consultation outcomes.
Sensitivities concentrate around PNRR disbursement velocity, silicon carbide substrate supply expansion, and OCPI roaming protocol harmonization across Italian operators. Forecasts reflect documented assumptions regarding fleet electrification mandate enforcement and municipal transit procurement timelines. Quarterly review of Terna connection approval rates, ARERA regulatory filings, and PNRR milestone achievement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Wireless Charging Market