
 Europe Acetic Acid Market | 2026-2036
Europe Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acetic Acid Market Intelligence
REACH registration requirements is consolidating the Europe acetic acid landscape by raising compliance costs for smaller producers. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to sustain margin stability across Northwestern Europe. INEOS Group Limited anchors its position through high-purity glacial acetic acid output serving pharmaceutical-grade buyers. BASF competes on backward integration into petrochemical feedstocks, while Eastman Chemical Company differentiates via specialized derivatives for polymerization applications.
Acetic acid is a carboxylic acid with the formula CH₃COOH, typically produced through methanol carbonylation or acetaldehyde oxidation, and functions primarily as a chemical intermediate and solvent across industrial processes. Glacial acetic acid commands premium positioning due to its concentration above 99.5% and stringent purity requirements for pharmaceutical and food-grade applications. Chemical synthesis as an application dimension leads volume absorption, while polymerization-linked demand tracks fastest expansion tied to European packaging and coatings sectors. The food and beverages end-use channel maintains mature offtake patterns with stable margin pools concentrated among certified preservative suppliers.
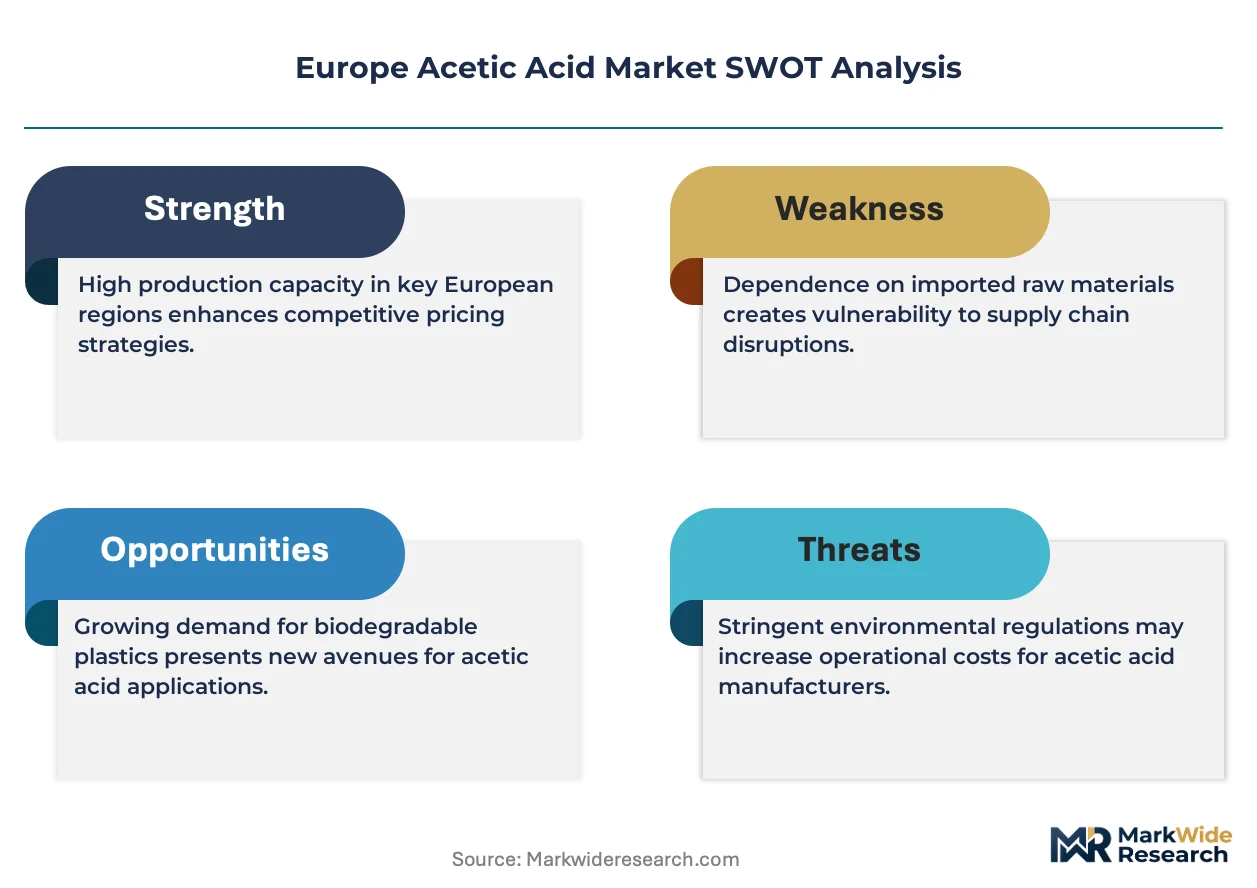
EMA pharmaceutical guidelines, REACH substance restrictions, and EU F-Gas Regulation collectively shape product purity thresholds, emission controls, and facility licensing across European acetic acid manufacturing. ECHA's evolving candidate list obligations force reformulation investments among derivative producers serving consumer-facing industries. Stakeholders must monitor regulatory divergence between EU-wide frameworks and emerging national chemical taxes in France and Germany that could fragment cost structures.
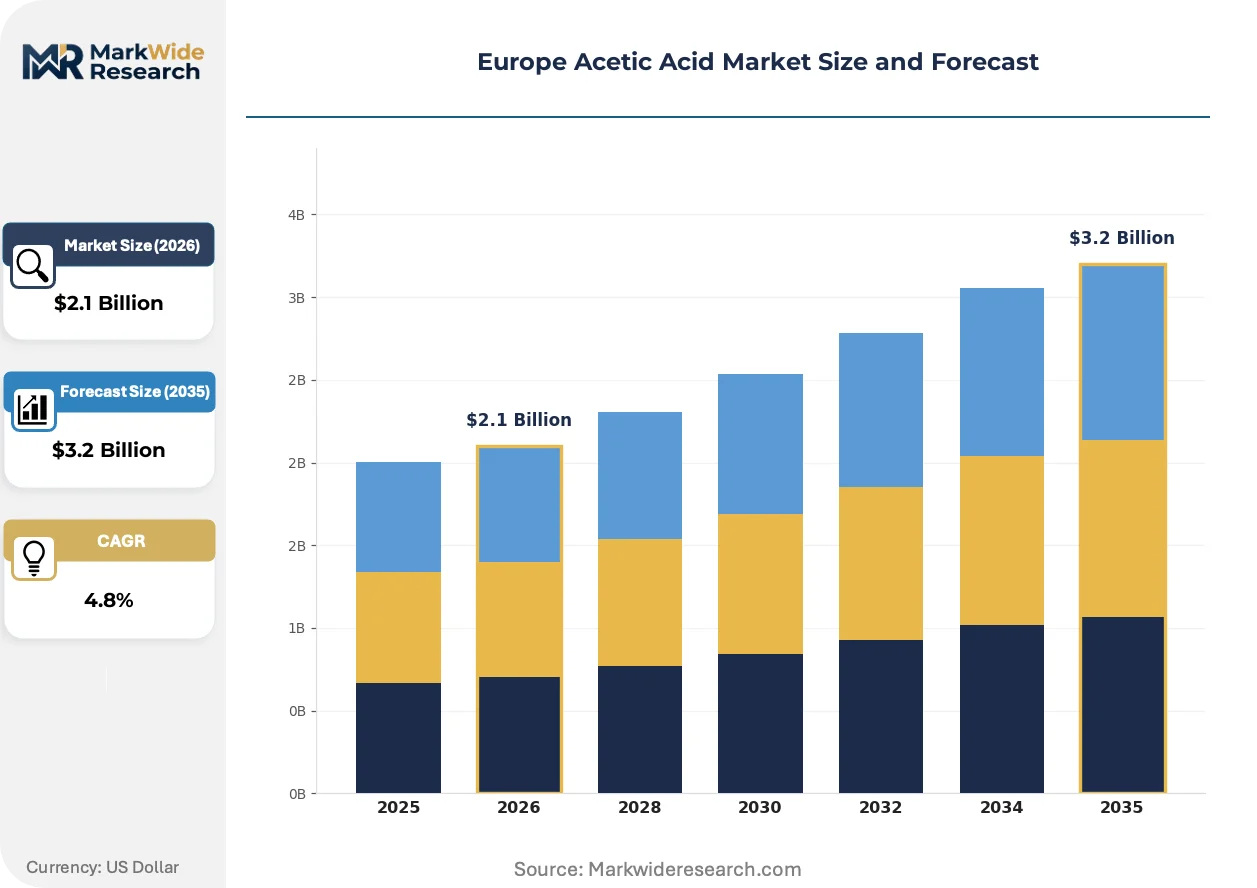
Market Dynamics
REACH compliance costs and carbon border adjustment mechanisms are compressing margins for non-integrated acetic acid producers across Northwestern Europe, forcing consolidation around methanol carbonylation assets with captive carbon capture.
Growth Catalysts
- EU Green Deal decarbonization mandates:Chemical producers in Germany's Ruhr corridor are retrofitting acetic acid plants with hydrogen-ready burners to secure operating licenses beyond 2030.
- Pharmaceutical-grade solvent demand:EMA purity guidelines for active pharmaceutical ingredient manufacturing are tightening specification windows for glacial acetic acid used in peptide synthesis.
- Bioplastics feedstock pull:Polyvinyl acetate derivatives for biodegradable packaging films are absorbing acetic acid volumes from converters in France's polymer cluster near Lyon.
Market Restraints
- Methanol price volatility:Natural gas-linked methanol contract structures in the Netherlands and Belgium transmit energy cost spikes directly into acetic acid variable production costs.
- Supply concentration risk:Three integrated producers control over 70% of European merchant acetic acid capacity, creating single-source vulnerability for specialty chemical formulators.
- Acetic anhydride substitution:Esterification processes in cellulose acetate manufacturing are partially migrating to ketene-based routes that bypass acetic acid intermediation.
Strategic Opportunities
- Poland's emerging chemical corridor:Lower carbon intensity grid electricity and proximity to Baltic methanol import terminals position Pomeranian production zones for cost-advantaged expansion.
- Carbon capture utilization:Acetic acid synthesis from captured CO₂ and green hydrogen is attracting pilot-scale investment under the EU Innovation Fund's decarbonization window.
- Specialty derivatives channel:Peracetic acid for food processing sanitation is opening premium pricing tiers as EFSA raises residual chlorine limits in cold chain applications.
Industry Challenges
- Process control engineering scarcity:Methanol carbonylation unit operators with Cativa and BP process certification command wage premiums exceeding 40% above standard chemical plant salaries.
- Legacy asset retrofit timelines:REACH authorization deadlines for chromium catalyst replacement in acetaldehyde oxidation units require 18-24 month shutdown windows that strain supply commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acetic Acid Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Diluted Acetic Acid, Anhydrous Acetic Acid, Acetic Acid Derivatives End Use Industry: Food & Beverages, Chemical Manufacturing, Textile Industry, Pharmaceuticals Application: Solvent, Preservative, Polymerization, Chemical Synthesis Distribution Channel: Direct Sales, Retail, Online Platforms, Distributors |
| Companies Covered | Celanese Corporation, Eastman Chemical Company, LyondellBasell Industries Holdings B.V., INEOS Group Limited, HELM AG, The Dow Chemical Company, Airedale Chemical Holdings Limited, SABIC, BASF, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acetic Acid Market Strategic Shifts & Innovations
Electrification of steam crackers and carbon accounting transparency are reshaping how acetic acid producers source methanol and justify premium pricing for low-carbon certified material.
Membrane-based acetic acid purification is overtaking traditional distillation sequences in new plant designs. Pharmaceutical and electronics-grade buyers in Switzerland and southern Germany are specifying membrane-refined product for trace metal contamination below 10 parts per billion. This technology is compressing energy intensity benchmarks and enabling smaller-scale distributed production units.
ECHA's 2024 update to the candidate list of substances of very high concern is forcing reformulation across acetic acid derivative supply chains. Coating and adhesive formulators serving consumer goods brands are accelerating substitution of certain catalyst residues. The food contact material segment is most affected, with migration testing protocols now mandatory for acetic acid-based plasticizers.
Long-term offtake contracting is displacing spot market exposure for integrated producers. Industrial buyers in the polymerization sector are locking in five-year supply agreements with fixed carbon intensity clauses. This pattern is most visible in the Benelux packaging cluster, where converters seek supply security for bioplastics capacity expansions tied to supermarket sustainability commitments.
Europe Acetic Acid Market Segmentation
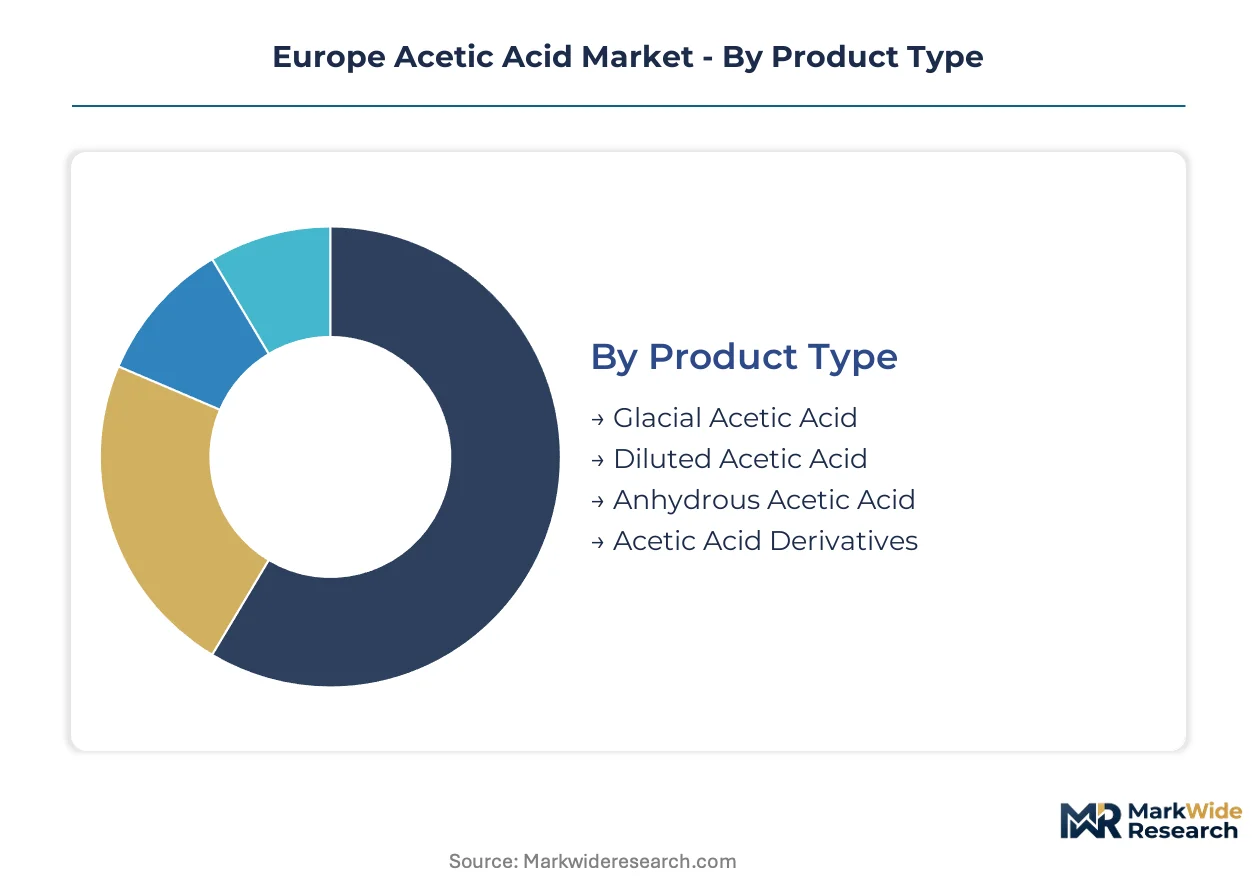
European acetic acid procurement patterns diverge sharply across purity grades and end-use specifications. Buyers in Germany's chemical corridor prioritize supply security and REACH documentation, while food-grade purchasers emphasize EFSA-compliant certification chains.
Product Type:
Purity thresholds determine pricing tiers and regulatory burden for European industrial buyers.
- Glacial Acetic Acid:Concentration exceeds 99.5% with stringent trace metal limits below 10 parts per billion. Pharmaceutical manufacturers in Switzerland and southern Germany specify membrane-refined material for peptide synthesis applications, paying premiums tied to EMA purity guidelines.
- Acetic Acid Derivatives:Peracetic acid and cellulose acetate intermediates command specialized margins. French converters near Lyon absorb volumes for biodegradable packaging films, with EFSA raising residual chlorine limits that favor acetic acid-based sanitation chemistry.
- Diluted Acetic Acid:Standard industrial grades at 60-80% concentration serve food preservation and textile processing across Italy and Spain.
- Anhydrous Acetic Acid:Water-free specification for moisture-sensitive polymerization reactions in Benelux coatings production.
Glacial acetic acid leads on scale; acetic acid derivatives lead on momentum.
End Use Industry:
Regulatory intensity varies by sector, with pharmaceutical and food channels facing the strictest ECHA compliance timelines.
- Chemical Manufacturing:Polyvinyl acetate and acetic anhydride production absorbs the largest volume share. Germany's Ruhr corridor anchors demand, with producers retrofitting plants with hydrogen-ready burners to secure operating licenses beyond 2030.
- Pharmaceuticals:EMA guidelines for active pharmaceutical ingredient manufacturing tighten specification windows continuously. Swissmedic and national regulators in Germany enforce batch-level documentation for solvent traceability.
- Food & Beverages:EFSA-regulated preservative applications maintain mature offtake with stable margin pools concentrated among certified suppliers.
- Textile Industry:Cellulose acetate fiber production in Portugal and northern Italy sources acetic acid for esterification processes.
Chemical manufacturing dominates volume absorption; pharmaceuticals climbs the fastest on regulatory premium capture.
Application:
Functional role in downstream processes determines technical specifications and contract structures.
- Chemical Synthesis:Intermediate consumption for acetic anhydride, esters, and chloroacetic acid production. Northwestern European integrated producers leverage methanol carbonylation assets with captive carbon capture to defend position against imports.
- Polymerization:Vinyl acetate monomer feedstock for adhesives and coatings. Benelux packaging converters lock in five-year supply agreements with fixed carbon intensity clauses tied to supermarket sustainability commitments.
- Solvent:Extraction and cleaning applications across pharmaceutical and electronics manufacturing.
- Preservative:Acidulant and antimicrobial functions in food processing, subject to EFSA migration testing protocols.
Chemical synthesis leads on scale; polymerization gains share fastest on bioplastics feedstock pull.
Distribution Channel:
Supply chain configuration reflects buyer scale and technical service requirements.
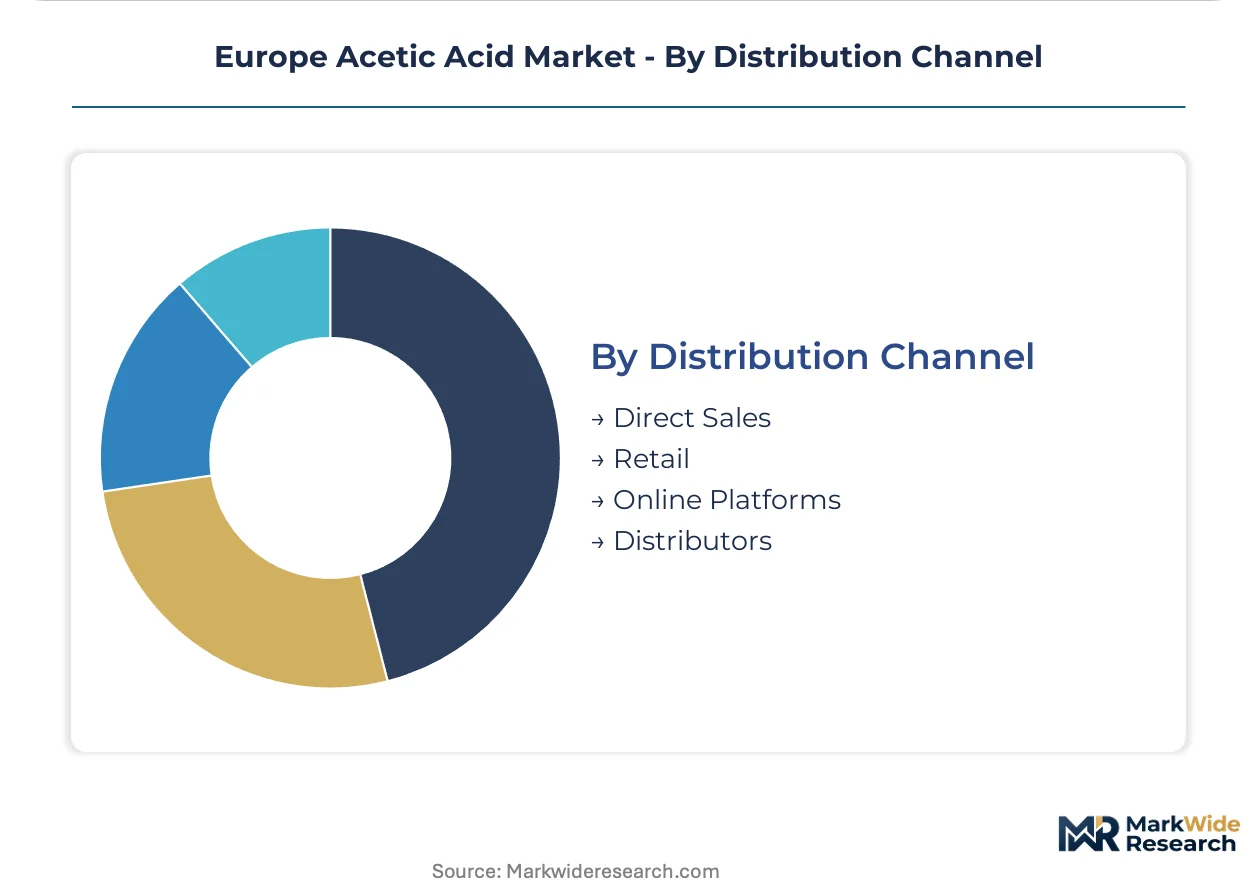
- Direct Sales:Integrated producers Celanese and INEOS supply polymerization and pharmaceutical customers through dedicated account management. Long-term offtake contracting displaces spot exposure for volume buyers seeking supply security.
- Distributors:Regional chemical distributors serve mid-size formulators in France, Italy, and Poland with inventory positioning and REACH documentation support.
- Online Platforms:Emerging channel for standardized grades and small-laboratory quantities.
- Retail:Limited to food-grade diluted products for commercial kitchens and small processors.
Direct sales leads on scale; distributors lead on momentum through Poland's emerging chemical corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acetic acid production in Europe traces its industrial lineage to the post-war chemical buildout along the Rhine-Ruhr corridor, where coal-to-chemicals infrastructure seeded the continent's first large-scale synthesis capacity. This foundation established Germany as the enduring center of European acetic acid manufacturing, with neighboring countries developing specialized derivative processing rather than primary production.
Germany
Ruhr-based integrated producers consume the largest acetic acid volumes for vinyl acetate monomer and acetic anhydride output. ECHA's REACH authorization timelines are forcing chromium catalyst replacement investments at legacy acetaldehyde oxidation units. The North Rhine-Westphalia chemical corridor is retrofitting plants with hydrogen-ready burners to secure operating licenses beyond 2030 under EU Green Deal mandates.
France
Polymer converters near Lyon absorb significant acetic acid derivative volumes for biodegradable packaging films serving supermarket sustainability commitments. ANSM pharmaceutical guidelines align with EMA purity standards for peptide synthesis solvents. The Auvergne-Rhône-Alpes cluster is expanding peracetic acid capacity for food processing sanitation as EFSA tightens residual chlorine limits.
Netherlands
Benelux packaging formulators lock in long-term offtake agreements with fixed carbon intensity clauses tied to supermarket chain procurement policies. Natural gas-linked methanol contract structures transmit energy cost volatility directly into acetic acid variable production costs. The Rotterdam-Antwerp port complex anchors methanol import logistics for Northwestern European carbonylation assets.
Switzerland
Swissmedic enforces batch-level documentation requirements for pharmaceutical-grade glacial acetic acid used in active pharmaceutical ingredient manufacturing. Basel-area chemical producers specify membrane-refined product with trace metal contamination below 10 parts per billion. The country's precision chemical sector commands premium positioning for high-purity solvent applications.
Poland
Pomeranian production zones are attracting investment interest due to lower carbon intensity grid electricity and proximity to Baltic methanol import terminals. The country's emerging chemical corridor offers cost-advantaged expansion potential compared to legacy Western European assets. Regional distributors are building inventory positioning to serve mid-size formulators across Central Europe.
Europe Acetic Acid Market Key Industry Players
The competitive structure tilts toward integrated petrochemical majors with captive methanol supply. Three producers control over 70 percent of European merchant acetic acid capacity, creating a concentrated supply environment for specialty chemical formulators. Strategic archetypes include backward-integrated methanol-to-acetic acid operators, high-purity pharmaceutical-grade specialists, and regional derivative-focused processors. Dominant competitive moves center on carbon capture retrofit investments and long-term offtake contracting with carbon intensity clauses.
Among integrated chemical majors, Celanese Corporation and INEOS Group Limited exemplify the methanol carbonylation archetype with Northwestern European production footprints. BASF represents the diversified petrochemical model with backward integration into feedstock supply chains. These three companies anchor the merchant market structure that specialty formulators must navigate for supply security.
| Leading Market Players |
|---|
| Celanese Corporation |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| INEOS Group Limited |
| HELM AG |
| The Dow Chemical Company |
| Airedale Chemical Holdings Limited |
| SABIC |
| BASF |
| Others |
Cost & Logistics Intelligence
Natural gas-linked methanol contract structures transmit energy cost volatility through acetic acid production economics, compressing margins for non-integrated producers while rewarding operators with captive methanol supply and carbon capture infrastructure. This cost cascade stratifies European pricing into three tiers: pharmaceutical-grade membrane-refined product commanding premiums from Swiss and German buyers, industrial-grade material serving polymerization customers under long-term offtake agreements, and standard grades facing spot market pressure.
Pricing Analysis
Long-term offtake contracting with fixed carbon intensity clauses dominates pricing structures for volume buyers, displacing spot exposure as Benelux packaging converters seek supply security for bioplastics expansions. Price differentiation rests on purity certification and REACH documentation depth, with EMA-compliant glacial acetic acid capturing widest margins. Cost compression in standard industrial grades intensifies because methanol price volatility transmits directly through variable production costs. Mid-size formulators in France and Poland exhibit highest price sensitivity, while pharmaceutical manufacturers in Switzerland and southern Germany prioritize specification compliance over unit economics.
Supply Chain Analysis
Methanol feedstock supply rests on import terminals at Rotterdam and Antwerp, with production concentration across Germany, the Netherlands, and Belgium creating geographic clustering of carbonylation assets. Raw material dependencies span natural gas for methanol synthesis, catalyst systems for Cativa and BP process units, and specialized membranes for pharmaceutical-grade purification. Single-source vulnerability runs through three integrated producers controlling over 70 percent of European merchant capacity. Distribution runs through direct sales for polymerization and pharmaceutical accounts, regional distributors serving mid-size formulators, and emerging online platforms for laboratory-scale quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe acetic acid market functions as a geographic-arbitrage play where Poland's lower-carbon grid electricity and Baltic methanol import access offer cost advantages against legacy Western European assets burdened by REACH compliance and carbon border adjustment exposure.
For Market Incumbents: Hedge methanol price exposure through backward integration into feedstock supply or long-term contracting with carbon intensity clauses. Celanese and INEOS should accelerate carbon capture retrofit investments at Ruhr corridor plants to defend position against emerging Polish capacity. Chromium catalyst replacement timelines at legacy acetaldehyde oxidation units demand 18-24 month shutdown windows that strain supply commitments and invite competitor encroachment. For New Entrants and Emerging Players: Carbon capture utilization technology from captured CO₂ and green hydrogen offers a technology-first wedge into premium sustainability-certified segments. Poland's Pomeranian production zones present the most penetrable geography given lower grid carbon intensity and proximity to Baltic methanol terminals. Target peracetic acid for food processing sanitation as EFSA raises residual chlorine limits, opening premium pricing tiers with shorter regulatory approval pathways than pharmaceutical grades. For Investors and Strategic Acquirers: Roll-up economics work for regional derivative-focused processors because ECHA's evolving candidate list obligations force reformulation investments that smaller formulators cannot fund internally. Mid-cap specialty chemical producers with REACH-compliant certification chains and established relationships with consumer-facing brands represent prime acquisition targets. Watch carbon border adjustment mechanism implementation timelines as the inflection signal determining cost competitiveness of imported versus domestic supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Celanese and INEOS anchor margin stability through captive feedstock control across Northwestern Europe. |
| Carbon Capture Retrofit Investment | Hydrogen-ready burner installations secure operating licenses beyond 2030 under EU Green Deal mandates. |
| Long-term Supply Agreement with Carbon Clauses | Benelux packaging converters lock in five-year contracts tied to supermarket sustainability procurement policies. |
| Membrane Purification Technology Deployment | Swissmedic and EMA guidelines drive pharmaceutical-grade specification windows below 10 parts per billion trace metals. |
| Peracetic Acid Capacity Expansion | EFSA residual chlorine limit revisions favor acetic acid-based sanitation chemistry in cold chain applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at integrated methanol carbonylation facilities, procurement leads at polymerization and pharmaceutical downstream OEMs, distribution channel partners serving France and Poland, and technical R&D directors overseeing membrane purification investments. Secondary validation drew from Cefic industry reports, customs and trade data for methanol and acetic acid flows, SEC 10-K filings from listed chemical majors, and ECHA regulatory update databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic sector weightings.
Segment-weighting approaches applied differential growth assumptions across purity grades, end-use industries, and regional production hubs throughout the forecast period. Chemical synthesis, polymerization, solvent, and preservative applications each carried distinct volume and value trajectories based on bioplastics feedstock pull and pharmaceutical regulatory premium capture. CAGRs derived from historical production data, announced capacity investments, and regulatory timeline impacts on operating cost structures. Carbon border adjustment mechanism implementation and ECHA candidate list expansion served as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal decarbonization mandate enforcement, methanol price volatility transmission, and chromium catalyst replacement timelines at legacy acetaldehyde oxidation units. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Coal Tar Pitch Market