
 North America Titanium Dioxide Market | 2026-2036
North America Titanium Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Titanium Dioxide Market Insights
Market Context with Strategic Players
Calcium carbonate extenders is recalibrating titanium dioxide loading rates in mid-tier paint formulations across North America. The Chemours Company leverages its Mississippi chloride-route facility to sustain cost-advantaged rutile output for regional coatings producers. Tronox Holdings plc anchors its position through integrated feedstock control at its Hamilton, Mississippi site, while Kronos Worldwide, Inc. competes via sulfate-process flexibility serving specialty anatase niches.
Technical Definition and Structural Segments
Titanium dioxide is a white inorganic pigment with a refractive index exceeding 2.7, produced through either the chloride or sulfate process, and functions primarily to provide opacity, brightness, and ultraviolet resistance in finished goods. Rutile grades dominate volume across coatings applications due to superior durability and hiding power, while specialty grades command margin pools in cosmetics and high-performance industrial finishes. The plastics application segment shows structural momentum as automotive lightweighting drives masterbatch consumption in exterior body panels and interior trim components across US and Mexican manufacturing plants.
Regulatory Frame and Forward-Looking Close
EPA enforcement of TSCA Section 5 and OSHA permissible exposure limits for respirable TiO2 dust constrain manufacturing practices and workplace controls at production sites in Mississippi and Ontario. Health Canada maintains aligned cosmetic ingredient hotlist restrictions that shape product registration pathways for beauty-sector specialty grades. Stakeholders must monitor evolving state-level PFAS contamination rules that could alter mining permits and waste disposal protocols at legacy sulfate-process facilities.
Market Dynamics
Waterborne architectural coatings are recalibrating titanium dioxide loading strategies across the United States and Canada as EPA Clean Air Act enforcement tightens volatile organic compound limits. Reformulation toward TiO2-rich low-VOC systems concentrates demand along the US Gulf Coast petrochemical corridor.
Growth Catalysts
- EPA Emissions Standards:Clean Air Act volatile organic compound limits are forcing architectural coatings reformulation toward TiO2-intensive waterborne systems across US manufacturing plants.
- Automotive Lightweighting:Exterior body panel and interior trim applications in US and Mexican assembly plants are expanding masterbatch consumption of rutile grades.
- Chloride-Process Efficiency:Mississippi corridor production sites leverage energy-advantaged chloride routes to serve regional coatings producers with cost-competitive rutile output.
Market Restraints
- Feedstock Concentration Risk:Synthetic rutile and ilmenite supply chains concentrate among limited bulk shippers, exposing Mississippi and Ontario production sites to bulk freight rate volatility.
- TSCA Section 5 Friction:EPA pre-manufacture notification requirements for modified nano-grade TiO2 extend product registration timelines and elevate compliance costs for specialty cosmetic applications.
- Calcium Carbonate Substitution:Mid-tier paint formulators are recalibrating titanium dioxide loading rates downward using precipitated calcium carbonate extenders in interior architectural segments.
Strategic Opportunities
- Mexican Manufacturing Expansion:Automotive assembly growth in Querétaro and Guanajuato creates captive demand for high-durability rutile masterbatches in exterior body panel applications.
- Clean Beauty Registration Pathways:Health Canada cosmetic ingredient hotlist alignment with EPA TSCA frameworks offers streamlined dual-market entry for specialty anatase grades in mineral sunscreen formulations.
- PFAS Contamination Rule Adaptation:Evolving state-level mining waste protocols at legacy sulfate-process sites in Ontario and Mississippi create first-mover advantage for chloride-route capacity expansion.
Industry Challenges
- Respirable Dust Controls:OSHA permissible exposure limit compliance for TiO2 dust requires capital-intensive ventilation upgrades at Mississippi and Ontario production facilities.
- Process Technology Talent Scarcity:Chloride-route operational expertise concentrates among aging workforce cohorts, constraining expansion timelines for new capacity in the US Gulf Coast corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Titanium Dioxide Market |
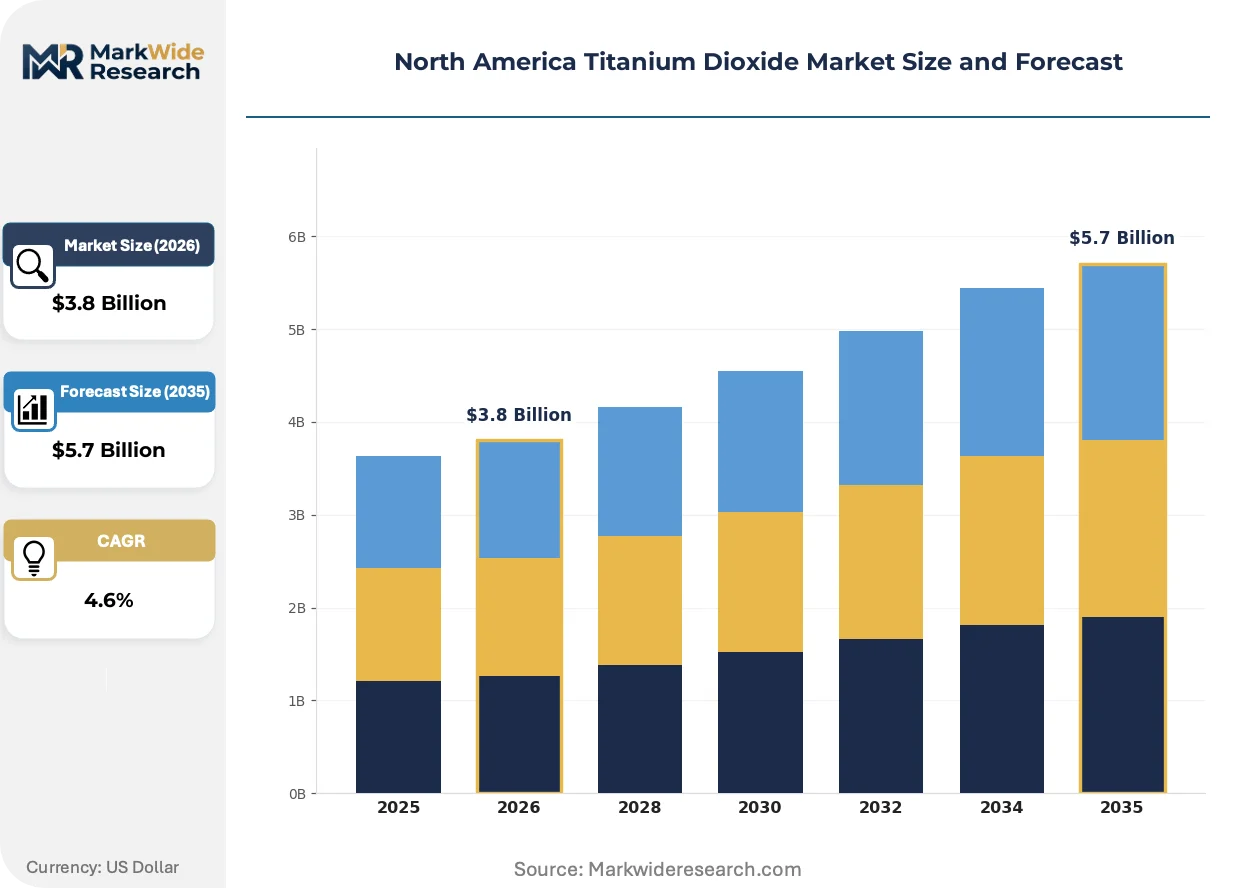
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rutile, Anatase, High-Performance, Specialty Application: Coatings, Plastics, Paper, Cosmetics End User: Aerospace, Automotive, Construction, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Venator Materials PLC, LB Group, The Chemours Company, The Kish Company, Inc., Evonik Industries AG, Tronox Holdings plc, INEOS, Argex Titanium Inc., Kronos Worldwide, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Titanium Dioxide Market Trends and Innovations
Process technology and regulatory frameworks are compressing the viable production base while end-use specifications fragment toward application-specific performance tiers. These forces are reshaping competitive positioning around feedstock security and formulation services capability.
Chloride-process rutile production is consolidating cost and quality leadership in North American coatings applications. Architectural coatings manufacturers in the US Gulf Coast corridor are migrating sulfate-process volumes toward chloride-route supply as energy efficiency and byproduct handling advantages compound. This technology is consolidating supplier tiers toward integrated feedstock-control players with captive synthetic rutile supply.
EPA enforcement of TSCA Section 5 pre-manufacture notification requirements is compressing innovation cycles for surface-modified nano-TiO2 grades. Cosmetic and sunscreen formulators face extended registration timelines and toxicology data requirements that favor incumbent suppliers with established new chemical entity dossiers. Specialty grade producers serving Health Canada-registered cosmetic applications are most affected, responding through dedicated regulatory affairs staffing and pre-submission consultation protocols.
Coatings procurement is fragmenting toward direct mill relationships and away from distributor intermediaries in high-volume architectural segments. Large US and Canadian paint manufacturers are negotiating direct chloride-route supply agreements with Mississippi corridor producers, compressing distributor margin pools. This pattern is most visible in waterborne architectural coatings serving EPA-regulated low-VOC compliance markets where formulation consistency and lot-to-lot uniformity command premium positioning.
North America Titanium Dioxide Market Segmentation
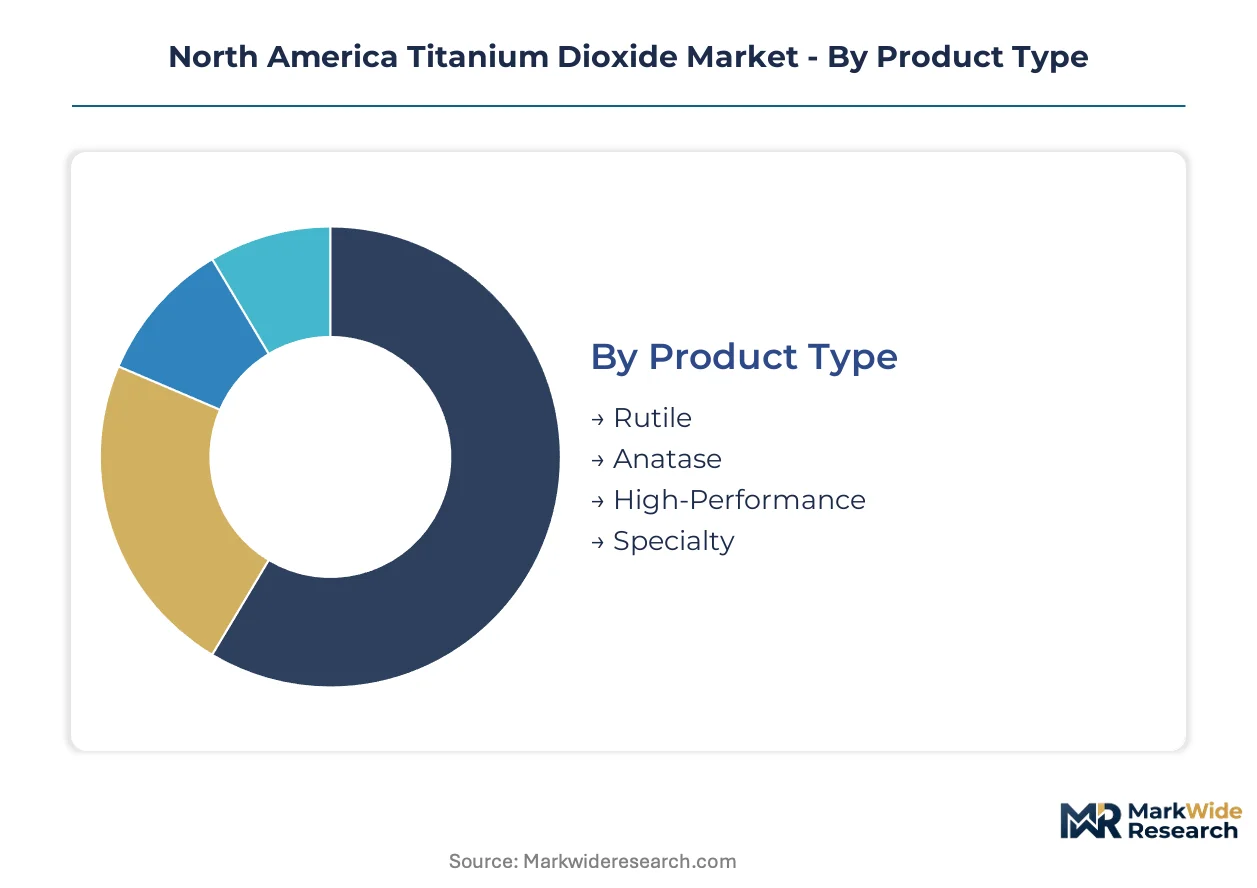
Segmentation in the North America titanium dioxide market reveals divergent margin structures across product grades and end-use applications. Chloride-route rutile commands premium positioning in architectural coatings, while sulfate-process anatase serves cost-sensitive industrial niches. Understanding these tiered demand patterns enables suppliers to align capacity investments with EPA-regulated reformulation trends.
Product Type:
Volume concentration clusters in standard rutile output, while premium capture concentrates in performance-optimized and regulatory-compliant specialty grades.
- Rutile:The tetragonal crystal structure delivers refractive indices above 2.7, providing superior opacity and exterior durability. Demand concentrates in waterborne architectural coatings across the US Gulf Coast corridor, where EPA Clean Air Act compliance drives TiO2-rich low-VOC reformulation.
- Anatase:This orthorhombic variant offers softer pigment characteristics suited for interior applications and chemical catalysis. Loading rates in mid-tier interior paints are recalibrating downward as calcium carbonate extenders substitute volume in cost-sensitive formulations.
- High-Performance:Surface-treated grades with alumina and silica encapsulation serve automotive OEM clearcoat applications demanding weathering resistance.
- Specialty:Nano-scale and ultrafine grades face extended EPA TSCA Section 5 registration timelines for cosmetic and sunscreen deployments.
Mature deployment sits with Rutile. Newer deployment is concentrated in Specialty grades navigating Health Canada cosmetic ingredient hotlist pathways.
Application:
Coatings absorb the dominant volume share, while plastics and cosmetics deliver margin expansion through specification-driven procurement.
- Coatings:Architectural, industrial, and automotive finishes represent the foundational demand base. Waterborne system reformulation across US manufacturing plants is compressing distributor intermediaries as direct mill relationships with Mississippi corridor producers consolidate.
- Plastics:Masterbatch incorporation in exterior body panels and interior trim components is climbing the fastest as automotive lightweighting accelerates across US and Mexican assembly plants.
- Paper:Laminates and decorative surfacing applications consume lower-opacity grades with less stringent durability requirements.
- Cosmetics:Mineral sunscreen and color cosmetic formulations require anatase grades meeting Health Canada hotlist restrictions and EPA pre-manufacture notification protocols.
Specification maturity anchors Coatings procurement. Growth velocity concentrates in Plastics serving Querétaro and Guanajuato automotive expansion.
End User:
Construction-driven coatings demand dominates volume, while automotive and aerospace specifications command technical premium tiers.
- Construction:Residential and commercial architectural coatings represent the baseline consumption anchor across US and Canadian building markets.
- Automotive:Exterior panel and interior trim applications in US and Mexican plants drive rutile masterbatch specifications with durability certification requirements.
- Aerospace:Specialty coatings for airframe and component protection require ultra-high-performance grades with extended service life guarantees.
- Consumer Goods:Packaging plastics and personal care formulations span diverse specification tiers from commodity to cosmetic-grade compliance.
Established procurement patterns characterize Construction. Emerging specification intensity concentrates in Automotive lightweighting programs.
Distribution Channel:
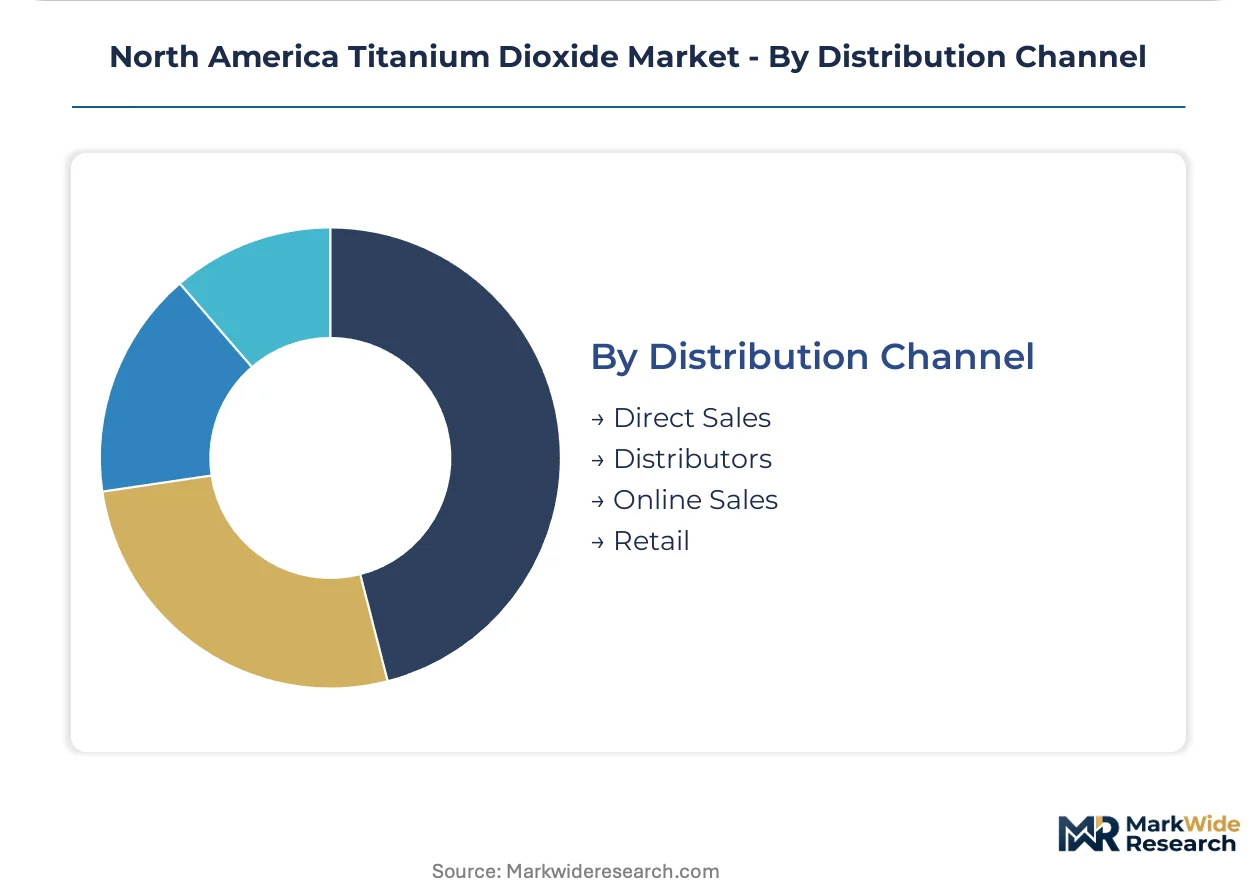
Direct supply relationships are displacing traditional distributor networks in high-volume architectural segments, while digital and retail channels serve fragmented specialty demand.
- Direct Sales:Large US and Canadian paint manufacturers negotiate chloride-route supply agreements with Mississippi corridor producers, eliminating intermediary margins in EPA-regulated low-VOC markets.
- Distributors:Regional chemical distributors retain relevance in specialty anatase and smaller-volume coatings formulations requiring technical service support.
- Online Sales:Digital procurement platforms serve mid-tier formulators seeking price transparency in standardized rutile grades.
- Retail:Consumer-facing channels move small-format specialty grades for DIY and artisanal cosmetic applications.
Channel consolidation favors Direct Sales in volume coatings. Distributor relevance persists in specialty grades requiring formulation guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for titanium dioxide concentrates along the US Gulf Coast petrochemical corridor, where coatings manufacturers cluster near chloride-route production facilities. EPA Clean Air Act enforcement drives reformulation toward TiO2-rich waterborne systems across the region.
United States
Architectural coatings producers in Texas and Louisiana are expanding TiO2 loading in low-VOC waterborne formulations. EPA emissions standards under the Clean Air Act mandate volatile organic compound reductions that favor TiO2-intensive systems. Mississippi corridor facilities supply rutile grades directly to Gulf Coast paint manufacturers, bypassing traditional distribution channels.
Canada
Health Canada cosmetic ingredient hotlist restrictions shape specialty anatase demand for mineral sunscreen formulations. Ontario-based production sites face evolving provincial PFAS contamination rules that could alter waste disposal protocols at legacy sulfate-process facilities. Quebec and Ontario construction markets anchor coatings consumption across residential and commercial building segments.
Mexico
Automotive assembly expansion in Querétaro and Guanajuato drives rutile masterbatch consumption for exterior body panels and interior trim components. Mexican manufacturing growth creates captive demand for high-durability grades from US Gulf Coast suppliers. Northern border states concentrate plastics compounding operations serving tier-one automotive suppliers.
North America Titanium Dioxide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated feedstock controllers commanding premium positioning in chloride-route rutile. The supplier base concentrates around three strategic archetypes: captive synthetic rutile operators, sulfate-process flexibility players, and specialty nano-grade registrants. Competitive moves center on direct mill relationship formation and regulatory dossier accumulation for modified pigment grades.
Within the integrated feedstock tier, The Chemours Company and Tronox Holdings plc exemplify chloride-route scale operators with Mississippi corridor presence. Kronos Worldwide, Inc. occupies a position representing sulfate-process flexibility serving specialty anatase niches. These three anchors demonstrate how production technology choice maps to end-use segment access across architectural coatings and cosmetic applications.
| Leading Market Players |
|---|
| Venator Materials PLC |
| LB Group |
| The Chemours Company |
| The Kish Company, Inc. |
| Evonik Industries AG |
| Tronox Holdings plc |
| INEOS |
| Argex Titanium Inc. |
| Kronos Worldwide, Inc. |
| Others |
Pricing and Supply Chain Analysis
Large architectural coatings manufacturers in the US Gulf Coast corridor negotiate direct chloride-route supply agreements, compressing intermediary margins and consolidating contract-based long-term offtake as the dominant pricing model. This buyer concentration shifts pricing power toward integrated producers with captive synthetic rutile supply.
Pricing Analysis
Volume concentrates in standard rutile grades where cost compression intensifies from calcium carbonate substitution in mid-tier interior paints, while margin capture clusters in specialty nano-grades facing extended EPA TSCA Section 5 registration timelines. Three-tier pricing structure across premium, standard, and economy levels differentiates by quality grade and certification level for Health Canada cosmetic compliance. Price differentiation stems from chloride-route energy efficiency advantages at Mississippi corridor facilities versus legacy sulfate-process overhead. Mid-tier paint formulators show highest price sensitivity, while automotive OEMs demonstrate lowest sensitivity due to durability certification requirements.
Supply Chain Analysis
Direct-to-mill channels handle high-volume architectural demand as coatings manufacturers bypass distributor intermediaries, while regional chemical distributors serve specialty anatase segments requiring technical service support. Feedstock supply concentrates in Australia, South Africa, and Canada as primary ilmenite and synthetic rutile sources. Production draws from titanium-bearing ores, chlorine gas, and petroleum coke as critical inputs. Single-source vulnerability from limited bulk shippers exposes Mississippi and Ontario facilities to bulk freight rate volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where feedstock security and regulatory dossier accumulation determine competitive durability. Players pursue backward integration into captive synthetic rutile supply as the decisive upstream lever.
For Market Incumbents: Lock in direct mill relationships with Gulf Coast coatings manufacturers to defend volume positions against distributor disintermediation. Secure chloride-route capacity expansion permits ahead of evolving state-level PFAS contamination rules at legacy sulfate-process sites. Accumulate EPA TSCA Section 5 pre-manufacture notification dossiers for surface-modified nano-grades to extend regulatory moats against specialty entrants.
For New Entrants and Emerging Players: Nano-grade surface modification technology offers the most penetrable wedge into cosmetic and mineral sunscreen segments where extended registration timelines favor established regulatory affairs capabilities. Target Health Canada-aligned dual-market entry pathways for specialty anatase grades. Pursue toll manufacturing arrangements with existing sulfate-process facilities to bypass capital-intensive chloride-route buildouts.
For Investors and Strategic Acquirers: The window for entry favors chloride-route operators with integrated feedstock control and established EPA regulatory dossiers. Long-term viability hinges on production technology choice rather than scale alone. Monitor EPA enforcement intensity for TSCA Section 5 pre-manufacture notifications as the inflection indicator for specialty grade margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rutile | Captive feedstock supply insulates Mississippi corridor producers from bulk shipping volatility. |
| Long-term Supply Agreement | Direct mill contracts with Gulf Coast coatings manufacturers compress distributor margin pools. |
| Capacity Expansion | Chloride-route additions at energy-advantaged Mississippi sites consolidate cost leadership. |
| Regulatory Dossier Accumulation | EPA TSCA Section 5 submissions for nano-grades extend timelines for cosmetic applications. |
| Joint Venture | Mexican automotive masterbatch partnerships in Querétaro capture lightweighting demand. |
Research Methodology
Independent corroboration across plant managers at chloride-route facilities, procurement leads at downstream coatings manufacturers, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, American Chemistry Council reports, SEC 10-K filings, and EPA enforcement records. Bottom-up capacity and consumption estimates triangulate against top-down macroeconomic indicators.
Comparable historical periods anchor the projection horizon across product type, application, and regional production hub dimensions. CAGRs derive from segment-specific demand elasticity modeling calibrated to EPA regulatory enforcement intensity and automotive production forecasts. Modeled inputs include coatings reformulation rates, masterbatch incorporation ratios, and chloride-route capacity utilization assumptions.
Several conditions sit outside the modeled scope, including unanticipated EPA rulemaking acceleration, abrupt feedstock supply disruptions from geopolitical events, and breakthrough substitution technologies. Forecasts reflect assumptions about regulatory continuity and feedstock price stability. Practitioners should monitor EPA TSCA Section 5 notification backlog trends and state-level PFAS mining waste rule evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market