
 Dithiocarbamates Market | 2026-2036
Dithiocarbamates Market Size, Share, and Industry Trends Forecast 2026-2036
Dithiocarbamates Market Analysis
Rubber processing demand is repositioning dithiocarbamate procurement toward sulfur donor accelerators and vulcanization agents. UPL Limited leverages its agrochemical distribution network to sustain dual-channel supply into both crop protection and rubber chemical buyers. LANXESS AG anchors European manufacturing scale through backward integration into key intermediates, while Dow Chemical Company competes on specification-grade purity for specialty polymer applications.
Dithiocarbamates are sulfur-nitrogen chelating compounds formed by reacting carbon disulfide with primary or secondary amines, typically containing a functional group with the general formula R1R2N-CS2- and serving primarily as accelerators in rubber vulcanization and fungicides in crop protection. Dithiocarbamate salts dominate volume production due to their straightforward synthesis and established use in agricultural fungicide formulations, while dithiocarbamate esters command premium positioning through specialized rubber accelerator applications where thermal stability requirements are stringent. The agriculture application segment retains mature volume leadership though faces margin compression from regulatory re-registration costs, whereas rubber processing generates expanding margin pools as tire manufacturers reformulate for lower rolling resistance specifications.
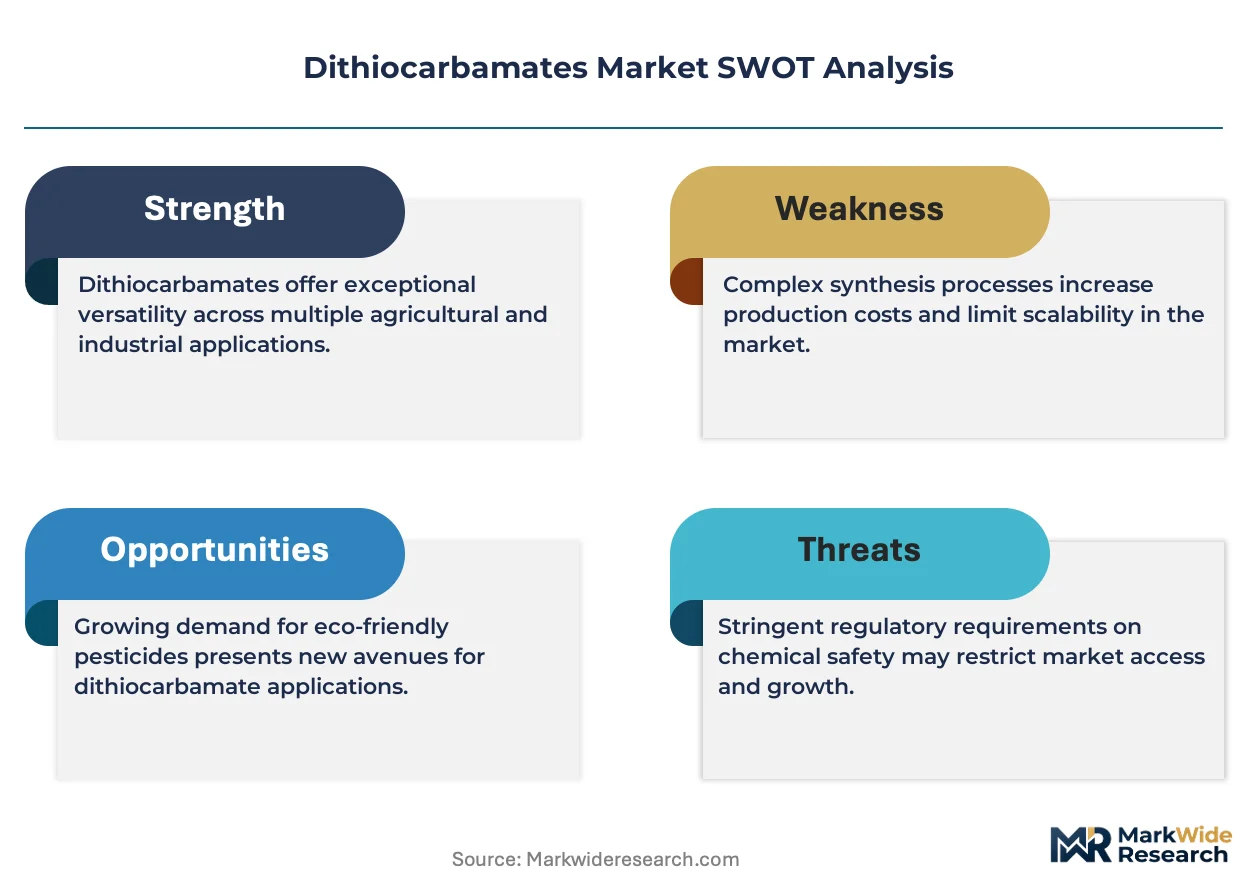
EPA registration requirements under FIFRA govern agricultural dithiocarbamate fungicide sales in the United States, while REACH compliance and the EU Green Deal chemical sustainability framework constrain active ingredient approvals across Europe. India's Central Insecticides Board mandates dual registration for import and formulation, creating layered market access barriers that favor established domestic producers. Stakeholders must monitor evolving residue tolerance harmonization between EPA, EFSA, and India's FSSAI to anticipate reformulation investment cycles and geographic portfolio rebalancing.
Market Dynamics
Rubber manufacturers are reformulating vulcanization systems to meet lower rolling resistance tire specifications, pulling dithiocarbamate demand toward sulfur donor accelerators with superior thermal stability profiles.
Growth Catalysts
- EU Green Deal chemical sustainability framework:REACH re-registration timelines are compressing active ingredient portfolios toward higher-margin specialty grades that command premium positioning in rubber processing applications.
- Tire industry reformulation cycles:Rolling resistance mandates from automotive OEMs are accelerating adoption of zinc-free and low-nitrosamine dithiocarbamate variants in passenger vehicle tire compounds.
- India:Domestic agrochemical manufacturing expansion under PLI scheme incentives is building captive dithiocarbamate intermediate capacity that feeds both crop protection and rubber chemical value chains.
Market Restraints
- Carbon disulfide feedstock volatility:Petrochemical input cost swings compress formulation margins for salt-grade dithiocarbamates used in high-volume fungicide applications.
- European regulatory friction:ECHA substance evaluation deadlines are extending re-registration timelines for established active ingredients, freezing portfolio investment decisions.
- Biological fungicide substitution:Microbial biocontrol agents are displacing dithiocarbamate-based protectants in specialty crop segments with shorter residue tolerance windows.
Strategic Opportunities
- Brazil:ANVISA registration harmonization with OECD test guidelines is opening streamlined market access for dithiocarbamate fungicide formulations in soybean and sugarcane protection.
- Recovered carbon black integration:Dithiocarbamate accelerator systems are converging with tire pyrolysis feedstock streams to enable closed-loop rubber compound manufacturing.
- India's FSSAI residue harmonization:Alignment with Codex Alimentarius maximum residue limits is reducing dual-testing burdens for export-oriented formulation producers.
Industry Challenges
- Process analytical chemistry talent scarcity:Regulatory submission requirements for impurity profiling and metabolite identification are outpacing specialist workforce availability in contract research organizations.
- Legacy formulation equipment retrofit costs:Dust-free granulation and extrusion systems require capital outlays that strain mid-tier producers serving generic fungicide markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dithiocarbamates Market |
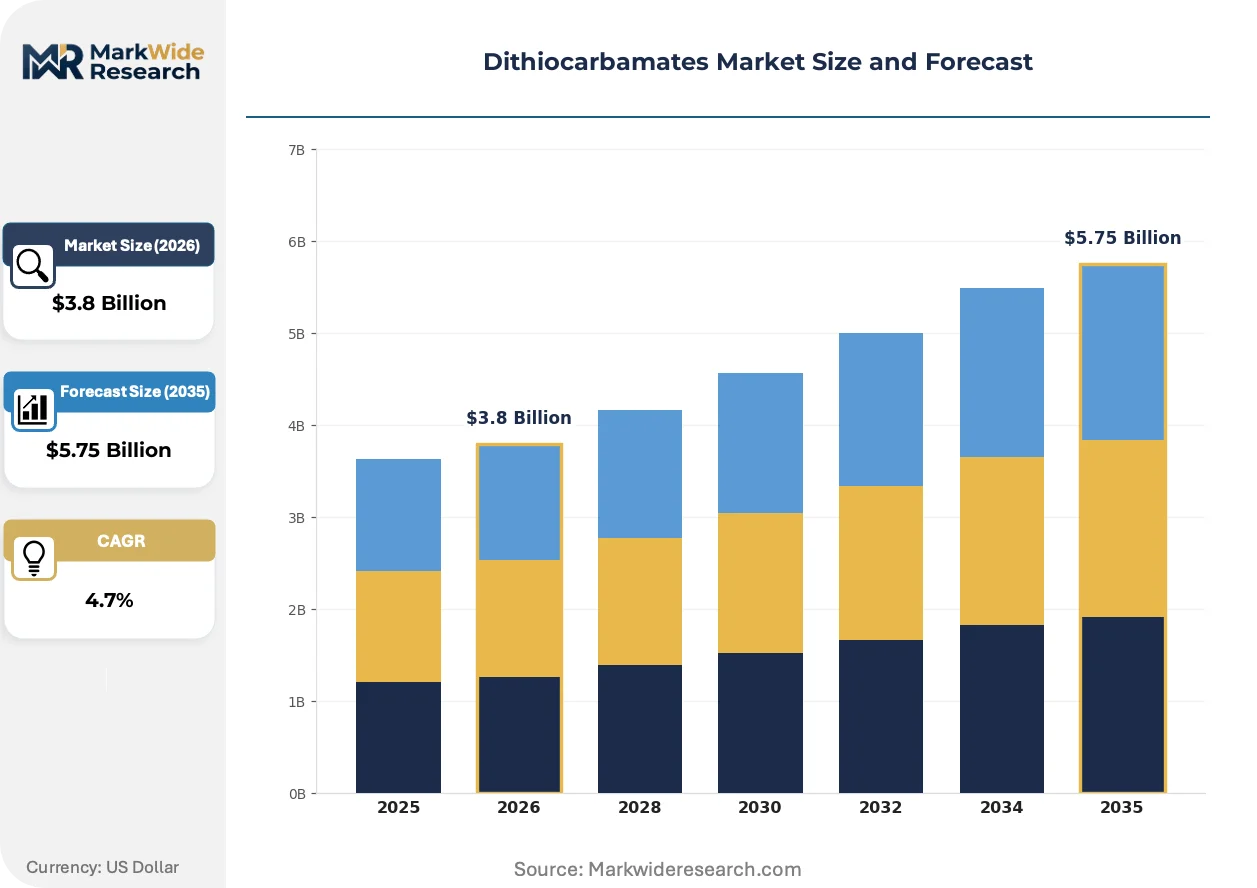
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dithiocarbamate Salts, Dithiocarbamate Esters, Sodium Dithiocarbamate, Potassium Dithiocarbamate Application: Agriculture, Rubber Processing, Mining, Chemical Synthesis End User: Agricultural Sector, Mining Companies, Chemical Manufacturers, Industrial Users Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | UPL Limited, LANXESS AG, Dow Chemical Company, BASF SE, Arkema Group, Coromandel International, Indofil Industries Limited, ADAMA Ltd., Limin Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dithiocarbamates Market Emerging Trajectories
Formulation chemistry and regulatory compliance systems are advancing in parallel, with sulfur donor technology and residue analytics driving product differentiation across rubber and agricultural end uses.
Ultra-accelerator dithiocarbamate complexes are converging with silica-reinforced tire compound formulations to enable faster cure cycles without sacrificing scorch safety. Bridgestone and Michelin compound development centers in Japan and France are piloting these systems at production scale. The technology is converging with automated mixing line investments to compress batch-to-batch variability and reduce manufacturing energy intensity.
REACH restriction proposal procedures for zinc compounds are forcing reformulation of conventional zinc-based dithiocarbamate accelerators toward metal-free alternatives. Compounders serving European automotive OEMs face mandatory substitution timelines by 2027. Tire manufacturers with integrated European mixing capacity are accelerating qualification programs for zinc-free dithiocarbamate ester variants to defend supply contracts.
Long-term offtake agreements are displacing spot market purchasing for dithiocarbamate rubber chemicals as tire manufacturers consolidate supplier bases to manage formulation complexity. Tier-one compounders are embedding technical service teams directly at tire plant mixing facilities to co-develop application-specific accelerator packages. This pattern is most visible in Germany and the US where automotive OEMs enforce approved supplier list requirements for critical rubber chemicals.
Dithiocarbamates Market Segmentation
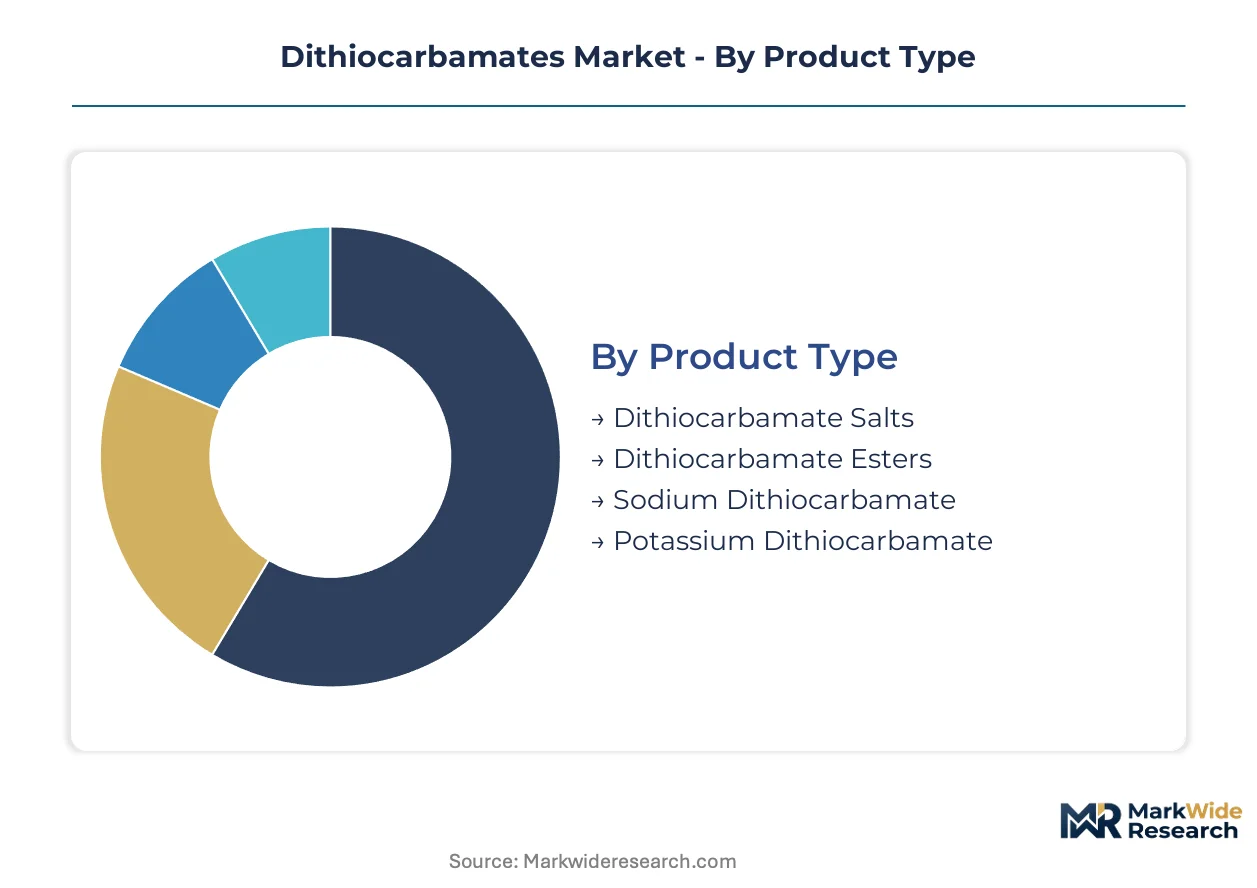
Dithiocarbamate market segmentation reveals divergent capital requirements across product chemistry and end-use specifications. Rubber processing and agricultural applications impose distinct technical standards that reshape investment priorities for manufacturers scaling capacity.
Product Type:
Capital intensity varies sharply across salt versus ester chemistries, with synthesis complexity and purification infrastructure driving fixed cost differentials.
- Dithiocarbamate Salts:Water-soluble ionic compounds manufactured through direct carbon disulfide-amine reaction with straightforward precipitation recovery. Agricultural fungicide demand in India absorbs the majority of salt-grade capacity under PLI scheme incentives.
- Dithiocarbamate Esters:These neutral organic derivatives require multi-step synthesis with stringent thermal stability controls for rubber accelerator applications. Bridgestone and Michelin compound specifications in Japan and France are pulling ester demand toward ultra-accelerator complexes with superior scorch safety profiles.
- Sodium Dithiocarbamate:Alkali metal salt variant serving niche flotation reagent applications in copper and zinc ore processing.
- Potassium Dithiocarbamate:Higher solubility analogue deployed in specialized rubber cure systems requiring rapid ion exchange kinetics.
Dithiocarbamate salts absorb the bulk of installed capacity; dithiocarbamate esters are expanding most quickly.
Application:
Margin structure diverges across mature agricultural protectants versus reformulating rubber chemical systems.
- Agriculture:Mature fungicide segment facing margin compression from ECHA re-registration costs and biological substitution pressure in European specialty crops.
- Rubber Processing:Vulcanization accelerator demand concentrates in tire manufacturing reformulation for EU rolling resistance mandates. Zinc-free dithiocarbamate variants are gaining qualification status at German automotive OEM mixing facilities ahead of REACH restriction timelines.
- Mining:Flotation collector applications in copper and polymetallic ore beneficiation.
- Chemical Synthesis:Intermediate demand for pharmaceutical and agrochemical active ingredient manufacturing.
Agriculture retains volume leadership; rubber processing is climbing the fastest on value-added reformulation cycles.
End User:
Procurement sophistication separates commodity buyers from specification-driven compound developers.
- Agricultural Sector:Generic fungicide formulators and plantation operators purchasing salt-grade materials through distributor networks.
- Mining Companies:Concentrator operators specifying dithiocarbamate collectors for sulfide ore flotation circuits.
- Chemical Manufacturers:Multi-step synthesis houses requiring high-purity intermediates with documented impurity profiles.
- Industrial Users:Diverse rubber compounders, adhesive formulators, and specialty chemical blenders.
Chemical manufacturers impose the most stringent qualification protocols; agricultural sector procurement is expanding most quickly in India and Brazil.
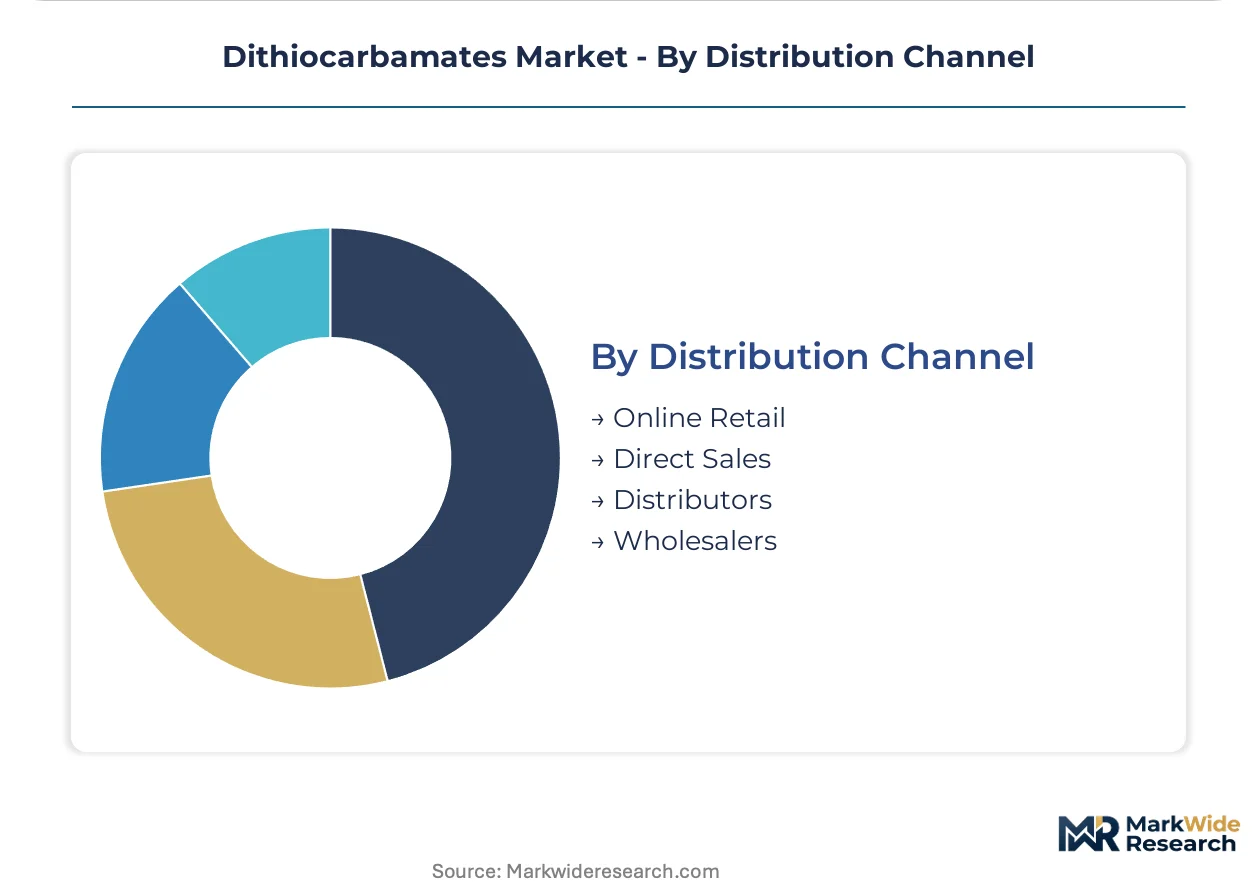
Distribution Channel:
Channel economics reflect product standardization and technical service requirements.
- Online Retail:Limited to small-volume laboratory reagents and analytical standards.
- Direct Sales:Tier-one tire manufacturers embed supplier technical teams at mixing facilities for co-developed accelerator packages.
- Distributors:Regional chemical distributors serving mid-tier rubber compounders and agricultural formulators.
- Wholesalers:Volume handlers of commodity salt grades for fungicide blending operations.
Direct sales capture the highest-margin specialty volumes; distributor channels are gaining share fastest in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions are concentrating dithiocarbamate capacity under PLI scheme incentives. Germany's chemical parks anchor European reformulation activity for REACH-compliant variants. China's Yangtze River Delta maintains intermediate production scale for export-oriented salt grades.
India
Rubber accelerator demand from tire manufacturers in Chennai and Pune is pulling dithiocarbamate procurement toward sulfur donor systems. The Central Insecticides Board's dual registration mandate for import and formulation creates layered barriers favoring domestic producers. Coromandel International and UPL Limited operate integrated manufacturing complexes in Andhra Pradesh and Maharashtra that supply both agrochemical and rubber chemical value chains.
Germany
Automotive OEM rolling resistance specifications are accelerating zinc-free dithiocarbamate qualification programs at tire mixing facilities. ECHA substance evaluation deadlines under REACH are compressing active ingredient portfolios toward specialty grades. LANXESS AG leverages backward integration into key intermediates at its Leverkusen and Krefeld sites to defend supply contracts with integrated European compounders.
United States
EPA registration requirements under FIFRA govern agricultural fungicide sales while tire manufacturers reformulate for Corporate Average Fuel Economy standards. The Southeast rubber belt spanning Georgia and South Carolina concentrates mixing capacity for passenger vehicle tire production. Dow Chemical Company competes on specification-grade purity for specialty polymer applications serving automotive OEM approved supplier lists.
China
Carbon disulfide feedstock availability from coal-chemical complexes supports salt-grade dithiocarbamate production for export markets. NMPA registration harmonization with OECD test guidelines is streamlining agrochemical export documentation. Limin Chemical and regional producers in the Yangtze River Delta maintain volume positions in generic fungicide intermediates despite margin compression from environmental compliance upgrades.
Brazil
Soybean and sugarcane protection demand is expanding formulation capacity for dithiocarbamate-based fungicides in the Cerrado region. ANVISA registration harmonization with OECD guidelines is reducing testing burdens for imported active ingredients. Regional distributors are building blending infrastructure in Mato Grosso and Goiás to serve plantation operators with shorter procurement lead times.
Dithiocarbamates Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates defending position in specification-grade rubber accelerators while regional formulators capture agricultural salt-grade volumes. The vendor base organizes into three tiers: multinational integrated producers with backward integration into intermediates, domestic champions leveraging distribution networks for dual-channel supply, and specialty chemical houses focused on ultra-pure ester variants. Consolidation pressure concentrates in European rubber chemical segments where REACH compliance costs favor scale, while agricultural fungicide markets retain fragmentation due to distributor-centric procurement patterns. Competitive moves center on long-term offtake agreements with tire manufacturers and PLI-linked capacity expansion in India.
Among multinational integrated producers, LANXESS AG and Dow Chemical Company exemplify the capital-intensive archetype with captive intermediate supply and automotive OEM qualification status. UPL Limited occupies a distinct position as a domestic champion with dual-channel reach into both crop protection and rubber chemical buyers through its agrochemical distribution infrastructure. These three anchors represent divergent strategic postures: European manufacturing scale, American specification-grade purity competition, and Indian PLI-leveraged domestic capacity integration.
| Leading Market Players |
|---|
| UPL Limited |
| LANXESS AG |
| Dow Chemical Company |
| BASF SE |
| Arkema Group |
| Coromandel International |
| Indofil Industries Limited |
| ADAMA Ltd. |
| Limin Chemical |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical sustainability framework compliance gates qualified supply access and premium-tier pricing for zinc-free dithiocarbamate ester variants. Tire manufacturers in Germany and France now mandate REACH-compliant accelerator packages, compressing margins on salt-grade fungicide materials while elevating pricing power for specification-grade rubber chemicals with documented impurity profiles.
Pricing Analysis
Short lead-time premiums dominate dithiocarbamate rubber chemical procurement as tire manufacturers consolidate approved supplier lists. Contract-based long-term offtake agreements anchor pricing for specification-grade esters, while spot inventory trades at discounts in agricultural salt-grade markets. Price differentiation hinges on REACH certification tier and carbon disulfide feedstock purity grade. Pricing pressure stems from carbon disulfide volatility squeezing salt-grade margins. Agricultural formulators in India exhibit highest price sensitivity; German automotive OEM compounders show least sensitivity due to qualification lock-in.
Supply Chain Analysis
Dual-sourcing requirements from Bridgestone and Michelin mandate multi-supplier qualification for ultra-accelerator dithiocarbamate complexes. Supply concentrates in India, Germany, and China for distinct tier requirements. Carbon disulfide, primary and secondary amines, and precipitation recovery systems constitute critical input dependencies. Single-source vulnerability around carbon disulfide feedstock from coal-chemical complexes in China's Yangtze River Delta poses structural risk. Distribution runs through direct technical service teams at tire mixing facilities for premium tiers, with regional distributors handling agricultural salt-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dithiocarbamate markets are transitioning from zinc-based to metal-free accelerator systems as REACH restriction proposals force reformulation cycles. Zinc-free dithiocarbamate ester technology is displacing legacy zinc-based variants in European tire manufacturing.
For Market Incumbents: Anticipate biological fungicide substitution in European specialty crops by accelerating zinc-free dithiocarbamate ester qualification programs at German automotive OEM mixing facilities. Backward integration into carbon disulfide and amine intermediates defends margin position against feedstock volatility. Lock in long-term offtake agreements with tier-one tire manufacturers before REACH restriction timelines consolidate supplier bases further. For New Entrants and Emerging Players: Enter via Brazil's ANVISA registration harmonization pathway for dithiocarbamate fungicide formulations serving soybean and sugarcane protection in the Cerrado region. The agricultural salt-grade segment offers lowest qualification barriers compared to rubber chemical specification tiers. Partner with regional distributors building blending infrastructure in Mato Grosso and Goiás to bypass direct sales team requirements. For Investors and Strategic Acquirers: ECHA substance evaluation deadline extensions freezing portfolio investment decisions are the leading indicator that consolidation pressure is concentrating in European rubber chemical segments. The five-to-ten year viability window favors acquisition targets with captive intermediate supply and automotive OEM qualification status. Monitor zinc compound REACH restriction proposal advancement as the critical inflection signal for metal-free accelerator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive carbon disulfide and amine supply shields margin from petrochemical volatility at LANXESS Leverkusen complex. |
| Long-term Supply Agreement | Tier-one tire manufacturers embed technical teams at mixing facilities to co-develop accelerator packages with qualified suppliers. |
| Green Manufacturing Transition | Zinc-free dithiocarbamate ester production qualifies for EU Green Deal chemical sustainability framework incentives. |
| Capacity Expansion | India's PLI scheme incentives build captive intermediate capacity feeding both agrochemical and rubber chemical value chains. |
| Joint Venture | Regional distributors in Brazil's Cerrado region partner with formulators to shorten procurement lead times for plantation operators. |
Methodological Framework
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone for dithiocarbamate market sizing and competitive positioning analysis. Primary interviews with rubber compound procurement leads at tire manufacturers, agrochemical formulator technical directors, and carbon disulfide plant managers validated production capacity and qualification timeline assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against downstream consumption patterns in rubber processing and agricultural applications.
Bottom-up modeling aggregated segment-level consumption across product type, application, and end-user dimensions, while top-down analysis tracked carbon disulfide feedstock availability and REACH registration status. The projection horizon spans from base year through forecast endpoint with CAGRs derived from elasticity-adjusted demand curves. Segment growth rates incorporated tire industry reformulation cycles for rolling resistance compliance and PLI scheme capacity expansion timelines in India.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance evaluation deadline delays or accelerated biological fungicide substitution in European specialty crops. Deviation in carbon disulfide feedstock pricing or REACH zinc compound restriction implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Global Cyclopentane Market