
 ASEAN Sulfur Market | 2026-2036
ASEAN Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Sulfur Market Outlook
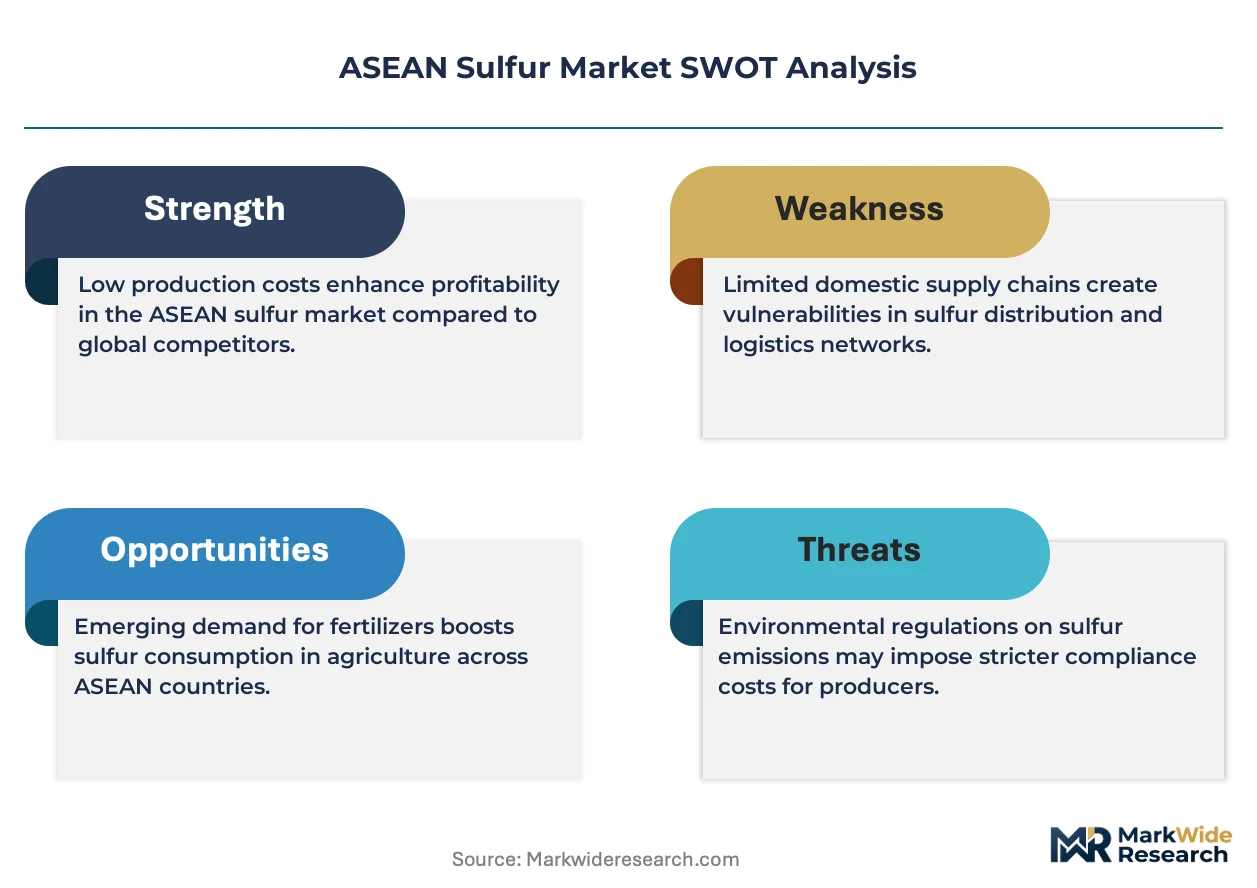
Project finance tied to state-backed petrochemical complexes is tilting competitive access toward integrated energy majors with sovereign balance-sheet support. Petronas leverages its Malaysian sour-gas processing infrastructure to captive-produce granular sulfur for domestic fertilizer and rubber chemical customers. PT Pertamina (Persero) anchors Indonesian supply through refinery sulfur recovery units serving East Java's agrochemical manufacturers. SINOPEC competes via cross-border liquid sulfur shipments into Thai and Vietnamese port terminals, extending its Southeast Asian trading footprint.
Sulfur, a bright yellow nonmetal occurring naturally in elemental form and as hydrogen sulfide in sour natural gas and crude oil, typically achieves purity exceeding 99.5 percent through the Claus process before conversion to sulfuric acid or direct agricultural application. The element serves primarily as the indispensable feedstock for sulfuric acid production, which underpins phosphate fertilizer manufacture, metal ore leaching, and petroleum refining. Granular sulfur dominates ASEAN trade flows due to superior handling characteristics and ocean freight economics, while liquid sulfur commands premium positioning among integrated refinery-chemical complexes with dedicated pipeline offtake. Fertilizers as an application category sit at the center of regional demand, with sulfuric acid production representing the critical intermediate step where margin pools concentrate among Claus-unit operators with captive acid plants.
Indonesia's Ministry of Energy and Mineral Resources enforces sulfur recovery mandates at sour-gas processing facilities, directing elemental sulfur into domestic chemical manufacturing rather than export bulk. Vietnam's Ministry of Agriculture and Rural Development regulates fertilizer quality standards that specify sulfur content thresholds for compound and blended products, shaping importer procurement specifications. Thailand's Department of Industrial Works administers hazardous substance controls on sulfur storage and handling that constrain small distributor participation. Stakeholders must track how evolving national downstream requirements in each ASEAN member state reshape sulfur allocation between export markets and domestic value-added processing.
Market Dynamics
Indonesia's Ministry of Energy and Mineral Resources enforces sulfur recovery mandates at sour-gas processing facilities, redirecting elemental sulfur from export bulk into domestic chemical manufacturing and tightening regional supply availability for fertilizer producers across ASEAN.
Growth Catalysts
- Agricultural intensification:Vietnam's Mekong Delta fertilizer corridor and Indonesia's East Java industrial belt are expanding phosphate fertilizer capacity, pulling additional sulfuric acid feedstock through integrated chemical complexes.
- Downstream mandates:National policies in Malaysia and Indonesia require state energy majors to channel refinery sulfur into domestic value chains rather than seaborne export, building captive supply security for regional manufacturers.
- Claus process optimization:Advanced sulfur recovery units at sour-gas facilities are achieving purity thresholds exceeding 99.5 percent, enabling direct agricultural application without intermediate acid conversion.
Market Restraints
- Input cost volatility:Natural gas price fluctuations directly impact hydrogen sulfide processing economics at sour-gas facilities, compressing margins for Claus-unit operators without long-term feedstock contracts.
- Supply concentration risk:Indonesia's state-controlled energy infrastructure directs the majority of domestic sulfur allocation toward PT Pertamina-linked chemical complexes, limiting independent distributor access to bulk granular product.
- Substitution pressure:Phosphate rock processing innovations in select Chinese facilities are reducing sulfuric acid intensity per ton of fertilizer output, threatening long-term demand elasticity in import-dependent ASEAN markets.
Strategic Opportunities
- Underpenetrated geography:The Philippines' fertilizer manufacturing base remains import-dependent for sulfur feedstock, creating white space for cross-border liquid sulfur terminal infrastructure at Batangas or Subic Bay.
- Technology convergence:Integration of digital inventory management with granular sulfur handling systems is enabling just-in-time delivery models for mid-sized rubber chemical processors in Thailand's Eastern Economic Corridor.
- Regulatory tailwind:Vietnam's Ministry of Agriculture and Rural Development quality standards mandate minimum sulfur content in compound fertilizers, embedding structural demand for high-purity elemental sulfur in importer procurement specifications.
Industry Challenges
- Capex intensity:Dedicated liquid sulfur pipeline infrastructure requires substantial upfront investment, constraining smaller Vietnamese distributors from securing direct refinery offtake agreements.
- Compliance complexity:Thailand's Department of Industrial Works hazardous substance controls on sulfur storage and handling impose certification timelines that disqualify informal traders from formal supply chain participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Sulfur Market |
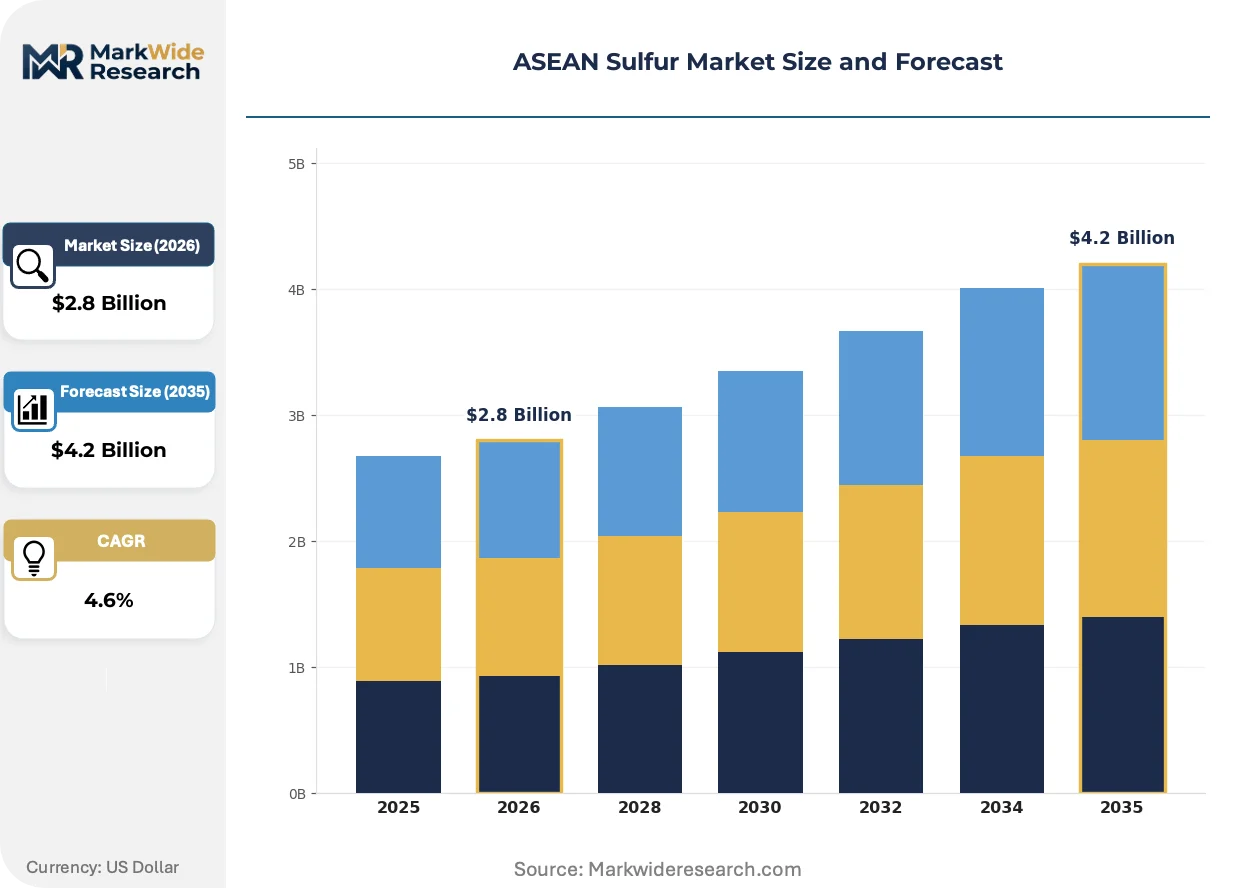
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Sulfur, Liquid Sulfur, Powdered Sulfur, Sulfur Pellets End User: Agriculture, Chemical Industry, Oil Refineries, Pharmaceuticals Application: Fertilizers, Rubber Processing, Sulfuric Acid Production, Pesticides Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Petronas, PT Pertamina (Persero), Shell plc, Abu Dhabi National Oil Company, QatarEnergy, China Petroleum & Chemical Corporation (SINOPEC), PETROVIETNAM CHEMICAL AND SERVICES CORPORATION (PVDMC), PT Candi Ngrimbi, Qatar Petroleum for the Sale of Petroleum Products Company Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Sulfur Market Strategic Shifts
Digital logistics platforms and advanced handling technologies are compressing traditional supply chain layers between Claus-unit operators and end-use fertilizer manufacturers across Southeast Asia.
Membrane-based sulfur recovery extensions are collapsing the capital cost differential between large-scale sour-gas processing facilities and mid-sized refinery sulfur recovery units. Indonesian fertilizer producers with captive acid plants are adopting these modular extensions to reduce dependence on imported granular sulfur. The technology is collapsing barriers to backward integration that previously favored only integrated energy majors with sovereign balance-sheet capacity.
Indonesia's Ministry of Energy and Mineral Resources sulfur recovery mandates are hardening into enforceable allocation requirements with quarterly compliance reporting. Industrial consequence includes mandatory domestic sulfur reservation quotas that supersede export contracts for integrated energy producers. East Java's agrochemical manufacturers are securing preferential pipeline access under these rules while spot market participants face tightened bulk availability.
Consolidation among Vietnamese fertilizer distributors is compressing procurement cycles from quarterly spot purchasing toward annual framework agreements with fixed-volume clauses. Mid-sized compound fertilizer blenders in the Mekong Delta are ceding negotiating leverage to larger integrated producers with direct acid plant ownership. This pattern is most visible in An Giang and Dong Thap provinces where phosphate fertilizer complexes anchor regional consumption clusters.
ASEAN Sulfur Market Segmentation
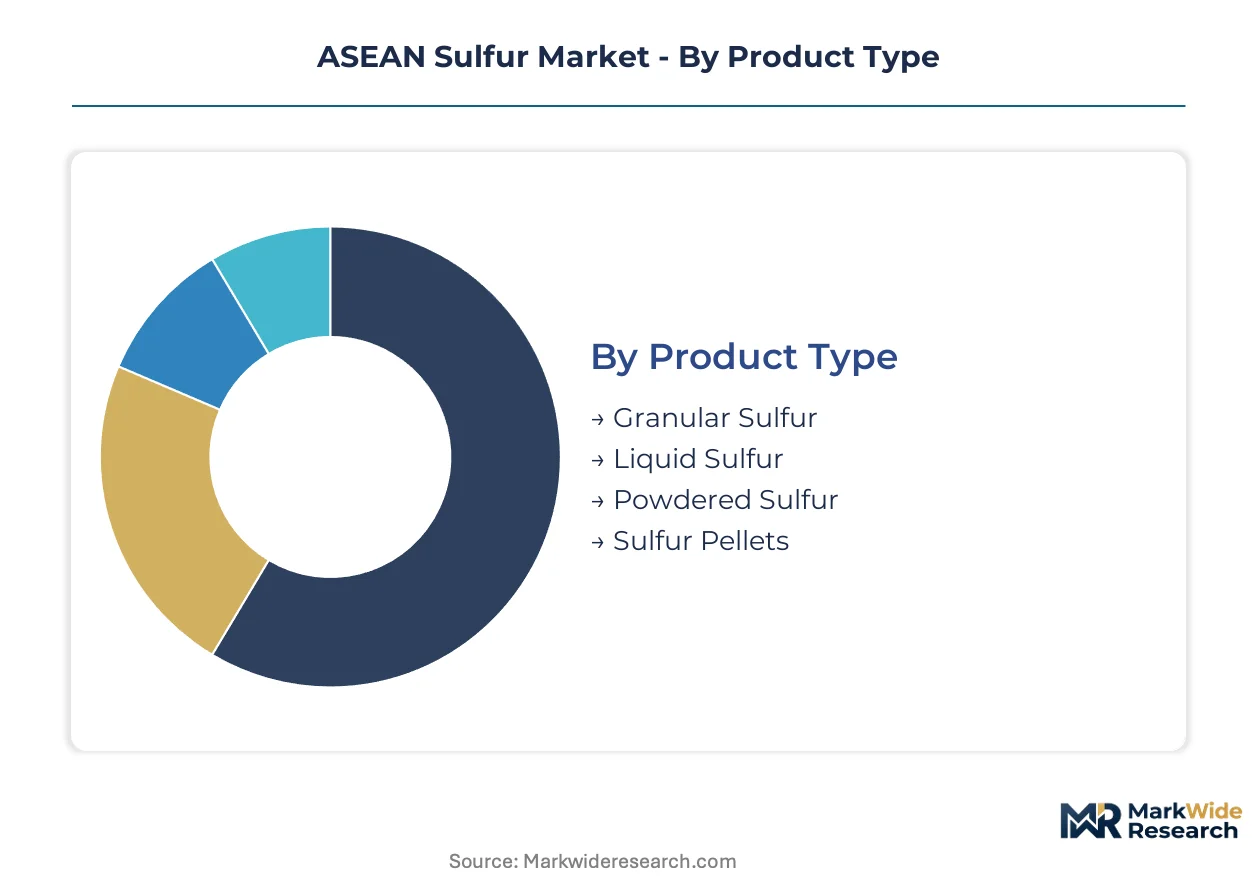
Sulfur market segmentation in ASEAN reflects divergent handling economics and downstream integration levels. Product form determines freight costs and storage infrastructure requirements. End-user concentration shapes procurement patterns across state-backed energy majors and independent fertilizer distributors.
Product Type:
Handling characteristics and supply chain economics span four distinct physical forms serving integrated refineries and distributed agricultural markets.
- Liquid Sulfur:Maintained above 115°C in insulated tankage and dedicated pipelines, this form commands premium positioning among refinery-chemical complexes with continuous offtake agreements. PT Pertamina's East Java complexes and Petronas's Malaysian sour-gas facilities leverage direct pipeline access to captive acid plants, eliminating granular handling costs entirely.
- Granular Sulfur:Formed into 2-4mm prills with superior flow characteristics and ocean freight economics, this product dominates ASEAN seaborne trade. Vietnam's Mekong Delta fertilizer corridor and Indonesia's East Java industrial belt absorb bulk shipments through dedicated port terminals at Cai Mep and Gresik.
- Sulfur Pellets:Compressed into dense cylindrical forms for specialized rubber chemical applications in Thailand's Eastern Economic Corridor.
- Powdered Sulfur:Micronized material serving niche pharmaceutical and pesticide formulation requirements with strict purity certifications.
The dominant share belongs to granular sulfur, while liquid sulfur is closing the gap fastest through refinery integration mandates.
End User:
Customer concentration varies from sovereign energy majors with captive supply to fragmented agricultural distributors dependent on spot procurement.
- Agriculture:Phosphate fertilizer manufacturers across Vietnam's An Giang province and Indonesia's East Java belt constitute the volume anchor. These compound fertilizer blenders specify minimum sulfur content thresholds under Vietnam's Ministry of Agriculture and Rural Development quality standards, embedding structural demand for high-purity elemental sulfur in procurement contracts.
- Chemical Industry:Sulfuric acid producers and rubber chemical processors in Thailand's Eastern Economic Corridor drive specification-grade demand. Digital inventory management systems are enabling just-in-time delivery models for mid-sized processors previously excluded from direct refinery offtake.
- Oil Refineries:Integrated Claus-unit operators serve internal acid plant requirements under national downstream mandates.
- Pharmaceuticals:Specialized micronized sulfur applications for dermatological and industrial chemical synthesis with stringent purity documentation.
Agriculture commands the dominant consumption position, though chemical industry procurement is expanding most quickly through rubber processing growth.
Application:
Value capture concentrates at the sulfuric acid conversion stage where margin pools favor integrated producers with captive Claus units.
- Sulfuric Acid Production:The indispensable intermediate step consuming over 80% of regional sulfur intake. Indonesian fertilizer producers with captive acid plants are adopting membrane-based sulfur recovery extensions to reduce import dependence. The technology collapses barriers to backward integration that previously favored only sovereign balance-sheet capacity.
- Fertilizers:Phosphate rock processing via the wet acid method anchors demand in Vietnam's Mekong Delta corridor. Chinese phosphate processing innovations threaten long-term sulfuric acid intensity per ton of output in import-dependent ASEAN markets.
- Rubber Processing:Vulcanization accelerators and rubber chemicals for Thailand's tire manufacturing sector.
- Pesticides:Sulfur-based fungicides and intermediate chemicals for Southeast Asian agricultural protection.
Sulfuric acid production holds the dominant application share, while fertilizer demand is gaining share fastest through agricultural intensification policies.
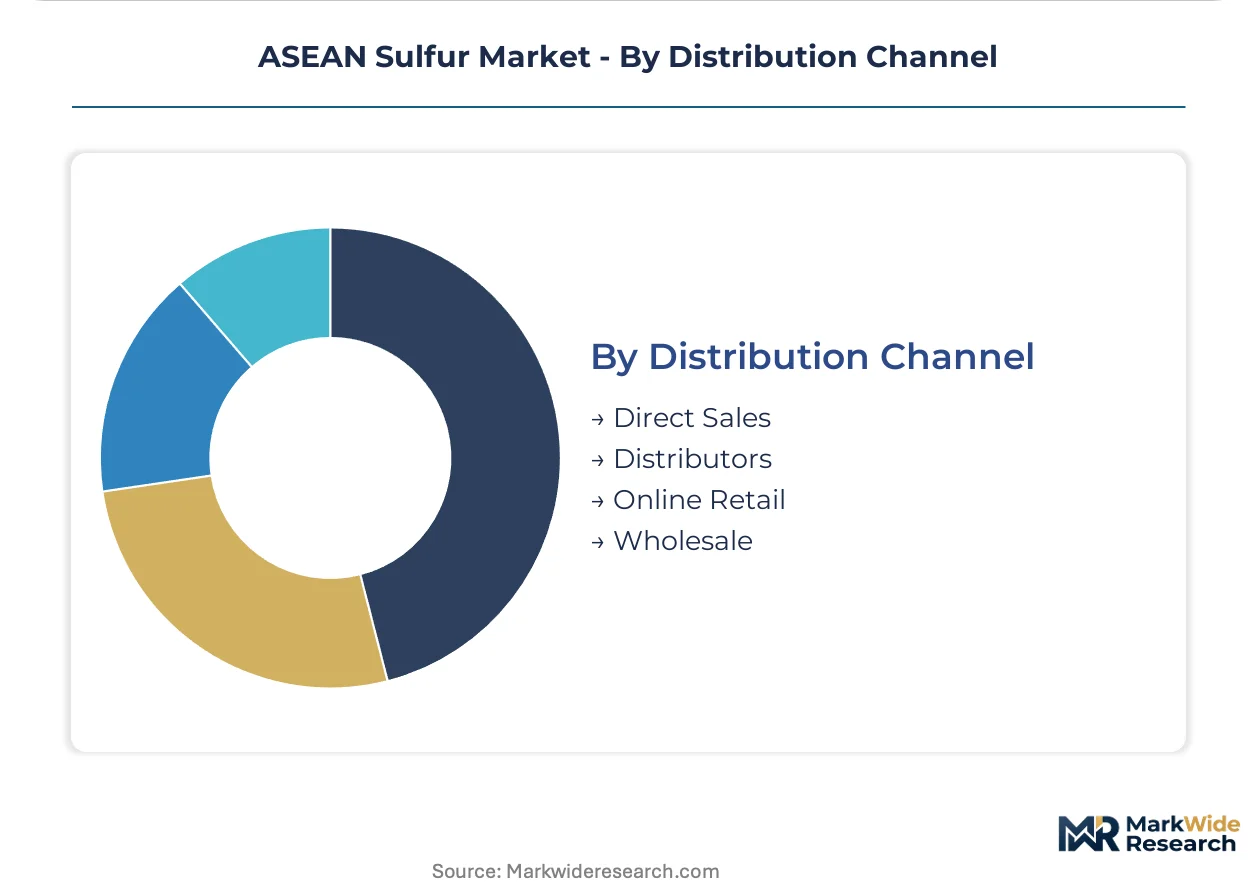
Distribution Channel:
Channel structure reflects the tension between sovereign energy majors with direct pipeline access and fragmented distributors facing storage certification barriers.
- Direct Sales:Long-term offtake agreements between Claus-unit operators and integrated fertilizer complexes with dedicated pipeline or tanker access. PT Pertamina and Petronas leverage this channel to satisfy national downstream mandates while excluding independent traders.
- Distributors:Regional bulk handlers with certified storage infrastructure serving mid-sized compound fertilizer blenders. Thailand's Department of Industrial Works hazardous substance controls constrain participation to formal operators with compliance documentation.
- Wholesale:Aggregated bulk shipments for provincial fertilizer cooperatives in Vietnam's Dong Thap and Long An provinces.
- Online Retail:Emerging platform for specialty sulfur products and agricultural micronutrient blends.
Direct sales capture the dominant channel share, while distributor consolidation is reshaping procurement fastest toward annual framework agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed energy majors with integrated sour-gas processing infrastructure command procurement leverage over independent fertilizer distributors. National downstream mandates channel refinery sulfur into domestic chemical value chains, tightening spot market availability. Geographic demand concentrates in Vietnam's Mekong Delta corridor and Indonesia's East Java industrial belt.
Indonesia
East Java's agrochemical manufacturers anchor regional sulfur consumption through phosphate fertilizer complexes. The Ministry of Energy and Mineral Resources enforces mandatory domestic sulfur reservation quotas that supersede export contracts for integrated energy producers. Gresik industrial zone hosts PT Pertamina-linked chemical complexes securing preferential pipeline access under quarterly compliance reporting requirements.
Vietnam
Mekong Delta fertilizer blenders in An Giang and Dong Thap provinces drive granular sulfur offtake for compound fertilizer production. The Ministry of Agriculture and Rural Development mandates minimum sulfur content thresholds in quality standards for imported products. Cai Mep port terminals handle bulk seaborne shipments serving phosphate processing facilities clustered along the delta corridor.
Malaysia
Petronas leverages sour-gas processing infrastructure to captive-produce granular sulfur for domestic rubber chemical and fertilizer customers. National downstream policies require state energy majors to prioritize domestic value chain integration over seaborne export. Integrated Claus-unit operators at Malaysian refineries serve internal acid plant requirements under sovereign balance-sheet supported project finance structures.
Thailand
Rubber chemical processors in the Eastern Economic Corridor drive specification-grade sulfur demand for vulcanization accelerators. The Department of Industrial Works administers hazardous substance controls on storage and handling that constrain informal trader participation. Mid-sized compounders adopt digital inventory management systems enabling just-in-time delivery models previously excluded from direct refinery offtake.
Philippines
Fertilizer manufacturing capacity remains import-dependent for sulfur feedstock with limited domestic sour-gas processing infrastructure. National agricultural intensification programs expand phosphate fertilizer demand without matching domestic sulfur supply development. Batangas and Subic Bay port locations present white space for cross-border liquid sulfur terminal infrastructure serving Luzon-based agrochemical producers.
ASEAN Sulfur Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct procurement tiers. State energy majors with integrated sour-gas infrastructure dominate direct sales channels through long-term offtake agreements and pipeline access. Independent distributors compete on certified storage capacity and compliance documentation. Strategic archetypes include sovereign-backed integrated producers, regional bulk handlers with hazardous substance certifications, and cross-border trading specialists. Competitive moves concentrate on backward integration into acid plant ownership and geographic expansion through port terminal partnerships.
Within the sovereign-integrated tier, Petronas and PT Pertamina (Persero) occupy positions exemplifying national downstream mandate execution. Among cross-border trading specialists, China Petroleum & Chemical Corporation represents the archetype of liquid sulfur shipment operations extending regional trading footprints through Thai and Vietnamese port terminals.
| Leading Market Players |
|---|
| Petronas |
| PT Pertamina (Persero) |
| Shell plc |
| Abu Dhabi National Oil Company |
| QatarEnergy |
| China Petroleum & Chemical Corporation (SINOPEC) |
| PETROVIETNAM CHEMICAL AND SERVICES CORPORATION (PVDMC) |
| PT Candi Ngrimbi |
| Qatar Petroleum for the Sale of Petroleum Products Company Limited |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Indonesian state-controlled sour-gas infrastructure compresses pricing tier spreads while forcing supply chain shape toward direct pipeline offtake and away from spot bulk trade. Indonesia's Ministry of Energy and Mineral Resources reservation quotas tether granular sulfur availability to PT Pertamina-linked chemical complexes, amplifying cost-plus contract premiums for independent Vietnamese distributors lacking captive acid plant access.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks dominate long-term offtake agreements between Claus-unit operators and integrated fertilizer producers. Price differentiation rests on volume scale and pipeline access certification, with direct-sales customers capturing standard-tier positioning while spot-dependent distributors absorb premium-mid-economy pricing differentiation. Pricing pressure stems from membrane-based sulfur recovery extensions collapsing capital barriers for mid-sized Indonesian acid plant operators. Mid-sized compound fertilizer blenders in Vietnam's Dong Thap province exhibit highest price sensitivity due to quarterly procurement cycles, whereas Petronas and PT Pertamina demonstrate lowest sensitivity through sovereign balance-sheet supported captive supply.
Supply Chain Analysis
Export-control restrictions on sulfur recovery technology licensing limit Claus-unit capacity expansion outside sovereign energy majors, concentrating geographic supply in Indonesia, Malaysia, and cross-border shipments from China. Raw material dependencies draw from sour natural gas processing, hydrogen sulfide feedstock contracts, and specialized insulated tankage for liquid sulfur handling. Supply chain risk centers on single-source vulnerability where Indonesia's state-controlled infrastructure directs majority domestic allocation toward PT Pertamina-linked complexes. Distribution runs through direct pipeline networks for integrated refineries, certified bulk terminals for regional distributors, and seaborne granular shipments for Mekong Delta fertilizer corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based sulfur recovery extensions are disrupting competitive economics by collapsing backward integration barriers for mid-sized acid plant operators. Indonesia's hardening quarterly compliance reporting mandates accelerate this inflection by embedding preferential pipeline access for domestic chemical manufacturers.
For Market Incumbents: Build captive pipeline infrastructure moats through dedicated offtake agreements with East Java agrochemical complexes. Expand certified storage capacity at Cai Mep and Gresik port terminals to lock out independent distributors facing Thailand's Department of Industrial Works hazardous substance certification timelines. Counter SINOPEC's cross-border liquid sulfur shipments by securing multi-year framework agreements with Vietnamese Ministry of Agriculture and Rural Development-regulated fertilizer blenders requiring minimum sulfur content thresholds. For New Entrants and Emerging Players: The Philippines' import-dependent fertilizer manufacturing base with limited sour-gas infrastructure represents the most penetrable entry point for cross-border liquid sulfur terminal development at Batangas or Subic Bay. Mid-sized rubber chemical processors in Thailand's Eastern Economic Corridor adopting digital inventory management systems offer second white-space target for just-in-time granular sulfur delivery models. Go-to-market angle: partner with provincial fertilizer cooperatives in Vietnam's Long An province for aggregated wholesale procurement bypassing consolidated distributor tier. For Investors and Strategic Acquirers: Indonesia's mandatory domestic sulfur reservation quotas reshapes the acquisition landscape toward integrated acid plant operators with captive Claus-unit access. Long-term viability over the next decade hinges on exposure to national downstream mandate enforcement and membrane technology adoption curves. Acquisition target archetype: mid-sized Indonesian fertilizer producers with backward integration into sulfur recovery extensions and preferential pipeline allocation under Ministry of Energy and Mineral Resources compliance frameworks. Signal to watch: quarterly reporting data on export contract supersession rates for integrated energy producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Plant Ownership | Captures margin pools at sulfuric acid conversion stage for Indonesian fertilizer producers adopting membrane extensions. |
| Long-term Supply Agreement | Locks in pipeline access for East Java agrochemical manufacturers under Indonesia's domestic reservation quotas. |
| Joint Venture | Enables cross-border liquid sulfur terminal infrastructure at Batangas serving Luzon-based agrochemical producers. |
| Capacity Expansion | Builds certified granular sulfur storage at Cai Mep port terminals for Vietnam's Mekong Delta fertilizer corridor. |
| Green Manufacturing Transition | Aligns Claus-unit optimization with membrane-based recovery extensions reducing import dependence for Indonesian producers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Claus-unit plant managers, fertilizer procurement leads at Vietnamese compound blender cooperatives, sulfur distribution channel partners with hazardous substance certifications, and technical R&D directors evaluating membrane recovery extensions. Secondary validation drew from Indonesian Ministry of Energy and Mineral Resources compliance filings, Vietnam customs trade data for granular sulfur imports, ASEAN fertilizer association reports, and SEC disclosures from integrated energy majors. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Calibration anchored volume and value outputs to historical trade flow patterns, regulatory mandate implementation timelines, and technology adoption curves for modular sulfur recovery systems. Segmentation dimensions modeled include product form, end-use industry concentration, application stage, and distribution channel structure. CAGRs were derived from regression analysis against agricultural intensification policy targets and refinery integration mandates. Industry-specific forecast inputs incorporated phosphate fertilizer capacity expansion announcements and sour-gas processing infrastructure development pipelines.
Practitioners should monitor regulatory enforcement intensity, membrane technology licensing availability, and natural gas price volatility for early signals of forecast deviation. Forecasts reflect assumptions about downstream mandate continuity and cross-border trade flow stability. Material shifts in Indonesia's domestic sulfur allocation quotas or Chinese phosphate processing sulfuric acid intensity reductions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Europe Castor Oil Market