
 Coal Tar Pitch Market | 2026-2036
Coal Tar Pitch Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Tar Pitch Market Intelligence
Bio-based binder alternatives are expanding their addressable niche in anode formulations, yet coal tar pitch retains cost dominance across high-volume aluminum electrolysis. Koppers Inc. leverages its integrated tar distillation network across North America and Europe to sustain supply security for smelter customers. Rain Carbon Inc. anchors its position through backward integration into refinery feedstocks, while Himadri Speciality Chemical Ltd dominates Indian domestic supply with captive coal tar refining capacity.
Coal tar pitch is a complex aromatic hydrocarbon residue from high-temperature coal tar distillation, with softening points typically ranging from 35°C to 180°C depending on grade and intended use; it functions primarily as a binder matrix in carbon electrodes and refractory linings. Needle pitch commands premium positioning in ultra-high-power graphite electrode production where low coefficient of thermal expansion is essential. Thermal pitch occupies the volume base in aluminum smelting anodes, while blown pitch variants serve lower-specification foundry and construction applications where cost sensitivity overrides performance thresholds.
EPA emissions standards in the United States and REACH registration requirements in Europe constrain tar distillation capacity expansion and elevate compliance costs for cross-border pitch shipments. China's MEE enforces stricter volatile organic compound limits on coal chemical processing, reshaping export availability from the country's tar refiners. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate supply chain reconfiguration and qualify alternative binder sources before specification mandates tighten.
Market Dynamics
Aluminum smelter capacity expansion in India and the Middle East is pulling thermal pitch volumes upward while REACH carbon-border adjustments tighten European import specifications, creating divergent demand pressures across geographies.
Growth Catalysts
- Prebaked anode commissioning:Hindalco and Vedanta are commissioning new Indian smelters requiring binder pitch for anode production, pulling regional supply chains toward South Asia.
- Electrode grade specialization:Needle pitch specifications for ultra-high-power graphite electrodes are tightening quality premiums as electric arc furnace steelmaking expands.
- Refinery integration:Backward integration into refinery feedstocks is securing tar supply continuity for major pitch producers amid volatile coal chemical markets.
Market Restraints
- Feedstock concentration:Coking coal supply bottlenecks in Australia and Mongolia concentrate tar distillation feedstock risk among limited metallurgical coal sources.
- Emissions compliance costs:EPA emissions standards in the United States constrain greenfield tar distillation capacity and elevate capital requirements for facility upgrades.
- Bio-based substitution:Bio-pitch alternatives are capturing niche anode formulation trials as aluminum producers test carbon-neutral binder pathways.
Strategic Opportunities
- Middle East smelter buildout:Emirates Global Aluminium and Ma'aden expansion projects are creating dedicated pitch demand requiring new supply agreements.
- Carbon border arbitrage:EU Green Deal carbon-border adjustments are incentivizing low-carbon pitch certification for European aluminum import compliance.
- Refractory grade diversification:Blown pitch variants for foundry and construction binders offer volume stability outside electrode cyclicality.
Industry Challenges
- Tar distillation talent scarcity:Specialized process engineering expertise for high-temperature coal tar refining is concentrating among aging workforce cohorts in Germany and Japan.
- Cross-border qualification timelines:REACH registration requirements for pitch importers extend certification cycles to 18-24 months, delaying market entry for new suppliers.
- Legacy anode integration:Soderberg anode conversions to prebaked systems require pitch specification recalibration, complicating technical service demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Tar Pitch Market |
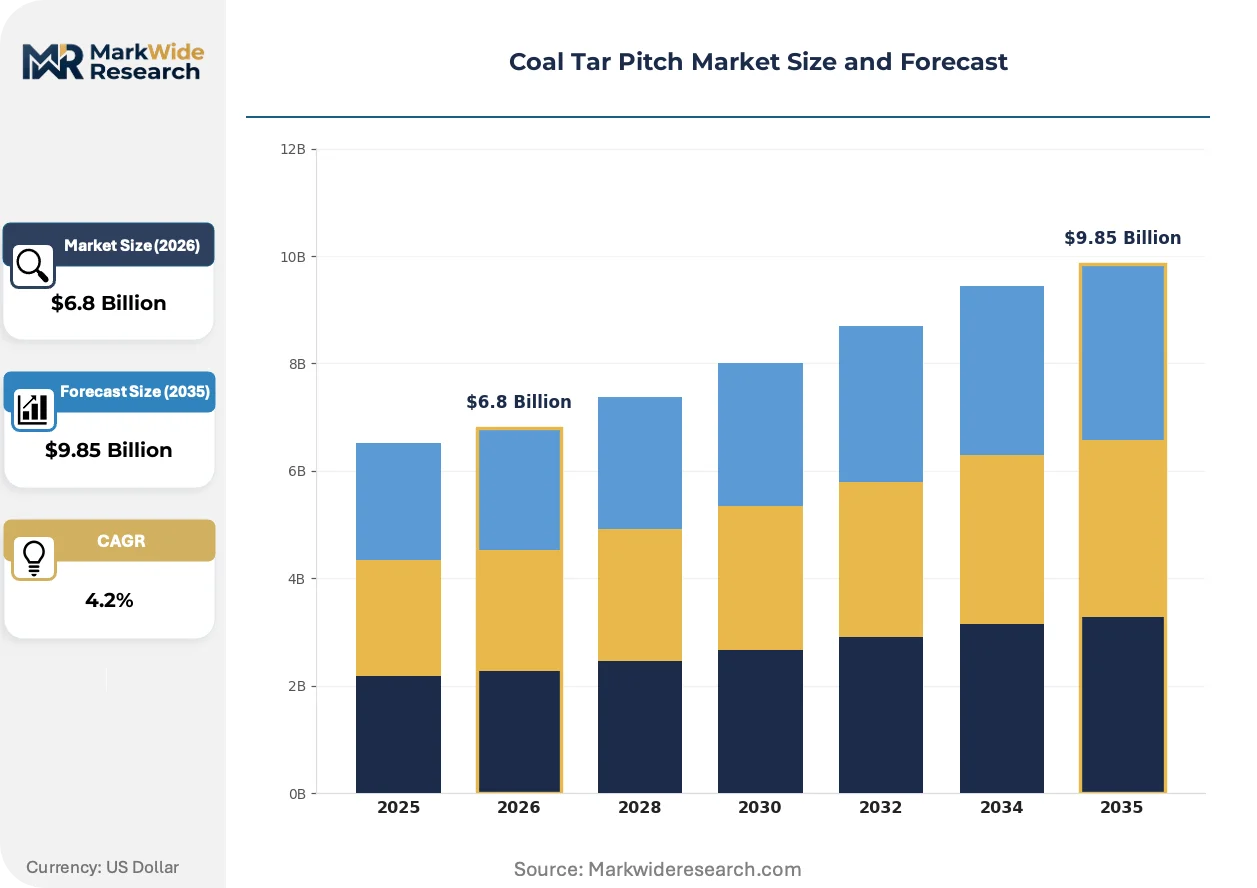
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Pitch, Airblown Pitch, Thermal Pitch, Blown Pitch Application: Carbon Anode Manufacturing, Aluminum Smelting, Foundry, Refractory Materials Form: Solid, Liquid, Semi-solid, Powder End User Industry: Metallurgical Plants, Chemical Manufacturers, Construction Sectors, Electrical Components Producers |
| Companies Covered | Mitsubishi Chemical Corporation, DEZA a.s., Rain Carbon Inc., Jining Carbon Group Co. Ltd., Bilbaína de Alquitranes S.A., Koppers Inc., JFE Chemical Corporation, Epsilon Carbon Private Limited, Himadri Speciality Chemical Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Tar Pitch Market Strategic Shifts & Innovations
Bio-based binder development, regulatory carbon accounting, and smelter procurement consolidation are restructuring how pitch suppliers qualify volumes and capture long-term offtake agreements.
Needle coke precursor pitch is overtaking standard binder formulations in premium electrode applications. Graphite electrode manufacturers in Japan and South Korea are adopting low-thermal-expansion pitch at accelerated qualification cycles. This specification compression is overtaking volume-based procurement in ultra-high-power segments.
REACH registration deadlines are forcing tar distillers to submit full substance dossiers for pitch UVCB substances. European importers face documentation gaps from Chinese refiners lacking standard toxicity datasets. German and Dutch customs authorities are rejecting shipments lacking compliant safety data sheets, redirecting trade flows toward qualified Indian suppliers.
Long-term offtake contracting is displacing spot purchasing among major aluminum smelters. Hindalco and Vedanta are locking three-to-five-year supply agreements with fixed volume commitments and quality bands. This contracting pattern concentrates supplier relationships in India while marginalizing traders without distillation assets.
Coal Tar Pitch Market Segmentation
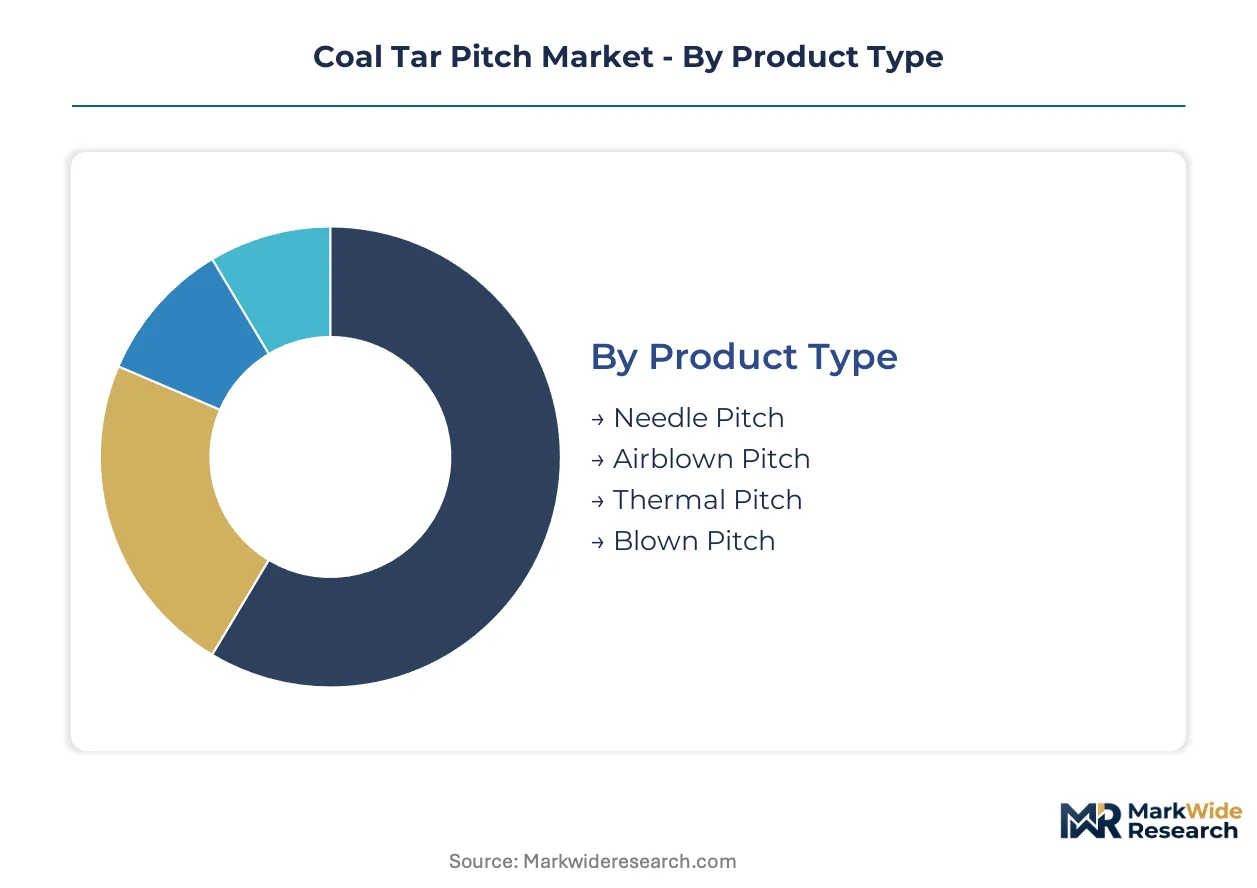
Segmentation in coal tar pitch tracks how specification tiers align with capital deployment in carbon electrode manufacturing. Distillation complexity and end-use performance thresholds create divergent margin profiles across product grades.
Product Type:
Needle pitch demands the heaviest capital outlay for high-temperature distillation units and precision filtration systems required to achieve ultra-low thermal expansion specifications.
- Needle Pitch:Premium aromatic hydrocarbon fraction with highly oriented crystalline structure enabling ultra-low coefficient of thermal expansion. Japanese and South Korean graphite electrode manufacturers concentrate procurement here as electric arc furnace steelmaking scales. Quality premiums widen with each tightening specification cycle.
- Thermal Pitch:Standard-distillation binder matrix serving high-volume aluminum electrolysis with softening points calibrated to prebaked anode forming requirements. Indian smelter buildouts by Hindalco and Vedanta pull disproportionate volumes toward this grade.
- Airblown Pitch:Oxidized variant produced by controlled air injection during distillation, yielding higher softening points for specialized refractory applications.
- Blown Pitch:Lower-specification binder for foundry and construction uses where cost sensitivity overrides performance thresholds.
Most installed capacity flows through Thermal Pitch. Expansion is steepest in Needle Pitch.
Application:
Carbon anode manufacturing anchors volume throughput while aluminum smelting commands the tightest specification compliance for electrolytic performance.
- Carbon Anode Manufacturing:Binder matrix integration for prebaked anode production requiring precise softening point control and low impurity thresholds. Middle East smelter projects by Emirates Global Aluminium and Ma'aden are redirecting supply chain focus toward this application.
- Aluminum Smelting:Direct electrolytic consumption in Hall-Héroult cells where pitch-derived anodes serve as both conductor and carbon source. Soderberg-to-prebaked conversions in Eastern Europe are recalibrating technical service requirements.
- Foundry:Mold and core binding in ferrous and non-ferrous casting operations.
- Refractory Materials:High-temperature lining binders for steelmaking vessels and cement kilns.
Carbon Anode Manufacturing captures the largest share of distillation output. Aluminum Smelting is climbing the fastest as capacity migrates to low-cost power geographies.
Form:
Liquid handling infrastructure dominates working capital allocation, though solidification and packaging equipment adds downstream capital intensity for distant shipments.
- Solid:Cooled and flaked pitch for stable long-distance transport and extended storage, preferred by European importers facing REACH documentation requirements.
- Liquid:Molten bulk delivery via heated tankers to adjacent smelter operations, minimizing reprocessing energy but requiring dedicated logistics assets.
- Semi-solid:Intermediate consistency for specialized blending operations.
- Powder:Micronized form for precision refractory and carbon composite formulations.
Solid form handles the greatest tonnage for intercontinental trade. Liquid form is gaining share fastest where smelter-distillery proximity permits.
End User Industry:
Metallurgical plants concentrate the most sophisticated technical service relationships, with specification negotiation occurring at individual smelter level rather than through distributors.
- Metallurgical Plants:Integrated aluminum and steel production facilities specifying binder pitch for captive anode and electrode manufacturing. Indian primary aluminum producers are consolidating procurement through three-to-five-year offtake agreements.
- Chemical Manufacturers:Carbon black and specialty chemical producers utilizing pitch fractions as feedstock or binder inputs.
- Construction Sectors:Roofing waterproofing and pavement sealant applications utilizing lower-grade blown pitch variants.
- Electrical Components Producers:Carbon brush and commutator manufacturers requiring controlled electrical resistivity in binder matrices.
Metallurgical Plants absorb the dominant share of high-specification output. Chemical Manufacturers are expanding most quickly as carbon material diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East smelter corridor stretching from Jebel Ali to Ras Al-Khair anchors near-term thermal pitch demand as Emirates Global Aluminium and Ma'aden commission capacity requiring dedicated binder supply agreements.
India
Hindalco and Vedanta are commissioning new smelters in Odisha and Chhattisgarh, pulling disproportionate thermal pitch volumes toward domestic supply chains. The Bureau of Indian Standards enforces tighter softening point specifications for prebaked anode binders under revised BIS 7167 protocols. The Korba-Raipur industrial belt concentrates captive coal tar refining capacity where Himadri Speciality Chemical Ltd operates integrated distillation complexes.
United States
EPA emissions standards constrain greenfield tar distillation capacity expansion while electric arc furnace steelmaking pulls needle pitch demand upward. The Environmental Protection Agency enforces Maximum Achievable Control Technology limits on volatile organic compound releases from coal chemical processing. The Pittsburgh-Gary corridor hosts Koppers Inc. distillation assets serving regional electrode manufacturers with integrated tar supply networks.
China
MEE enforcement of stricter VOC limits on coal chemical processing is reshaping export availability from Shandong and Shanxi tar refiners. The Ministry of Ecology and Environment mandates closed-loop emission controls and real-time monitoring for high-temperature distillation units. The Yangtze River Delta clustering around Shanghai and Ningbo concentrates needle coke precursor production where Jining Carbon Group processes specialized pitch fractions.
Germany
REACH registration deadlines for pitch UVCB substances are extending certification cycles for importers while carbon-border adjustments tighten specification compliance. The European Chemicals Agency requires full substance dossiers including standard toxicity datasets for cross-border shipments. The Ruhr industrial region maintains legacy tar distillation expertise where aging workforce cohorts concentrate specialized high-temperature refining knowledge.
Saudi Arabia
Ma'aden expansion at Ras Al-Khair is creating dedicated pitch demand requiring new long-term supply agreements with fixed volume commitments. The Saudi Food and Drug Authority and national environmental regulator enforce import documentation standards aligned with EU REACH protocols for metallurgical chemical shipments. The Jubail industrial city anchors carbon anode manufacturing clusters serving regional aluminum electrolysis capacity.
Coal Tar Pitch Market Key Industry Players
Global majors compete with regional champions across tar distillation capacity and smelter proximity. The vendor base separates into integrated refinery operators, captive coal tar processors, and specialized needle pitch refiners. Three archetypes dominate: backward-integrated energy companies securing feedstock continuity, regional champions exploiting domestic metallurgical coal access, and premium-grade specialists serving ultra-high-power electrode specifications. Competitive moves concentrate on long-term offtake contracting and distillation asset acquisitions.
Within the integrated refinery tier, Rain Carbon Inc. and Koppers Inc. exemplify upstream control strategies, while Himadri Speciality Chemical Ltd occupies a position as the dominant Indian domestic supplier. Mitsubishi Chemical Corporation and JFE Chemical Corporation represent Japanese precision-distillation capabilities for premium needle coke applications. DEZA a.s. anchors European supply security through Czech-based tar processing infrastructure.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| DEZA a.s. |
| Rain Carbon Inc. |
| Jining Carbon Group Co. Ltd. |
| Bilbaína de Alquitranes S.A. |
| Koppers Inc. |
| JFE Chemical Corporation |
| Epsilon Carbon Private Limited |
| Himadri Speciality Chemical Ltd |
| Others |
Cost & Logistics Intelligence
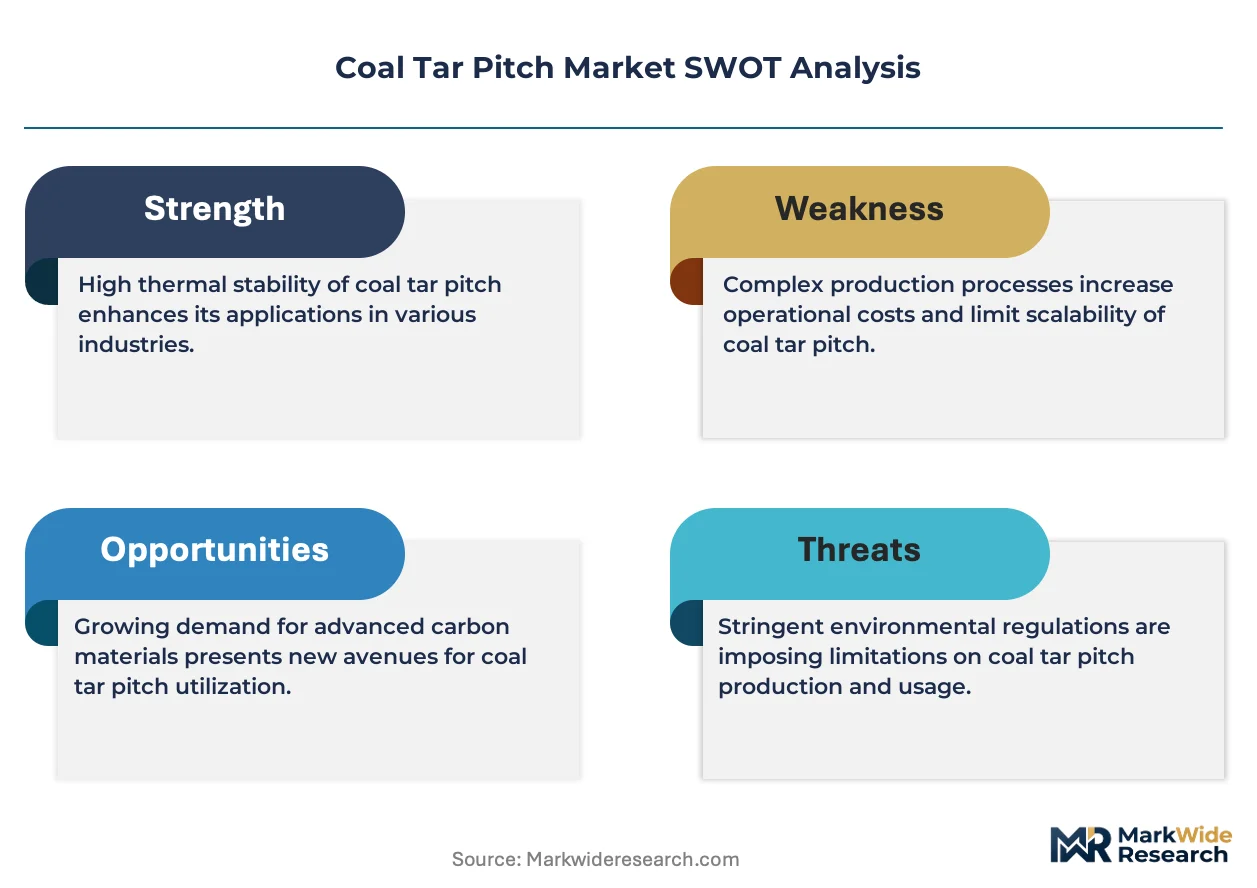
Needle pitch versus thermal pitch grade bifurcation creates divergent margin architectures that reshape both procurement economics and logistics configurations across the coal tar pitch value chain. Premium needle coke precursor commands qualification-heavy supply relationships with Japanese electrode manufacturers, while commodity thermal pitch flows through volume-optimized channels serving Indian aluminum smelters.
Pricing Analysis
Input-cost pass-through from metallurgical coal tar feedstock dominates pricing formation, with Australian coking coal volatility transmitting directly to distillation margins. Three-tier pricing structure across needle, thermal, and blown grades reflects distillation complexity and end-use performance thresholds. Cost compression in thermal pitch is intensifying because Hindalco and Vedanta are consolidating procurement through multi-year offtake agreements. Foundry-grade blown pitch buyers exhibit highest price sensitivity, while ultra-high-power graphite electrode producers accept premium positioning for low-thermal-expansion specifications.
Supply Chain Analysis
Direct-to-smelter molten delivery channels handle hyperscale aluminum producer demand in India and the Middle East, minimizing reprocessing energy but requiring dedicated heated tanker assets. Geographic supply concentrates in China, India, and the United States, with Shandong tar refiners, Himadri's Korba-Raipur complexes, and Koppers' Pittsburgh-Gary corridor anchoring regional availability. Feedstock dependencies rest on Australian and Mongolian metallurgical coal, coking coal byproduct tar, and refinery stream integration. Single-source vulnerability concentrates in needle pitch distillation expertise, where aging German and Japanese engineering cohorts limit capacity expansion. Distribution runs through long-term contract structures displacing spot trade among major aluminum electrolysis operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coal tar pitch market functions as a stable compounder anchored by irreplaceable binder demand in primary aluminum electrolysis, where prebaked anode specifications create sustained volume commitments across decade-long smelter operating horizons.
For Market Incumbents: Anchor distillation capacity in tar-proximate geographies to secure feedstock continuity as Australian coking coal bottlenecks intensify. Prioritize REACH dossier completion for European market access before carbon-border adjustments tighten. Backward integration into refinery feedstocks defends margin position against volatile coal chemical markets. Invest in needle pitch filtration assets to capture quality premiums from expanding electric arc furnace steelmaking. For New Entrants and Emerging Players: The premium-to-economy price-point gap in needle pitch versus blown pitch applications offers entry traction for specialized refiners targeting refractory-grade diversification. Target Middle East smelter buildouts at Ras Al-Khair and Ma'aden expansion zones where dedicated supply agreements remain uncommitted. Pursue bio-pitch formulation partnerships with aluminum producers testing carbon-neutral binder pathways as a qualification-fast-track strategy. For Investors and Strategic Acquirers: Consolidation pressure builds where aging workforce expertise in high-temperature tar distillation concentrates among limited German and Japanese engineering cohorts. Five-to-ten year viability favors integrated operators with captive coal tar refining and smelter-proximate logistics assets. Target acquisition archetype: mid-scale Indian or Czech distillation facilities with BIS or REACH compliance infrastructure. Monitor bio-based binder trial outcomes at Hindalco and Vedanta as inflection signal for substitution risk timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Feedstocks | Rain Carbon secures tar supply continuity independent of volatile coal chemical spot markets. |
| Long-term Supply Agreement | Hindalco locks three-to-five-year thermal pitch volumes with fixed quality bands and volume commitments. |
| REACH Registration Completion | Indian suppliers redirect trade flows from rejected Chinese shipments toward qualified European entry. |
| Needle Pitch Filtration Capacity Addition | Japanese electrode manufacturers accelerate qualification cycles for low-thermal-expansion precursor supply. |
| Bio-pitch Formulation Partnership | Aluminum producers test carbon-neutral binder pathways alongside conventional pitch for compliance positioning. |
Research Approach
Direct dialogue with tar distillation plant managers, aluminum smelter procurement leads, graphite electrode technical directors, and REACH regulatory consultants grounded qualitative insights in operational reality. Secondary validation drew from EPA emissions filings, ECHA substance dossiers, BIS standard protocols, SEC 10-K disclosures from listed chemical operators, and customs trade flow data. Bottom-up capacity assessments and top-down end-use demand modeling were triangulated against primary interview findings.
Bottom-up segment modeling tracked needle pitch, thermal pitch, and blown pitch grades across carbon anode manufacturing, aluminum smelting, and refractory applications throughout the projection horizon. Geographic clustering analyzed India, China, the United States, Germany, and Saudi Arabia as distinct regulatory and demand environments. CAGRs were derived from volume-demand elasticity models calibrated to smelter capacity commissioning timelines and electrode grade specification evolution. Forecast inputs incorporated REACH registration deadlines, MEE VOC enforcement trajectories, and BIS protocol revisions.
Caveats apply where bio-based substitution acceleration, coking coal supply disruptions, or carbon-border adjustment stringency could materially shift the outlook. Forecasts embed assumptions regarding smelter buildout pacing and distillation capacity regulatory clearance that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Alunite Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Ammonium Molybdate Market