
 Nanofibrillar Cellulose Market | 2026-2036
Nanofibrillar Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Nanofibrillar Cellulose Market Intelligence
Pharmaceutical-grade purity specifications is collapsing the gap between commodity cellulose and high-value nanofibrillar outputs. CelluForce leverages its Quebec-based demonstration plant to sustain consistent nano-crystalline yields for industrial buyers. Borregaard anchors Scandinavian supply through its Sarpsborg biorefinery, while Stora Enso competes across packaging and construction segments with integrated forest-product chains.
Nanofibrillar cellulose consists of liberated cellulose microfibrils with diameters below 100 nanometers, typically produced through high-pressure homogenization or enzymatic pretreatment of wood pulp, yielding specific surface areas exceeding 100 square meters per gram for reinforcement and barrier applications. Wood-based grades dominate current volume due to established pulp infrastructure, though bacterial nanocellulose commands premium positioning in biomedical applications where endotoxin control determines market access. Composites and coatings applications are attracting accelerated formulation investment as automotive lightweighting mandates intensify, while paper segment margins compress amid mature demand patterns.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States establish divergent compliance pathways that fragment product certification costs across export markets. EPA toxicity testing protocols for nanoscale materials add further pre-market validation burdens for US-bound shipments. Stakeholders must monitor evolving ISO/TC 229 nanomaterial characterization standards, as harmonized metrology will determine which producers qualify for cross-border biomedical and food-contact supply chains.
Market Dynamics
Pharmaceutical-grade purity benchmarks are compressing the traditional gap between commodity cellulose and high-value nanofibrillar outputs, forcing producers to reconfigure purification trains and analytical protocols.
Growth Catalysts
- Automotive Lightweighting Mandates:CAFE standards in the United States and EU CO2 fleet targets are accelerating composite formulation trials with nanofibrillar cellulose for interior panels and structural reinforcements.
- REACH Registration Pathways:ECHA's evolving nanoform guidance is creating first-mover advantages for producers who complete dossier submissions ahead of 2025 compliance deadlines.
- Finnish-Swedish Pulp Integration:Existing kraft mill infrastructure in Scandinavia enables capital-efficient enzymatic pretreatment retrofits without greenfield construction.
Market Restraints
- High-Pressure Homogenization Energy Costs:Mechanical fibrillation consumes 2-5 MWh per tonne of dry nanocellulose, anchoring production economics to regional electricity tariffs.
- Scandinavian Supply Concentration:Over 60 percent of commercial capacity sits within 500 kilometers of the Baltic Sea, exposing buyers to single-region logistics disruptions.
- Bacterial Nanocellulose Substitution:Biomedical grades face competition from precision-fermentation bacterial cellulose where endotoxin specifications exceed wood-derived purification limits.
Strategic Opportunities
- Underpenetrated US Food-Contact Channel:FDA food-contact substance notification backlogs have delayed market entry, creating whitespace for first movers with completed toxicity dossiers.
- Construction Sector Barrier Films:Cementitious coating applications for moisture control represent an emerging volume sink outside traditional paper and packaging segments.
- EU Green Deal Biomaterial Mandates:Public procurement guidelines favoring bio-based construction materials are redirecting R&D budgets toward structural composite certification.
Industry Challenges
- ISO/TC 229 Metrology Gaps:Absence of harmonized nanomaterial characterization protocols forces redundant analytical spending across export destinations.
- Specialized Rheology Expertise Scarcity:Formulation chemists capable of tuning nanocellulose gel networks for industrial coating lines command premium compensation.
- Multi-Jurisdiction Certification Timelines:Parallel REACH, FDA, and EPA notification processes extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanofibrillar Cellulose Market |
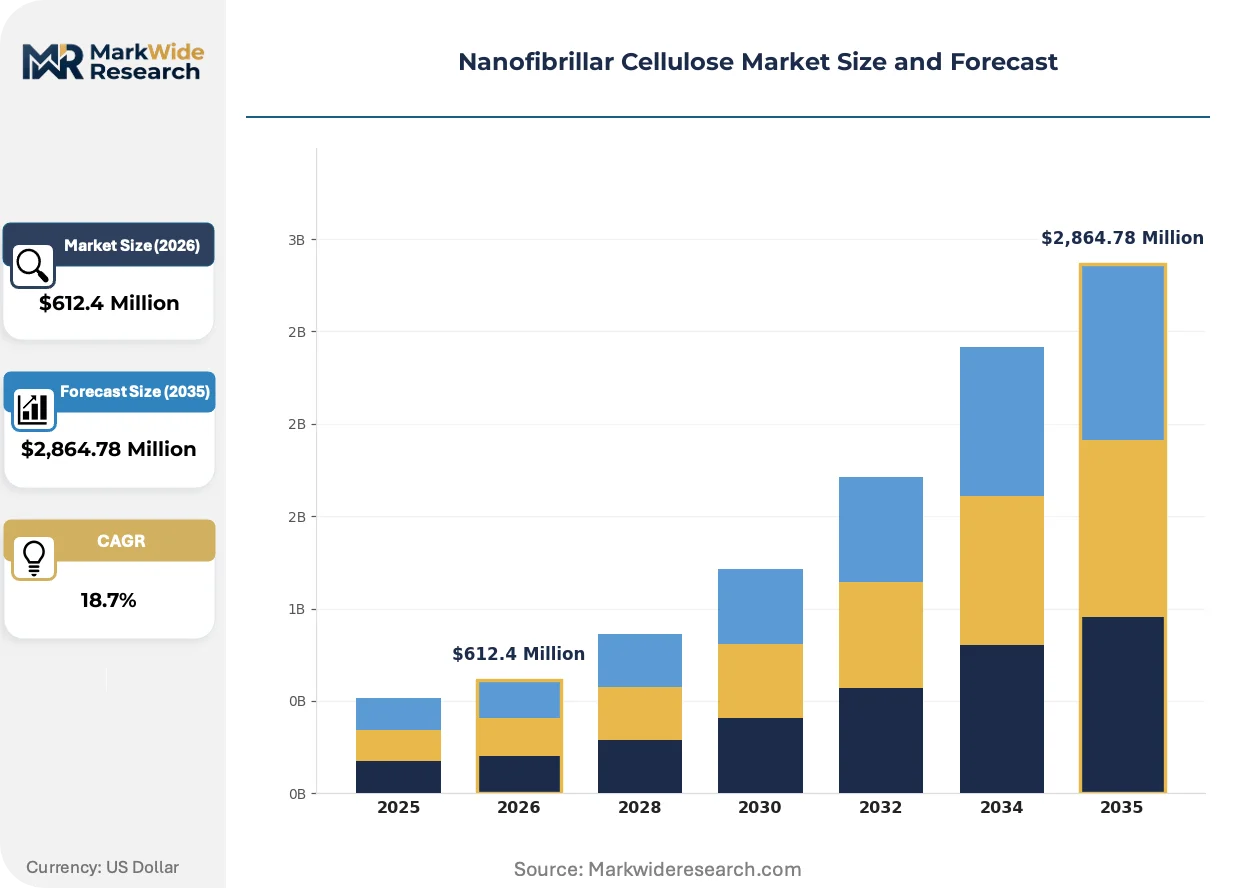
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood-Based, Cotton-Based, Bacterial, Others Application: Composites, Coatings, Paper, Biomedical End User: Automotive, Consumer Goods, Packaging, Construction Form: Dry Powder, Suspension, Gel, Sheet |
| Companies Covered | CelluForce, American Process, Nippon Paper Industries, Kruger, FiberLean Technologies, Borregaard, Stora Enso, Cellucomp, Sappi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanofibrillar Cellulose Market Strategic Shifts & Innovations
Production technology is splitting into divergent pathways optimized for either commodity volume or premium functional grades, with equipment choices locking producers into irreversible cost structures.
Enzymatic pretreatment is bifurcating the competitive landscape. Finland-based producers deploy cellulase cocktails to reduce homogenization energy by 40 percent, while North American entrants favor mechanical-only routes to avoid enzyme cost volatility. Automotive tier-one suppliers now specify enzymatic grades for Class A surface finishes, forcing mechanical-only producers toward bulk packaging applications with thinner margins.
EPA's TSCA Section 5(a) significant new use rules for nanoscale cellulose are tightening pre-manufacture notification requirements. Industrial buyers now demand completed toxicity profiles before pilot-scale trials, compressing the traditional sample-to-contract timeline. US-bound biomedical shipments face the steepest validation burdens, with EPA 90-day review cycles becoming standard procurement checkpoints.
Specification-driven purchasing is displacing relationship-based sourcing in composite formulation. Tier-one automotive and construction buyers now require ISO-compliant particle size distributions and surface charge metrics in every lot certificate. This shift concentrates procurement among producers with captive analytical laboratories, marginalizing smaller toll manufacturers in Germany and Japan who rely on third-party testing.
Nanofibrillar Cellulose Market Segmentation
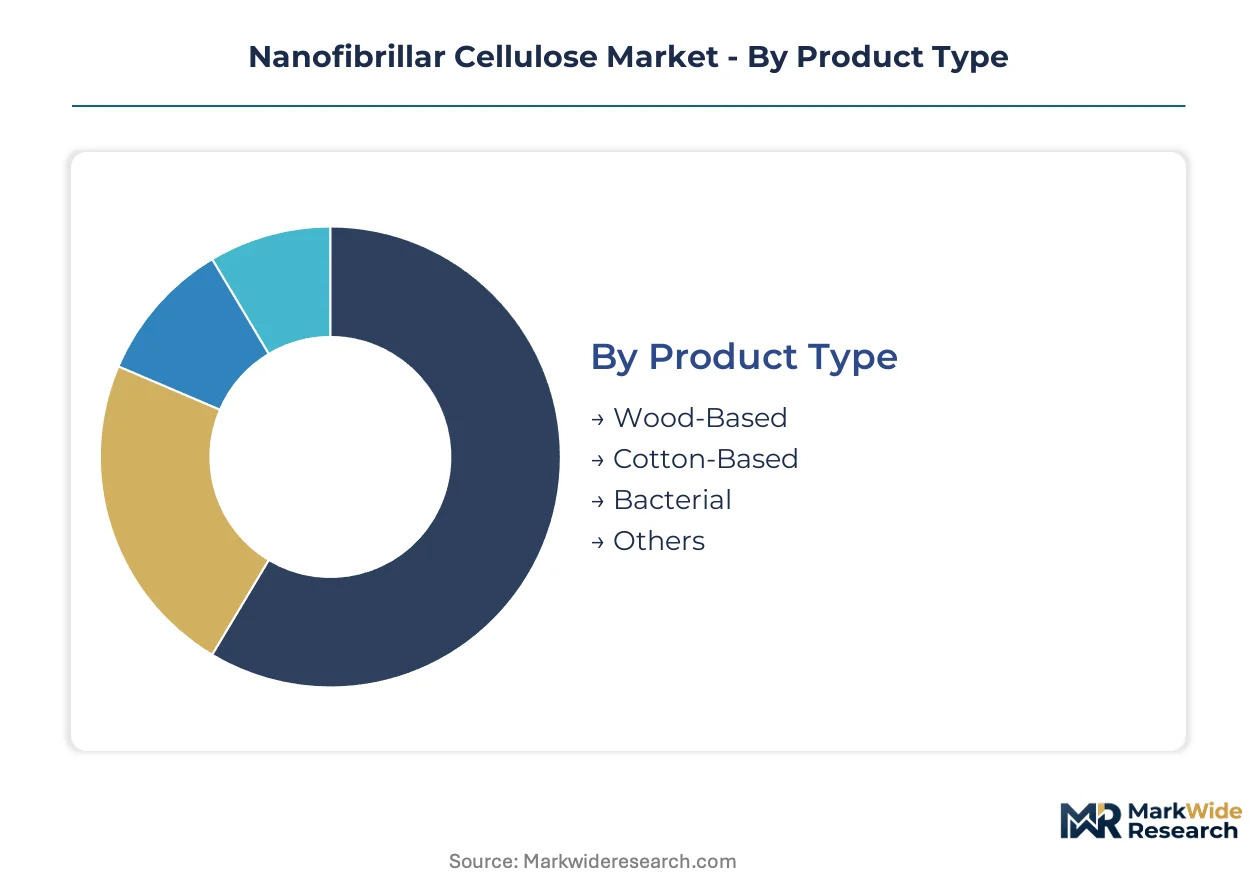
Segmentation in nanofibrillar cellulose reveals how production technology and end-use specifications fragment pricing power across otherwise similar material grades. Producers must choose between commodity scale and premium functional positioning, with each segment demanding distinct certification investments and supply chain configurations.
Product Type:
Wood-based grades face the most acute substitution pressure from bacterial nanocellulose in biomedical applications, where endotoxin specifications exceed mechanical purification limits.
- Wood-Based:Liberated cellulose microfibrils from kraft pulp deliver specific surface areas exceeding 100 square meters per gram. Demand concentrates in Finland and Sweden where enzymatic pretreatment retrofits at existing mills reduce homogenization energy by 40 percent.
- Bacterial:Precision-fermentation-derived cellulose achieves ultrahigh purity with controlled fibril alignment for wound dressings and implant scaffolds. Endotoxin control requirements in FDA-regulated biomedical channels command price multiples over wood-derived alternatives.
- Cotton-Based:Linters and textile waste streams provide alternative feedstock with lower lignin content, appealing to cosmetic and personal care formulators seeking non-wood origin claims.
- Others:Algal and agricultural residue sources remain pre-commercial, constrained by inconsistent fibril dimensions and scale-up economics.
Wood-based grades anchor the volume base while bacterial nanocellulose gains share at the steepest rate.
Application:
Margin structures diverge sharply across applications, with coatings commanding formulation premiums and paper segment margins compressing amid mature demand patterns.
- Composites:Automotive lightweighting mandates from NHTSA CAFE standards and EU CO2 fleet targets drive Class A surface finish specifications. Tier-one suppliers now require enzymatic grades with ISO-compliant particle size distributions in every lot certificate.
- Coatings:Cementitious barrier films for moisture control in construction represent an emerging volume sink outside traditional packaging segments. Rheology tuning for industrial coating lines demands scarce formulation expertise.
- Paper:Reinforcement applications in packaging and specialty grades face thinning margins as mature demand patterns limit pricing power.
- Biomedical:Wound care, drug delivery matrices, and tissue engineering scaffolds require pharmaceutical-grade purity that collapses the gap between commodity cellulose and high-value outputs.
Composites and coatings concentrate procurement growth while biomedical applications deliver the highest unit margins.
End User:
Customer type determines certification burden intensity, with automotive and biomedical buyers imposing the steepest validation protocols.
- Automotive:Interior panels and structural reinforcements require lot-consistent rheology for automated composite molding lines. EPA TSCA Section 5(a) notification requirements compress sample-to-contract timelines.
- Packaging:Barrier films and lightweight structural components scale adoption as EU Green Deal biomaterial mandates redirect public procurement toward bio-based construction materials.
- Construction:Cementitious coating applications for moisture control attract accelerated formulation investment outside traditional paper segments.
- Consumer Goods:Cosmetic and personal care applications favor cotton-based and bacterial grades for non-wood origin positioning.
Packaging anchors current volume while automotive procurement expands most quickly under regulatory lightweighting pressure.
Form:
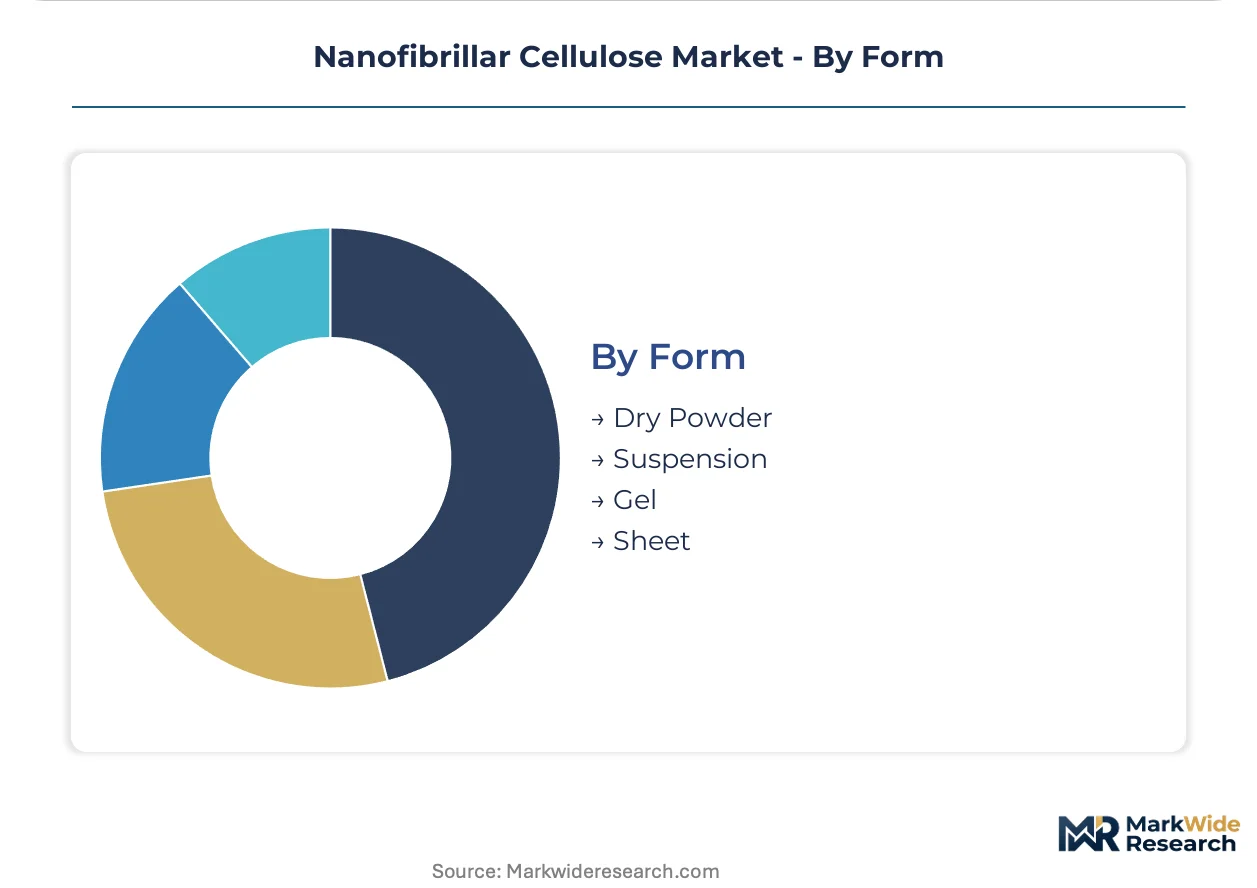
Physical form dictates logistics economics and formulation flexibility, with suspensions dominating industrial scale and gels capturing premium functional positioning.
- Suspension:Aqueous dispersions at 2-10 percent solids enable pumpable delivery to coating and composite lines. Scandinavian producers leverage Baltic Sea logistics for bulk shipment to European formulators.
- Gel:Higher concentration networks suit biomedical and cosmetic applications requiring precise rheology control without redispersion steps.
- Dry Powder:Spray-dried grades reduce transport costs for distant buyers but require redispersion equipment and expertise that marginalizes smaller toll manufacturers.
- Sheet:Cast films and membranes serve niche biomedical and filtration applications with limited current volume.
Suspensions dominate industrial procurement while gel formats climb the fastest in biomedical and cosmetic channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and Swedish buyers absorb premium pricing for pharmaceutical-grade nanofibrillar cellulose with minimal elasticity, while US packaging converters remain acutely sensitive to energy-cost pass-throughs from Scandinavian supply chains.
Finland
Enzymatic pretreatment retrofits at existing kraft mills slash homogenization energy by 40 percent, anchoring cost-competitive supply for barrier film manufacturers. EU Green Deal biomaterial procurement guidelines redirect public construction budgets toward certified nanocellulose composites. The Äänekoski bioproduct mill cluster integrates nanofibrillar output with pulp logistics, enabling Baltic Sea bulk shipment to German automotive tier-ones.
Sweden
Stora Enso's integrated forest-product chains dominate packaging and construction segment supply, leveraging captive pulp streams for consistent nano-crystalline yields. REACH nanoform dossier submissions ahead of 2025 deadlines create first-mover certification advantages for Swedish producers. The Sundsvall timber processing corridor concentrates enzymatic capacity within 300 kilometers of Borregaard's Sarpsborg biorefinery across the Norwegian border.
United States
Automotive lightweighting mandates under NHTSA CAFE standards accelerate composite formulation trials for interior panels, though FDA food-contact substance notification backlogs delay packaging market entry. EPA TSCA Section 5(a) significant new use rules impose 90-day pre-manufacture review cycles that compress sample-to-contract timelines. Wisconsin and Minnesota pulp belts attract enzymatic retrofit investment to reduce electricity dependence from mechanical-only routes.
Canada
CelluForce's Quebec demonstration plant sustains consistent nano-crystalline yields for industrial buyers seeking North American sourcing alternatives to Baltic supply. Health Canada's evolving nanomaterial guidance under the Canadian Environmental Protection Act parallels EPA toxicity testing protocols, creating dual-notification burdens for biomedical shipments. The Saguenay-Lac-Saint-Jean forestry region hosts pilot-scale capacity with hydropower cost advantages over US mechanical producers.
Japan
Nippon Paper Industries anchors Asia-Pacific supply through integrated pulp-to-nanocellulose conversion at existing mill infrastructure. METI's carbon neutrality roadmap prioritizes bio-based material substitution in automotive and electronics packaging, redirecting R&D budgets toward composite certification. The Kushiro pulp cluster on Hokkaido exploits cold-water enzymatic efficiency gains unavailable to tropical climate competitors.
Nanofibrillar Cellulose Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with enzymatic-pretreatment specialists commanding premium positioning while mechanical-only producers compete on volume scale. The market structure concentrates around Scandinavian integrated forest-product corporations and North American demonstration-plant operators, with Japanese pulp conglomerates anchoring Asia-Pacific supply. Three archetypes dominate: enzymatic-pretreatment integrated mills, mechanical-fibrillation toll manufacturers, and precision-fermentation bacterial cellulose specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves, as producers seek to lock in automotive and biomedical offtake ahead of regulatory certification deadlines.
Among Scandinavian integrated producers, Borregaard and Stora Enso exemplify the enzymatic-pretreatment archetype, leveraging captive pulp streams and Baltic logistics to serve European automotive and construction demand. CelluForce occupies a position as the North American demonstration-plant anchor, representing the capital-efficient retrofit model for industrial buyers seeking supply chain diversification. These three companies illustrate how geographic proximity to pulp infrastructure and regulatory early-mover status combine to determine competitive positioning.
| Leading Market Players |
|---|
| CelluForce |
| American Process |
| Nippon Paper Industries |
| Kruger |
| FiberLean Technologies |
| Borregaard |
| Stora Enso |
| Cellucomp |
| Sappi |
| Others |
Cost & Logistics Intelligence
REACH nanoform dossier requirements gate both supply qualification and price differentiation simultaneously, forcing producers to absorb certification costs upfront while biomedical buyers pay minimal elasticity premiums for validated grades. Scandinavian enzymatic producers capture margin advantages through energy-efficient retrofits, while mechanical-only competitors face cost pass-through vulnerability to regional electricity tariffs.
Pricing Analysis
After-sales technical service and formulation support contracts drive lifetime value for nanofibrillar cellulose suppliers, with automotive tier-ones bundling rheology tuning into multi-year offtake agreements. Pricing stratifies across pharmaceutical-grade, food-contact, and industrial commodity tiers, with FDA notification completion separating premium biomedical positioning from standard packaging grades. Cost compression in wood-based commodity volumes is intensifying because mechanical-only producers cannot match enzymatic energy savings. Packaging converters in the United States show the highest price sensitivity to Baltic logistics costs, while biomedical device manufacturers in Germany and Japan accept steep premiums for bacterial nanocellulose with validated endotoxin profiles.
Supply Chain Analysis
Baltic Sea port congestion and container availability constraints on the Rotterdam-Hamburg trade lane expose buyers to extended lead times for Scandinavian-sourced material. Supply concentrates in Finland, Sweden, and Norway, with over sixty percent of commercial capacity sitting within five hundred kilometers of the Baltic coast. Production draws from kraft pulp feedstock, cellulase enzyme inputs, and high-pressure homogenization equipment. Single-region logistics vulnerability represents the dominant structural risk, with winter ice conditions and labor disruptions capable of severing European automotive supply lines. Distribution runs through bulk aqueous suspension shipments to coating and composite formulators, supplemented by smaller gel and dry powder parcels for biomedical and cosmetic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanofibrillar cellulose market sits in early-stage cyclical recovery, with automotive lightweighting mandates and EU Green Deal biomaterial procurement driving demand normalization after years of pilot-scale stagnation.
For Market Incumbents: Shield margin position by deepening captive pulp integration at Finnish and Swedish mill clusters, locking in enzymatic cost advantages that mechanical-only competitors cannot replicate. Accelerate REACH nanoform dossier submissions ahead of compliance deadlines to freeze out late entrants from European biomedical supply chains. Prioritize analytical laboratory investments to meet ISO-compliant particle size certification requirements that tier-one automotive buyers now mandate in every lot certificate.
For New Entrants and Emerging Players: Toll manufacturing capacity scarcity in North America and Asia-Pacific offers white-space entry for capital-efficient retrofit operators. Target the underpenetrated United States food-contact channel, where FDA notification backlogs have delayed incumbent market entry and created procurement whitespace for completed toxicity dossiers. Pursue joint development agreements with Wisconsin and Minnesota pulp belt operators to secure hydropower-cost-advantaged feedstock without greenfield construction exposure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed enzymatic-pretreatment specialists in Scandinavia and demonstration-plant operators in Quebec. Five-to-ten year viability hinges on regulatory early-mover status consolidation and automotive offtake locking ahead of certification deadline clustering. Watch EPA TSCA Section 5(a) notification completion rates as the inflection signal—producers with cleared toxicity profiles will command procurement preference as industrial buyers abandon pilot-scale sampling for qualified supply contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Pretreatment Retrofit | Finnish kraft mills slash homogenization energy by forty percent, anchoring cost leadership against mechanical-only competitors. |
| REACH Nanoform Dossier Submission | First-mover certification advantages lock European biomedical and food-contact supply chains ahead of compliance deadlines. |
| Captive Analytical Laboratory Investment | In-house ISO-compliant particle size verification meets tier-one automotive lot certificate requirements, marginalizing toll manufacturers. |
| North American Demonstration Plant Scale-Up | Quebec and Wisconsin capacity addresses FDA notification backlogs, capturing whitespace in underpenetrated food-contact packaging. |
| Bacterial Nanocellulose Precision-Fermentation Buildout | Endotoxin-controlled production serves wound dressing and implant scaffold demand where wood-derived purification limits fail. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nanocellulose plant managers, automotive tier-one procurement leads, biomedical device regulatory affairs directors, and coating formulation chemists. Secondary validation drew from ECHA REACH registration databases, FDA food-contact substance notification filings, EPA TSCA Section 5(a) pre-manufacture notices, and ISO/TC 229 nanomaterial characterization standards. Bottom-up capacity modeling and top-down demand triangulation were cross-referenced against customs trade data and integrated forest-product corporation SEC disclosures.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, application, end user, and physical form dimensions. CAGRs were derived from production capacity buildout schedules, regulatory approval timeline assumptions, and automotive lightweighting content-per-vehicle penetration curves. Forecast inputs incorporated enzymatic energy efficiency gains, Baltic logistics cost indices, and biomedical grade purity premium elasticity estimates.
Forecasts assume regulatory continuity in REACH, FDA, and EPA regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include ISO/TC 229 metrology standard delays, bacterial nanocellulose substitution acceleration in biomedical channels, and Scandinavian logistics disruption severity. Practitioners should keep alternative scenarios live as automotive electrification content mix and EU Green Deal procurement enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Boron Nitride Market