
 United Kingdom Methanol Market | 2026-2036
United Kingdom Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Methanol Market Insights
The UK Emissions Trading Scheme is hardening the cost-of-entry calculus for methanol producers reliant on natural gas reforming. Methanex Corporation leverages its global shipping logistics to sustain supply continuity into UK terminals. Associated British Ports anchors import volume through its Humber and Thames storage facilities. Ørsted competes with renewable hydrogen-linked methanol pathways, positioning its electrolyzer projects near Danish-connected offshore wind zones.
Methanol is a light, volatile alcohol (CH₃OH) produced industrially via steam methane reforming or coal gasification, with specifications typically requiring purity above 99.85% for chemical synthesis and lower grades for fuel applications. Its primary commercial purpose centers on formaldehyde precursor manufacture and increasingly on marine fuel blending under IMO 2020 sulfur caps. Bulk Methanol dominates volume flows through UK ports, while Fuel Grade Methanol represents the fastest-expanding category as shipping operators retrofit vessels for methanol dual-fuel engines. Chemical Grade Methanol sustains margin pools among pharmaceutical and acetic acid manufacturers who require ISO-certified purity tiers.
The Health and Safety Executive enforces COMAH regulations for methanol storage thresholds above 10,000 tonnes, while the Environment Agency monitors aqueous discharge from reforming facilities under integrated pollution prevention and control permits. The UK REACH framework shapes product standards for methanol purity and labeling, directly affecting market access for non-UK suppliers. Stakeholders must monitor carbon border adjustment mechanism developments and hydrogen subsidy allocations to determine whether biomethanol or e-methanol routes achieve cost parity with fossil-derived supply.
Market Dynamics
The UK Emissions Trading Scheme is compressing margins for natural gas-reformed methanol while simultaneously accelerating capital flows toward electrolyzer-linked e-methanol pathways. This carbon pricing mechanism is restructuring feedstock economics across the Humber industrial cluster.
Growth Catalysts
- IMO 2020 Marine Sulfur Caps:Shipping operators at Immingham and Grimsby are retrofitting dual-fuel engines to accept methanol blends, creating sustained offtake demand for fuel-grade product.
- UK Hydrogen Subsidy Allocation:Government funding for electrolyzer projects near North Sea offshore wind zones is enabling renewable hydrogen feedstock for e-methanol pilot plants.
- Methanol-to-Olefins Integration:Petrochemical facilities in the Humber cluster are co-locating methanol cracking units with existing ethylene infrastructure, reducing logistics costs for derivative production.
Market Restraints
- Natural Gas Price Volatility:Steam methane reforming economics remain tethered to North Sea and continental gas benchmarks, exposing producers to input cost swings.
- Import Concentration Risk:Over 80% of UK methanol supply arrives through Rotterdam and Antwerp transit, creating chokepoint vulnerability during Channel logistics disruptions.
- Biomethanol Feedstock Scarcity:Agricultural residue and municipal waste streams suitable for gasification remain underdeveloped at commercial scale within British supply chains.
Strategic Opportunities
- Scottish Carbon Capture Cluster:Acorn and Net Zero Teesside projects offer geological storage for reforming emissions, potentially qualifying blue methanol for EU carbon border adjustment exemptions.
- Thames Estuary Bunkering Hub:Port of London Authority infrastructure investments could establish a secondary marine fueling point independent of Humber concentration.
- Pharmaceutical Grade Premium:Acetic acid and solvent applications for UK-based drug manufacturers command purity premiums above commodity fuel-grade pricing tiers.
Industry Challenges
- COMAH Compliance Complexity:Health and Safety Executive thresholds above 10,000 tonnes trigger major hazard site classification, extending permitting timelines for new storage investments.
- Electrolyzer Engineering Talent Gap:Specialist skills for solid oxide and PEM stack integration with methanol synthesis loops remain concentrated in Danish and German labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Methanol Market |
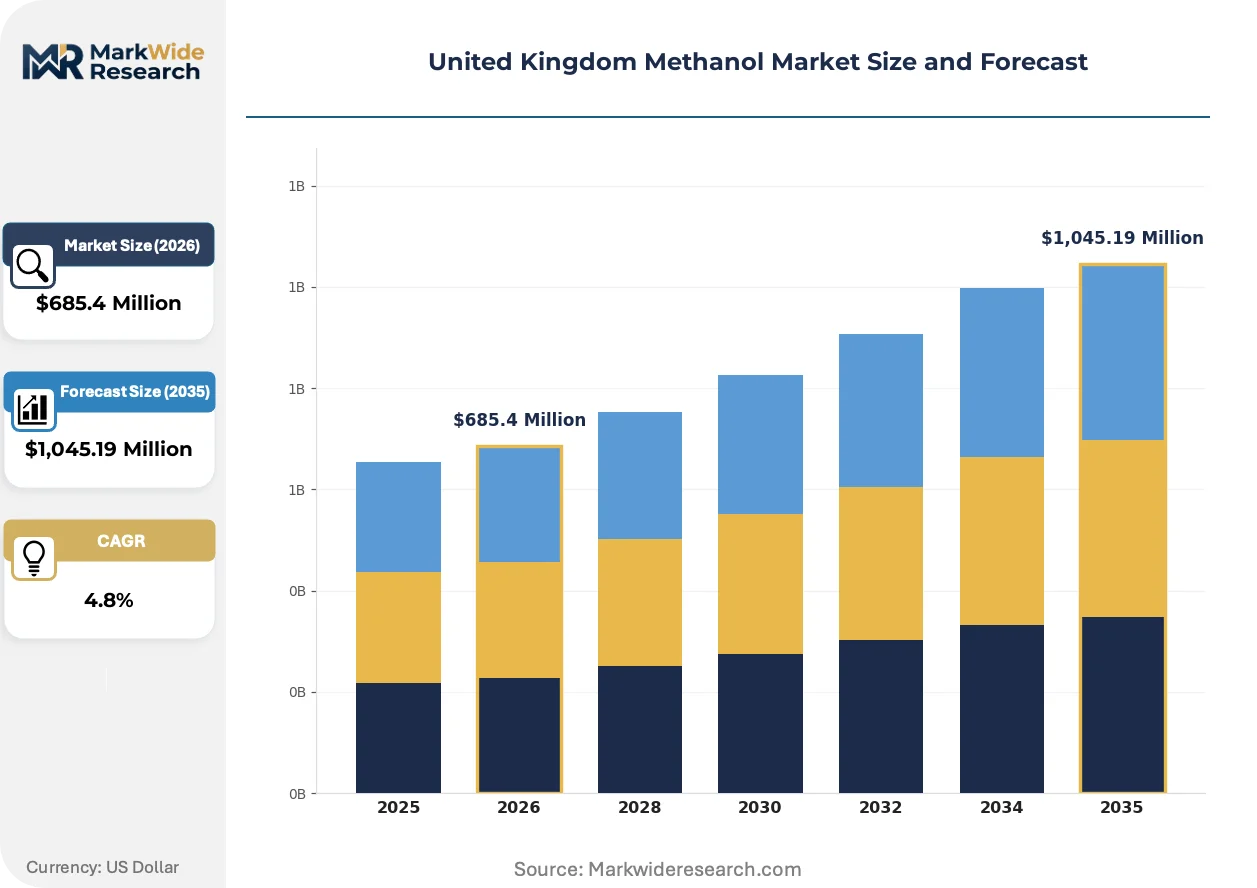
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Methanol, Denatured Methanol, Industrial Methanol, Fuel Grade Methanol, Chemical Grade Methanol Application: Fuel Additives, Formaldehyde Production, Acetic Acid Manufacture, Solvent Usage, Biodiesel Production, Antifreeze Agents End User: Chemical Manufacturers, Fuel Suppliers, Paint Producers, Pharmaceutical Companies, Agriculture Producers, Printing Firms Distribution Channel: Direct Sales, Wholesale Distributors, Online Platforms, Industrial Supply Stores, Exporters |
| Companies Covered | CIMC Enric, China National Petroleum Corporation, Methanex Corporation, Gazprom, Saudi Aramco, Exolum, Associated British Ports, Mitsubishi Gas Chemical, Ørsted, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Methanol Market Trends and Innovations
Electrolyzer scale-up and marine engine retrofits are converging to restructure methanol demand composition. Technology vendors and port authorities are aligning capital deployment around dual-fuel infrastructure.
Automated blending systems for marine fuel terminals are automating quality control and batch documentation. Associated British Ports is deploying these systems at Immingham to handle variable methanol-biodiesel ratios. The technology is automating compliance verification for IMO fuel certification while compressing berth turnaround times for methanol-fueled vessels.
UK REACH framework amendments are tightening substance registration requirements for imported methanol. The Environment Agency is cross-referencing purity declarations against actual discharge monitoring data. Chemical-grade importers face expanded testing obligations for pharmaceutical and electronics applications, prompting suppliers to seek third-party ISO 17025 certification.
Long-term offtake contracting is displacing spot market purchasing among shipping operators. Maersk and other container lines are securing five-to-ten-year supply agreements directly with methanol producers. This pattern concentrates volume commitments with Humber and Thames terminal operators while marginalizing traditional distributor intermediaries in the UK market.
United Kingdom Methanol Market Segmentation
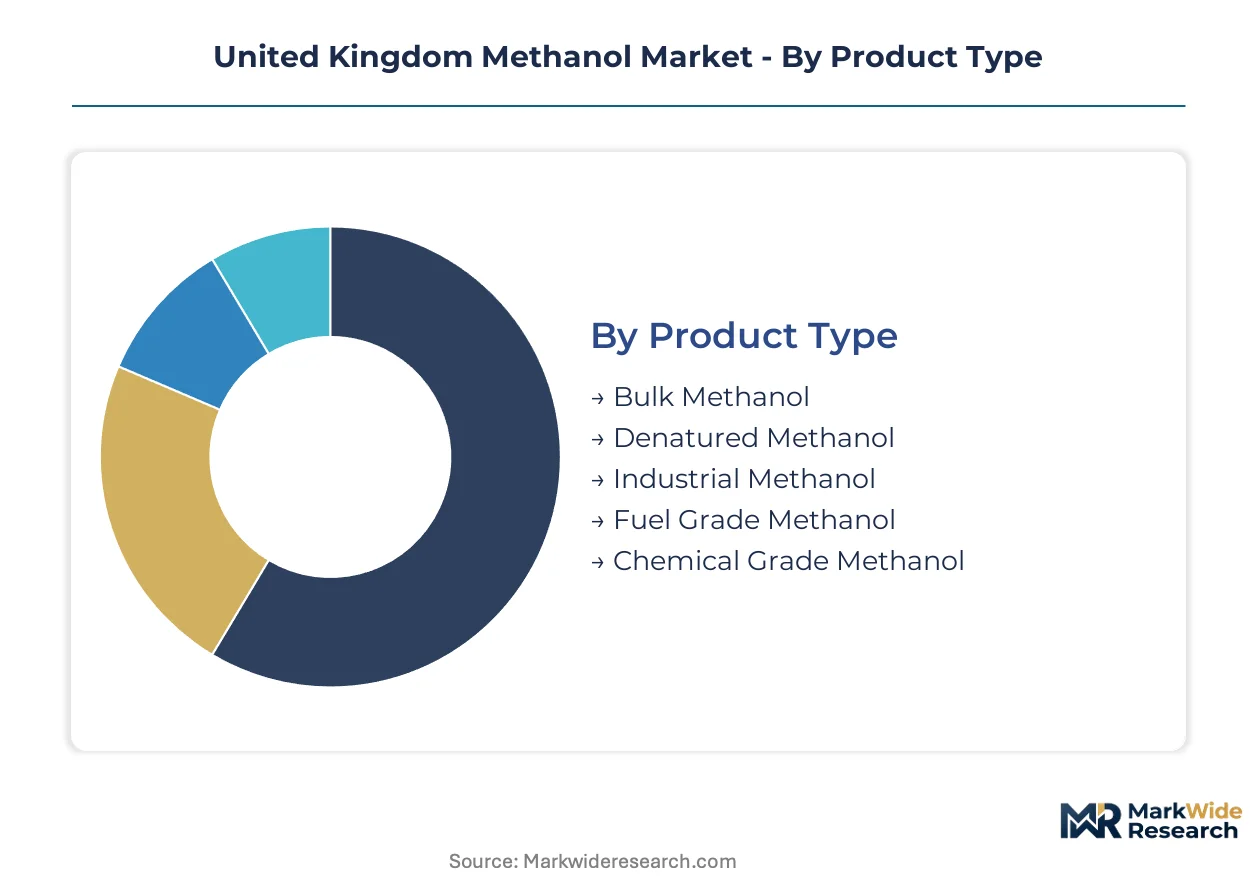
Methanol demand in the United Kingdom fragments across purity grades, end-use chemistry, and fuel specifications. Each segment carries distinct margin profiles and regulatory exposure under UK REACH and the Emissions Trading Scheme.
Product Type:
Bulk commodity flows dominate port throughput, while specialty grades capture premium pricing in regulated applications.
- Fuel Grade Methanol:Specifications accommodate marine and road fuel blending with sulfur content below IMO 2020 thresholds. Shipping operators at Immingham and Grimsby are retrofitting dual-fuel engines, pulling volume through Associated British Ports storage facilities as bunker demand accelerates.
- Chemical Grade Methanol:Purity exceeds 99.85% for pharmaceutical precursor and electronics solvent applications. Acetic acid manufacturers and drug formulators in the Humber cluster pay ISO-certified premiums above commodity benchmarks.
- Bulk Methanol:Standard industrial grade moves through Rotterdam-Antwerp transit corridors into Thames and Humber terminals.
- Denatured Methanol:Bitrex or methanol-blend additives render the product unfit for human consumption under HMRC excise regulations.
- Industrial Methanol:Intermediate purity tier serves general solvent and cleaning compound formulations.
Today's leader: Bulk Methanol. Tomorrow's challenger: Fuel Grade Methanol.
Application:
Demand concentrates in formaldehyde chemistry, with fuel additive applications climbing fastest on marine decarbonization mandates.
- Formaldehyde Production:Methanol oxidation yields formaldehyde for resin manufacture in construction and automotive supply chains. Humber-based petrochemical complexes consume the largest single share of UK chemical-grade supply.
- Fuel Additives:Marine bunkering and road fuel blending absorb lower-purity methanol under tightening sulfur caps. Port of London Authority infrastructure investments could establish a secondary marine fueling point independent of Humber concentration.
- Acetic Acid Manufacture:Carbonylation processes at chemical manufacturers convert methanol to acetic acid for polymer and coating applications.
- Solvent Usage:Paint producers and printing firms utilize methanol for ink formulation and surface preparation.
- Biodiesel Production:Transesterification catalyst applications in small-scale renewable fuel facilities.
- Antifreeze Agents:De-icing formulations for aviation and automotive sectors.
Formaldehyde Production commands current volume leadership; Fuel Additives are expanding most quickly on regulatory tailwinds.
End User:
Chemical manufacturers anchor procurement scale, while fuel suppliers are restructuring offtake patterns around long-term marine contracts.
- Chemical Manufacturers:Methanol-to-olefins crackers and formaldehyde producers in the Humber cluster negotiate term supply agreements with global traders.
- Fuel Suppliers:Bunker fuel blenders at Immingham and Thames terminals are securing five-to-ten-year offtake contracts directly with producers.
- Paint Producers:Solvent applications in industrial and decorative coatings.
- Pharmaceutical Companies:High-purity requirements for active pharmaceutical ingredient synthesis.
- Agriculture Producers:Pesticide formulation and silage preservation applications.
- Printing Firms:Ink solvent demand in packaging and publication sectors.
Chemical Manufacturers retain procurement dominance; Fuel Suppliers are gaining share fastest on marine engine retrofits.
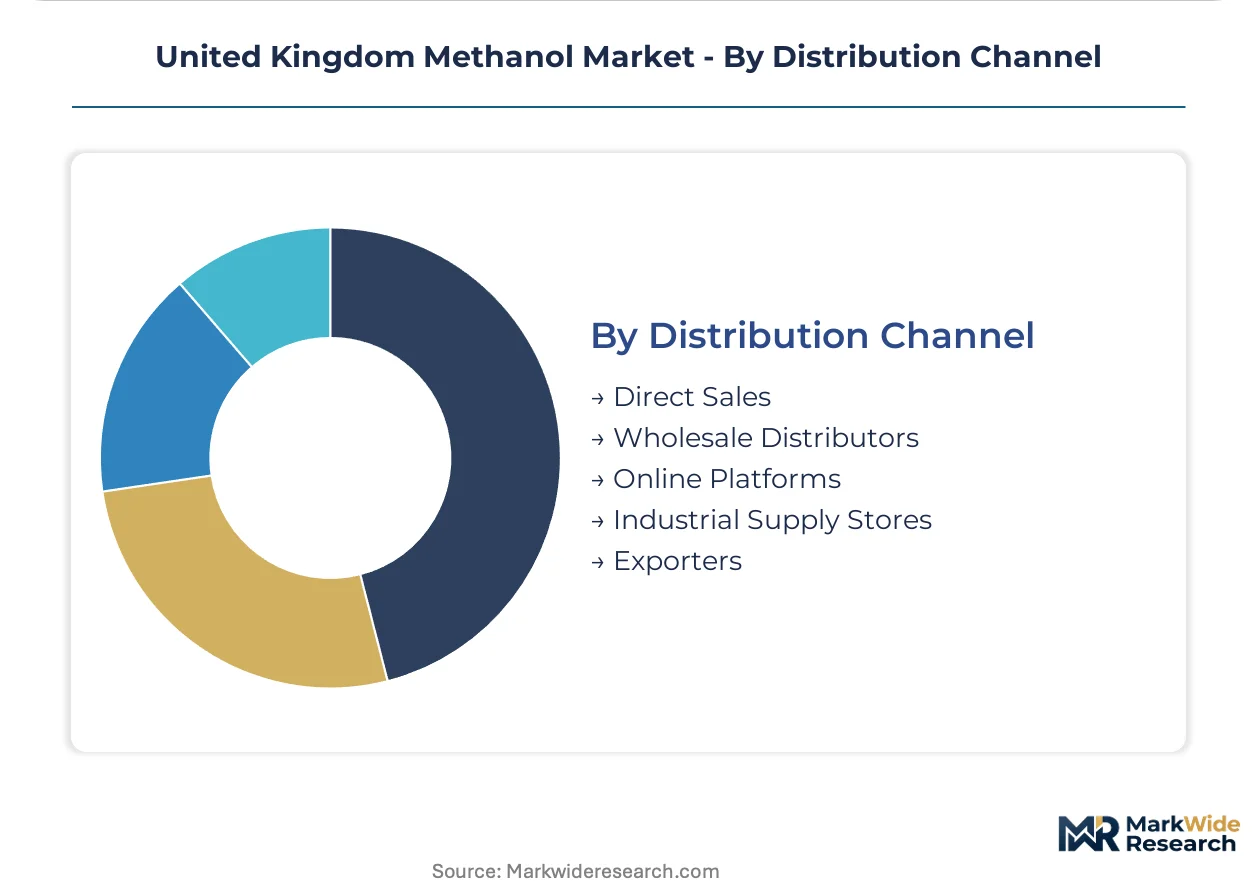
Distribution Channel:
Terminal-direct procurement is displacing traditional distributor intermediaries as shipping lines consolidate volume commitments.
- Direct Sales:Methanex Corporation and comparable global producers contract directly with Humber and Thames terminal operators, bypassing wholesale layers.
- Wholesale Distributors:Regional stockists serve smaller chemical manufacturers and paint producers with break-bulk deliveries.
- Online Platforms:Industrial chemical marketplaces facilitate spot purchasing for laboratory and small-batch users.
- Industrial Supply Stores:Local distribution for maintenance solvents and antifreeze products.
- Exporters:Re-export flows through UK ports to Irish and Nordic destinations.
Direct Sales channels command the largest volume flows; Online Platforms are climbing fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist engineering talent for electrolyzer-methanol integration clusters disproportionately around the Humber estuary and Thames corridor, anchoring the UK's position in low-carbon fuel pathways.
England
Formaldehyde manufacturers and methanol-to-olefins crackers in the Humber cluster consume the dominant share of chemical-grade supply. The UK Emissions Trading Scheme compresses margins for natural gas-reformed methanol while accelerating e-methanol pilot investments. Immingham and Grimsby terminals handle the bulk of import volume through Associated British Ports facilities.
Scotland
Acorn carbon capture and storage infrastructure offers geological sequestration for reforming emissions, potentially qualifying blue methanol for EU carbon border adjustment exemptions. The Scottish Government's hydrogen action plan channels subsidy toward electrolyzer projects in the northeast. Aberdeen's energy transition zone repurposes offshore engineering capabilities for e-methanol synthesis development.
Wales
Port Talbot's steel decarbonization discussions include methanol as a reductant alternative in blast furnace conversions. The Welsh Government's industrial strategy identifies low-carbon fuel production as a priority sector. Milford Haven's existing LNG infrastructure provides potential feedstock integration points for methanol synthesis.
Northern Ireland
Belfast Harbour's marine retrofit capabilities position the region for methanol bunkering services on Irish Sea routes. The Northern Ireland Executive's energy strategy references imported low-carbon fuels as a decarbonization lever. Limited indigenous chemical manufacturing constrains bulk methanol demand outside fuel applications.
London and Southeast
The Port of London Authority's Thames Estuary infrastructure investments could establish a secondary marine fueling hub independent of Humber concentration. Pharmaceutical manufacturers in the Southeast command ISO-certified purity premiums for active ingredient synthesis. Cross-Channel logistics connectivity maintains supply continuity through Rotterdam-Antwerp transit corridors.
United Kingdom Methanol Market Competitive Landscape
The competitive structure tilts toward integrated global traders with captive shipping logistics and terminal infrastructure. Market concentration reflects high barriers to entry in COMAH-regulated storage and the capital intensity of marine fuel supply chains. Two archetypes dominate: global methanol producers with dedicated vessel fleets, and port-terminal operators controlling import chokepoints. Capacity expansion and long-term offtake contracting constitute the primary competitive moves, with five-to-ten-year supply agreements displacing spot market purchasing among shipping operators.
Among global producers with UK terminal access, Methanex Corporation and Mitsubishi Gas Chemical exemplify the integrated trader archetype, leveraging captive logistics to sustain supply continuity into Humber and Thames facilities. Associated British Ports anchors the infrastructure-operator tier, controlling storage and blending capacity at Immingham and other key import points. These three entities represent the structural poles around which procurement patterns reorganize as marine fuel demand accelerates.
| Leading Market Players |
|---|
| CIMC Enric |
| China National Petroleum Corporation |
| Methanex Corporation |
| Gazprom |
| Saudi Aramco |
| Exolum |
| Associated British Ports |
| Mitsubishi Gas Chemical |
| Ørsted |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between fuel-grade and chemical-grade methanol manifests in divergent pricing architectures and procurement pathways across UK terminals. Fuel-grade product commands spot-market responsiveness at Immingham bunkering hubs, while ISO-certified chemical-grade supply chains tether to pharmaceutical manufacturers through audited distributor networks under UK REACH traceability mandates.
Pricing Analysis
Bundled terminal services—encompassing storage, blending, and IMO fuel certification—capture premium spreads against unbundled commodity procurement for chemical manufacturers. Pricing stratifies across pharmaceutical-grade ISO certifications, marine fuel sulfur compliance tiers, and standard industrial solvent specifications. Cost compression in natural gas-reformed methanol intensifies as UK Emissions Trading Scheme carbon costs accumulate, while fuel suppliers exhibit lowest price sensitivity due to long-term marine offtake contracts.
Supply Chain Analysis
Regional distribution centers at Rotterdam and Antwerp anchor hub-and-spoke patterns feeding Thames and Humber terminals. UK supply draws from Trinidad and Tobago, the Middle East, and Russian-origin flows subject to sanctions complexity. Steam methane reforming feedstock costs and electrolyzer engineering talent scarcity constitute structural vulnerabilities. Distribution runs through Associated British Ports storage facilities and Methanex Corporation captive vessel logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK methanol market functions as a regulatory compounder where UK Emissions Trading Scheme carbon pricing and IMO 2020 marine sulfur mandates continuously restructure feedstock economics and demand composition.
For Market Incumbents: Acquire carbon capture and storage assets at Acorn or Net Zero Teesside to qualify blue methanol for EU carbon border adjustment exemptions. Secure electrolyzer engineering talent through Danish and German specialist recruitment pipelines before Ørsted consolidates renewable hydrogen-linked methanol pathways. Capacity addition in Scottish offshore wind zones offers defensive positioning against natural gas price volatility. For New Entrants and Emerging Players: Enter via pharmaceutical-grade methanol purification services for Southeast England drug manufacturers requiring ISO 17025-certified supply chains. Target the Thames Estuary bunkering hub as Port of London Authority infrastructure investments establish secondary marine fueling capacity independent of Humber concentration. Partner with automated blending system vendors to bypass incumbent terminal relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where COMAH-regulated storage thresholds above 10,000 tonnes create permitting bottlenecks for new market entrants. Long-term viability hinges on e-methanol and biomethanol pathway cost parity achievement within the next decade. Monitor hydrogen subsidy allocation announcements as the primary inflection signal for electrolyzer-linked methanol project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Capture | Acorn CCS infrastructure qualifies blue methanol for EU carbon border adjustment exemptions. |
| Long-term Supply Agreement | Maersk and container lines secure five-to-ten-year offtake contracts displacing spot purchasing. |
| Green Manufacturing Transition | Electrolyzer projects near North Sea offshore wind zones enable renewable hydrogen feedstock. |
| Joint Venture | Ørsted partnerships with port authorities co-locate electrolyzer capacity with terminal infrastructure. |
| Capacity Expansion | Associated British Ports storage additions at Immingham handle accelerating methanol-biodiesel blending ratios. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each regional industrial cluster. The research combines interviews with Humber petrochemical plant managers, Thames terminal operators, pharmaceutical procurement leads, and marine fuel supply specialists with secondary validation from UK Environment Agency discharge permits, Health and Safety Executive COMAH registrations, and Associated British Ports throughput disclosures. Bottom-up volume modeling and top-down value triangulation cross-validate segment estimates.
Granularity extends to fuel-grade versus chemical-grade purity tiers, formaldehyde versus marine fuel additive applications, and direct sales versus wholesale distribution channels across the projection horizon. CAGRs derive from regression analysis against UK Emissions Trading Scheme carbon price trajectories and IMO marine fuel demand elasticity. Electrolyzer capacity buildout schedules and hydrogen subsidy allocation pathways inform e-methanol supply-side assumptions.
Inputs from UK regulatory filings and port authority infrastructure plans were available through the study window; gaps in proprietary offtake contract terms introduce uncertainty bands around marine fuel demand elasticity estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Dimethyldichlorosilane Market
Chemicals
Ferric Fluoride Market
Chemicals
Benzenoid Market
Chemicals
Pyrimidine Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Quaternium-15 Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
United States Construction Chemicals Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Deicing Fluid Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Triethylenediamine Market
Chemicals
Periodic Acid Market
Chemicals
Laboratory Chemicals Market
Chemicals
Diphosphate Market