
 Europe Bioplastics Market | 2026-2036
Europe Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bioplastics Market Foresight
European polymer distribution channels are reshaping as compounders and converters bypass traditional petrochemical distributors to secure direct bioplastic resin supply. BASF SE leverages its Ludwigshafen headquarters to anchor continental supply of certified compostable grades, while Novamont S.P.A. competes through its integrated Mater-Bi production complex in Terni, Italy. Total Corbion PLA dominates PLA resin availability through its Thai-European supply architecture, extending reach into thermoforming and fiber applications.
Bioplastics comprise polymeric materials derived wholly or partially from renewable biomass sources, with PLA requiring lactic acid fermentation from corn or sugar beet feedstock followed by ring-opening polymerization to achieve molecular weights exceeding 100,000 g/mol for durable applications. These materials serve industrial and commercial purposes primarily as drop-in replacements for conventional plastics in packaging and agriculture where end-of-life compostability delivers regulatory compliance. Biodegradable plastics lead European volume due to harmonized EN 13432 certification requirements across member states, while bio-based plastics capture margin concentration in automotive interior panels where OEMs specify renewable content thresholds. PLA material grades occupy the fastest-expanding position as polymerization efficiency improvements reduce unit conversion costs relative to PHA alternatives.
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate carbon intensity reductions and restrict persistent fluorinated compounds in food contact materials, compelling resin producers to obtain OK compost INDUSTRIAL and seedling certification for market access. ECHA substance evaluations further constrain additive packages in bio-based formulations, elevating formulation complexity for compounders serving medical and food packaging segments. Stakeholders must monitor pending revisions to the EU Packaging and Packaging Waste Regulation to calibrate capacity investments against mandated recycled and renewable content thresholds.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to redesign supply chains around certified compostable materials, creating procurement urgency across food contact applications while polymer distribution channels bypass traditional petrochemical distributors entirely.
Growth Catalysts
- EU Green Deal carbon intensity targets:Food packaging manufacturers accelerate procurement of PLA and starch-based films to comply with binding emissions reduction frameworks.
- EN 13432 harmonized certification:Biodegradable plastics capture volume leadership as cross-border standardization eliminates regulatory fragmentation across member states.
- Rhine-Ruhr chemical cluster concentration:Integrated production and R&D facilities in Germany enable rapid scale-up of certified compostable grades for continental supply.
Market Restraints
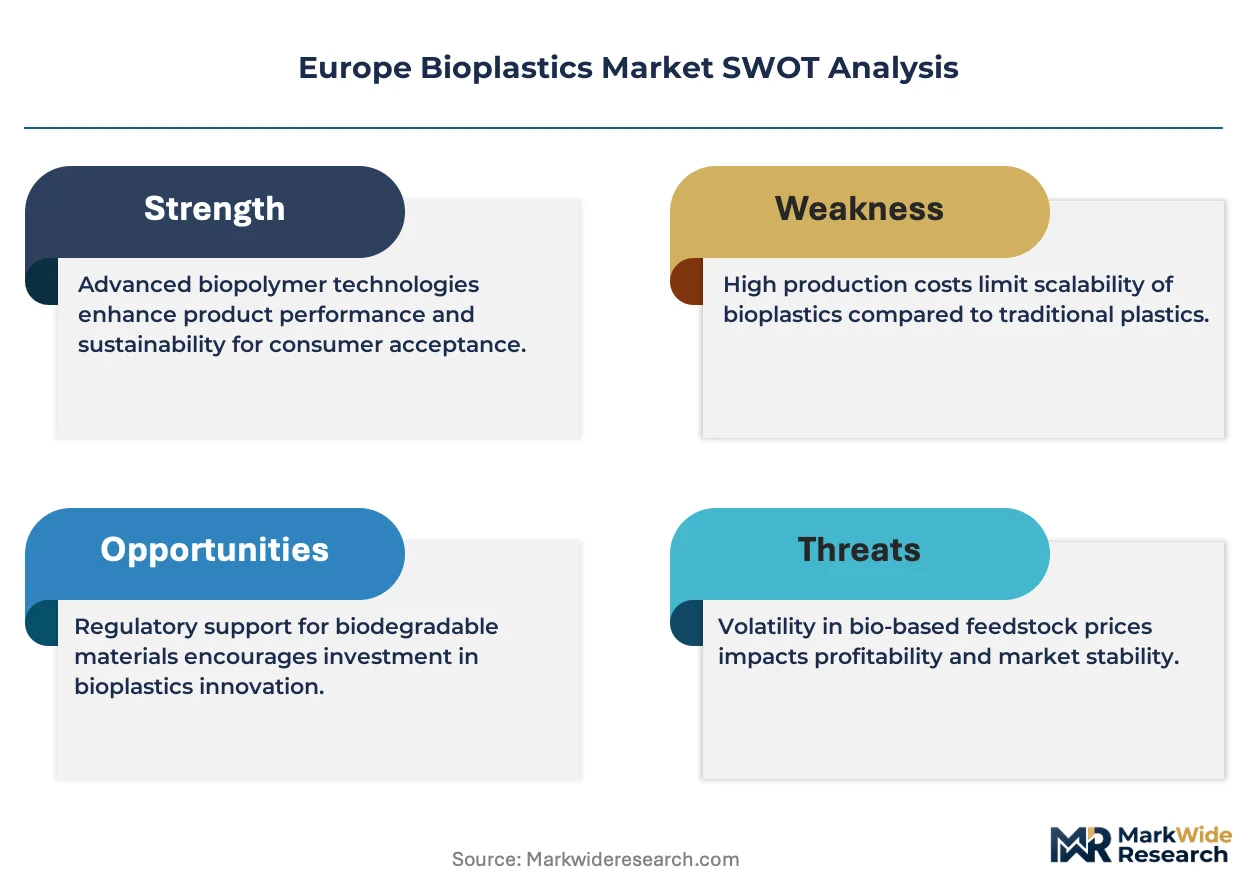
- Lactic acid feedstock cost volatility:Corn and sugar beet price swings compress margins for PLA producers dependent on agricultural commodity markets.
- Thai-European supply architecture dependency:Total Corbion PLA's dominant resin availability creates geographic concentration risk for thermoforming converters.
- REACH additive package constraints:ECHA substance evaluations limit formulation flexibility for compounders serving medical packaging segments.
Strategic Opportunities
- French agricultural film conversion:Underpenetrated mulch and silage wrap applications offer expansion paths for starch-based biodegradable grades.
- OK compost INDUSTRIAL certification:Regulatory tailwind from mandatory compostability labeling creates first-mover advantages for certified resin suppliers.
- Direct bioplastic resin channels:Compounders and converters establishing captive supply relationships bypass traditional petrochemical distributors entirely.
Industry Challenges
- Ring-opening polymerization technical talent:Scarce expertise in achieving molecular weights exceeding 100,000 g/mol constrains PLA durable application expansion.
- F-Gas Regulation compliance timeline:Persistent fluorinated compound restrictions in food contact materials demand rapid reformulation of barrier coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bioplastics Market |
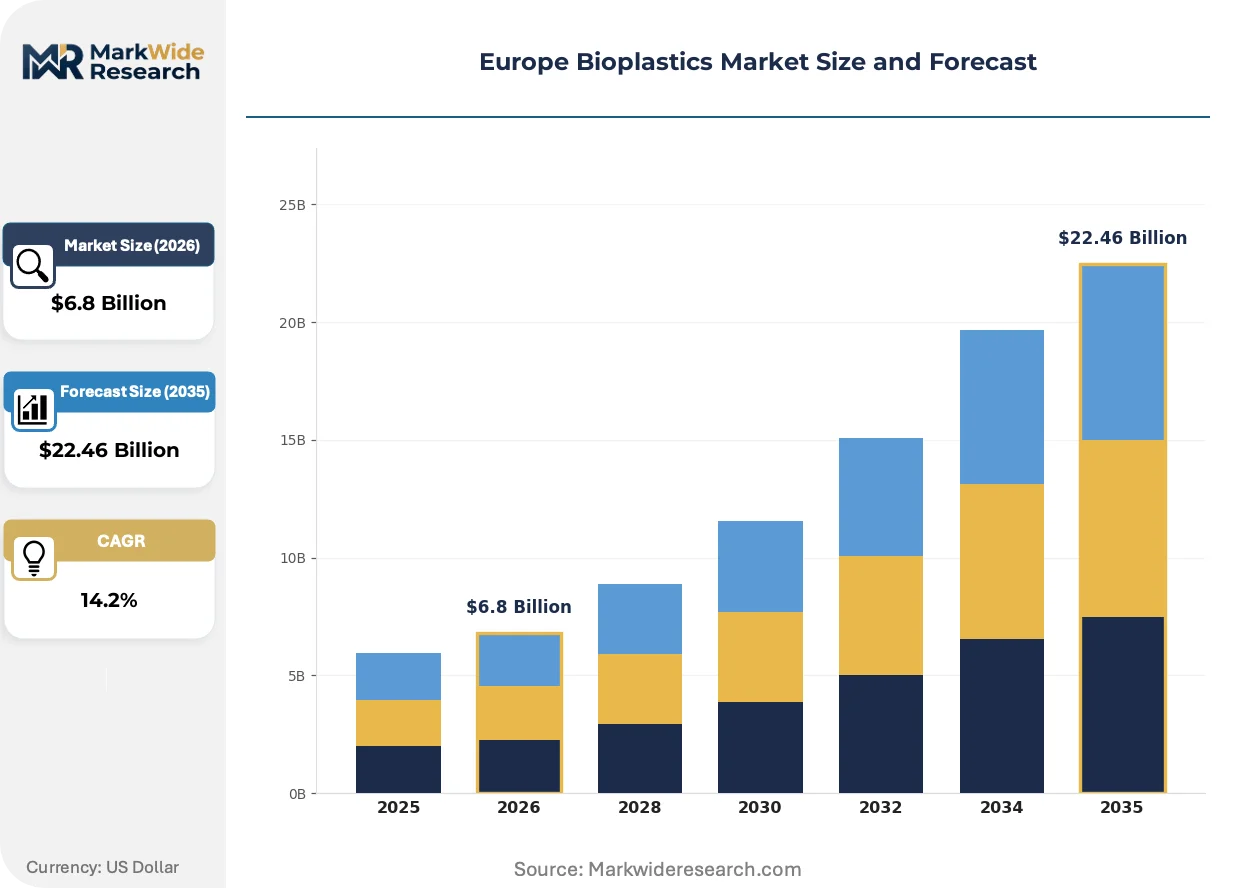
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Plastics, Bio-based Plastics, Composites, Blends End User: Agriculture, Packaging, Consumer Goods, Automotive Application: Food Packaging, Medical Applications, Agricultural Films, 3D Printing Material: PLA, PHA, Starch Blends, PBAT |
| Companies Covered | BASF SE, Novamont S.P.A., Total Corbion PLA, Avantium N.V., Carbios, Biome Bioplastics, Sabic, FKuR Kunststoff GmbH, Futerro, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bioplastics Market Shifts & Advancements
Active polymerization efficiency improvements and supply chain reconfiguration are compressing unit conversion costs while regulatory certification requirements reshape competitive positioning across European bioplastics.
PLA material grades are migrating from packaging-only applications toward durable automotive interior panels and fiber applications as polymerization efficiency improvements reduce unit conversion costs relative to PHA alternatives. Thermoforming converters in Italy and Germany adopt these expanded grades at accelerating pace. The technology is migrating from commodity film markets into engineered performance segments previously dominated by petroleum-derived engineering polymers.
EU F-Gas Regulation restrictions on persistent fluorinated compounds in food contact materials are compelling resin producers to obtain OK compost INDUSTRIAL and seedling certification for market access. Industrial consequence includes elevated formulation complexity for barrier coatings and additive packages. Medical and food packaging segments across Germany and France respond by consolidating procurement around pre-certified compounders with established ECHA compliance documentation.
Food packaging manufacturers now specify renewable content thresholds in supplier contracts rather than accepting conventional petroleum-derived alternatives. Direct resin procurement from integrated producers displaces traditional distributor relationships. This specification-driven preference shift is most visible across German retail private-label supply chains where converters face mandatory disclosure of biobased content percentages.
Europe Bioplastics Market Segmentation
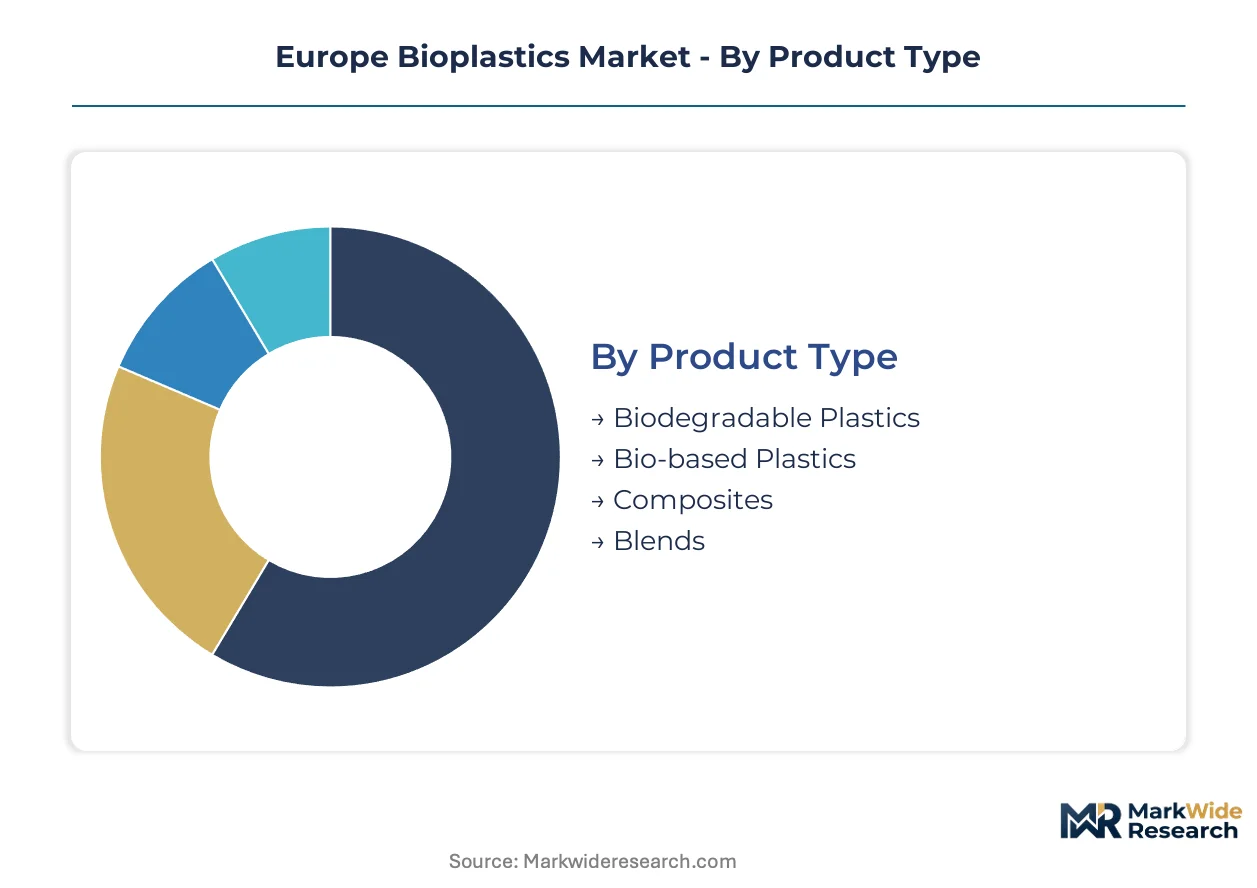
European bioplastics procurement diverges sharply across product maturity and certification requirements. Material selection determines regulatory compliance pathways, while end-use specifications dictate formulation complexity and supply chain configuration.
Product Type:
Mature certified grades dominate procurement volumes while emerging categories reshape margin structures.
- Biodegradable Plastics:Polyesters and starch-based polymers engineered for industrial composting per EN 13432 standards. Food packaging converters across Germany and France concentrate demand here as the EU Packaging and Packaging Waste Regulation mandates certified end-of-life pathways.
- Bio-based Plastics:Drop-in polymers derived from renewable feedstock but chemically identical to conventional plastics. Automotive OEMs specify these grades for interior panels to meet EU Green Deal carbon intensity thresholds without redesigning manufacturing equipment.
- Composites:Reinforced bioplastic matrices combining natural fibers with polymer binders.
- Blends:Alloyed formulations merging biodegradable and bio-based chemistries to optimize cost-performance ratios.
Biodegradable plastics handles the majority of throughput; bio-based plastics is the fastest mover on share.
End User:
Application-specific certification requirements create divergent customer economics across sectors.
- Packaging:Thermoformed trays, films, and rigid containers serving food contact applications. Retail private-label supply chains across the German Rhine-Ruhr cluster now mandate renewable content disclosure, accelerating specification shifts toward certified compostable grades.
- Agriculture:Mulch films, silage wraps, and planting trays requiring soil biodegradability. French farming cooperatives represent underpenetrated demand as starch-based alternatives displace conventional polyethylene in seasonal applications.
- Automotive:Interior trim panels, seat foams, and under-hood components.
- Consumer Goods:Disposable cutlery, cosmetic containers, and household durables.
Packaging commands the dominant procurement volume; agriculture is gaining share fastest through mulch film conversion programs.
Application:
Regulatory tailwinds concentrate investment in food contact and medical segments where certification barriers protect margin.
- Food Packaging:Flexible films, rigid thermoforms, and barrier coatings for perishable goods. EFSA compliance documentation and OK compost INDUSTRIAL certification have become non-negotiable entry requirements for suppliers to German retail chains.
- Agricultural Films:Soil-biodegradable mulch and greenhouse coverings. Italian vegetable farming regions around Terni demonstrate concentrated adoption where Novamont's integrated production complex enables rapid technical service response.
- Medical Applications:Sterile packaging, surgical instruments, and drug delivery systems.
- 3D Printing:Filament feedstocks for additive manufacturing prototypes and end-use parts.
Food packaging absorbs the largest resin allocation; agricultural films are expanding most quickly on a percentage basis.
Material:
Feedstock chemistry and polymerization route determine cost position and performance envelope.
- PLA:Ring-opening polymerization of lactide derived from corn or sugar beet fermentation. Total Corbion's Thai-European supply architecture dominates resin availability, though polymerization efficiency improvements are compressing unit costs relative to historical benchmarks.
- Starch Blends:Thermoplastic starch compounded with biodegradable polyesters. Novamont's Mater-Bi production complex in Terni anchors continental supply for film extrusion and injection molding grades.
- PHA:Bacterial fermentation products accumulating as intracellular carbon storage.
- PBAT:Fossil-derived biodegradable polyester commonly blended with PLA or starch to enhance flexibility.
PLA carries the heaviest throughput volume; starch blends are climbing the fastest as compounding technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders extract pricing premiums from Rhine-Ruhr cluster integration while Italian converters in Terni face tighter margin compression from agricultural feedstock volatility.
Germany
Food packaging manufacturers across the Rhine-Ruhr chemical cluster accelerate procurement of certified compostable grades as the EU Packaging and Packaging Waste Regulation mandates renewable content disclosure. ECHA substance evaluations constrain additive packages for medical packaging compounders. BASF SE anchors continental supply from its Ludwigshafen headquarters, extending certified resin availability into thermoforming applications.
Italy
Vegetable farming cooperatives in the Terni basin drive concentrated demand for soil-biodegradable mulch films as starch-based alternatives displace polyethylene. The EU Green Deal carbon intensity targets compel Novamont S.P.A. to scale its integrated Mater-Bi production complex for rapid technical service response. Italian converters bypass traditional petrochemical distributors to secure direct bioplastic resin supply from captive producers.
France
Underpenetrated silage wrap and agricultural film applications offer expansion paths for starch-based biodegradable grades across French farming regions. The F-Gas Regulation restricts persistent fluorinated compounds in food contact materials, demanding rapid reformulation of barrier coatings. Paris-based retail private-label supply chains now mandate OK compost INDUSTRIAL certification as a non-negotiable entry requirement.
Netherlands
Thermoforming converters adopt expanded PLA grades for fiber applications as polymerization efficiency improvements compress unit conversion costs. REACH compliance documentation elevates formulation complexity for compounders serving medical packaging segments. Rotterdam polymer distribution channels reshape around direct bioplastic resin procurement, displacing traditional petrochemical intermediaries.
Spain
Automotive OEMs specify bio-based plastics for interior trim panels to meet EU Green Deal carbon intensity thresholds without manufacturing equipment redesign. The EN 13432 harmonized certification eliminates regulatory fragmentation for cross-border biodegradable plastic trade. Barcelona-area compounders consolidate procurement around pre-certified suppliers with established EFSA compliance documentation.
Europe Bioplastics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on feedstock and polymerization technology. The European bioplastics market structures around three strategic archetypes: integrated chemical conglomerates with captive fermentation and polymerization assets, specialized biopolymer pure-plays focusing on certified compostable grades, and regional compounders serving niche thermoforming and fiber applications. Competitive dynamics concentrate on backward integration into lactic acid feedstock and direct resin procurement relationships that bypass traditional distribution channels.
Among integrated chemical producers, BASF SE and Novamont S.P.A. exemplify the platform archetype through their respective Ludwigshafen and Terni production complexes. Total Corbion PLA occupies a position bridging Thai-European supply architecture with continental thermoforming demand. These three entities represent distinct competitive vectors: German-engineered system integration, Italian agricultural film specialization, and transcontinental PLA resin availability.
| Leading Market Players |
|---|
| BASF SE |
| Novamont S.P.A. |
| Total Corbion PLA |
| Avantium N.V. |
| Carbios |
| Biome Bioplastics |
| Sabic |
| FKuR Kunststoff GmbH |
| Futerro |
| Others |
Supply & Pricing Matrix
Single-source dependency on Thai-European lactic acid feedstock corridors determines both the premium spread for certified compostable grades and the three-tier supply chain configuration spanning integrated producers, captive compounders, and spot-market converters. Corn and sugar beet price volatility feeds directly into margin compression at the standard tier while reinforcing pricing power for backward-integrated specialists.
Pricing Analysis
The customization-premium spread separates configured-to-order certified grades from standard EN 13432-compliant resins. Contract-based long-term offtake dominates the premium tier where BASF SE and Novamont S.P.A. anchor supply, while spot-market transactional pricing governs standard-grade PLA from Total Corbion's Thai-European architecture. Price differentiation hinges on OK compost INDUSTRIAL certification level and volume scale commitments. Pricing pressure stems from lactic acid feedstock cost volatility compressing margins at the standard tier. Small-scale thermoforming converters exhibit highest price sensitivity; automotive OEMs with renewable content mandates show least.
Supply Chain Analysis
Upstream agricultural feedstock from corn and sugar beet cultivation in France, Germany, and Belgium anchors the European bioplastics supply base. Raw material dependencies center on lactic acid fermentation capacity, starch processing infrastructure, and ring-opening polymerization catalysts. Single-source vulnerability concentrates in Total Corbion PLA's Thai-European resin architecture. Distribution runs through direct procurement relationships that bypass traditional petrochemical distributors, with compounders and converters securing captive supply from integrated producers in the Rhine-Ruhr cluster and Terni basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states on compostability certification timelines creates fragmentation opportunity for specialists capturing niche certification pathways ahead of harmonization.
For Market Incumbents: Pre-empt margin erosion from Thai-European supply concentration by securing captive lactic acid fermentation capacity in the Rhine-Ruhr corridor. Invest in OK compost INDUSTRIAL certification ahead of pending EU Packaging and Packaging Waste Regulation revisions to lock in specification-driven procurement from German retail chains. For New Entrants and Emerging Players: French agricultural film applications represent the most penetrable entry point, with underpenetrated silage wrap and mulch film demand from farming cooperatives seeking starch-based polyethylene alternatives. Target technical service partnerships with Novamont S.P.A.'s Terni complex for rapid formulation support as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors compounders with pre-certified EFSA documentation and established ECHA compliance pathways. Long-term viability hinges on backward integration into agricultural feedstock or polymerization technology. Watch EN 13432 harmonization progress across member states as the inflection signal for scale-platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive feedstock supply from French and German agricultural regions reduces commodity exposure. |
| OK Compost INDUSTRIAL Certification Investment | Pre-certified status unlocks specification-driven procurement from Rhine-Ruhr retail supply chains. |
| Direct Resin Procurement Channel Development | Bypassing traditional petrochemical distributors captures margin from converter relationships. |
| Agricultural Film Application Expansion | French mulch and silage wrap demand offers volume growth outside saturated food packaging. |
| Polymerization Efficiency R&D Partnership | Collaboration with Terni or Ludwigshafen technical centers accelerates durable-grade PLA cost parity. |
Research Methodology
Desk research of EU regulatory filings, ECHA substance evaluations, EN 13432 certification databases, and Cefic polymer trade statistics preceded structured interviews with bioplastic plant managers, food packaging procurement leads at German retail chains, agricultural cooperative technical directors, and polymer distribution channel partners. Primary fieldwork across the Rhine-Ruhr cluster and Terni basin was cross-validated against customs data and SEC filings from integrated chemical producers. Bottom-up resin volume estimates and top-down regulatory impact assessments were triangulated to establish market sizing.
Assumptions around EU Green Deal carbon intensity target enforcement, F-Gas Regulation compliance timelines, and EN 13432 harmonization progress were held fixed across baseline scenarios while lactic acid feedstock price volatility and Thai-European logistics disruption were stress-tested in sensitivity runs. The analytical framework modeled product type, end-use industry, application segment, and material chemistry across the projection horizon. CAGRs were derived from segment-level volume build-ups incorporating polymerization efficiency improvement curves and regulatory mandate implementation schedules.
Stress conditions across corn and sugar beet price bands, Thai baht-euro exchange rate volatility, and EU Packaging and Packaging Waste Regulation revision scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on certification adoption rates and feedstock cost trajectories. Cross-checking against Cefic polymer production statistics and ECHA substance evaluation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
North America Bioplastics Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Global Bioplastic Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market