
 Europe Caustic Soda Market | 2026-2036
Europe Caustic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Caustic Soda Market Analysis
Membrane cell electrolysis is reshaping European chlor-alkali production economics by slashing energy intensity and eliminating mercury-based processes. Nobian leverages its integrated salt-to-soda supply chain across the Netherlands and Germany to sustain cost leadership in merchant caustic supply. BASF anchors substantial captive consumption at its Ludwigshafen Verbund site, while Ercros competes through specialized high-purity grades for pharmaceutical and water treatment applications.
Caustic soda, sodium hydroxide with a minimum purity of 98 percent in solid form or 50 percent concentration in liquid form, serves as a strong base for pH adjustment, chemical synthesis, and organic processing across heavy industry. The membrane cell production process dominates European capacity after REACH-driven mercury phaseouts, while lime-soda methods retain niche positions in regions with favorable limestone access. Liquid caustic soda leads product type volumes due to lower handling costs for bulk industrial users, though flake caustic soda commands premium positioning in remote or seasonal applications where transport economics favor solid forms.
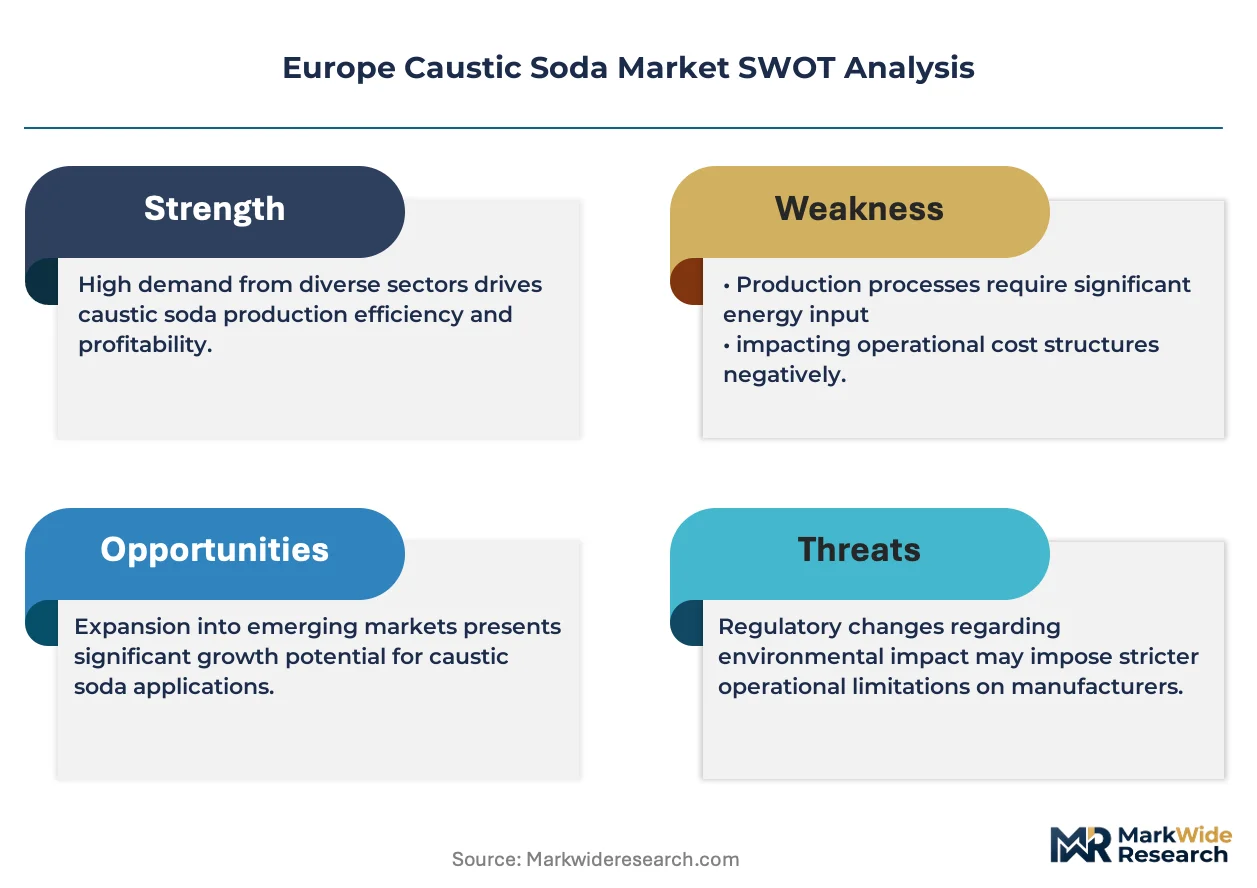
REACH and the EU F-Gas Regulation shape chemical manufacturing standards, with ECHA enforcing substitution requirements that elevate membrane technology adoption and restrict legacy process chemistries. The EU Green Deal's carbon border adjustments and national industrial decarbonization contracts in Germany and France are redirecting investment toward electrolyzers powered by renewable electricity. Stakeholders must monitor the pace of power purchase agreement contracting for green hydrogen-linked chlor-alkali expansions, as these project commitments will determine which production sites secure long-term cost advantages.
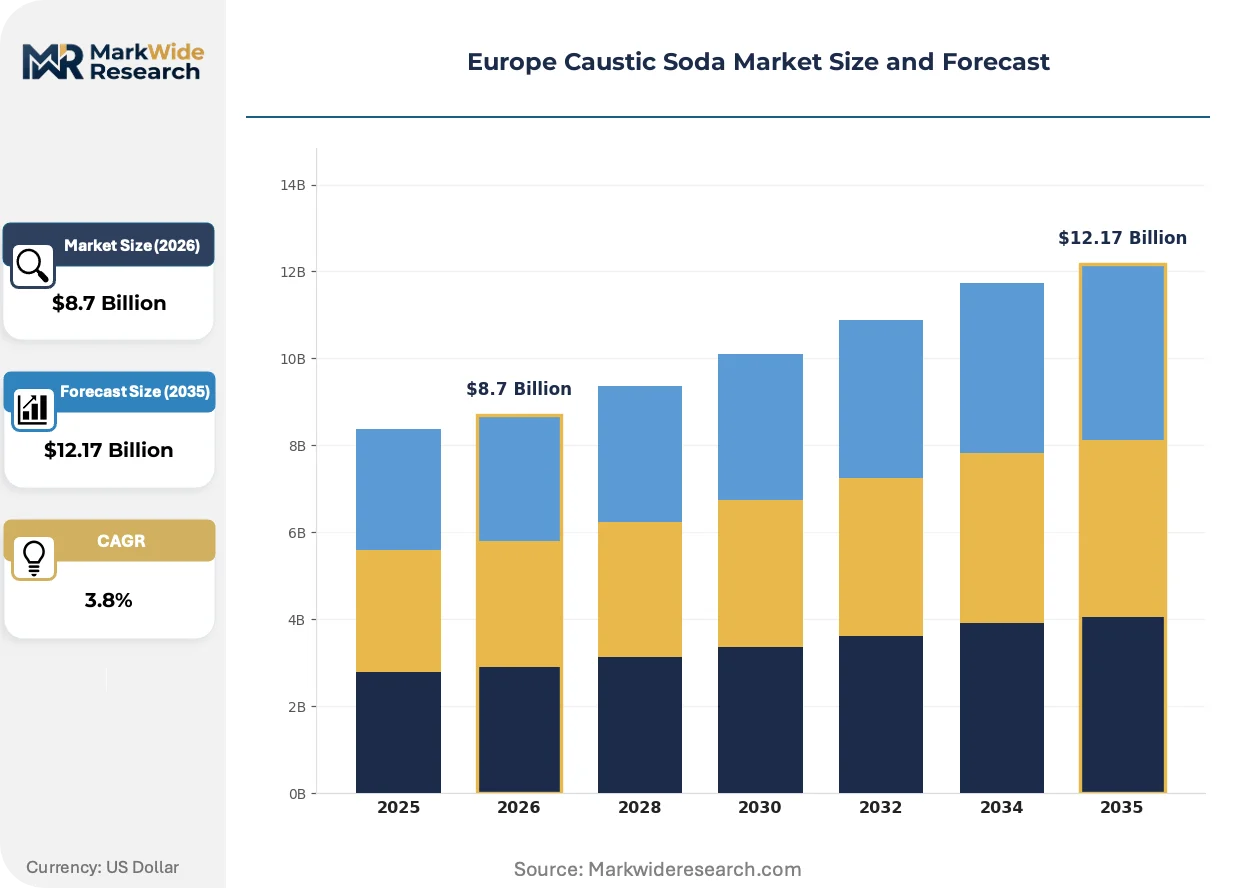
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are forcing chlor-alkali producers to abandon mercury cell technology and electrify operations through renewable power purchase agreements. This structural shift concentrates investment in membrane cell electrolysis and green hydrogen-linked expansions.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates demand for caustic soda in industrial heat pump and refrigeration manufacturing across Germany and France.
- Pulp and paper sector expansion:Scandinavian mills are modernizing bleaching and chemical recovery cycles, driving merchant caustic consumption in Finland and Sweden.
- Membrane cell technology:Energy intensity reductions of 15-25% versus diaphragm processes improve margins for Rhine-Ruhr producers supplying Ludwigshafen chemical complexes.
Market Restraints
- Electricity cost volatility:German and Dutch chlor-alkali operations face margin compression from natural gas price spikes affecting grid power contracts.
- Supply concentration risk:Merchant caustic availability tightens around Nobian's integrated salt-to-soda network in the Netherlands and Germany.
- Substitution by potassium hydroxide:Specialty soap and biodiesel producers in Southern Europe switch to caustic potash for certain pH adjustment applications.
Strategic Opportunities
- Polish chemical corridor:Underdeveloped chlor-alkali capacity creates white space for membrane cell investments serving Central European downstream users.
- Green hydrogen co-production:Electrolyzer-linked chlor-alkali expansions qualify for German and French national decarbonization contracts and carbon border adjustment exemptions.
- High-purity pharmaceutical grades:EMA quality standards for active pharmaceutical ingredient manufacturing drive premium pricing for specialized caustic in water treatment and synthesis.
Industry Challenges
- Electrical technician scarcity:Membrane cell retrofits and renewable integration projects face delays from shortages of chlor-alkali process engineers in Germany's chemical belt.
- REACH registration timelines:ECHA substance evaluation procedures for imported caustic soda extend certification cycles, disrupting just-in-time supply arrangements for SME formulators.
- Legacy mercury site remediation:Former diaphragm and mercury cell facilities in Eastern Europe require costly environmental liability management before brownfield redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Caustic Soda Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Caustic Soda, Solid Caustic Soda, Flake Caustic Soda, Tablet Caustic Soda End User: Pulp & Paper, Textiles, Agriculture, Soap & Detergents Production Process: Electrolytic, Lime-Soda, Membrane Cell, Mercury Cell Application: Chemicals, Water Treatment, Oil & Gas, Pharmaceuticals |
| Companies Covered | Nobian, Kem One, Dow, Westlake Corporation, BASF, Covestro, Ercros, Olin Corporation, INEOS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Caustic Soda Market Emerging Trajectories
Digital process control and renewable power integration are transforming European chlor-alkali economics. Producers are virtualizing operations, decarbonizing supply chains, and repositioning for carbon border adjustment compliance.
Advanced process control software is virtualizing membrane cell monitoring and predictive maintenance across German and Dutch chlor-alkali plants. BASF and Nobian operations teams deploy machine learning algorithms to optimize current density and brine purity in real time. This virtualization compresses unplanned downtime and extends electrode coating lifecycles beyond traditional preventive maintenance schedules.
REACH and the EU Green Deal's carbon border adjustment mechanism are redirecting capital toward electrolyzers with documented renewable electricity sourcing. German producers secure 10-15 year power purchase agreements with offshore wind developers to lock in green hydrogen-linked chlor-alkali expansions. French chemical sites qualify for national industrial decarbonization contracts covering membrane cell retrofits and grid balancing services.
Merchant buyers are consolidating procurement through long-term offtake contracts with integrated producers rather than spot market purchases. Pulp and paper mills in Scandinavia and water treatment operators in Benelux negotiate five-year supply agreements with fixed-volume, indexed-price structures. This contract concentration is most visible in Germany's Rhine-Ruhr corridor, where captive Ludwigshafen consumption limits merchant availability and pushes independent buyers toward Dutch and Belgian supply alternatives.
Europe Caustic Soda Market Segmentation
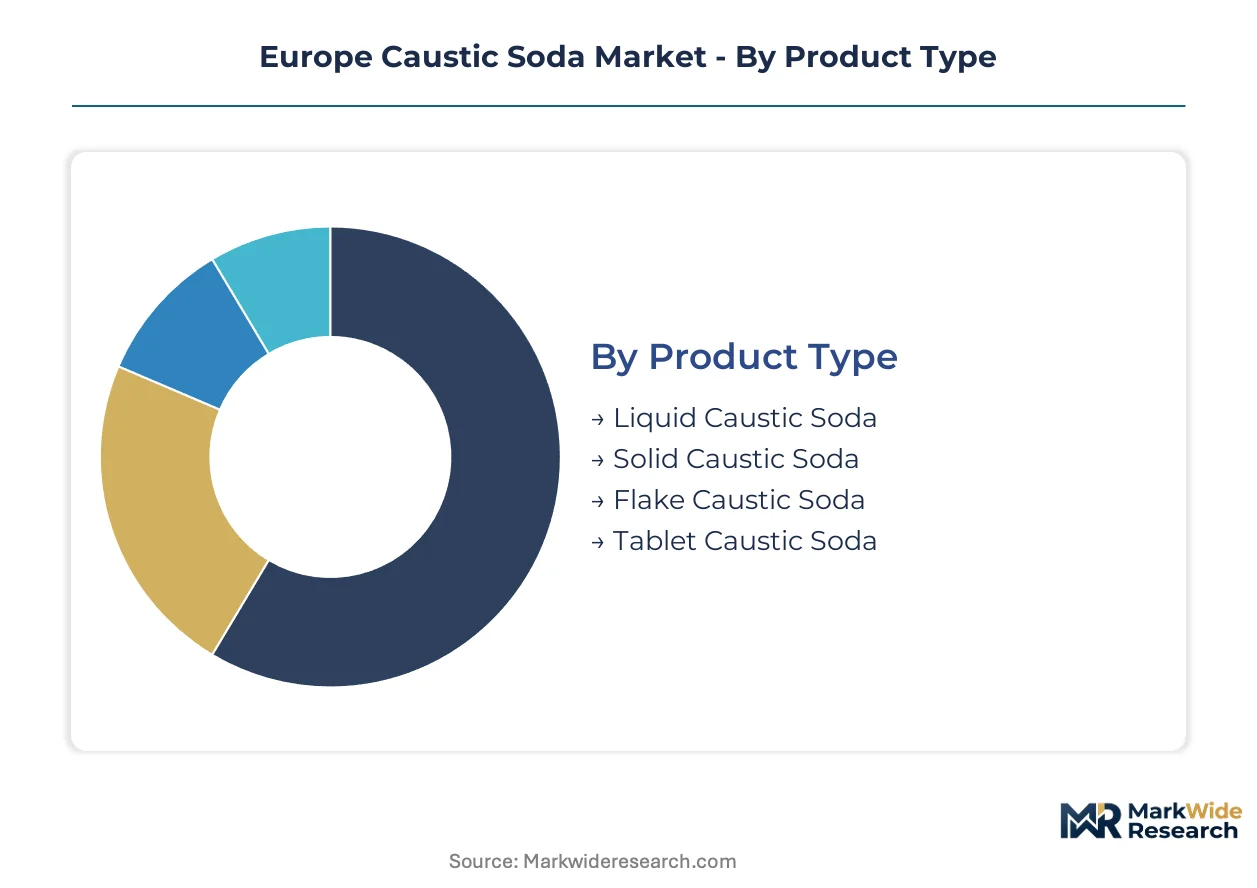
Caustic soda segmentation across Europe reflects divergent supply chain economics and regulatory compliance burdens. Each category maps distinct technical specifications to downstream value capture, from membrane cell purity grades to solid form logistics premiums.
Product Type:
After-sales service intensity varies sharply across physical forms, with liquid demanding bulk logistics partnerships and solid formats requiring technical handling support.
- Liquid Caustic Soda:Aqueous solution at 50% concentration dominates Rhine-Ruhr chemical corridor deliveries. BASF's Ludwigshafen Verbund and Scandinavian pulp mills absorb tanker volumes where pipeline and barge infrastructure minimizes handling costs.
- Flake Caustic Soda:Solid form produced through evaporation and flaking delivers 98% purity for remote sites lacking liquid storage. Seasonal water treatment operators in Alpine regions and mobile industrial cleaners pay logistics premiums for reduced transport weight.
- Solid Caustic Soda:Cast blocks and crushed forms serve foundry flux and specialized metallurgical applications across Germany's industrial belt.
- Tablet Caustic Soda:Precision-dosed tablets support laboratory reagent markets and small-scale pH adjustment in swimming pool and aquarium maintenance across Benelux.
By volume, liquid caustic soda leads. By growth pace, flake caustic soda is ahead.
End User:
Cost tier stratification separates commodity bulk consumers from specialty formulation buyers, with pulp and paper commanding lowest unit margins and pharmaceuticals extracting highest purity premiums.
- Pulp & Paper:Kraft process pulping and chlorine dioxide generation consume merchant caustic across Finland's Botnia Gulf mills and Sweden's Värmland forests. REACH-compliant bleaching sequences displace elemental chlorine, sustaining chemical recovery cycle intensity.
- Soap & Detergents:Saponification and surfactant synthesis drive batch consumption at Henkel's Düsseldorf operations and mid-sized Italian formulators. Fatty acid neutralization demands consistent 50% liquid grades with controlled carbonate levels.
- Textiles:Mercerization and dyeing processes apply caustic to cotton fibers across Portugal's northern textile cluster and Turkey's Bursa region.
- Agriculture:pH adjustment for herbicide formulations and silage treatment supports seasonal demand patterns in France's cereal belt and Poland's dairy regions.
Pulp and paper anchors volume share. Pharmaceutical-adjacent soap and detergent applications are climbing the fastest.
Production Process:
Application maturity divides legacy technologies facing phaseout from membrane cell investments qualifying for French and German decarbonization contracts.
- Membrane Cell:Ion-exchange membrane electrolysis delivers 32% caustic directly with lowest energy intensity. Nobian's Rotterdam and Delfzijl sites and INOVYN's Runcorn complex deploy this technology for EU Green Deal compliance.
- Mercury Cell:Castner-Kellner process using liquid mercury cathodes persists in limited Eastern European capacity facing ECHA-mandated conversion timelines and remediation liabilities.
- Electrolytic:Diaphragm cell variants without membrane specificity retain niche positions where existing infrastructure delays capital replacement.
- Lime-Soda:Chemical synthesis from soda ash and lime serves isolated markets with favorable limestone access and limited chlorine co-product demand.
Membrane cell commands installed capacity leadership. Lime-soda retains steepest expansion trajectory in Central European greenfield planning.
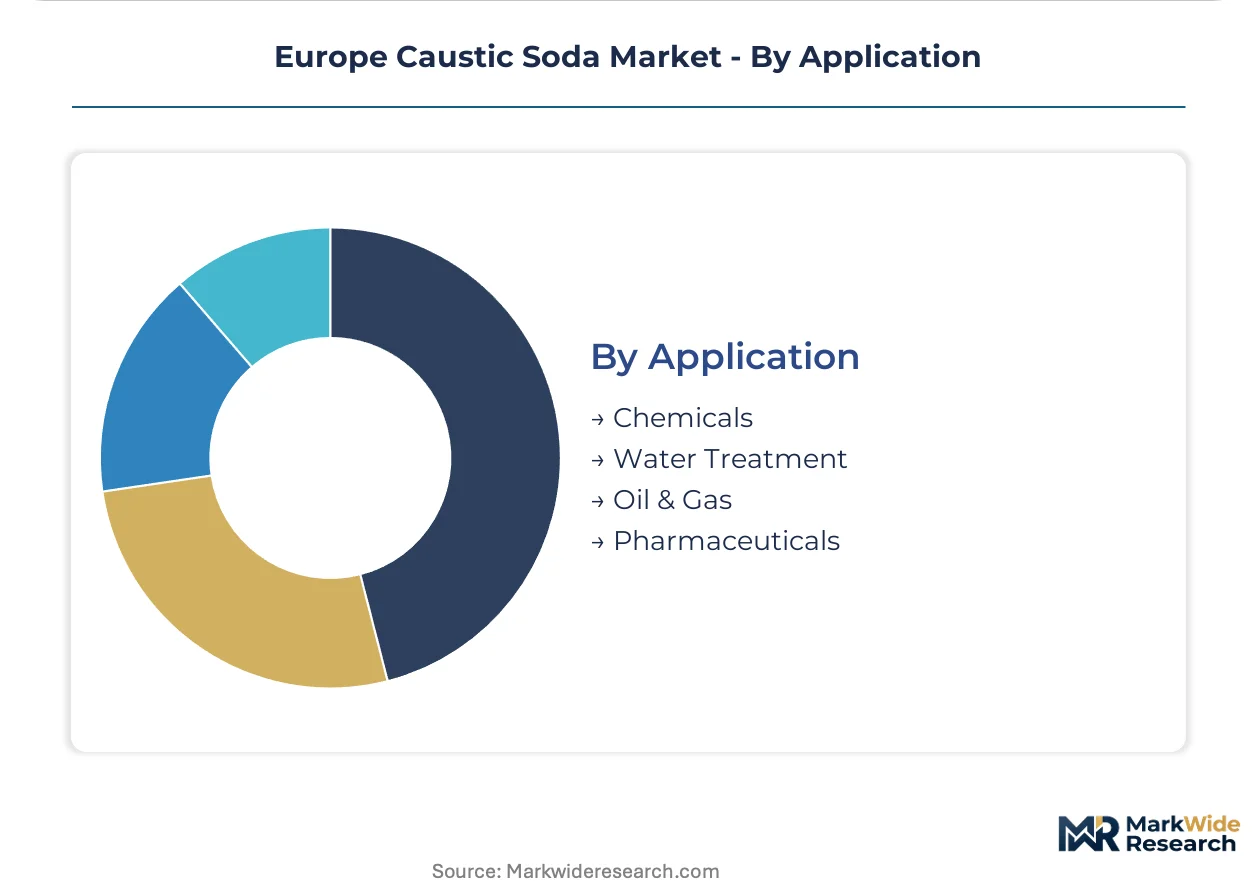
Application:
Supply concentration by customer type funnels merchant volumes through integrated producers for chemicals and water treatment, while oil and gas procurement fragments across field service distributors.
- Chemicals:Organic synthesis, petrochemical derivatives, and chlorinated intermediates absorb captive and merchant supply. Ludwigshafen's Verbund sites and Antwerp's chemical cluster integrate caustic into ethylene oxide and polycarbonate chains.
- Water Treatment:Municipal and industrial effluent pH adjustment drives drum and tote deliveries across German states implementing stricter wastewater discharge limits.
- Pharmaceuticals:EMA-grade high-purity caustic supports active pharmaceutical ingredient synthesis and equipment cleaning validation at Irish and Swiss manufacturing sites.
- Oil & Gas:Drilling mud pH control and refinery alkylation unit neutralization sustain North Sea platform and Rotterdam refinery offtake.
Chemicals application leads by volume. Pharmaceuticals is gaining share fastest on purity premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant caustic buyers concentrate around integrated chlor-alkali corridors where pipeline and barge infrastructure minimize logistics costs. Rhine-Ruhr chemical complexes absorb captive volumes while independent formulators compete for residual supply.
Germany
Ludwigshafen's Verbund sites and Rhine-Ruhr industrial belt consume membrane cell output for ethylene oxide and polycarbonate synthesis. The national industrial decarbonization program funds electrolyzer retrofits with renewable power purchase agreements. BASF's Ludwigshafen complex anchors captive demand while merchant buyers face tight supply availability.
Netherlands
Rotterdam's chemical cluster and Delfzijl production sites supply Benelux water treatment and Scandinavian pulp mills through integrated salt-to-soda networks. REACH compliance costs elevate membrane technology adoption across Dutch chlor-alkali capacity. Nobian's Rotterdam operations control merchant supply flows into Germany's independent chemical formulators.
France
Specialty soap manufacturers and pharmaceutical formulators in Lyon and Paris regions drive high-purity caustic consumption. The national industrial decarbonization contract scheme subsidizes membrane cell retrofits and grid balancing services. Kem One's Fos-sur-Mer and Pont-de-Claix sites serve Mediterranean chemical corridors with chlorine-integrated output.
Sweden
Botnia Gulf pulp mills modernize bleaching sequences under REACH-compliant chemical recovery mandates. The EU F-Gas Regulation accelerates industrial heat pump manufacturing demand across Nordic chemical engineering clusters. Värmland forest industry complexes sustain seasonal merchant caustic offtake for kraft process intensification.
Poland
Underdeveloped chlor-alkali capacity creates supply gaps for Central European downstream chemical users. ECHA substance evaluation timelines extend certification cycles for imported caustic, disrupting just-in-time procurement. The emerging chemical corridor around Płock and Upper Silesia attracts membrane cell investment interest from Western European producers.
Europe Caustic Soda Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a structure shaped by captive consumption and merchant availability tensions. Integrated salt-to-soda networks concentrate supply power while independent formulators fragment procurement. Three archetypes dominate: integrated chemical conglomerates with captive Verbund consumption, merchant-focused chlor-alkali specialists with pipeline distribution control, and diversified industrial gas players with electrolyzer co-production capabilities. Capacity expansion and renewable power contracting represent the dominant competitive moves as carbon border adjustments reshape site economics.
Among integrated chemical conglomerates, BASF and Covestro exemplify captive consumption models where Ludwigshafen and Antwerp Verbund sites internalize caustic within ethylene oxide and isocyanate chains. Ercros occupies a position within the high-purity specialist tier, serving pharmaceutical and water treatment applications where EMA quality standards command premium positioning. These three entities represent distinct strategic postures: full integration, regional merchant control, and premium-grade specialization.
| Leading Market Players |
|---|
| Nobian |
| Kem One |
| Dow |
| Westlake Corporation |
| BASF |
| Covestro |
| Ercros |
| Olin Corporation |
| INEOS |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr barge corridors anchor European caustic soda logistics, where pipeline and tanker infrastructure concentrates supply power among integrated producers. This freight geometry elevates cost-plus contract indexation for independent formulators while membrane cell producers capture margin premiums through renewable power purchase agreements.
Pricing Analysis
Cost-plus contracts with monthly electricity indexation dominate merchant caustic procurement across Germany and the Netherlands. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and economy-merchant levels separates EMA-certified purity from commodity 50% liquid grades. Pricing pressure stems from grid power volatility affecting German chlor-alkali margins. Pulp and paper mills exhibit highest price sensitivity due to volume scale and captive alternative sourcing, while pharmaceutical formulators absorb purity premiums with limited negotiation leverage.
Supply Chain Analysis
Export-control regimes on membrane cell technology limit capacity expansion equipment flows into Eastern European markets. Supply concentrates in Germany, the Netherlands, and Belgium, with salt-to-soda networks drawing from North Sea brine deposits and imported rock salt. Chlorine co-product offtake agreements and renewable power purchase contracts constitute critical input dependencies. Single-source vulnerability runs through Nobian's Rotterdam-Delfzijl corridor for Benelux and Northern German merchant demand. Distribution runs through integrated producer direct contracts rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium hydroxide substitution in Southern European soap and biodiesel applications threatens caustic soda volume retention, demanding proactive defense from established producers.
For Market Incumbents: Build renewable power purchase agreement moats to lock in electrolyzer economics against grid price volatility. Secure long-term salt supply contracts from North Sea brine operators to reinforce backward integration into feedstock security. Pursue membrane cell retrofit completion before ECHA mercury phaseout deadlines tighten. Prioritize pharmaceutical-grade certification investments to capture EMA-tier pricing premiums escaping commodity competition. For New Entrants and Emerging Players: Pursue Polish chemical corridor greenfield development where underdeveloped chlor-alkali capacity meets Central European downstream demand. Target high-purity pharmaceutical and water treatment segments where EMA quality standards and REACH compliance create qualification barriers protecting margin structures. Deploy membrane cell technology with documented renewable sourcing to qualify for French and German national decarbonization contract subsidies. For Investors and Strategic Acquirers: Merchant-focused chlor-alkali specialists with pipeline distribution control represent the optimal acquisition archetype for portfolio exposure to European industrial decarbonization. Long-term viability hinges on power purchase agreement contracting velocity and electrolyzer technology access across the next decade. Watch German industrial electricity pricing spreads against Dutch offshore wind contract rates as the inflection signal for site competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Locks in electrolyzer electricity costs for membrane cell operations qualifying under EU Green Deal contracts. |
| Membrane Cell Retrofit Completion | Eliminates mercury cell liabilities and secures ECHA REACH compliance before mandated phaseout deadlines. |
| Pharmaceutical-Grade Certification | Captures EMA-tier pricing premiums from Irish and Swiss active pharmaceutical ingredient manufacturers. |
| Salt-to-Soda Vertical Integration | Secures North Sea brine supply chains against imported rock salt price volatility for Rotterdam producers. |
| Polish Corridor Greenfield Entry | Addresses Central European supply gaps where ECHA import certification delays disrupt just-in-time procurement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with chlor-alkali plant managers, downstream chemical procurement leads, pulp mill technical directors, and water treatment operators; and secondary validation through customs trade data, Cefic chlor-alkali reports, SEC filings from listed producers, and EU ETS emissions disclosures. Bottom-up capacity modeling and top-down demand reconciliation triangulated volume estimates across production process, product form, and end-use segment dimensions.
Forecast inputs considered membrane cell capacity expansion timelines, renewable power purchase agreement contracting velocity, and EU F-Gas Regulation implementation pace across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, production technology, and regional production hub dimensions. CAGRs derived from installed capacity utilization rates, electrolyzer energy intensity improvements, and downstream demand elasticity parameters specific to pulp and paper, chemical synthesis, and water treatment applications.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, natural gas grid spreads, or carbon border adjustment implementation timing would shift the trajectory. Forecasts reflect documented assumptions on ECHA enforcement timelines and national decarbonization contract funding continuity. Material shifts in membrane cell technology licensing access or Polish regulatory framework acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Phosphorus and Derivatives Market