
 North America Carbon Black Market | 2026-2036
North America Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
North America Carbon Black Market Outlook
Direct supply contracts between carbon black producers and tire manufacturers is reconfiguring procurement patterns across North America. Cabot Corporation leverages its integrated manufacturing network to sustain feedstock security along the US Gulf Coast. Birla Carbon anchors its regional position through specialized furnace black production for high-performance tire grades. Orion Engineered Carbons competes by focusing on specialty grades that command premium positioning in non-tire applications.
Carbon black is a colloidal carbon material produced by incomplete combustion of heavy petroleum products, with primary particle sizes ranging from ten to five hundred nanometers and surface areas between twenty and two hundred fifty square meters per gram. It functions as a reinforcing filler in rubber compounds, a pigment in coatings and inks, and a conductive additive in plastics and electronics. The tire application dominates volume flows, though specialty grades for plastics and electronics concentrate margin pools due to technical barriers and qualification requirements. HTR and PHR product types lead in tonnage, while specialty carbon black for coatings and electronics represents the fastest-expanding category as conductivity specifications tighten.
EPA emissions standards under the Clean Air Act shape furnace black production investments, while OSHA permissible exposure limits drive workplace controls and automation spending. The US Toxic Substances Control Act and corresponding state-level environmental reviews in Texas and Louisiana influence facility permitting timelines and capital deployment decisions. Stakeholders must monitor regulatory alignment between federal air quality mandates and emerging state carbon accounting rules to anticipate compliance cost trajectories and facility upgrade cycles.
Market Dynamics
Electric vehicle tire specifications are reconfiguring carbon black procurement across North America. Higher load-bearing requirements and reduced rolling resistance targets are forcing compound reformulations that favor specialized furnace black grades with tailored surface area and structure properties.
Growth Catalysts
- EPA Clean Air Act enforcement:Stricter emissions standards for furnace black production are accelerating capital deployment toward cleaner thermal processes and emission control retrofits across US Gulf Coast facilities.
- Electric vehicle tire demand:EV manufacturers require reinforced tread compounds to manage battery weight and torque delivery, expanding consumption of high-structure carbon black grades.
- US Gulf Coast feedstock integration:Proximity to integrated refineries provides cost-advantaged access to aromatic oils and creosote feedstocks, sustaining regional production economics.
Market Restraints
- Crude oil price volatility:Carbon black feedstock costs track aromatic oil indices, compressing margins during upstream price spikes and limiting pricing flexibility.
- US Gulf Coast concentration risk:Over half of North American capacity clusters in hurricane-exposed coastal zones, creating single-point vulnerability to weather-related supply disruptions.
- Silica-silane substitution:Green tire formulations are displacing carbon black volume in low-rolling-resistance segments, threatening share in passenger vehicle OEM specifications.
Strategic Opportunities
- Canadian oil sands integration:Alberta's heavy crude upgraders offer alternative feedstock streams that could diversify supply chains beyond US Gulf Coast dependence.
- Conductive plastics for battery housings:EV battery enclosure specifications are opening specialty carbon black demand in thermal management and electrostatic discharge applications.
- OSHA workplace automation mandates:Tightening permissible exposure limits are creating competitive advantage for producers with advanced process control and closed-loop material handling systems.
Industry Challenges
- Process control engineering talent:Furnace black production requires specialized expertise in combustion optimization and particle size distribution control that is aging out of the workforce.
- Emissions control capex cycles:Scrubber and baghouse upgrades demand sustained capital allocation while returns compete with specialty grade expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Carbon Black Market |
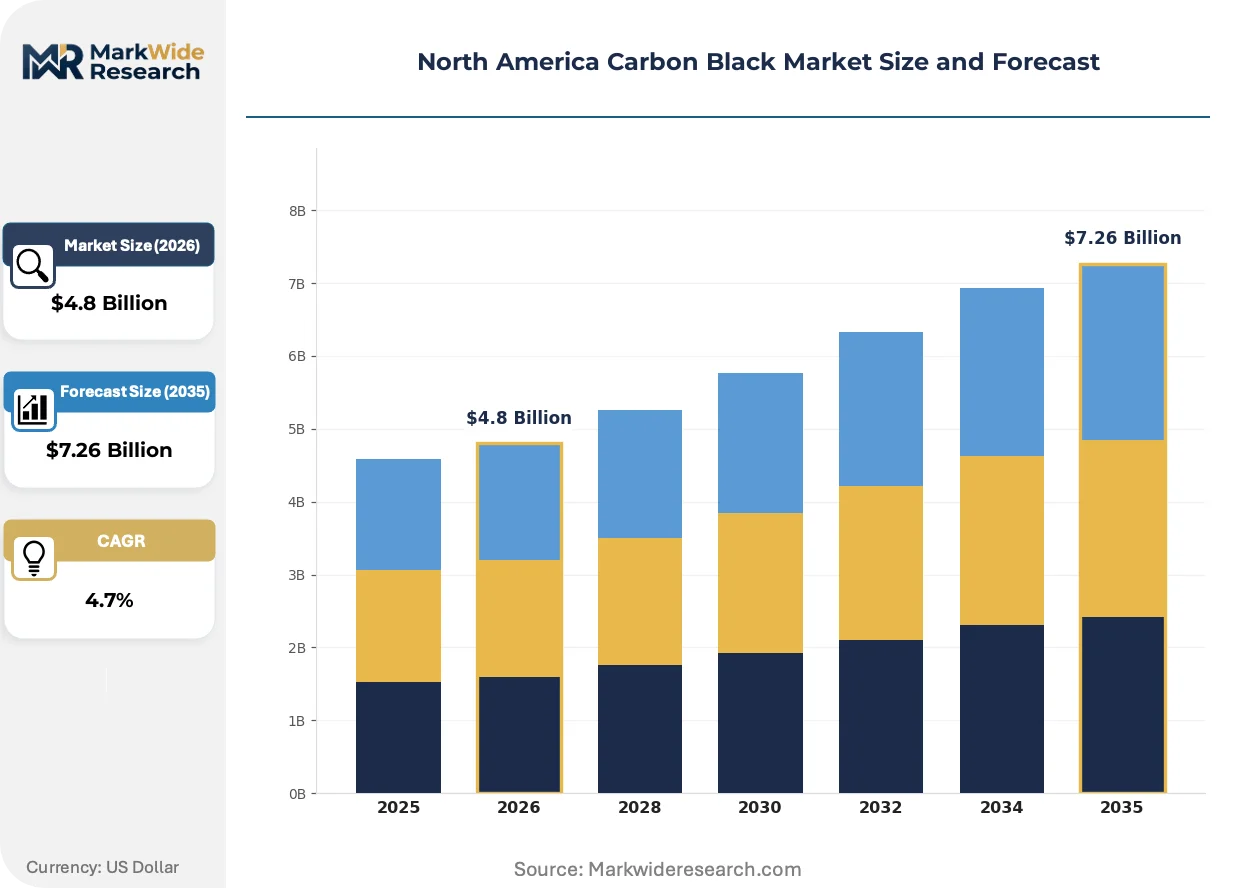
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HTR, PHR, SR, Specialty Application: Tires, Coatings, Plastics, Inks End User: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Cabot Corporation, Birla Carbon, Orion Engineered Carbons, Continental Carbon Company, Tokai Carbon Co., Ltd., Sid Richardson Carbon & Energy Co, Imerys, Mitsubishi Chemical Corporation, OMSK Carbon Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Carbon Black Market Strategic Shifts
Process intelligence and feedstock flexibility are reshaping carbon black manufacturing economics. Producers are deploying advanced analytics to optimize furnace operations while diversifying input streams beyond traditional aromatic oils.
Plasma-assisted carbon black production is digitizing quality control workflows in pilot installations. The technology enables real-time particle size monitoring through inline spectroscopy, allowing continuous adjustment of reactor conditions. Specialty tire compounders in the US Midwest are qualifying plasma-derived grades for ultra-high-performance applications where batch-to-batch consistency commands premium positioning.
OSHA's updated permissible exposure limits for carbon black dust are compressing facility upgrade timelines across Texas and Louisiana. The standard forces accelerated automation of bagging and bulk handling operations, favoring producers with capital reserves for robotic material transfer systems. Integrated Gulf Coast operators are consolidating maintenance windows to coordinate emissions control retrofits with OSHA compliance investments.
Direct mill integration contracts are displacing spot market purchases among major tire manufacturers. Compounders are negotiating captive offtake arrangements that guarantee feedstock security in exchange for volume commitments, concentrating procurement relationships around three to four preferred suppliers. This pattern is most pronounced in US Southeast tire production corridors where just-in-time compound delivery requirements leave minimal buffer inventory.
North America Carbon Black Market Segmentation
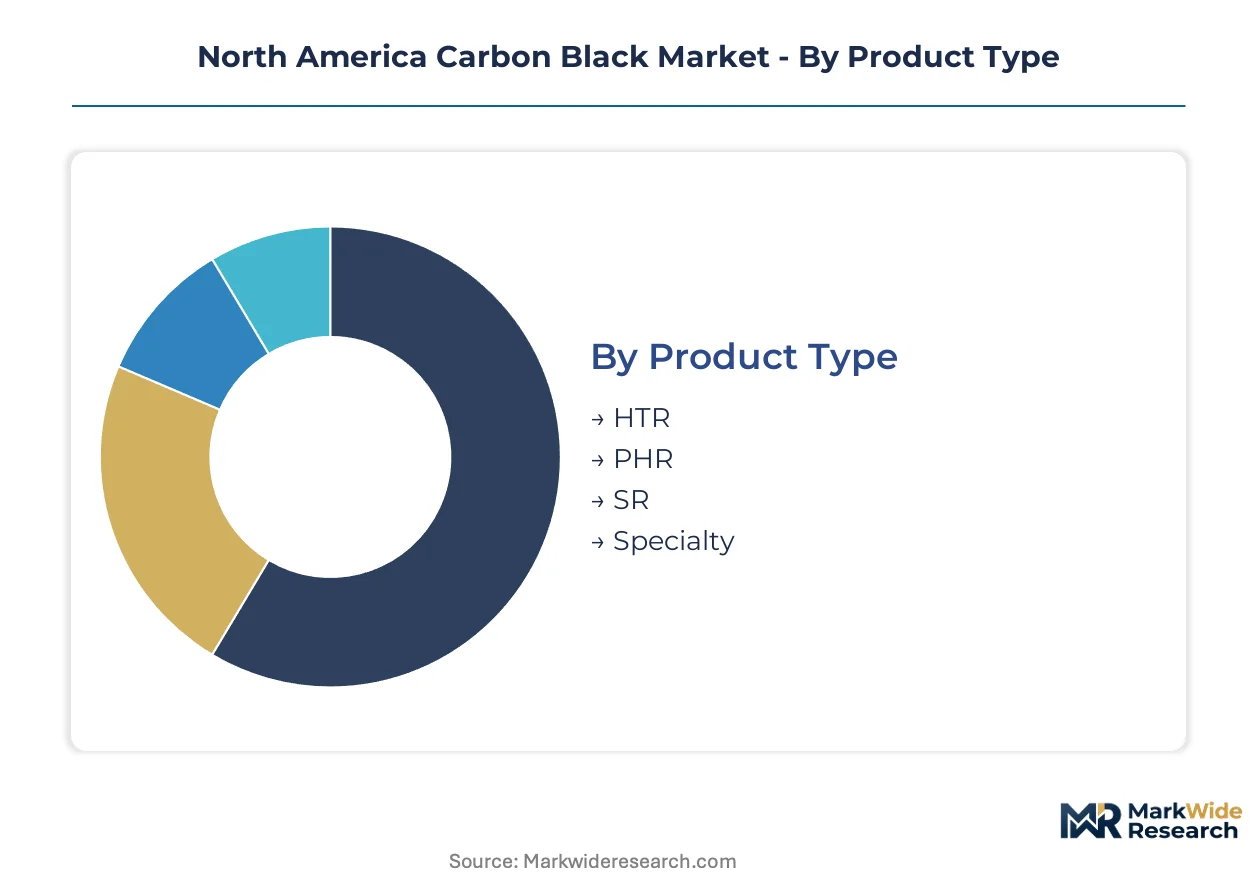
Carbon black segmentation reveals distinct margin architectures across product grades and end-use applications. Technical specifications, qualification barriers, and supply chain integration depth vary dramatically between commodity furnace black and specialty conductive grades.
Product Type:
After-sales service intensity concentrates in specialty grades requiring technical support for formulation optimization, while commodity grades operate on volume logistics with minimal field engineering.
- HTR:High-tensile reinforcing carbon black features primary particle sizes of twenty to thirty-five nanometers with surface areas exceeding one hundred twenty square meters per gram. Tire manufacturers across the US Southeast specify HTR for truck and bus radial applications where tread wear resistance commands premium compound costs.
- PHR:Processing-resistant hard blacks maintain structural integrity under high-shear mixing conditions in dense rubber formulations. EV tire producers in Texas and South Carolina are expanding PHR procurement for high-load-bearing tread compounds managing battery weight distribution.
- SR:Semi-reinforcing grades bridge performance between hard blacks and soft blacks in general-purpose rubber applications.
- Specialty:Conductive and pigment grades for plastics, coatings, and electronics carry qualification-driven technical service requirements.
HTR holds the largest share; momentum sits with Specialty grades expanding most quickly in battery enclosure and electrostatic discharge applications.
Application:
Application segmentation tracks directly to formulation complexity and customer concentration, with tire compounds demanding scale economies and specialty coatings requiring batch customization.
- Tires:Tread, sidewall, and carcass compounds consume over seventy percent of North American carbon black volume. Major tire manufacturers in Tennessee, Ohio, and South Carolina operate direct mill integration contracts that bypass distributor margins.
- Coatings:Pigment-grade carbon black delivers jetness and UV stability in automotive and industrial finishes. Formulators in Michigan and Illinois are qualifying low-PAH grades for automotive OEM specifications tightening under EPA air quality mandates.
- Plastics:Masterbatch and conductive compounds for packaging and electronics housings.
- Inks:Publication and packaging gravure applications with particle size distribution critical to print quality.
Tires dominate volume flows; climbing the fastest are Plastics applications in EV battery thermal management systems.
End User:
End-user segmentation reflects divergent procurement power, with automotive OEMs commanding direct supply relationships and construction buyers fragmenting across regional distributors.
- Automotive:OEM tire specifications and under-the-hood rubber components drive qualification-intensive procurement. Detroit-area automakers are embedding carbon black sustainability metrics into supplier scorecards ahead of anticipated SEC climate disclosure rules.
- Construction:Roofing membranes, sealants, and industrial hose applications favor cost-optimized furnace black grades.
- Consumer Goods:Footwear, sporting equipment, and appliance components.
- Electronics:Conductive compounds for device housings and battery systems.
Automotive anchors demand volume; Electronics gains share fastest on conductivity specification tightening.
Distribution Channel:
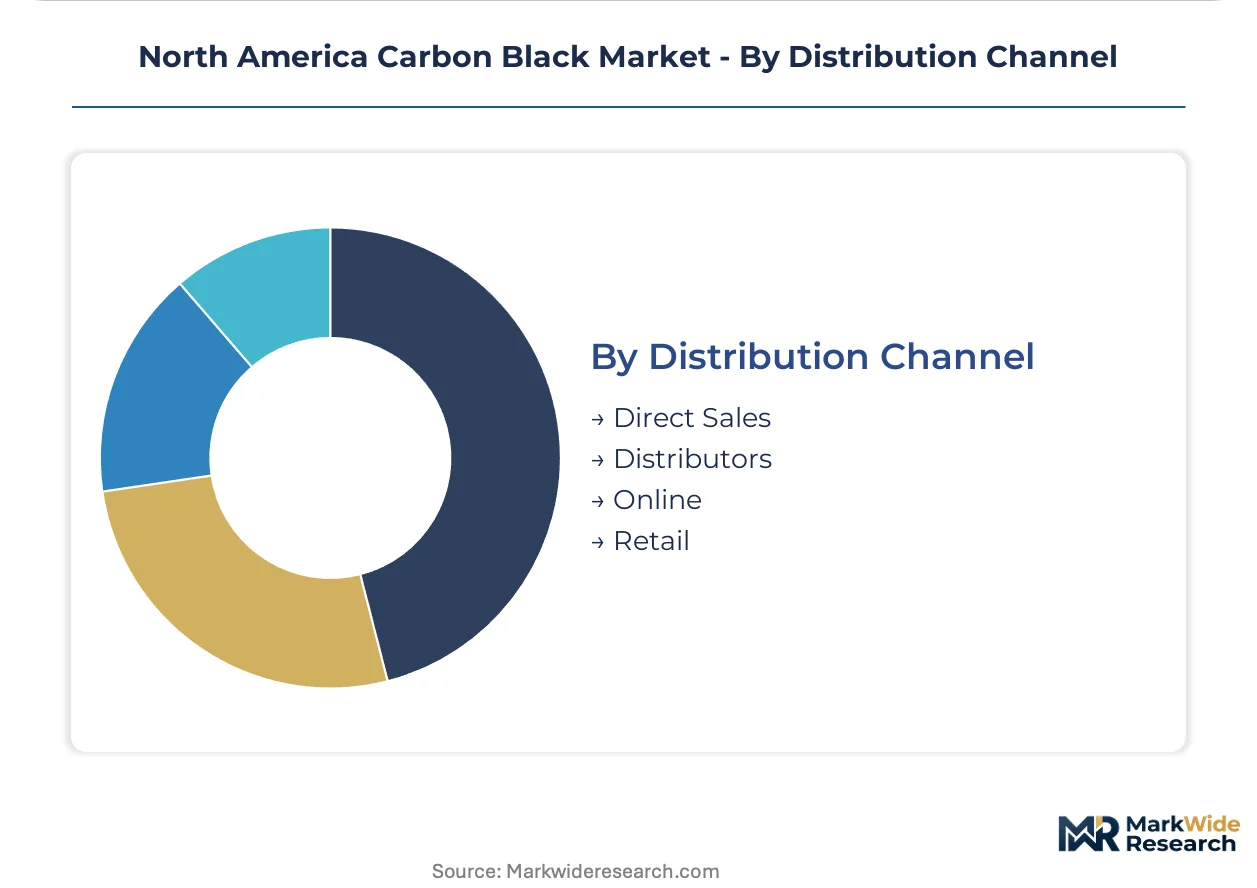
Channel structure stratifies by customer scale and technical service requirements, with direct sales capturing compounder volume and distributors serving fragmented end-users.
- Direct Sales:Captive offtake contracts link Gulf Coast producers to major tire compounders, eliminating inventory buffers. Cabot Corporation and Birla Carbon operate dedicated account teams co-located with customer technical centers.
- Distributors:Regional chemical distributors serve mid-tier rubber processors and specialty formulators lacking volume for direct mill arrangements.
- Online:Digital procurement platforms for standard grades with published specifications.
- Retail:Limited to small-volume coating and ink applications.
Direct Sales commands the largest share; momentum sits with Distributors as mid-tier compounders consolidate purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Air Act enforcement and state-level carbon accounting rules are reshaping facility investment decisions across the region. Integrated refinery corridors provide feedstock cost advantages while concentrating weather-related supply vulnerabilities. Regional demand patterns track tire manufacturing clusters and emerging EV battery compound specifications.
United States
Tire manufacturers in Tennessee, Ohio, and South Carolina are expanding carbon black procurement contracts to secure compound supply for EV production ramps. EPA emissions standards under the Clean Air Act mandate scrubber retrofits and thermal process upgrades at Gulf Coast production facilities. The US Gulf Coast petrochemical corridor from Houston to Lake Charles hosts over half of North American capacity, with integrated refineries supplying aromatic oil feedstocks.
Canada
Alberta's heavy crude upgraders offer alternative feedstock streams that could diversify supply chains beyond US Gulf Coast dependence. Environment and Climate Change Canada regulations on industrial air emissions influence facility permitting timelines and capital deployment decisions. Ontario's automotive manufacturing corridor around Windsor and Oshawa anchors specialty carbon black demand for tire and rubber component production.
Mexico
Nearshoring of tire manufacturing to northern border states is expanding carbon black consumption for export-oriented production. SEMARNAT environmental standards govern industrial emissions and workplace exposure limits at manufacturing facilities. The Querétaro and Nuevo León industrial corridors are attracting compounder investments that link to US automotive supply chains.
North America Carbon Black Market Competitive Environment
On the supply side, the industry is consolidating around integrated producers with captive refinery feedstock access and specialized compounders serving technical grade segments. Three strategic archetypes dominate: Gulf Coast-integrated volume producers, specialty grade technical specialists, and diversified chemical conglomerates with carbon black divisions. Competitive positioning depends on backward integration into feedstock supply and forward integration into direct mill contracts with tire manufacturers.
Among US-based integrated producers, Cabot Corporation and Sid Richardson Carbon & Energy Co occupy positions anchored to Gulf Coast refinery corridors. Birla Carbon represents the diversified conglomerate archetype with furnace black production networks spanning multiple regional markets. Orion Engineered Carbons exemplifies the specialty grade specialist model, focusing on non-tire applications where technical qualification barriers sustain premium positioning.
| Leading Market Players |
|---|
| Cabot Corporation |
| Birla Carbon |
| Orion Engineered Carbons |
| Continental Carbon Company |
| Tokai Carbon Co., Ltd. |
| Sid Richardson Carbon & Energy Co |
| Imerys |
| Mitsubishi Chemical Corporation |
| OMSK Carbon Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity signals across the US Gulf Coast furnace black corridor are tightening supplier discipline and amplifying pricing leverage for integrated producers with captive feedstock security. This utilization dynamic concentrates negotiating power among compounders locked into direct mill contracts while forcing spot buyers toward premium tiering.
Pricing Analysis
Volume-discount tiering separates captive offtake arrangements from spot market purchases, with tire manufacturers commanding steep escalators for guaranteed supply security. Price differentiation rests on feedstock integration depth and EPA compliance certification tiers, where scrubber-retrofitted facilities extract premiums over legacy operations. Cost compression in commodity furnace black is intensifying because silica-silane substitution threatens share in passenger tire segments. Tier 2 rubber processors lacking direct mill access exhibit highest price sensitivity, while EV tire compounders prioritize performance grades over cost optimization.
Supply Chain Analysis
Export-control regimes on refinery technology limit Gulf Coast facility upgrades, constraining capacity expansion timelines and reinforcing concentration risk. Geographic supply concentration centers on the United States, Canada, and Mexico, with over half of regional capacity clustered in hurricane-exposed Texas and Louisiana corridors. Raw material dependencies draw from aromatic oil feedstocks, creosote streams, and Alberta heavy crude upgrader outputs. Single-source vulnerability to weather-related disruptions represents the dominant structural risk. Distribution runs through direct mill integration contracts for major tire compounders, with regional distributors serving fragmented mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America carbon black market is cycling through recovery as EV tire production ramps force compound reformulations and restocking cycles. This cyclical driver justifies selective capacity positioning ahead of demand inflection.
For Market Incumbents: Pre-empt silica-silane substitution threats by accelerating specialty grade qualification programs for high-load EV tread compounds. Secure backward integration into Canadian oil sands feedstock streams to diversify beyond Gulf Coast concentration risk. Prioritize OSHA-compliant automation investments to compress facility upgrade timelines and capture regulatory-driven competitive advantage.
For New Entrants and Emerging Players: Build out conductive plastics capabilities targeting EV battery thermal management applications, where qualification barriers remain lower than tire-grade furnace black. The most penetrable segment sits in specialty masterbatch for electronics housings, with Midwest compounders actively sourcing alternative suppliers. A technical service-heavy go-to-market angle differentiates against volume-focused incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty-grade technical specialists with established automotive qualification pathways and defensible margin pools outside commodity tire applications. Long-term viability favors producers with demonstrated EPA compliance execution and feedstock flexibility across multiple crude streams. The signal to watch is EV platform standardization announcements from Detroit-area OEMs, which would trigger accelerated compound reformulation cycles and specialty grade demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive access to Alberta heavy crude upgraders reduces Gulf Coast hurricane exposure and stabilizes input costs. |
| OSHA Compliance Automation | Robotic material handling systems at Texas and Louisiana facilities compress permissible exposure limit upgrade timelines. |
| Specialty Grade Capacity Expansion | Conductive carbon black for EV battery housings opens premium positioning outside commodity tire volume competition. |
| Direct Mill Integration Contracts | Captive offtake arrangements with Tennessee and South Carolina tire manufacturers eliminate distributor margin capture. |
| Plasma-Assisted Production Piloting | Inline spectroscopy quality control at Midwest installations enables ultra-high-performance tire grade qualification. |
Study Parameters
Initial hypotheses were tested against primary input from carbon black plant managers, tire compounder procurement leads, refinery feedstock specialists, and specialty chemicals distribution channel partners and refined through secondary validation. Sources included EPA enforcement action databases, OSHA permissible exposure limit regulatory filings, US Customs aromatic oil trade data, and SEC 10-K disclosures from integrated chemical producers. Bottom-up demand modeling across tire, coatings, and plastics applications was triangulated against top-down capacity assessments from Gulf Coast facility records.
Demand-supply-balance dynamics across the analysis window were modeled through segmentation across product grade tiers, end-use industries, regional production hubs, and direct versus distributor channel structures. CAGRs were derived from compound growth trajectory fitting to historical volume flows and projected EV tire content requirements. Forecast inputs incorporated EPA Clean Air Act compliance cost assumptions and silica-silane substitution elasticity estimates from compounder formulation surveys.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Gulf Coast-integrated volume producers to accelerate specialty grade transitions would shift outcomes beyond modeled ranges. Material shifts in EPA emissions enforcement timelines or OSHA workplace standard implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Global Acrolein Market