
 Oxalic Acid Market | 2026-2036
Oxalic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Oxalic Acid Market Intelligence
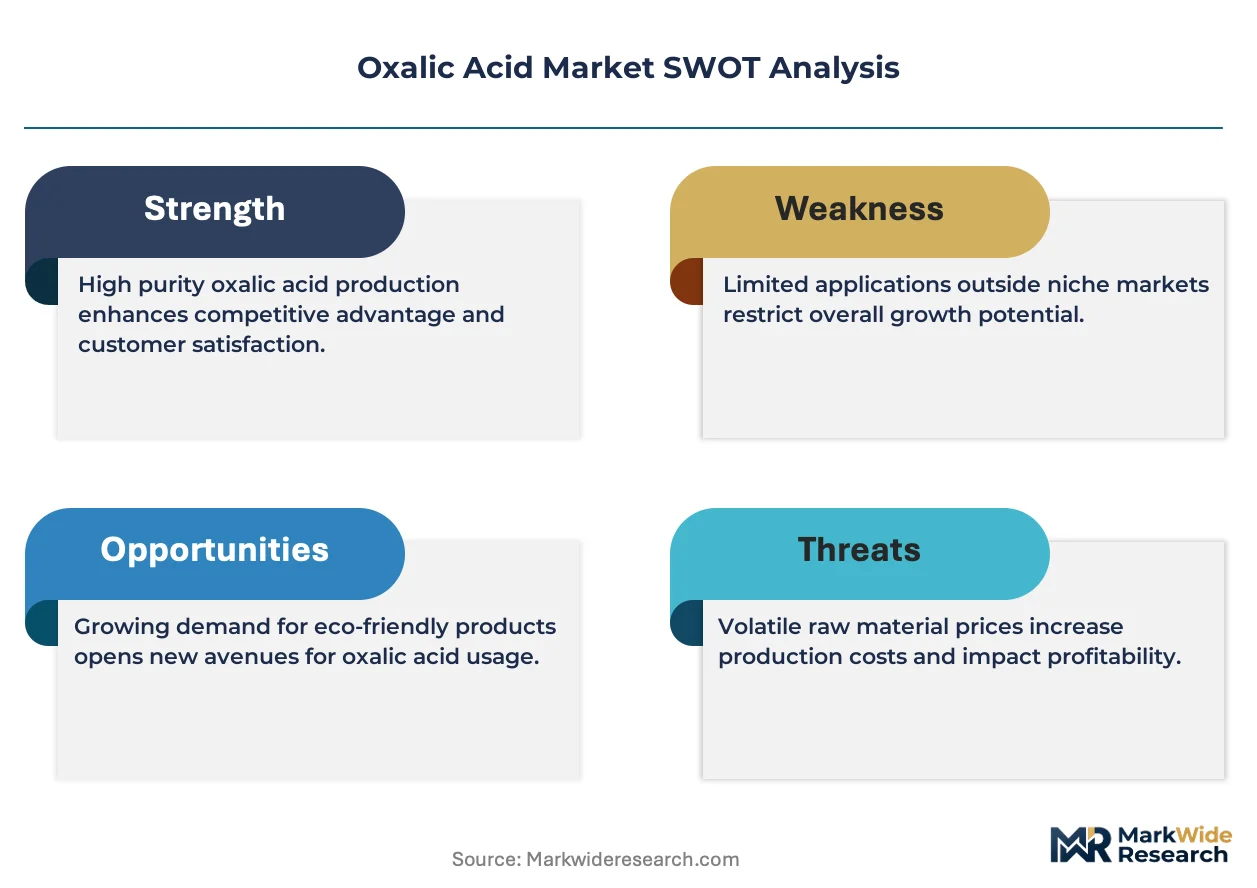
The capital investment differential between large-scale synthesis and specialized purification is unwinding the market's historical production structure. Large-scale producers like UBE Industries and Shijiazhuang Taihe Chemical operate with significant economies of scale, serving commodity-grade demand. In contrast, Clariant AG differentiates through a broad portfolio and global distribution network. Niche specialists such as Oxaquim focus on high-purity grades required by the electronics and pharmaceutical sectors.
Oxalic acid is a crystalline solid and a dicarboxylic acid with the formula C2H2O4, known for its strong acidic and reducing properties. Its primary industrial function is as a chelating agent, effectively binding with metal ions, which makes it valuable for rust removal and mineral processing. The dihydrate product form represents the bulk of commercial volume due to its stability and cost-effectiveness. While metal treatment and bleaching applications are mature segments, consumption within chemical manufacturing for synthesis is a significant value driver.
Compliance with regulations from Europe's ECHA under the REACH framework and the US EPA's TSCA dictates market access and worker safety protocols. In parallel, China's GB standards for chemical purity and the MEE's environmental mandates govern production efficiency and export quality. Future competitiveness will hinge on navigating these divergent regulatory landscapes and managing supply chain exposure to a highly concentrated production base.
Market Dynamics
The market's central dynamic is the growing divergence between bulk, commodity-grade production and the specialized, high-purity segments. This split is driven by concentrated manufacturing in China meeting price-sensitive demand, while stringent regulatory frameworks in Europe and North America create demand for certified, higher-value products.
Growth Catalysts
- Metal Treatment Expansion:Use in metal finishing and rust removal applications continues to expand, particularly within the automotive restoration and industrial maintenance sectors where its chelating properties are highly effective.
- REACH Compliance:The EU's REACH regulation mandates stringent registration and purity data for chemical imports, creating a preference for suppliers who can provide compliant, well-documented oxalic acid grades.
- Chemical Synthesis Demand:Demand from China's chemical industry for oxalic acid as a synthesis intermediate and reducing agent remains a primary volume driver, supporting large-scale production facilities.
Market Restraints
- Supply Chain Concentration:Heavy reliance on a few key production regions, notably China, exposes the global supply chain to significant geopolitical and logistical disruption risks.
- Input Cost Volatility:The cost of precursor chemicals and energy required for industrial synthesis creates price instability, which can compress margins for producers serving commodity markets.
- Regulatory Compliance Burden:The cost and complexity of adhering to multiple international standards, such as the US EPA's TSCA and Europe's ECHA requirements, act as a barrier for smaller producers.
Strategic Opportunities
- High-Purity Electronics Grade:Developing ultra-high purity oxalic acid for the semiconductor industry presents a significant value-add opportunity, serving applications in wafer cleaning and metal etching.
- Pharmaceutical Intermediates:There is an opportunity to supply certified cGMP-grade oxalic acid for use as a reagent or intermediate in the synthesis of active pharmaceutical ingredients (APIs).
- Rare Earth Element Processing:The role of oxalic acid as a precipitating agent in the extraction and purification of rare earth elements (REEs) from ore offers a new, high-growth application vector.
Industry Challenges
- Capital Investment for Purification:The significant capital expenditure required to build and operate facilities capable of producing high-purity grades for pharmaceutical or electronic use presents a major financial hurdle.
- Navigating Divergent Standards:Managing production and quality control to simultaneously meet China's GB standards for domestic markets and the stricter purity demands of export markets is a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxalic Acid Market |
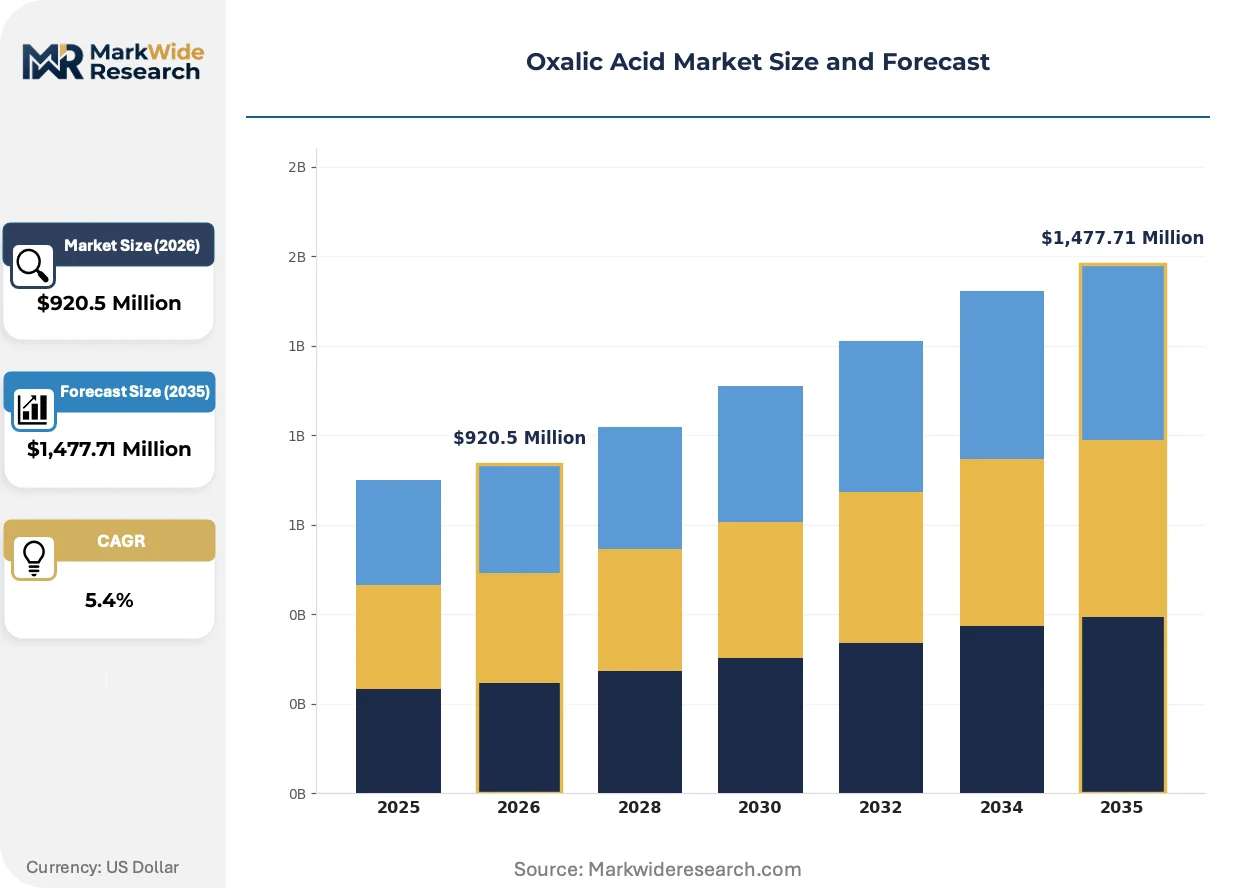
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,477.71 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Dihydrate, Anhydrous, Technical Grade Application: Cleaning Agents, Bleaching, Metal Treatment, Textile Processing, Water Treatment End Use Industry: Chemical Manufacturing, Paper Production, Metal Fabrication, Leather Processing, Electronics Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Clariant AG, Spectrum Chemical Manufacturing, Oxaquim, STAROXOCHEM Pvt Ltd, Shijiazhuang Taihe Chemical, UBE Industries, Indian Oxalate Limited, Honeywell International, Mudanjiang Fengda Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxalic Acid Market Strategic Shifts & Innovations
The market is defined by a clear bifurcation in product strategy and supply chain structure. Technology is enabling the creation of highly specialized grades, while regulatory and behavioral shifts are reshaping sourcing patterns and production economics for the entire industry.
Advanced purification technology is a key driver of value differentiation. These methods, including multi-stage crystallization and ion-exchange processes, produce ultra-high purity oxalic acid. End-users in the pharmaceutical and semiconductor industries are the primary adopters, requiring these grades for critical manufacturing steps. This advancement is fragmenting the supplier landscape into high-volume commodity producers and niche, high-margin purification specialists.
Environmental regulations from China's Ministry of Ecology and Environment (MEE) are altering production economics. These mandates require investment in cleaner synthesis routes and more effective wastewater treatment, increasing operational costs for manufacturers. Export-focused producers are most affected, as they must absorb these compliance costs while competing on the global market, impacting pricing and supply availability.
A shift toward certification-driven procurement is altering buyer behavior in technical sectors. End-users are increasingly bypassing general distributors to engage directly with manufacturers who can provide traceable, batch-specific certificates of analysis. This trend ensures material purity and consistency for sensitive applications. The practice is most visible within the electronics and specialty chemical supply chains in South Korea and Germany.
Oxalic Acid Market Segmentation
The oxalic acid market exhibits a stratified structure, reflecting diverse purity requirements and application-specific demands across various industries. Understanding these segmentations reveals where value accrues and where competitive pressures are most pronounced. This granular analysis provides clarity on market dynamics and strategic positioning.
Product Type:
Product type segmentation highlights the varying degrees of substitution pressure, with commodity grades facing competition from alternative chelating agents and organic acids.
- Dihydrate:This crystalline solid contains two water molecules per oxalic acid molecule, offering enhanced stability and ease of handling. Its widespread use in metal treatment and bleaching applications drives substantial volume demand in China's industrial sector.
- Anhydrous:Anhydrous oxalic acid is a pure form without water molecules, demanded for applications sensitive to moisture or requiring higher concentration. The electronics and pharmaceutical sectors in South Korea and Germany increasingly procure this grade for precision manufacturing.
- Monohydrate:Monohydrate oxalic acid contains one water molecule, finding use in specific chemical synthesis processes requiring precise hydration levels.
- Technical Grade:Technical grade oxalic acid is a lower purity formulation, primarily utilized in large-scale industrial cleaning and mineral processing operations.
Dihydrate anchors the volume base while Anhydrous gains share at the steepest rate, driven by specialized industry requirements.
Application:
The application segment delineates oxalic acid's functional utility, with each use case presenting distinct growth trajectories and purity requirements.
- Metal Treatment:Oxalic acid functions as a potent chelating agent in metal treatment, effectively removing rust and scale from surfaces. Its expanding use in automotive restoration and industrial maintenance sectors drives consistent demand across North America and Europe.
- Chemical Manufacturing:In chemical manufacturing, oxalic acid serves as a critical synthesis intermediate and reducing agent for various organic compounds. China's expansive chemical industry represents the primary volume driver for this application, supporting large-scale production.
- Cleaning Agents:Oxalic acid is incorporated into various cleaning formulations for its acidic and chelating properties, particularly for stain removal.
- Bleaching:As a bleaching agent, oxalic acid is employed in wood restoration and textile processing, offering effective stain lightening.
- Textile Processing:Within textile processing, oxalic acid acts as a mordant and a bleaching agent, improving dye uptake and fabric appearance.
- Water Treatment:Oxalic acid finds limited use in water treatment for removing metal ions and controlling pH in specific industrial wastewater streams.
Demand for metal treatment applications is expanding, while chemical manufacturing sustains the largest volume concentration.
End Use Industry:
End-use industry segmentation reveals the primary sectors driving oxalic acid consumption, with demand concentration varying significantly by industrial maturity and regulatory landscape.
- Chemical Manufacturing:This industry segment utilizes oxalic acid extensively as a precursor for various chemicals, including esters, oxalates, and dyes. China's vast chemical production facilities generate immense demand for commodity-grade oxalic acid.
- Electronics:The electronics industry requires ultra-high purity oxalic acid for wafer cleaning, etching, and other critical semiconductor manufacturing processes. Niche specialists cater to this high-value segment, particularly in advanced manufacturing hubs like Taiwan and Japan.
- Paper Production:In paper production, oxalic acid acts as a bleaching agent and a chelating agent to improve pulp brightness and quality.
- Metal Fabrication:Metal fabrication uses oxalic acid for surface preparation, rust removal, and pickling processes before coating or plating.
- Leather Processing:Leather processing employs oxalic acid for deliming and bleaching hides, contributing to the final texture and appearance of leather products.
Chemical manufacturing represents the largest volume segment, while the electronics industry drives significant value differentiation.
Packaging Type:
Packaging type segmentation reflects the logistical requirements and scale of operations for different end-users, influencing distribution efficiency and cost structures.
- Bulk Containers:Bulk containers, such as ISO tanks or large industrial sacks, are used for high-volume shipments to large industrial consumers. This packaging minimizes per-unit shipping costs for commodity-grade oxalic acid destined for chemical plants.
- Bags:Industrial bags, typically 25kg or 50kg, offer a balance between bulk handling and manageability for medium-scale users and distributors. This format is prevalent for metal treatment and textile processing applications across Southeast Asia.
- Drums:Drums provide a secure packaging solution for intermediate volumes, often preferred for specialty grades or where precise dispensing is required.
- Bottles:Smaller bottles are used for laboratory reagents or very specialized, high-purity applications where precise measurement and minimal contamination are critical.
Bulk containers prioritize logistical efficiency for large-scale industrial buyers, whereas bottles cater to specialized laboratory and high-purity needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the oxalic acid market, with buyers in commodity segments highly price-sensitive while specialized applications prioritize purity and certification. This fundamental split shapes regional consumption patterns and regulatory influences.
China
Demand for oxalic acid in China's chemical manufacturing sector remains a primary volume driver. The Ministry of Ecology and Environment (MEE) mandates cleaner synthesis routes, impacting production economics. Industrial clusters in the Yangtze River Delta continue to expand capacity for commodity-grade output.
Germany
Europe's technical sectors drive demand for high-purity oxalic acid, particularly for electronics and pharmaceuticals. The EU's REACH regulation requires stringent purity data, influencing procurement decisions. Chemical manufacturing hubs around Ludwigshafen emphasize specialized grades for export.
United States
Metal treatment applications, including automotive restoration, sustain consistent demand for oxalic acid across the United States. The Environmental Protection Agency (EPA) under TSCA governs chemical safety and market access. Industrial maintenance sectors in states like Texas utilize oxalic acid for surface preparation.
South Korea
The electronics industry in South Korea requires ultra-high purity anhydrous oxalic acid for semiconductor manufacturing. Certification-driven procurement patterns are prevalent, ensuring material consistency for critical processes. Advanced manufacturing clusters in Gyeonggi Province lead in adopting these specialized grades.
India
India's growing chemical industry provides a significant market for commodity-grade oxalic acid as a synthesis intermediate. The Bureau of Indian Standards (BIS) sets purity benchmarks for industrial chemicals. Manufacturing zones near Gujarat are expanding to meet domestic and regional demand.
Oxalic Acid Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the oxalic acid market. The industry bifurcates into high-volume commodity producers and niche specialists offering ultra-high purity grades. Strategic archetypes include large-scale integrated manufacturers, diversified chemical conglomerates, and focused purification providers. Capacity expansion in commodity production and targeted R&D for specialized applications represent dominant competitive moves.
At the scale-driven end, UBE Industries and Shijiazhuang Taihe Chemical exemplify large-scale synthesis capabilities, serving commodity-grade demand across global markets. Oxaquim represents a niche specialist, focusing on high-purity grades required by sensitive electronics and pharmaceutical sectors. These companies collectively illustrate the market's divergent production structures and specialized product offerings.
| Leading Market Players |
|---|
| Clariant AG |
| Spectrum Chemical Manufacturing |
| Oxaquim |
| STAROXOCHEM Pvt Ltd |
| Shijiazhuang Taihe Chemical |
| UBE Industries |
| Indian Oxalate Limited |
| Honeywell International |
| Mudanjiang Fengda Chemical |
| Others |
Cost & Logistics Intelligence
Three-month lead times for specialized anhydrous oxalic acid grades underscore the market's fractured supply chain and its impact on premium pricing power. This dynamic contrasts sharply with the longer, more volatile lead times for commodity volumes, where price sensitivity remains high.
Pricing Analysis
After-sales revenue from certified, high-purity oxalic acid grades commands premium pricing through value-based models. Pricing stratifies across purity levels, with ultra-high purity grades for electronics and pharmaceuticals fetching significantly higher prices than technical or dihydrate forms. Price differentiation stems from stringent certification requirements like REACH compliance and the specific purity grade achieved. Pricing pressure stems from input cost volatility, particularly for energy and precursor chemicals, compressing margins for commodity producers. Buyers in China's chemical manufacturing sector exhibit the highest price sensitivity for bulk volumes.
Supply Chain Analysis
Logistical chokepoints in shipping lanes from China underwrite the vulnerability of the global oxalic acid supply chain. Geographic supply concentration centers primarily in China and India, which produce the majority of commodity-grade material. The industry draws from precursor chemicals like propylene and energy inputs for industrial synthesis. Geopolitical disruption and trade policy shifts represent a significant structural risk for global availability. Distribution runs through bulk containers for large industrial consumers and specialized channels for high-purity, low-volume requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxalic acid market is undergoing a platform-economics inflection, driven by the need for certified, traceable material that creates a new ecosystem of trusted suppliers and specialized applications.
For Market Incumbents:Consolidate market share in commodity segments through further economies of scale and cost optimization. Invest in advanced purification technologies to meet the rising demand for high-purity grades, mitigating the threat from niche specialists. Secure long-term supply agreements for precursor chemicals to stabilize input costs. Leverage existing global distribution networks to offer a diversified portfolio of standard and specialized products across regions.
For New Entrants and Emerging Players:Lead with innovative purification processes to target white-space opportunities in ultra-high purity electronics and cGMP pharmaceutical intermediates. The most penetrable segment lies within advanced manufacturing hubs in South Korea and Germany, where demand for precision chemicals is acute. A direct manufacturer-to-end-user engagement model, emphasizing batch-specific certification and technical support, offers a strong go-to-market angle. Focus on developing proprietary synthesis routes that offer environmental advantages or cost efficiencies.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-driven differentiation play because increasing compliance requirements favor specialized producers. Target acquisition archetypes include niche purification specialists with proprietary technologies or established certification pathways. Look for companies with strong intellectual property in advanced synthesis or waste treatment solutions. The signal to watch is the increasing enforcement of purity standards by regulators like ECHA and the US EPA, driving demand for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Addresses growing demand from electronics and pharmaceutical sectors in South Korea. |
| Investment in Cleaner Synthesis Routes | Ensures compliance with China's MEE environmental mandates, impacting production economics. |
| Development of Rare Earth Processing Applications | Unlocks a new, high-growth application vector for oxalic acid as a precipitating agent. |
| Certification Program for Traceability | Builds trust with technical buyers in Germany and enhances market access for specialized grades. |
| Long-term Offtake Agreements with Electronics Manufacturers | Secures stable demand for anhydrous oxalic acid in critical semiconductor manufacturing. |
Research Approach
The analysis maps high-purity grades, commodity production, metal treatment, and chemical synthesis sub-sectors, each validated through extensive primary interviews with industry experts. This approach combines insights from plant managers, procurement leads at downstream OEMs, R&D directors, and regulatory compliance officers. Secondary validation draws from customs and trade data, chemical industry reports, ECHA and EPA regulatory filings, and company 10-K reports, triangulating data for both bottom-up and top-down assessments.
Consistency checks against external benchmarks ensured the robustness of the forecast framework across the analysis window. Segmentation dimensions modeled include product type, application, end-use industry, packaging type, and purity grade. Compound annual growth rates were derived from historical trends and projected demand, incorporating factors like regulatory compliance costs and precursor chemical price fluctuations as key inputs.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or major technological breakthroughs in synthesis would require recalibration. Forecasts reflect assumptions regarding market dynamics and regulatory stability. Practitioners should keep alternative scenarios live as global trade policies and environmental mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Global Anthracite Market