
 Glacial Acetic Acid Market | 2026-2036
Glacial Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Glacial Acetic Acid Market Analysis
Market Context
Pharmaceutical-grade specification tiers is bifurcating the competitive landscape as buyers enforce stricter purity thresholds for active pharmaceutical ingredient synthesis. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to sustain cost leadership across North American supply corridors. Jiangsu Sopo (Group) Co., Ltd. anchors regional supply networks through its concentrated production base in eastern China.
Glacial acetic acid is anhydrous acetic acid with purity exceeding 99.5 percent, produced primarily via methanol carbonylation or acetaldehyde oxidation, serving as a foundational reagent for vinyl acetate monomer, purified terephthalic acid, and pharmaceutical intermediates. Acetate esters segments command premium margins in coatings applications where volatile organic compound regulations tighten formulation standards. Chemical synthesis applications dominate volume offtake as downstream acetic anhydride and chloroacetic acid derivatives expand capacity.
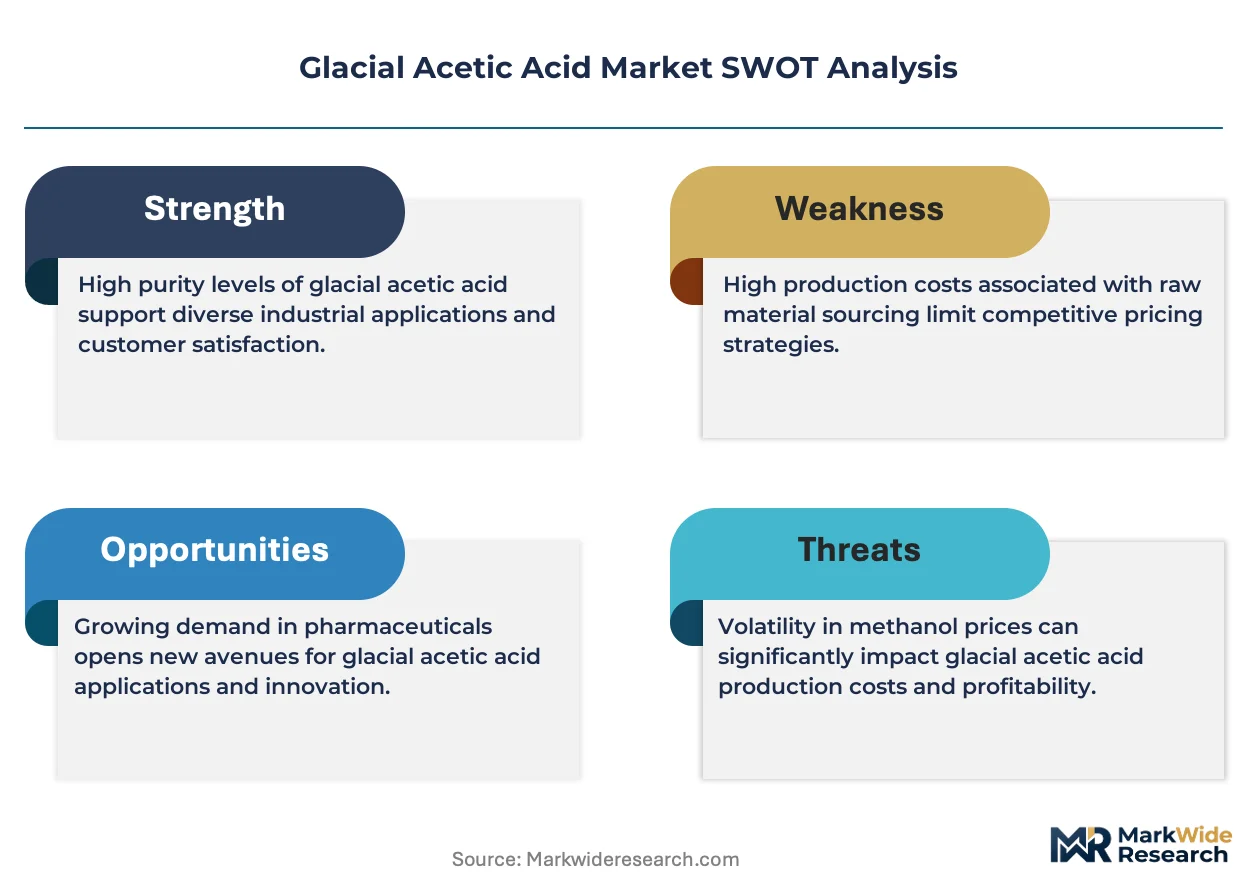
EPA standards in the United States, REACH frameworks in Europe, and China's MEE emission controls collectively elevate compliance costs for mercury-cell and older carbonylation assets. FDA cGMP requirements for pharmaceutical-grade material further segment the market between industrial and refined product tiers. Stakeholders must monitor carbon intensity disclosure rules and feedstock switching economics as methanol sourcing faces dual pressure from green hydrogen mandates and natural gas price volatility.
Market Dynamics
China's dual carbon goals and stricter MEE emission controls are forcing a wholesale reconfiguration of production methods, as mercury-cell and older carbonylation assets face accelerated obsolescence across the country's eastern manufacturing belt.
Growth Catalysts
- Pharmaceutical-grade purity mandates:FDA cGMP requirements for active pharmaceutical ingredient synthesis are pulling demand toward certified high-purity tiers, expanding the addressable market for refined product specifications.
- Vinyl acetate monomer expansion:Construction and packaging adhesives sectors in East Asian chemical manufacturing clusters are sustaining offtake volumes for acetic acid feedstock.
- Acetate esters premiumization:Volatile organic compound regulations in coatings applications are tightening formulation standards and commanding margin expansion for compliant solvent grades.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings and green hydrogen mandate pressures are destabilizing input cost structures for carbonylation-based production routes.
- Asset stranding risk in legacy corridors:Jiangsu province and Yangtze River Delta industrial clusters face concentrated exposure to MEE-mandated capacity retirements and environmental compliance upgrades.
- Mercury-cell process obsolescence:EPA standards and REACH frameworks are rendering older electrolytic assets economically unviable before full depreciation cycles complete.
Strategic Opportunities
- Biomass-derived acetic acid pathways:Bio-based feedstock technologies are opening certification-advantaged supply positions for European and North American pharmaceutical contract manufacturers.
- Purified terephthalic acid integration:Polyester value chain backward integration is creating captive demand anchors for glacial acetic acid in textile and packaging resin applications.
- Carbon intensity disclosure premiums:EU Green Deal and CSRD-aligned procurement specifications are enabling price differentiation for low-carbon-intensity production certificates.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA validation protocols for new production facilities are extending time-to-revenue for purity-tier upgrades by 18-36 months.
- Process safety expertise scarcity:Carbonylation reactor operation and methanol handling specializations are concentrating among aging workforce cohorts in established production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glacial Acetic Acid Market |
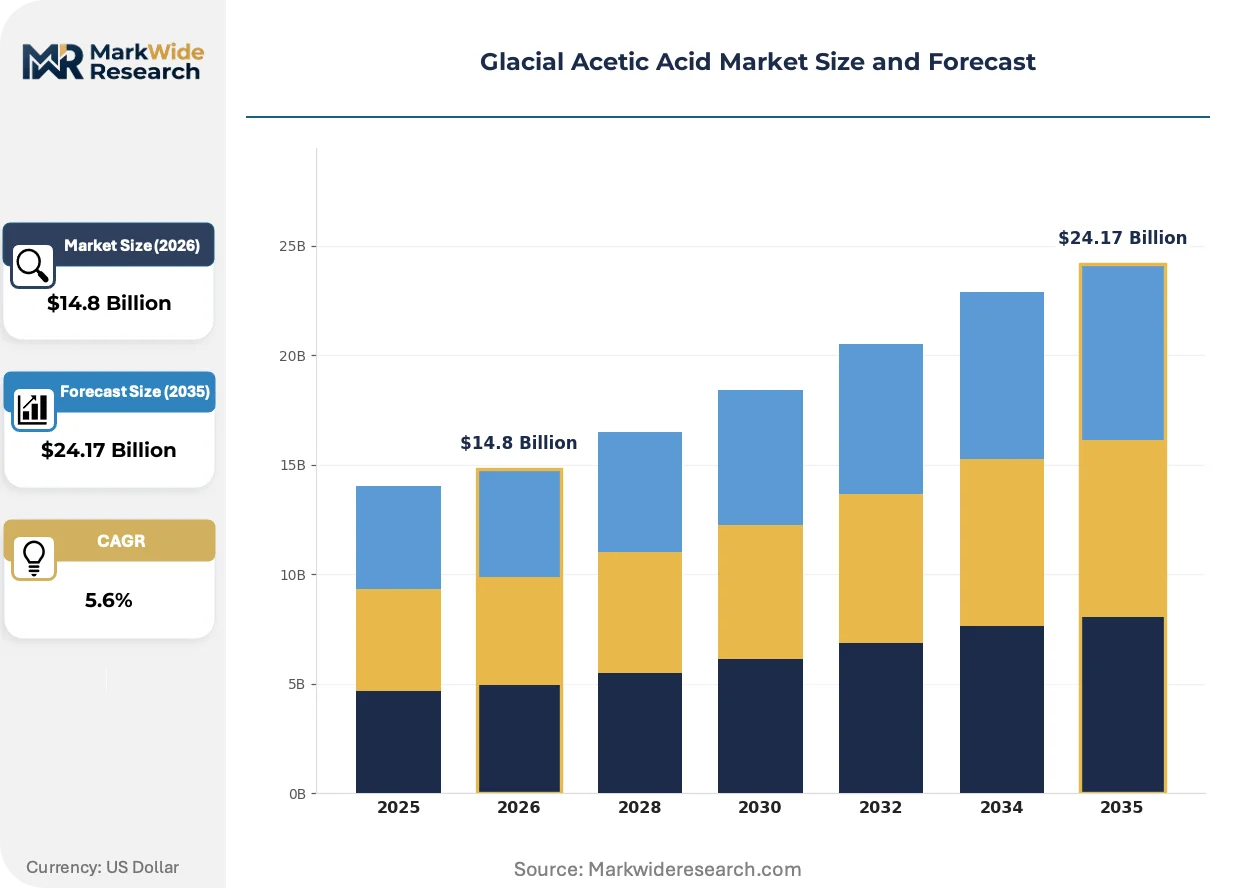
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Acetic Anhydride, Acetate Esters, Other Acetic Derivatives Application: Textile Industry, Food Additives, Chemical Synthesis, Pharmaceutical Manufacturing End User: Food Processing, Paints & Coatings, Plastics, Adhesives Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | LyondellBasell Industries Holdings B.V., INEOS, Celanese Corporation, BASF SE, Jiangsu Sopo (Group) Co., Ltd., BP p.l.c., SABIC, Mitsubishi Chemical Corporation, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glacial Acetic Acid Market Emerging Trajectories
Production technology divergence and regulatory fragmentation are splitting the competitive landscape into parallel tracks, with sustainability credentials and purity certification becoming primary sorting mechanisms for buyer segmentation.
Membrane-based acetic acid purification is fragmenting the technology base for pharmaceutical-grade production. Specialty chemical manufacturers in Switzerland and Germany are adopting electrodialysis and pervaporation systems to bypass traditional crystallization bottlenecks. This diffusion of purification approaches is fragmenting equipment supplier relationships and fragmenting process licensing markets that previously consolidated around carbonylation technology providers.
REACH authorization requirements for acetic anhydride precursors are tightening substance control frameworks across European chemical manufacturing. Downstream users in pharmaceutical intermediate synthesis are restructuring supply contracts to secure pre-authorized feedstock channels. Celanese Corporation's integrated methanol-to-acetic acid chain is capturing preferential positioning as buyers prioritize supply security over spot-market flexibility.
Specification-driven procurement is compressing supplier qualification cycles for pharmaceutical-grade material. Large molecule drug manufacturers are unbundling solvent sourcing from general chemical procurement and establishing direct relationships with purity-certified producers. This disintermediation is most visible in Massachusetts and North Carolina biopharma corridors, where FDA inspection history and batch-level traceability are becoming non-negotiable selection criteria.
Glacial Acetic Acid Market Segmentation
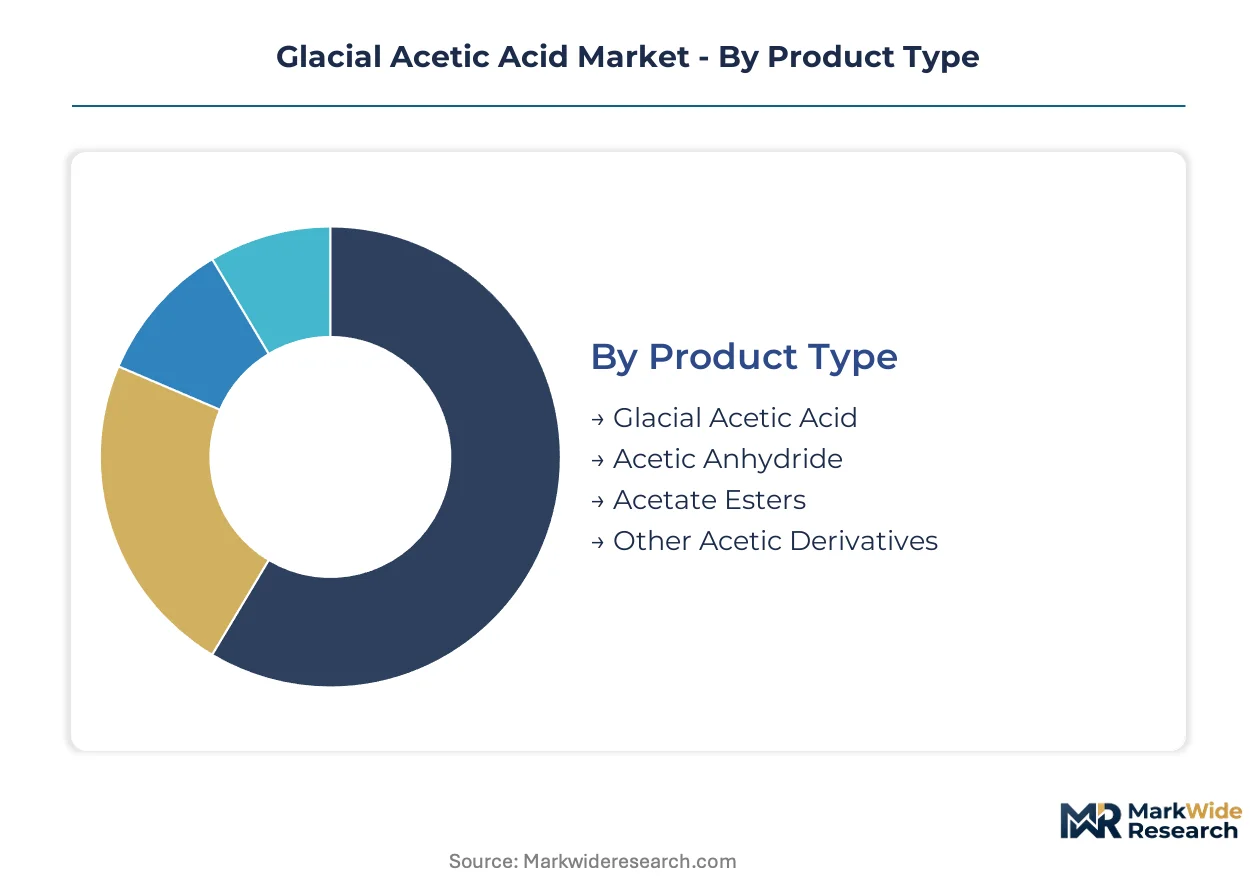
Glacial acetic acid specifications fragment across purity tiers, each carrying distinct regulatory burdens and margin profiles. Buyers in pharmaceutical corridors enforce certificate-of-analysis requirements that industrial purchasers rarely demand.
Product Type:
Domestic consumption patterns vary sharply by product tier, with commodity-grade material serving captive industrial demand while refined specifications command export premiums.
- Glacial Acetic Acid:Anhydrous acetic acid exceeding 99.5% purity serves as the foundational feedstock for vinyl acetate monomer and purified terephthalic acid synthesis. FDA cGMP-certified production in Massachusetts and North Carolina biopharma corridors is tightening supply availability for industrial-grade buyers.
- Acetic Anhydride:The dehydration derivative functions as acetylating agent in cellulose acetate and pharmaceutical intermediate manufacturing. REACH authorization requirements across European chemical manufacturing are restructuring supply contracts toward pre-authorized feedstock channels.
- Acetate Esters:Solvent grades for coatings applications face volatile organic compound regulatory pressure.
- Other Acetic Derivatives:Chloroacetic acid and specialty salts serve agrochemical and polymer additive niches.
Glacial acetic acid commands the established base. The steepest expansion runs through acetate esters.
Application:
Cost-tier stratification separates commodity chemical synthesis from premium pharmaceutical-grade certification tracks.
- Chemical Synthesis:Volume-dominant acetic anhydride and chloroacetic acid derivative production anchors capacity planning in Jiangsu province manufacturing clusters. MEE emission controls are accelerating obsolescence of mercury-cell assets before full depreciation.
- Pharmaceutical Manufacturing:Active pharmaceutical ingredient synthesis demands batch-level traceability and FDA inspection history. EMA validation protocols for new production facilities are extending facility qualification timelines.
- Textile Industry:Purified terephthalic acid integration creates captive demand in polyester value chains.
- Food Additives:Acidulant and preservative applications face FSSAI and FDA food-grade specification enforcement.
Chemical synthesis maintains volume dominance. Pharmaceutical manufacturing claims margin leadership.
End User:
Customer-type concentration favors direct procurement relationships over spot-market flexibility in high-specification tiers.
- Plastics:Vinyl acetate monomer offtake from construction and packaging adhesive sectors sustains baseline demand in East Asian chemical manufacturing corridors.
- Adhesives:Pressure-sensitive and structural adhesive formulations require consistent solvent-grade specifications.
- Paints & Coatings:Volatile organic compound regulations in coatings applications tighten formulation standards for compliant solvent grades.
- Food Processing:Acidulant applications require food-grade certification tiers distinct from industrial specifications.
Plastics anchors volume offtake. Adhesives demonstrate the sharpest specification-driven procurement shift.
Distribution Channel:
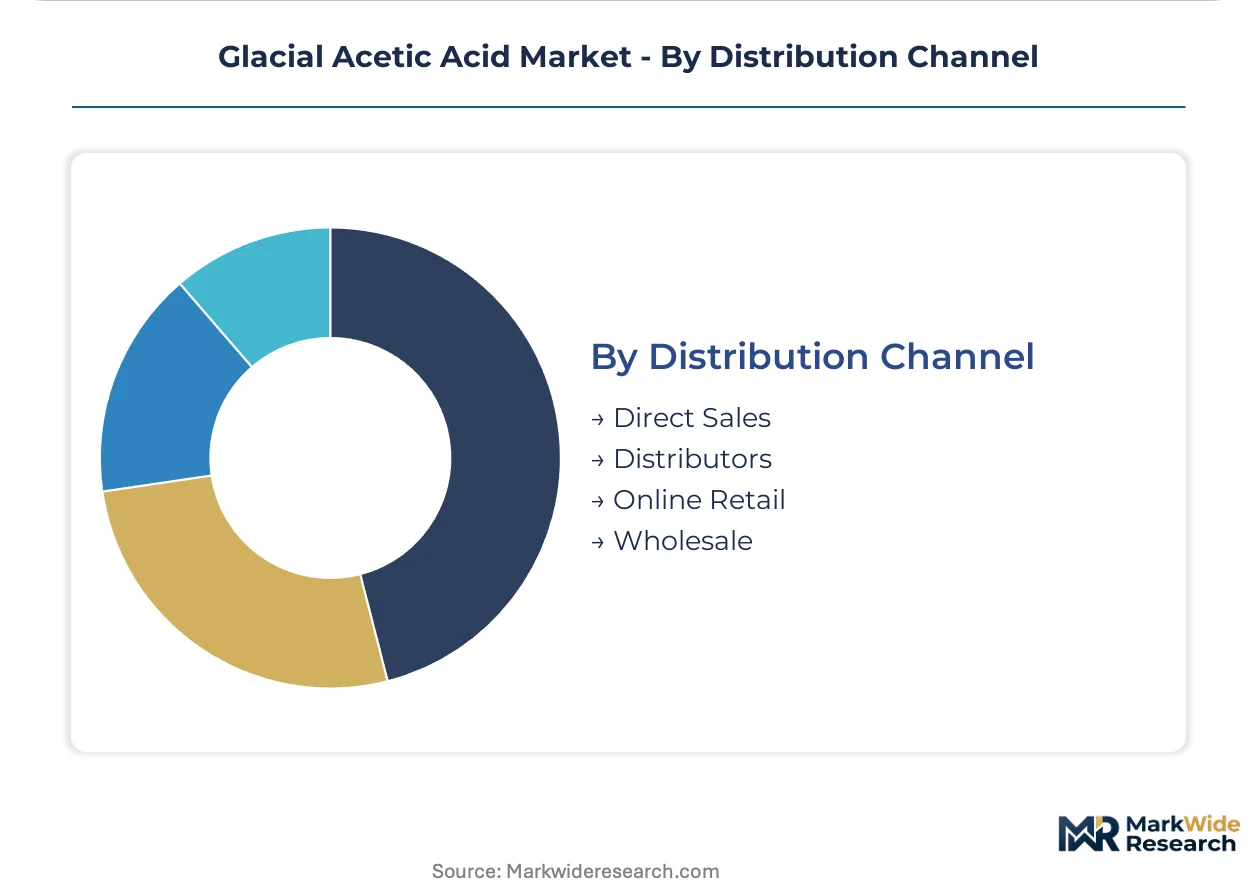
Supply concentration dictates channel selection, with bulk commodity flows favoring direct arrangements while specialty grades fragment through distributor networks.
- Direct Sales:Celanese Corporation's integrated methanol-to-acetic acid chain captures preferential positioning as buyers prioritize supply security. Long-term offtake agreements dominate pharmaceutical-grade procurement.
- Distributors:Regional supply networks through concentrated production bases serve spot-market flexibility needs for smaller industrial consumers.
- Wholesale:Commodity-grade material moves through bulk terminal and tank-car arrangements.
- Online Retail:Laboratory-scale and reagent-grade specifications serve research and quality-control applications.
Direct sales command pharmaceutical and large-volume industrial accounts. Distributors retain relevance in fragmented geographic markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbonylation capacity clusters in three distinct geographies, each shaped by feedstock access and environmental enforcement intensity. Methanol supply economics and regulatory stringency are reconfiguring investment flows across these production belts.
China
Jiangsu province and the Yangtze River Delta industrial corridor host the densest concentration of acetic acid manufacturing assets worldwide. MEE emission controls and dual carbon goals are forcing mercury-cell retirements and carbonylation technology upgrades. Zhenjiang and Nanjing chemical parks face accelerated environmental compliance timelines that compress facility modernization windows.
United States
Gulf Coast petrochemical corridors leverage integrated methanol-to-acetic acid chains serving vinyl acetate monomer and purified terephthalic acid derivatives. EPA standards elevate compliance costs for older carbonylation assets. Texas and Louisiana chemical manufacturing clusters sustain cost leadership through shale-advantaged natural gas feedstock economics.
Germany
REACH authorization requirements and ECHA substance controls are restructuring supply contracts for acetic anhydride precursors. Ludwigshafen and Marl industrial complexes anchor European pharmaceutical-grade production. CSRD-aligned procurement specifications from downstream buyers are enabling carbon intensity disclosure premiums for certified low-carbon production.
Saudi Arabia
Jubail and Yanbu industrial cities host methanol-to-derivatives complexes with strategic positioning for European and Asian export markets. SABIC-affiliated production leverages feedstock integration with regional petrochemical value chains. Domestic demand from construction adhesives and packaging sectors sustains baseline offtake volumes.
Japan
METI industrial policy and JIS standards enforce stringent purity specifications for pharmaceutical and electronics-grade applications. Chubu and Kansai manufacturing belts maintain specialized carbonylation capacity for domestic chemical synthesis demand. Aging reactor assets face replacement decisions against regional import competition.
Glacial Acetic Acid Market Vendor Landscape
Concentration sits with integrated petrochemical conglomerates and regional methanol-derivatives specialists. Three to five multinational chemical holding companies command capacity share through Gulf Coast and European production networks. Strategic archetypes split between backward-integrated methanol producers, pharmaceutical-grade purity specialists, and East Asian volume exporters. Capacity expansion and technology licensing dominate competitive moves as environmental retrofit economics reshape asset viability.
Among North American integrated producers, Celanese Corporation and Eastman Chemical Company exemplify methanol-carbonylation cost leadership through Gulf Coast supply corridors. Jiangsu Sopo (Group) Co., Ltd. anchors Chinese regional supply networks through Yangtze River Delta concentration. European diversified chemical holding companies including BASF SE and INEOS occupy positions shaped by REACH compliance and pharmaceutical-grade certification requirements.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| INEOS |
| Celanese Corporation |
| BASF SE |
| Jiangsu Sopo (Group) Co., Ltd. |
| BP p.l.c. |
| SABIC |
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
FDA cGMP certification gates both pharmaceutical-grade supply qualification and the price premiums that separate certified batches from industrial-tier material. This regulatory threshold simultaneously constrains supplier entry and enables three-tier pricing stratification across premium, standard, and economy levels in downstream procurement.
Pricing Analysis
REACH authorization dictates the pricing tier structure for acetic anhydride precursors across European chemical manufacturing. Pharmaceutical-grade certification commands substantial premiums over industrial specifications as buyers prioritize batch-level traceability and FDA inspection history. Cost compression in commodity-grade tiers intensifies because MEE-mandated environmental upgrades in China's eastern manufacturing belt are elevating baseline production costs. Large-volume industrial consumers exhibit the sharpest price sensitivity, while biopharma contract manufacturers prioritize supply security over spot-market flexibility.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability fluctuations are elevating inbound logistics costs for methanol feedstock deliveries to carbonylation facilities. Manufacturing gravity centers on China, the United States, and Germany, with Jiangsu province and the Yangtze River Delta hosting the densest asset concentration worldwide. Production draws from methanol, carbon monoxide, and catalyst inputs, with feedstock sourcing resting on regional natural gas economics and green hydrogen mandate pressures. Single-source vulnerability concentrates around legacy mercury-cell assets facing accelerated obsolescence. Distribution runs through direct long-term offtake agreements for pharmaceutical-grade tiers and bulk terminal arrangements for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based purification technologies are disrupting pharmaceutical-grade production economics, creating asymmetric opportunities for technology adopters versus carbonylation incumbents.
For Market Incumbents: Fortify cost leadership in Gulf Coast supply corridors through backward integration into shale-advantaged methanol production. Accelerate environmental retrofit timelines for Jiangsu province assets before MEE compliance windows compress. Prioritize FDA cGMP certification investments to defend margin position against specialty chemical manufacturers adopting electrodialysis systems in Switzerland and Germany. For New Entrants and Emerging Players: Anchor in biomass-derived acetic acid pathways to capture EU Green Deal procurement premiums from European pharmaceutical contract manufacturers. Target acetate esters solvent grades for coatings applications where volatile organic compound regulations are tightening formulation standards. Pursue direct qualification relationships with Massachusetts and North Carolina biopharma corridors rather than distributor-mediated market entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade purification technology upgrades as membrane-based systems displace traditional crystallization assets. Favor acquisition targets with pre-authorized REACH feedstock channels and established FDA inspection histories over greenfield certification plays. Monitor carbon intensity disclosure rule adoption as the signal to watch for low-carbon production certificate premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Celanese Corporation's methanol-to-acetic acid chain captures Gulf Coast feedstock cost advantages. |
| Green Manufacturing Transition | Biomass-derived pathways open certification-advantaged supply positions for European pharmaceutical buyers. |
| Long-term Supply Agreement | Direct offtake contracts dominate pharmaceutical-grade procurement, displacing spot-market flexibility. |
| Capacity Expansion | Jiangsu Sopo anchors regional supply networks through concentrated Yangtze River Delta production bases. |
| Joint Venture | SABIC-affiliated complexes in Jubail leverage feedstock integration with regional petrochemical value chains. |
Methodological Framework
The analysis maps carbonylation technology tiers, acetate esters solvent grades, and pharmaceutical-grade purity specifications, each validated through plant managers, procurement leads at downstream OEMs, and technical R&D directors. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings established production capacity and offtake patterns. Bottom-up facility-level modeling and top-down demand aggregation were triangulated to cross-verify volume estimates.
Consistency checks against external benchmarks validated output robustness across the projection horizon. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs were derived from fitted growth curves incorporating methanol feedstock cost trajectories, environmental compliance investment cycles, and pharmaceutical-grade certification adoption rates as industry-specific inputs.
Material uncertainties — feedstock price volatility, regulatory enforcement intensity variations, and technology substitution pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about carbonylation capacity retention and pharmaceutical-grade demand elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Feed Acidifiers Market
Additives
Anti-Pollution Ingredients Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Automotive Coolant Additives Market
Additives
Sodium Potassium Tartrate Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Organic Friction Modifier Additives Market
Additives
Organic Dispersants Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Nucleating and Clarifying Agents Market
Additives
Hydroxyethyl Cellulose Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Packaging Coating Additives Market
Additives
Global Silica-Based Matting Agents Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Middle East Feed Additives Market