
 Tertiary Butylhydroquinone Market | 2026-2036
Tertiary Butylhydroquinone Market Size, Share, and Industry Trends Forecast 2026-2036
Tertiary Butylhydroquinone Market Outlook
The capital-intensity divergence between integrated phenol derivative producers and standalone antioxidant specialists is bifurcating competitive returns in TBHQ manufacturing. Eastman Chemical Company leverages backward integration into petrochemical feedstocks to sustain margin stability across cyclical raw material swings. Camlin Fine Sciences anchors its position through concentrated R&D spending on high-purity grades for regulated food and pharmaceutical channels.
Tertiary butylhydroquinone is a synthetic phenolic antioxidant with the molecular formula C₁₀H₁₄O₂, manufactured through alkylation of hydroquinone with isobutylene and used primarily to inhibit lipid oxidation in oils, fats, and polymer systems. Food Grade TBHQ commands the largest volume share as processors seek shelf-life extension for fried and baked goods, while Pharmaceutical Grade generates superior margin pools due to stringent USP and EP certification requirements. Plastic Additives application growth tracks polyolefin production expansion, with antioxidant masterbatch formulators driving specification tightening for high-temperature processing environments.
REACH registration obligations in Europe and FDA food additive regulations under CFR 21 Part 172 govern TBHQ purity, residual solvent limits, and migration thresholds in food contact materials. China's NMPA and GB standards for food additives impose additional testing protocols that foreign suppliers must navigate for market access. Stakeholders should monitor evolving EFSA re-evaluations of phenolic antioxidant safety profiles and assess qualification timelines for emerging pharmaceutical excipient applications before committing capacity expansion decisions.
Market Dynamics
Integrated phenol derivative producers are leveraging backward integration into petrochemical feedstocks to compress cost structures and widen margin spreads against standalone antioxidant specialists. This structural divergence is concentrating competitive returns among feedstock-anchored players while forcing specialty manufacturers toward high-purity certification tiers.
Growth Catalysts
- REACH Registration Obligations:Tightening purity thresholds under ECHA oversight are disqualifying marginal suppliers and consolidating volume among qualified producers capable of meeting residual solvent limits.
- China Domestic Food Processing:Scaling packaged goods capacity and import substitution policies are accelerating local TBHQ production to serve frying oil and baked goods preservation demand.
- Polyolefin Production Expansion:Antioxidant masterbatch formulators are tightening specifications for high-temperature processing environments in plastic additives applications.
Market Restraints
- Hydroquinone Feedstock Volatility:Cyclical swings in benzene-derived phenol pricing transmit directly to TBHQ manufacturing economics, compressing margins during upstream cost spikes.
- EFSA Re-evaluation Risk:Pending safety profile assessments for phenolic antioxidants threaten regulatory status in European food contact applications.
- Natural Antioxidant Substitution:Rosemary extract and tocopherol blends are capturing clean-label positioning in premium food segments.
Strategic Opportunities
- Pharmaceutical Excipient Certification:USP and EP compliance pathways for high-purity TBHQ grades open margin pools in drug formulation applications.
- India Processed Food Sector:FSSAI-mandated shelf-life standards for edible oils are driving antioxidant adoption among domestic refiners.
- Continuous Flow Alkylation:Process intensification technology convergence with isobutylene recovery systems is reducing solvent waste and batch cycle times.
Industry Challenges
- Cross-Contamination Controls:Food-grade and technical-grade production lines require segregated equipment and validated cleaning protocols to prevent pharmaceutical channel disqualification.
- Analytical Method Harmonization:Divergent testing protocols between FDA, NMPA, and EFSA create redundant qualification timelines and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tertiary Butylhydroquinone Market |
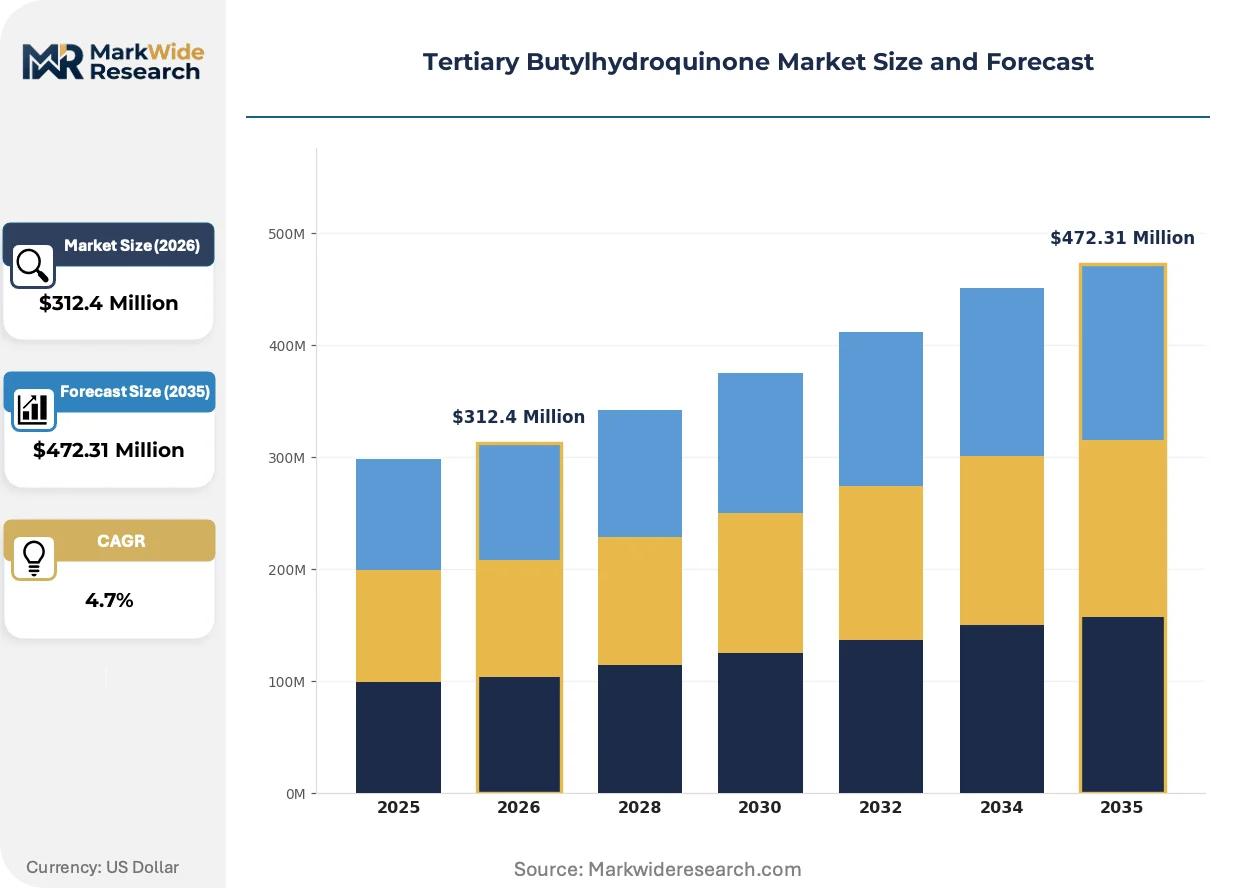
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharamaceutical Grade, Cosmetic Grade Application: Food Preservation, Plastic Additives, Cosmetics Manufacturing, Pharmaceutical Formulations End User: Food Industry, Cosmetic Manufacturers, Pharmaceutical Companies, Chemical Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Eastman Chemical Company, Camlin Fine Sciences Ltd., Solvay SA, Merck KGaA, Lanxess AG, Crystal Quinone, Milestone Preservatives, Nova International, Yasho Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tertiary Butylhydroquinone Market Strategic Shifts
Process intensification and regulatory harmonization pressures are converging to reshape manufacturing footprints and specification hierarchies across TBHQ supply chains. These forces are compressing legacy batch economics while elevating certified-grade premiums.
Continuous flow reactor technology is decomposing traditional batch alkylation economics by enabling tighter temperature control and reduced solvent inventory. Polymer masterbatch formulators in Germany and Japan are piloting these systems to meet REACH-mandated residual limits. The technology is decomposing cost advantages previously held by high-volume batch producers in China.
EFSA's pending re-evaluation of phenolic antioxidant safety profiles is tightening toxicological data requirements for food contact authorizations. Manufacturers must submit extended migration studies and metabolism data to maintain European market access. Food-grade TBHQ suppliers with existing EFSA dossiers are accelerating certification renewals ahead of deadline compression.
Refined oil processors are consolidating procurement around qualified antioxidant suppliers capable of dual food-grade and pharmaceutical-grade production. This specification stacking is displacing spot-market purchasing in favor of multi-year offtake agreements with audit rights. The shift is most visible in Chinese state-owned refinery tenders requiring NMPA and FDA dual certification.
Tertiary Butylhydroquinone Market Segmentation
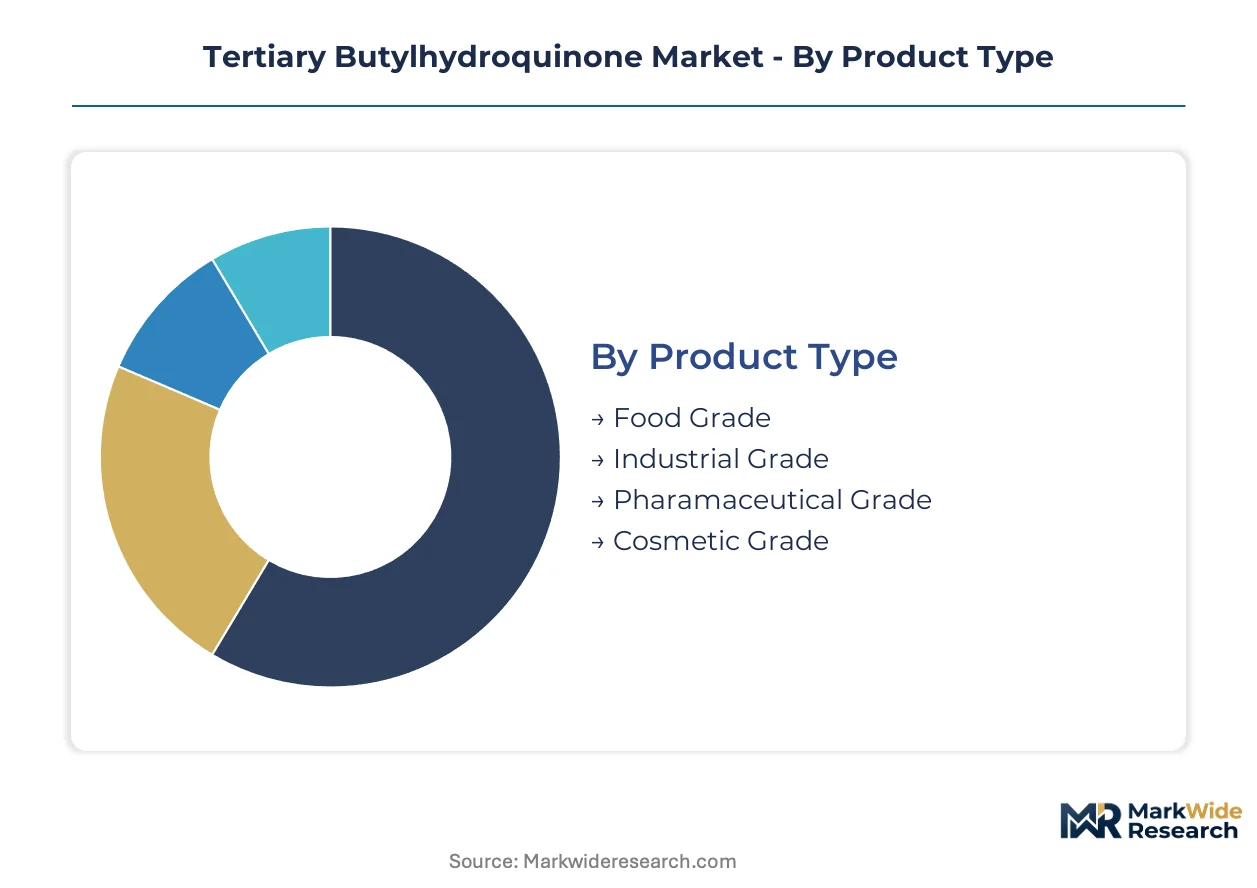
TBHQ procurement patterns diverge sharply across grade specifications, with regulatory thresholds determining supplier qualification tiers and pricing stratification. Food-grade volumes dominate transaction frequency, while pharmaceutical-grade certifications command structural premiums through USP and EP compliance burdens.
Product Type:
FDA, EFSA, and NMPA purity mandates create tiered entry barriers that segment manufacturers by analytical capability and validation infrastructure.
- Food Grade:Synthetic phenolic antioxidant meeting FDA 21 CFR 172.185 and GB 26403 residual solvent limits for edible oil preservation. Chinese state-owned refiners concentrate procurement around dual-certified suppliers capable of NMPA and FDA documentation packages.
- Pharmaceutical Grade:High-purity TBHQ conforming to USP-NF and EP monographs for drug formulation excipient use. European contract manufacturers drive specification tightening ahead of EFSA re-evaluation deadlines.
- Industrial Grade:Technical antioxidant for polymer stabilization with relaxed purity tolerances.
- Cosmetic Grade:Refined antioxidant meeting cosmetic directive stability requirements for personal care formulations.
Food Grade handles the majority of throughput; Pharmaceutical Grade is the fastest mover on share.
Application:
End-use thermal stress profiles dictate antioxidant loading rates and formulation compatibility requirements across divergent processing environments.
- Food Preservation:Lipid oxidation inhibition for frying oils, baked goods, and snack coatings under high-temperature processing. India's FSSAI-mandated shelf-life standards are accelerating refiner adoption among domestic edible oil processors.
- Plastic Additives:Polyolefin stabilization during extrusion and injection molding above 200°C. Antioxidant masterbatch formulators in Germany and Japan are tightening residual limits to meet REACH registration obligations.
- Cosmetics Manufacturing:Rancidity prevention in lipid-based emulsions and anhydrous formulations.
- Pharmaceutical Formulations:API stability enhancement and oxidative degradation control in solid dosage forms.
Food Preservation anchors volume absorption; Plastic Additives is expanding most quickly on specification intensity.
End User:
Customer scale and audit sophistication determine contract structure, with multinational food manufacturers imposing supplier qualification protocols that exclude regional producers.
- Food Industry:Packaged goods manufacturers and edible oil refiners requiring batch-level COA documentation and third-party audit rights. Chinese frying oil processors are consolidating procurement around qualified domestic suppliers under import substitution policies.
- Pharmaceutical Companies:Drug developers seeking excipient DMF filings and ICH Q3C residual solvent compliance. European formulation houses are accelerating dual USP-EP certification requirements ahead of regulatory harmonization pressures.
- Cosmetic Manufacturers:Personal care formulators prioritizing oxidative stability in natural oil bases.
- Chemical Producers:Polymer compounders and antioxidant masterbatch specialists serving automotive and packaging value chains.
Food Industry commands the dominant share of offtake; Pharmaceutical Companies is climbing the fastest on margin capture.
Distribution Channel:
Channel selection correlates with customer technical capability and volume scale, with qualified-grade procurement favoring direct manufacturer relationships over intermediary structures.
- Direct Sales:Manufacturer-to-manufacturer contracts with embedded technical service and formulation support. Major food processors in China and India are migrating toward multi-year offtake agreements with audit provisions.
- Distributors:Regional stocking intermediaries serving mid-scale compounders and toll manufacturers with fragmented geographic footprints.
- Wholesalers:Volume aggregation for technical-grade applications with standardized specifications and limited documentation requirements.
- Online Retail:E-procurement platforms for small-lot sampling and research-grade quantities.
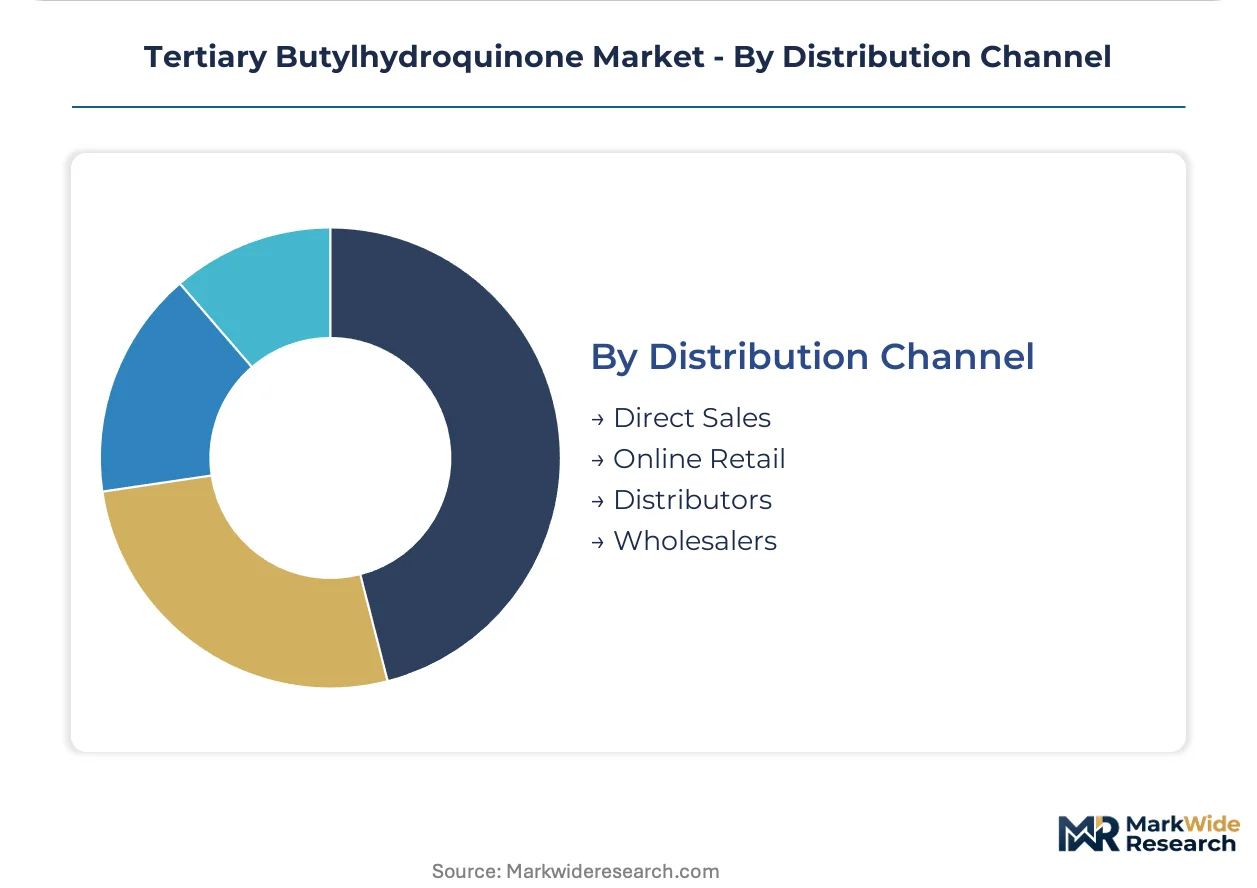
Direct Sales manages the bulk of qualified-grade volume; Distributors is gaining share fastest on geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese TBHQ manufacturers now exceed domestic consumption, reversing a decade of import dependency as domestic phenol derivative capacity expands. European buyers increasingly source from qualified Asian suppliers to manage REACH compliance costs. Import substitution policies in India and Brazil are accelerating local production investments.
China
State-owned edible oil refiners in Shandong and Jiangsu provinces are consolidating procurement around NMPA-certified domestic suppliers under import substitution mandates. GB 26403 food additive standards now require batch-level residual solvent documentation previously demanded only for export shipments. The Yangtze River Delta antioxidant cluster around Nanjing is capturing masterbatch formulator demand from Japanese polymer compounders seeking dual-certified supply.
United States
FDA 21 CFR 172.185 compliance remains mandatory for frying oil processors, with third-party audit rights now standard in multi-year offtake agreements. The Gulf Coast petrochemical corridor leverages captive hydroquinone supply to serve antioxidant demand from Mexican maquiladora polymer operations. Chicago-based packaged goods manufacturers are qualifying secondary suppliers to mitigate concentration risk in food-grade TBHQ procurement.
Germany
REACH registration obligations under ECHA oversight are disqualifying non-EU suppliers lacking extended toxicological dossiers for food contact applications. The Ruhr industrial basin hosts antioxidant masterbatch formulators tightening residual limits ahead of EFSA re-evaluation deadlines. Bavarian pharmaceutical contract manufacturers are accelerating dual USP-EP certification requirements for excipient-grade TBHQ in solid dosage formulations.
India
FSSAI-mandated shelf-life standards for refined edible oils are driving antioxidant adoption among domestic refiners in Gujarat and Maharashtra. Import duties on Chinese TBHQ have prompted Mumbai-based distributors to qualify local toll manufacturers for technical-grade supply. The Maharashtra industrial corridor is attracting phenol derivative investments targeting both food preservation and polymer stabilization demand.
Brazil
ANVISA food additive regulations are converging with Mercosur standards, creating qualification pathways for Argentine and Uruguayan suppliers into Brazilian packaged goods channels. São Paulo-state polymer compounders serving flexible packaging demand are importing antioxidant masterbatches with embedded TBHQ from German formulators. Domestic production incentives under the Plano Brasil Maior are supporting local alkylation capacity for technical-grade supply.
Tertiary Butylhydroquinone Market Competitive Environment
Concentration sits with integrated petrochemical producers possessing captive hydroquinone supply and validated multi-grade production lines. The supplier base separates into three archetypes: backward-integrated phenol derivative majors, high-purity certification specialists, and regional toll manufacturers serving technical-grade demand. Competitive positioning hardens around dual food-pharmaceutical certification capabilities and continuous flow process technology. Capacity expansion and strategic partnerships dominate competitive moves as players secure long-term offtake with state-owned refiners.
Within the integrated major tier, Eastman Chemical Company and Solvay SA exemplify feedstock-anchored positioning through phenol derivative integration. Camlin Fine Sciences Ltd. occupies the high-purity specialist archetype with concentrated R&D infrastructure for regulated channel qualification. These three entities collectively represent the certification-capable supply base that multinational food and pharmaceutical manufacturers require for audit-compliant procurement.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Camlin Fine Sciences Ltd. |
| Solvay SA |
| Merck KGaA |
| Lanxess AG |
| Crystal Quinone |
| Milestone Preservatives |
| Nova International |
| Yasho Industries |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR 172.185 certification tiers simultaneously gate supplier qualification and stratify price premiums, compressing spot-market participation while elevating contract-based offtake premiums for dual-certified producers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical-grade USP-EP certifications commanding substantial premiums over technical-grade polymer additives. Price differentiation rests on residual solvent documentation depth and batch-level COA granularity, with Chinese state-owned refiners least sensitive due to import substitution mandates while mid-scale toll manufacturers face acute cost compression from hydroquinone feedstock volatility.
Supply Chain Analysis
Just-in-time inventory preferences dominate among German and Japanese antioxidant masterbatch formulators seeking REACH-mandated residual limits, while Chinese producers maintain strategic stockpiles of isobutylene to buffer alkylation cycle disruptions. Geographic supply concentrates in China, India, and Germany, with raw material dependencies on benzene-derived phenol, isobutylene feedstock, and specialized hydrogenation catalysts. Tariff exposure on Chinese-origin food-grade shipments into India and Brazil is forcing qualification of secondary toll manufacturers. Distribution runs through direct manufacturer contracts with embedded technical service for qualified grades, while regional distributors handle technical-grade fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow alkylation technology convergence with EFSA re-evaluation deadlines is accelerating supplier consolidation, compressing legacy batch economics while rewarding certification-capable producers with structural margin capture.
For Market Incumbents: Secure captive hydroquinone supply through backward integration or long-term offtake agreements to defend against feedstock volatility squeezing standalone antioxidant specialists. Accelerate dual USP-EP certification renewals ahead of EFSA deadline compression to disqualify marginal competitors from pharmaceutical excipient channels.
For New Entrants and Emerging Players: Lead with continuous flow reactor deployments targeting REACH-mandated residual limits for German and Japanese polymer masterbatch formulators underserved by high-volume Chinese batch producers. Target India's FSSAI-mandated edible oil shelf-life standards through toll manufacturing partnerships with Gujarat-based refiners seeking import substitution from Chinese supply.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with orphaned TBHQ lines lacking pharmaceutical-grade certification infrastructure, presenting consolidation opportunities for specialty antioxidant platforms. Watch EFSA re-evaluation outcomes as the inflection signal determining whether phenolic antioxidant exposure limits trigger forced reformulation demand or sustain incumbent certification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | REACH-mandated residual solvent limits favor German and Japanese adopters over Chinese batch producers. |
| Dual USP-EP Certification Investment | Bavarian pharmaceutical contract manufacturers accelerate requirements ahead of EFSA re-evaluation deadlines. |
| Backward Integration into Phenol Feedstock | Gulf Coast petrochemical corridor leverages captive hydroquinone to serve Mexican maquiladora polymer demand. |
| Long-term Offtake Agreement Structuring | Chinese state-owned refiners consolidate procurement around qualified suppliers with NMPA-FDA dual documentation. |
| India Toll Manufacturing Partnership | FSSAI-mandated shelf-life standards drive Gujarat refiner adoption away from direct Chinese import dependency. |
Study Parameters
A standing panel of antioxidant plant managers, edible oil procurement leads at state-owned refiners, polymer masterbatch formulators, and pharmaceutical excipient quality directors provided ongoing calibration across primary interview cycles, validated against customs/trade data, SEC 10-K chemical segment disclosures, NMPA food additive registration databases, and EFSA food contact material opinions. Bottom-up volume triangulation from grade-specific production capacity was cross-checked against top-down demand aggregation from end-use consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning grade tier, end-use industry, regional production hub, and certification requirement cluster. CAGRs were derived from fitted growth curves incorporating hydroquinone feedstock cost trajectories, REACH registration obligation timelines, and import substitution policy intensity in target geographies.
Underlying assumptions cover regulatory deadline adherence, feedstock cost pass-through elasticity, and certification maintenance rates, with deviation risk concentrated in EFSA re-evaluation outcomes and benzene derivative pricing volatility. Revision becomes warranted when phenolic antioxidant safety profile assessments cross threshold restrictions forcing reformulation demand destruction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Sorbic Acid Market