
 Calcium Bromide Market | 2026-2036
Calcium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Bromide Market Analysis
The EU Green Deal's chemical sustainability criteria is rebalancing procurement priorities for bromide derivatives across European oilfield service buyers. LANXESS leverages its integrated bromine asset base in Germany to sustain supply security for pharmaceutical-grade output. ICL anchors its position through Dead Sea brine extraction, while TETRA Technologies, Inc. competes in North American drilling fluid formulations with specialized clear brine solutions. Albemarle Corporation differentiates through its lithium-bromine co-production economics in Arkansas.
Calcium bromide is a hygroscopic salt with the formula CaBr₂, typically produced at 52-96% aqueous concentration through the reaction of hydrobromic acid with calcium oxide or calcium carbonate; it functions primarily as a dense, solids-free brine for oil well completion and workover operations. Industrial grade formulations dominate volume consumption in drilling fluid applications where density requirements of 11.7-15.1 ppg drive formulation choices. Pharmaceutical grade commands premium positioning amid tightening pharmacopeial standards, while flame retardant applications in textile and polymer systems represent a structurally growing segment as halogenated fire safety regulations tighten in construction and electronics.
EPA underground injection control regulations and OSHA workplace exposure limits govern U.S. handling and disposal protocols for calcium bromide in oilfield environments, while China's SAMR enforces GB standards on industrial bromide purity and labeling. REACH registration requirements in Europe constrain market access for non-compliant importers, creating compliance cost barriers that favor established producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving PFAS substitution trends that could displace certain brominated flame retardant applications, requiring portfolio repositioning toward drilling fluid and pharmaceutical end uses where substitution economics remain less favorable for alternatives.
Market Dynamics
Upstream oilfield service consolidation around Permian Basin and Middle Eastern drilling programs is compressing formulation specifications toward higher-density, solids-free brine systems. This concentration is forcing calcium bromide producers to align purification investments with operator-specific density and clarity requirements.
Growth Catalysts
- Clear Brine Completion Fluids:Oil and gas operators in Saudi Arabia's upstream sector specify calcium bromide for density requirements of 14.2-15.1 ppg in high-pressure formations.
- EU Green Deal Chemical Sustainability:European oilfield service buyers are rebalancing procurement priorities toward bromide derivatives with verified lifecycle credentials.
- Flame Retardant Mandates:Construction and electronics sectors face tightening halogenated fire safety regulations that expand addressable demand for brominated polymer additives.
Market Restraints
- Bromine Feedstock Concentration:Dead Sea extraction and Arkansas brine operations control the majority of elemental bromine supply, creating geographic vulnerability.
- PFAS Substitution Risk:Regulatory pressure on per- and polyfluoroalkyl substances is spilling into adjacent halogenated chemistries, threatening certain polymer additive applications.
- Pharmaceutical Grade Purity Costs:GB standards from China's SAMR and tightening pharmacopeial specifications require capital-intensive purification infrastructure.
Strategic Opportunities
- Pharmaceutical Grade Expansion:Tightening pharmacopeial standards in sterile manufacturing and parenteral formulations create premium positioning for compliant producers.
- Co-Production Economics:Lithium-bromine extraction from Arkansas brine fields offers integrated margin structures unavailable to standalone bromide producers.
- REACH Registration Barriers:European chemical registration requirements constrain non-compliant importers, favoring established producers with dedicated regulatory affairs capacity.
Industry Challenges
- Underground Injection Control Compliance:EPA disposal protocols for oilfield brines require specialized handling infrastructure and real-time monitoring systems.
- Cross-Grade Contamination Risk:Industrial and pharmaceutical production lines demand segregated equipment and validation protocols that extend batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Bromide Market |
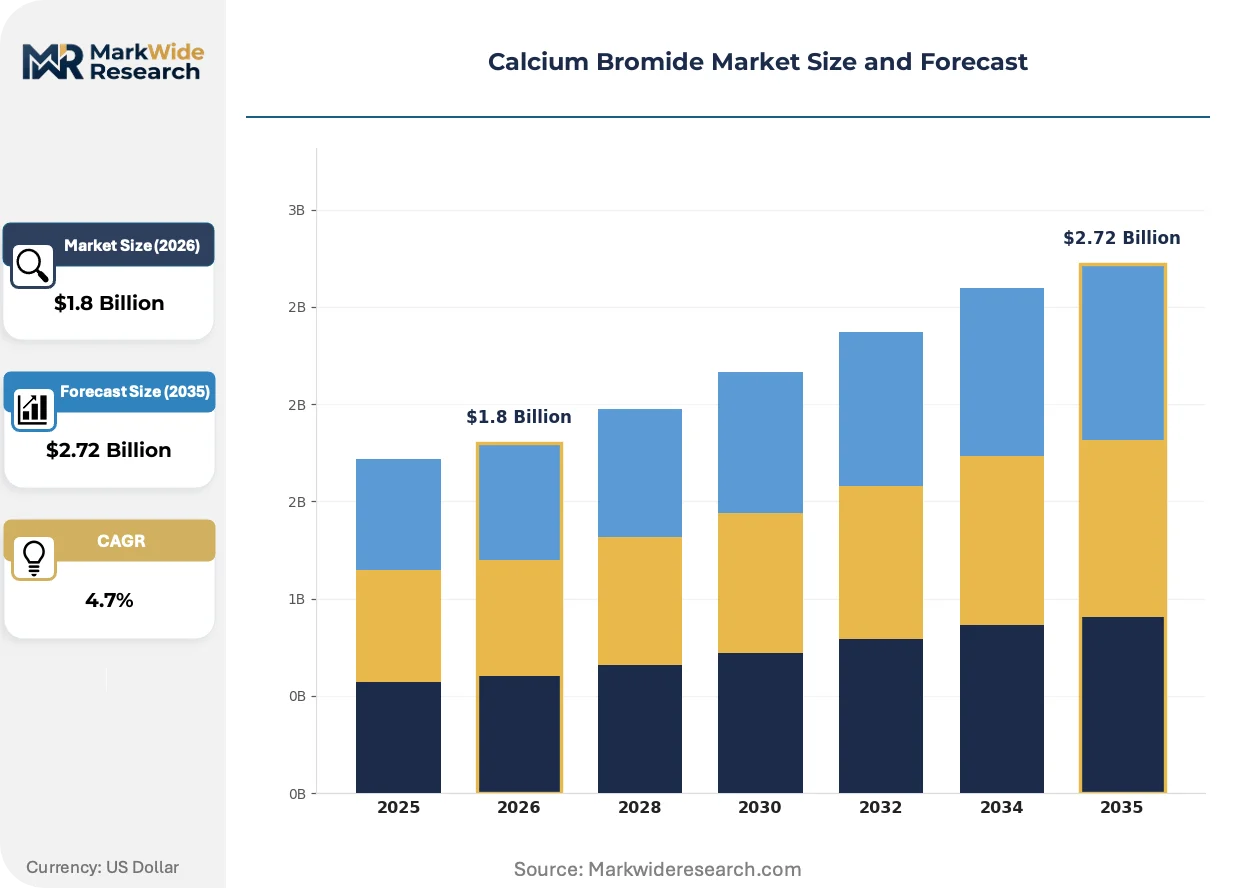
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Specialty Grade Application: Drilling Fluids, Flame Retardants, Water Treatment, Pharmaceutical End User: Oil & Gas, Chemicals, Pharmaceuticals, Agriculture Packaging Type: Bags, Drums, Bulk Containers, Cylinders |
| Companies Covered | LANXESS, Shandong Dongxin Chemical Industry Co., Ltd., ICL, Neogen Chemicals Ltd., Weifang Rixing Chemical Co., Ltd., Albemarle Corporation, TETRA Technologies, Inc., IRO Group Inc., Jordan Bromine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Bromide Market Emerging Trajectories
Formulation chemistry is pivoting toward density-optimized brine systems that eliminate solids loading while maintaining thermal stability. This shift is compressing traditional barite-weighted fluid market share and redefining supplier technical service requirements.
Membrane filtration and electrochemical purification systems are absorbing incremental capital investment across Dead Sea and Arkansas production facilities. North American drilling fluid formulators are adopting these systems to meet pharmaceutical-grade specifications without greenfield construction. The technology is absorbing volume from conventional crystallization processes by reducing energy intensity and water consumption in high-purity output.
China's MIIT updated industrial chemical standards are tightening purity requirements for bromide compounds used in domestic oilfield services. The regulation forces import-dependent formulators to qualify new suppliers or upgrade existing purification assets. Domestic producers with integrated bromine extraction are capturing share from traders unable to demonstrate GB standard compliance.
Operator procurement teams are consolidating completion fluid suppliers around integrated service packages that bundle technical design, logistics, and disposal. This bundling is displacing spot-market purchasing in the Permian Basin and Middle Eastern fields. Saudi Aramco's long-term drilling programs exemplify the shift toward multi-year supply agreements with density-guarantee clauses.
Calcium Bromide Market Segmentation
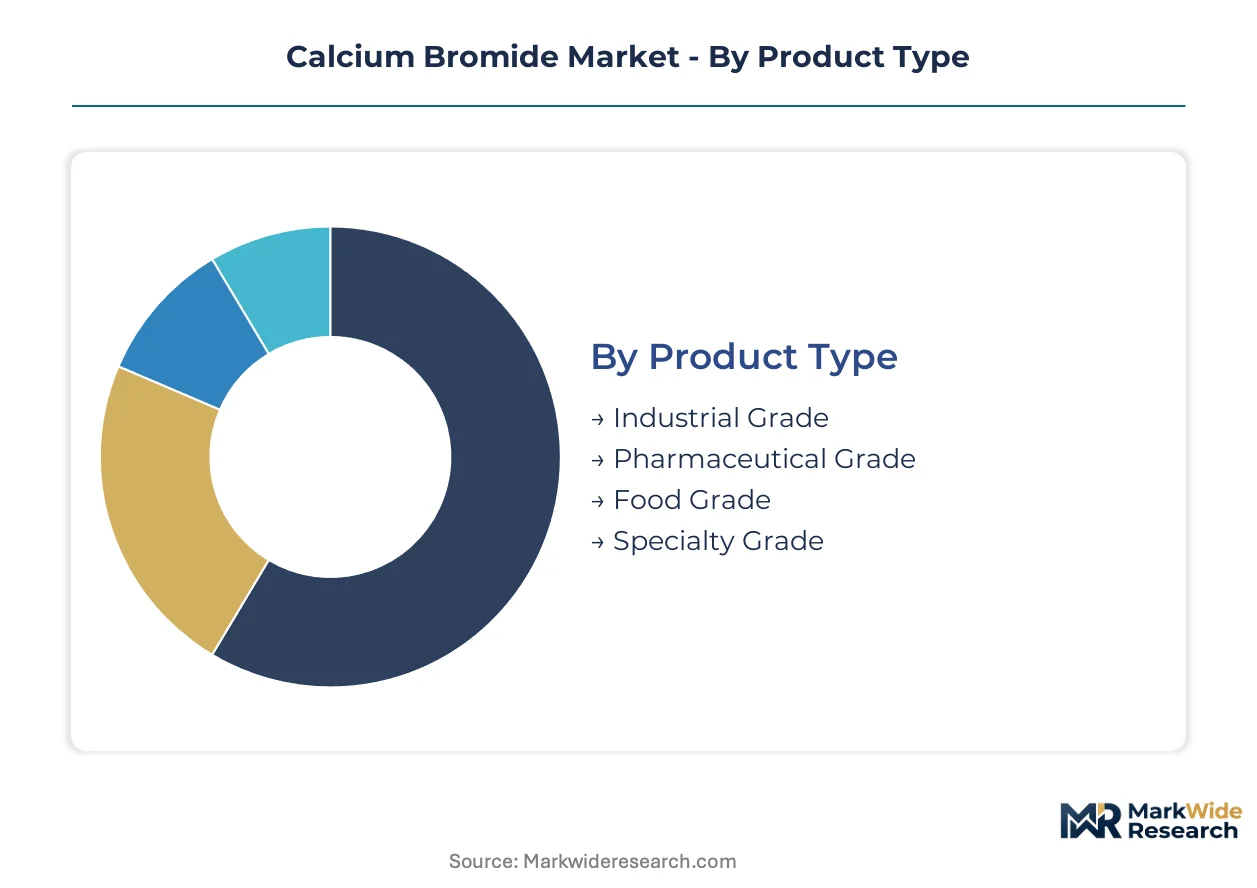
Calcium bromide producers configure their asset footprints around grade-specific purity thresholds that dictate capital intensity and regulatory compliance burden. Segmentation discipline separates commodity drilling fluid suppliers from premium pharmaceutical-grade operators with distinct margin structures and customer relationships.
Product Type:
Supply concentration in Dead Sea and Arkansas brine extraction favors producers with integrated purification infrastructure spanning multiple grade specifications.
- Industrial Grade:Aqueous solutions at 52-96% concentration serve density requirements of 11.7-15.1 ppg in oil well completion and workover operations. Permian Basin and Saudi Arabian drilling programs concentrate demand for solids-free brine systems with thermal stability specifications.
- Pharmaceutical Grade:Parenteral and sterile manufacturing applications command premium positioning amid tightening pharmacopeial standards from USP and EP. GB standards from China's SAMR and FDA sterile manufacturing guidelines require capital-intensive membrane filtration and electrochemical purification infrastructure.
- Food Grade:Limited addressable market constrained by alternative bromide sources in food processing applications.
- Specialty Grade:Niche formulations for electronics and laboratory reagents with exacting impurity specifications.
Today's leader: Industrial Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Cost tier differentiation separates commodity drilling fluid formulations from specialty chemical applications with divergent raw material sensitivity and technical service requirements.
- Drilling Fluids:Clear brine completion fluids displace barite-weighted systems in high-pressure formations across Saudi Aramco's long-term drilling programs and Permian Basin horizontal wells. Density-optimized formulations eliminate solids loading while maintaining thermal stability under downhole conditions.
- Flame Retardants:Construction and electronics sectors face tightening halogenated fire safety regulations that expand polymer additive demand. PFAS substitution risk threatens adjacent brominated chemistries in certain textile and polymer applications.
- Water Treatment:Disinfection and biocide applications compete with non-bromine alternatives on cost and regulatory acceptance.
- Pharmaceutical:Parenteral formulations and sterile manufacturing drive pharmacopeial compliance investments with multi-year validation timelines.
Volume concentration favors Drilling Fluids. Margin expansion concentrates in Pharmaceutical.
End User:
Customer type segmentation aligns supplier technical service capabilities with sector-specific regulatory exposure and procurement consolidation patterns.
- Oil & Gas:Upstream operators in Saudi Arabia's upstream sector and North American shale plays specify calcium bromide for high-density completion fluids. Operator procurement teams consolidate suppliers around integrated service packages bundling technical design, logistics, and disposal.
- Chemicals:Intermediate producers for flame retardant and bromine derivative manufacturing.
- Pharmaceuticals:Sterile manufacturers and parenteral drug formulators with pharmacopeial compliance requirements.
- Agriculture:Limited biocide and fumigant applications facing regulatory pressure on soil residues.
Procurement power concentrates with Oil & Gas. Compliance complexity escalates in Pharmaceuticals.
Packaging Type:
Logistics configuration determines working capital intensity and geographic reach for producers serving dispersed oilfield and industrial customers.
- Bags:Standard 25-50 kg units for industrial grade shipments to regional formulators and chemical distributors.
- Drums:Intermediate containment for pharmaceutical and specialty grade products requiring contamination control.
- Bulk Containers:Tote and ISO tank configurations serve integrated drilling fluid service companies with high-volume, continuous consumption patterns in Permian Basin and Middle Eastern fields.
- Cylinders:Pressurized containment for anhydrous or high-concentration specialty applications.
Scale economics favor Bulk Containers. Premium positioning attaches to Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calcium bromide production scaled from Dead Sea evaporite operations and Arkansas brine fields during the mid-20th century oil boom. These extraction sites remain foundational to global supply architecture. Regional demand now tracks high-pressure drilling programs and pharmaceutical purification investments across disparate regulatory environments.
United States
Permian Basin horizontal wells and Gulf of Mexico deepwater projects specify clear brine completion fluids at 14.2-15.1 ppg density. EPA underground injection control regulations govern disposal protocols for spent drilling fluids. Arkansas brine operations in Union County anchor domestic bromine extraction, with co-production economics linking lithium and calcium bromide output.
Saudi Arabia
Aramco's long-term drilling programs concentrate demand for high-density completion fluids in high-pressure carbonate formations. The national oil company consolidates procurement around multi-year supply agreements with density-guarantee clauses. Eastern Province oilfield services clusters around Dhahran and Jubail Industrial City host formulation facilities serving offshore and onshore developments.
China
Domestic shale gas exploration in Sichuan Basin and Tarim Basin drives consumption of solids-free brine systems. MIIT updated industrial chemical standards tighten purity requirements for bromide compounds used in oilfield services. Shandong Province chemical manufacturing corridors around Weifang concentrate bromide derivative production capacity.
Germany
European pharmaceutical manufacturers source pharmaceutical-grade calcium bromide for parenteral and sterile manufacturing applications. REACH registration requirements constrain market access for non-compliant importers, favoring established producers with dedicated regulatory affairs capacity. Leverkusen and Cologne chemical clusters host integrated bromine asset bases serving continental demand.
Israel
Dead Sea brine extraction operations supply elemental bromine feedstock to regional derivative producers. The unique evaporite geology supports integrated purification infrastructure spanning industrial through pharmaceutical grades. Negev Desert production facilities export to European and Asian formulators under long-term offtake arrangements.
Calcium Bromide Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across distinct value chain positions. The market structure concentrates around integrated bromine extractors with captive purification assets, while regional formulators and traders occupy fragmented downstream positions. Two strategic archetypes dominate: Dead Sea and Arkansas-based integrated producers with co-production economics, and regional chemical distributors with blending and logistics capabilities. Competitive moves center on purification capacity expansion and multi-year supply agreement negotiations with national oil companies.
Among integrated extraction specialists, LANXESS and ICL exemplify the asset-heavy archetype with integrated bromine operations. TETRA Technologies, Inc. occupies a position within North American drilling fluid formulation, representing the service-integrated tier. These three entities anchor distinct competitive vectors—European pharmaceutical-grade supply, Dead Sea evaporite extraction, and North American oilfield service bundling—without overlapping strategic positioning.
| Leading Market Players |
|---|
| LANXESS |
| Shandong Dongxin Chemical Industry Co., Ltd. |
| ICL |
| Neogen Chemicals Ltd. |
| Weifang Rixing Chemical Co., Ltd. |
| Albemarle Corporation |
| TETRA Technologies, Inc. |
| IRO Group Inc. |
| Jordan Bromine Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into Dead Sea and Arkansas brine extraction anchors both supply security and pricing power for calcium bromide producers, creating tiered margin structures that separate integrated extractors from downstream formulators dependent on spot bromine markets. This captive supply model insulates ICL and Albemarle Corporation from feedstock volatility while forcing non-integrated competitors to absorb elemental bromine price swings in their procurement costs.
Pricing Analysis
Contract-based long-term offtake agreements with density-guarantee clauses dominate procurement between Saudi Aramco and integrated producers, separating premium pharmaceutical-grade output from commodity drilling fluid formulations. Price differentiation rests on USP/EP certification tier and volume scale, with sterile manufacturing buyers least sensitive to cost. Cost compression in industrial grade intensifies because Permian Basin operators consolidate suppliers around bundled technical service packages.
Supply Chain Analysis
Single-source vulnerability sits with Dead Sea evaporite operations and Arkansas brine fields, which together feed the majority of global elemental bromine conversion. Geographic supply concentration centers on Israel, the United States, and China, while raw material dependencies draw from underground brine reservoirs, hydrobromic acid, and calcium oxide or carbonate sources. Tariff exposure on bromine derivatives threatens European formulators dependent on Middle Eastern feedstock. Distribution runs through ISO tank configurations for integrated drilling fluid service companies and regional chemical distributors serving fragmented downstream blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA underground injection control protocols and China's MIIT purity standards tightening compliance thresholds that favor established producers with dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter PFAS substitution risk spilling into adjacent brominated chemistries, LANXESS and ICL should deepen captive bromine extraction capacity in Germany and Israel while accelerating pharmacopeial certification investments for parenteral-grade output. Capacity addition in Arkansas lithium-bromine co-production sites secures integrated margin structures unavailable to standalone competitors. For New Entrants and Emerging Players: Direct-to-operator digital procurement platforms offer the most penetrable route into Saudi Aramco's consolidated supplier base, where technical documentation and real-time density certification can displace legacy distributor relationships. White-space targets include membrane filtration technology licensing to Chinese domestic producers facing GB standard compliance deadlines, and specialty-grade formulations for electronics reagent applications. For Investors and Strategic Acquirers: Roll-up economics work for regional drilling fluid formulators with blending assets in the Permian Basin and Eastern Province because operator procurement consolidation favors integrated service providers over pure chemical traders. Acquisition targets should display captive logistics infrastructure and multi-year supply agreement backlogs. The signal to watch is Saudi Aramco's tender frequency for long-term completion fluid contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Captive bromine supply insulates ICL and Albemarle from Dead Sea production volatility. |
| Pharmacopeial Certification Investment | USP and EP compliance opens sterile manufacturing contracts with premium margin structures. |
| Long-term Supply Agreement Negotiation | Density-guarantee clauses with Saudi Aramco lock in volume visibility across drilling cycles. |
| Membrane Filtration Technology Deployment | Electrochemical purification reduces energy intensity for Chinese producers facing MIIT standards. |
| Joint Venture with Regional Formulators | Local blending capacity in Dhahran Industrial City shortens logistics chains for Aramco programs. |
Methodological Framework
Coverage spans North America, the Middle East, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with oilfield service procurement directors, pharmaceutical sterile manufacturing executives, bromine extraction plant managers, and regulatory affairs specialists at chemical distributors. Secondary validation draws from EPA underground injection control filings, SAMR GB standard publications, SEC 10-K disclosures by integrated producers, and trade data from customs authorities in Germany, China, and Saudi Arabia. Bottom-up demand modeling triangulates against top-down bromine derivative production estimates.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon, with segmentation dimensions covering grade tier (industrial, pharmaceutical, food, specialty), end-use application (drilling fluids, flame retardants, pharmaceuticals, water treatment), packaging format (bulk containers, drums, bags), and regional production hub. CAGRs derive from trend extrapolation of Aramco drilling program announcements, Permian Basin rig counts, and pharmacopeial standard revision timelines. Industry-specific forecast inputs include lithium-bromine co-production economics and REACH registration compliance costs.
Regulatory enforcement variance, bromine feedstock concentration disruptions, and PFAS substitution acceleration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about drilling activity persistence and purity standard adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Granular Urea Market