
 Global Sodium Chloride Market | 2026-2036
Global Sodium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Chloride Market Foresight
REACH compliance is decoupling European supply chains from lower-purity sources, forcing capital upgrades across the value chain. Cargill leverages its integrated evaporation and packaging network across North American salt deposits. K+S Aktiengesellschaft anchors Central European supply through its controlled access to German and Spanish rock salt formations. China National Salt Industry Corporation dominates domestic distribution through state-mandated channel control.
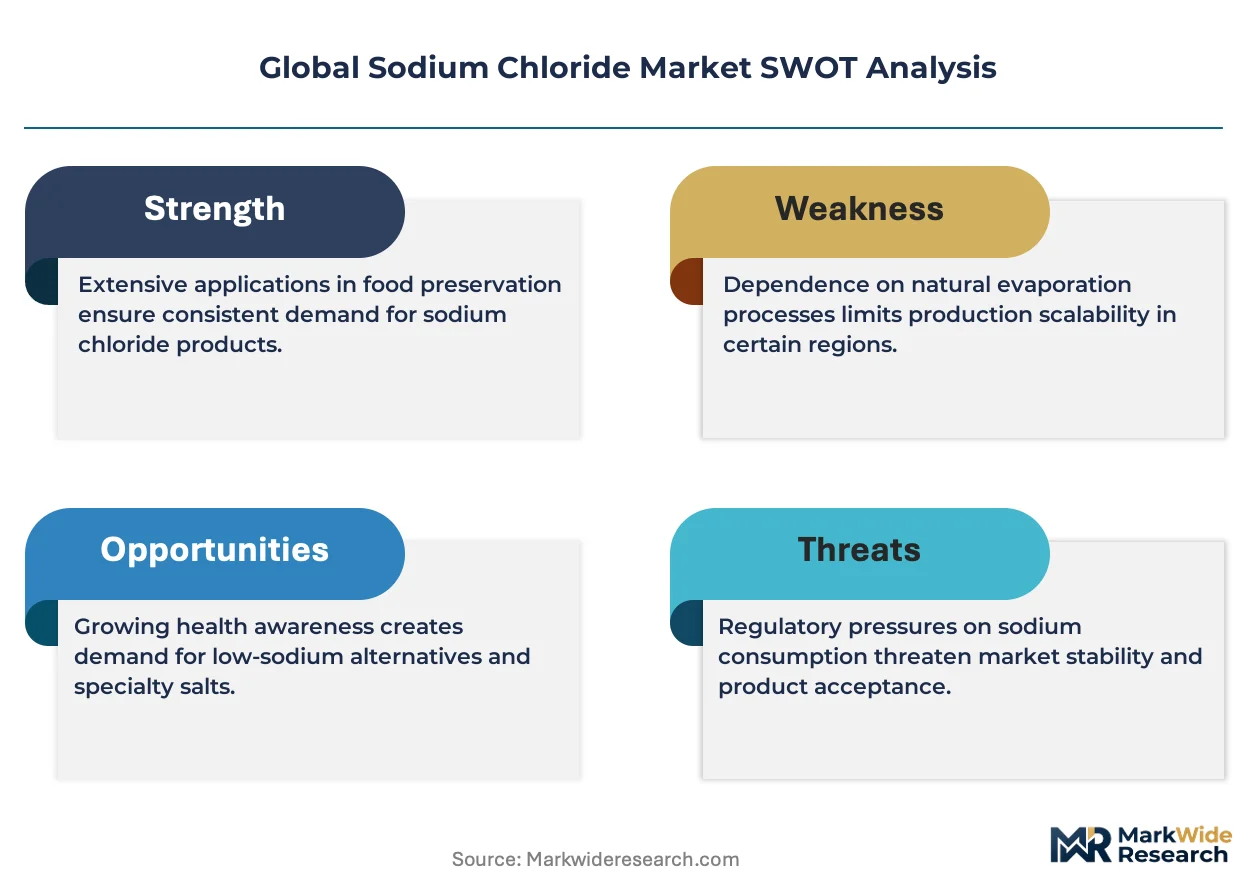
Sodium chloride is an ionic compound of sodium and chlorine with the formula NaCl, typically crystallizing in a face-centered cubic lattice structure and dissolving in water to yield a neutral pH solution. Manufacturers produce it through solar evaporation of brine, solution mining of underground deposits, or conventional underground mining of rock salt halite seams; the resulting material serves as a fundamental feedstock for chlor-alkali electrolysis, food preservation, and roadway safety applications. Industrial grade commands the largest volume share due to chlor-alkali demand, while pharmaceutical grade captures the highest margin pool because of USP and EP certification requirements. Deicing grade volumes fluctuate with winter severity cycles, creating seasonal cash flow asymmetries that distributors navigate through inventory pre-positioning.
FDA food-grade standards, EPA discharge permits for brine handling, and China's GB standards for industrial salt purity collectively shape product specifications and market access conditions across major producing regions. The EU F-Gas Regulation indirectly bolsters salt demand by accelerating chemical-based cooling system replacements that depend on chlor-alkali derivatives. Stakeholders must monitor how tightening brine discharge limits in coastal manufacturing zones reshape the economics of solar evaporation versus mechanical processing.
Market Dynamics
The sodium chloride market pivots on purification-grade bifurcation as REACH compliance and chlor-alkali feedstock specifications force capital reallocation between solar evaporation and mechanical processing routes.
Growth Catalysts
- EU Green Deal industrial benchmarks:Tightening emissions thresholds for chemical-grade feedstock are compelling membrane-based purification upgrades across European chlor-alkali plants.
- Southeast Asian desalination expansion:Water utilities in Thailand, Indonesia, and Vietnam are scaling reverse osmosis capacity, driving industrial salt demand for membrane cleaning and brine management.
- India's chemical corridor concentration:The Gujarat-Maharashtra industrial belt is attracting chlor-alkali capacity expansions that anchor regional salt offtake.
Market Restraints
- Rock salt supply concentration:German and Spanish underground deposits control Central European supply, creating single-source vulnerability for regional chemical processors.
- Mechanical processing energy costs:Vacuum evaporation and centrifugal separation consume natural gas and electricity at rates that compress margins when energy markets spike.
- Potassium chloride substitution in deicing:Municipal road authorities in Scandinavia and the Alpine region are blending KCl into salt stocks, eroding volume capture during mild winter cycles.
Strategic Opportunities
- Pharmaceutical-grade certification arbitrage:USP and EP compliance gaps in Eastern European and Latin American production create white space for qualified entrants.
- Integrated solar-mechanical hybrid processing:Combining Chilean and Australian solar evaporation assets with containerized purification units reduces brine discharge exposure.
- Brine-to-chemicals circular models:EU F-Gas Regulation acceleration of HFC phase-downs is expanding demand for chlor-alkali-derived refrigerants that depend on high-purity salt feedstock.
Industry Challenges
- Geological survey and seam mapping expertise:Solution mining of halite deposits requires specialized hydrogeological talent that competes with oil and gas sector compensation.
- Multi-jurisdictional certification timelines:Simultaneous USP, EP, and JP compliance for pharmaceutical-grade output extends validation cycles and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Chloride Market |
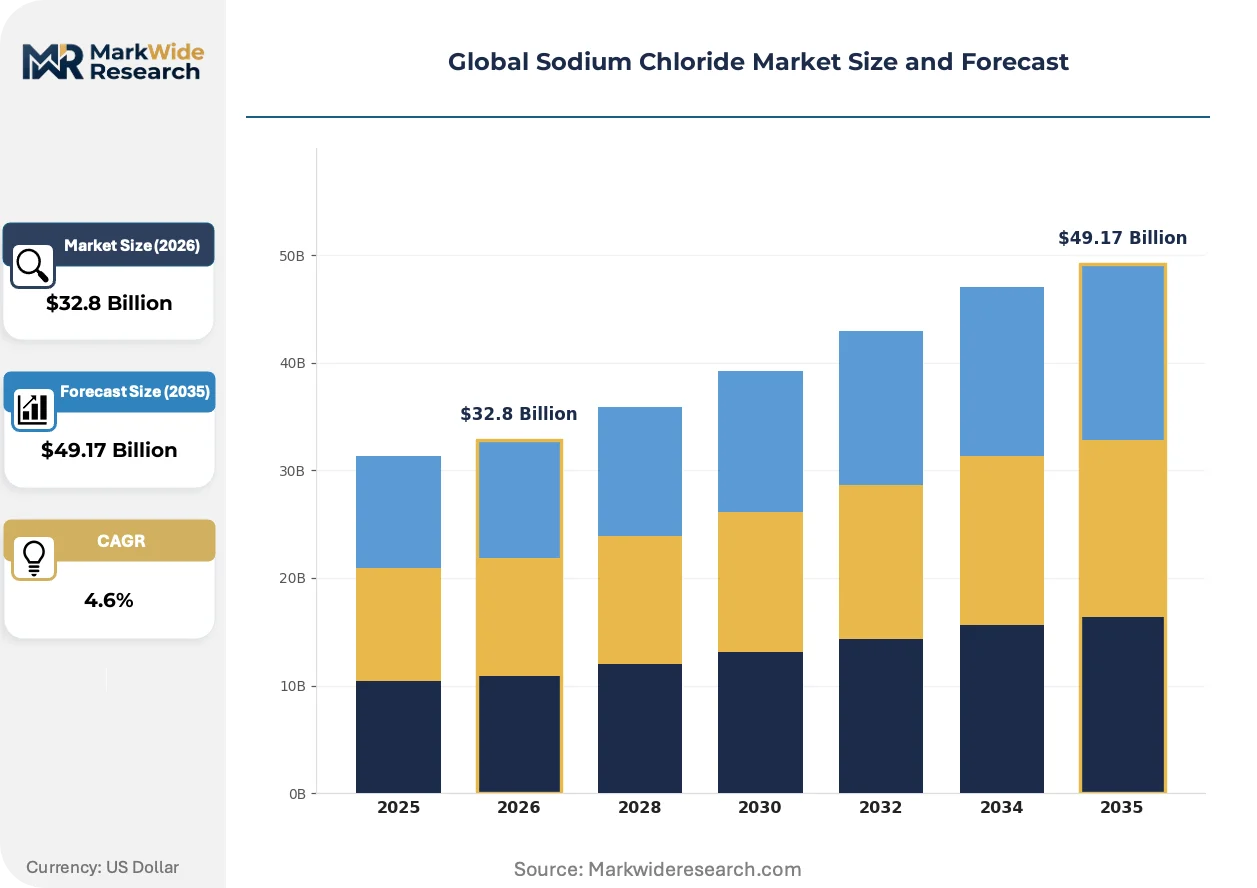
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Deicing Grade, Cosmetic Grade Application: Chemical Manufacture, Water Treatment, Food Processing, Deicing Roads, Animal Feed, Oil & Gas Extraction End User Industry: Chemical Plants, Water Utilities, Food Manufacturers, Transportation Departments, Animal Farms, Oilfield Services Distribution Channel: Direct Sales, Wholesale Distributors, Retail Chains, Online Platforms, Exporters |
| Companies Covered | Cargill, K+S Aktiengesellschaft, Compass Minerals, China National Salt Industry Corporation, Tata Chemicals, Nouryon, INEOS, Wacker Chemie AG, Südwestdeutsche Salzwerke AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Chloride Market Shifts & Advancements
Membrane technology and electrochemical processing are redrawing the economics of salt purification, compressing the historical advantage of geography-dependent solar evaporation.
Electrodialysis reversal systems are decentralizing brine concentration by enabling chemical processors to upgrade lower-grade feedstock on-site rather than sourcing pre-purified material. Chlor-alkali operators in Texas and Louisiana are adopting skid-mounted electrodialysis units to process locally sourced solution-mined brine. This distributed model is compressing the historical premium commanded by solar-evaporated salt from coastal deposits.
REACH authorization requirements are forcing European importers to document full substance lifecycle data for salt destined for food and pharmaceutical applications. ECHA's expanded SVHC candidate list now captures trace heavy metal contaminants that previously fell below detection thresholds. German and Dutch distributors are responding by qualifying captive North African solar evaporation assets with certified impurity profiles.
Direct procurement contracts between chlor-alkali majors and solution mining operators are displacing traditional merchant salt distributors in North America. Buyers in the Ohio River Valley and Gulf Coast corridors are negotiating ten-year offtake agreements with Appalachian and Louisiana brine producers. This channel compression is most advanced in polyethylene and PVC feedstock supply chains where volume predictability outweighs spot market flexibility.
Global Sodium Chloride Market Segmentation
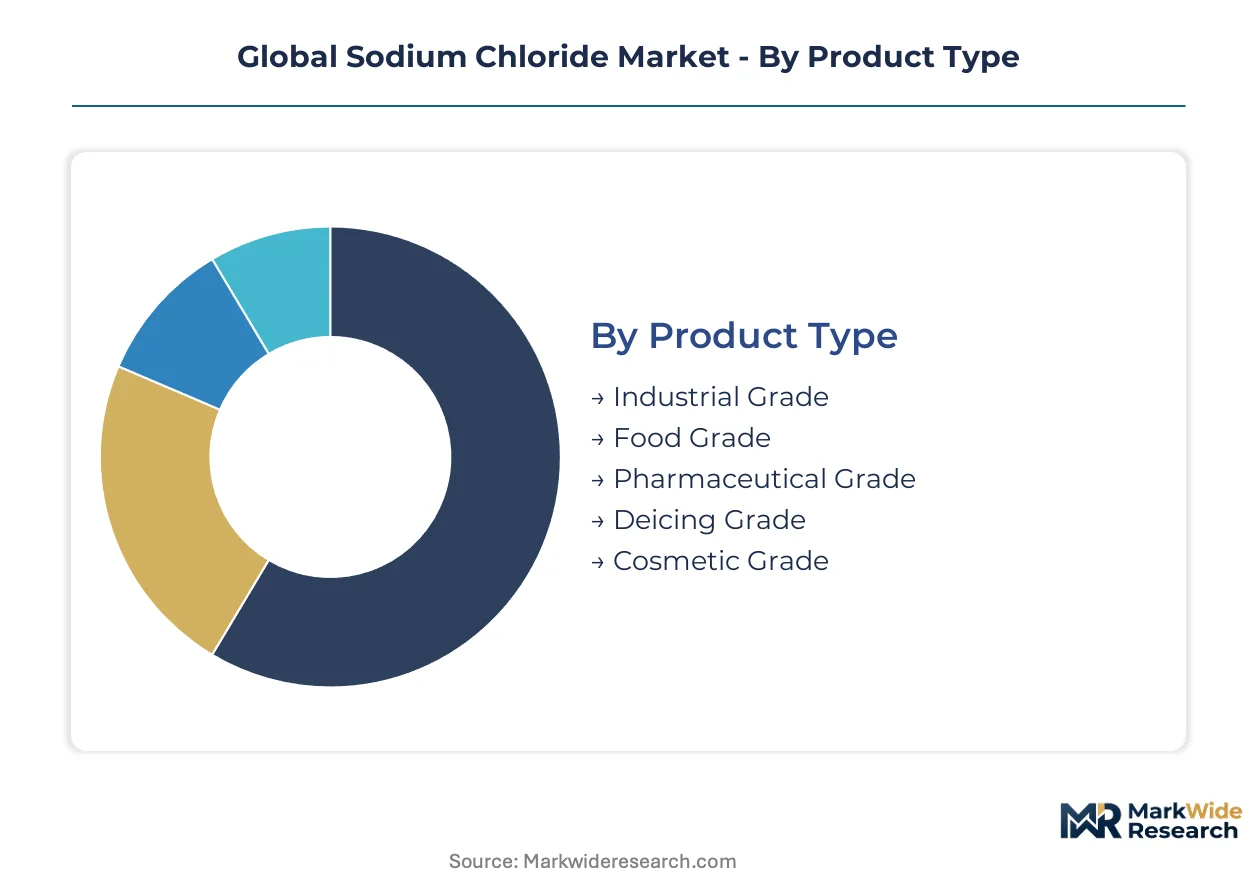
Sodium chloride purification requirements bifurcate sharply between embedded industrial processes and standalone consumer-facing applications. Grade certification thresholds determine which segments absorb capital-intensive mechanical processing versus solar-evaporated sourcing.
Product Type:
Industrial and pharmaceutical grades anchor fundamentally different supply chain architectures—one optimized for volume throughput, the other for contamination control.
- Industrial Grade:Chlor-alkali electrolysis demands NaCl purity above 97% with strict calcium and magnesium limits to prevent membrane fouling. Texas and Louisiana chemical corridors source this grade through solution-mined brine processed by skid-mounted electrodialysis units.
- Pharmaceutical Grade:USP and EP certification mandates heavy metal testing below 10 ppm and microbial limits that exclude solar evaporation from non-certified facilities. German and Dutch distributors now qualify captive North African assets with documented impurity profiles to satisfy ECHA's expanded SVHC candidate list.
- Food Grade:FDA and FSSAI standards govern anti-caking additive limits and iodine fortification protocols for table and preservation salt.
- Deicing Grade:Winter severity cycles drive seasonal procurement by transportation departments across the US Midwest and Alpine Europe.
- Cosmetic Grade:INCI compliance and particle size distribution specifications serve formulation houses in France and South Korea.
Volume placements concentrate in industrial grade; the faster expansion belongs to pharmaceutical grade.
Application:
Cost-tier stratification separates commodity-scale chemical consumption from premium-margin specialized treatments.
- Chemical Manufacture:Chlor-alkali plants consume the largest tonnage, converting salt to chlorine, caustic soda, and hydrogen for PVC and polyurethane feedstocks. Gujarat-Maharashtra corridor expansions anchor regional offtake growth.
- Water Treatment:Reverse osmosis membrane cleaning and brine management drive demand across Thailand, Indonesia, and Vietnamese desalination utilities. Southeast Asian capacity additions outpace global averages for this application.
- Food Processing:Curing, brining, and preservation operations in US meatpacking and EU dairy sectors require certified food-grade supply with full traceability documentation.
- Deicing Roads:Municipal authorities in Scandinavia blend potassium chloride into salt stocks, compressing pure NaCl capture during mild winter cycles.
- Animal Feed:Mineral supplementation for livestock operations follows regional agricultural intensity patterns in Brazil and Australia.
- Oil & Gas Extraction:Drilling mud weighting and completion brines in Permian Basin and North Sea operations demand specific density grades.
Chemical manufacture dominates absolute volume; water treatment applications are expanding most quickly.
End User Industry:
Customer-type concentration determines contract structure—direct procurement agreements versus merchant distributor relationships.
- Chemical Plants:Ten-year offtake agreements between chlor-alkali majors and Appalachian or Louisiana brine producers displace traditional distributors in the Ohio River Valley and Gulf Coast corridors.
- Water Utilities:State-owned and municipal operators in Vietnam and Thailand negotiate framework contracts for membrane maintenance chemicals.
- Food Manufacturers:Integrated meatpackers and dairy processors in the US and Germany qualify dual-source supply for HACCP compliance.
- Transportation Departments:Seasonal inventory pre-positioning requirements create working capital intensity for distributors serving state and provincial road authorities.
- Animal Farms:Feed compounders in Brazil's Mato Grosso and Australia's Queensland integrate salt into premix formulations.
- Oilfield Services:Halliburton and Schlumberger procurement specifications for drilling fluids drive quality certification requirements.
Volume placements concentrate in chemical plants; water utilities show the steepest expansion trajectory.
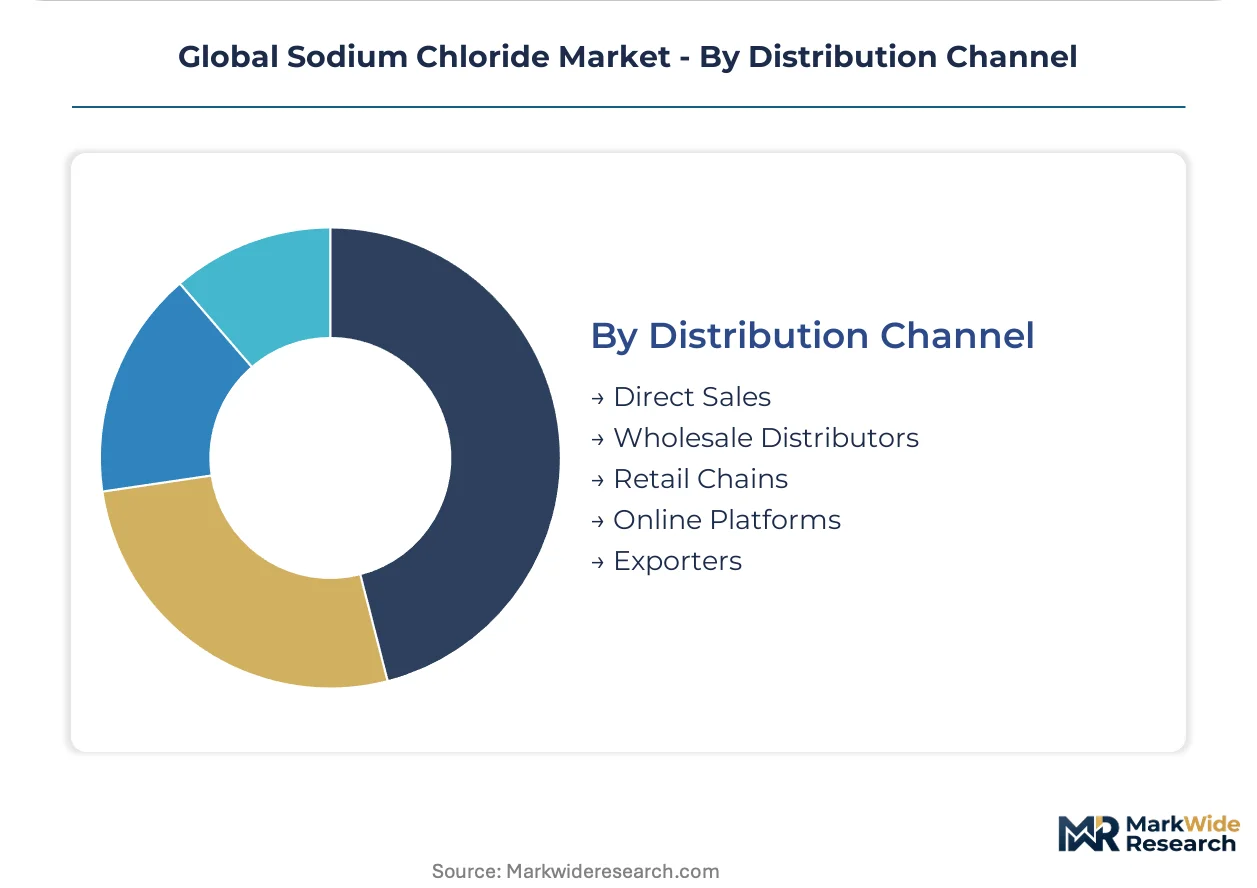
Distribution Channel:
Supply concentration and margin capture vary sharply between captive producer networks and third-party logistics platforms.
- Direct Sales:Chlor-alkali and oilfield chemical producers negotiate long-term contracts with solution mining operators, compressing distributor margins in North America.
- Wholesale Distributors:Regional salt merchants in Germany and Spain manage inventory pools for chemical processors dependent on Central European rock salt deposits.
- Retail Chains:Grocery and home improvement channels handle packaged food-grade and deicing products with seasonal promotional calendars.
- Online Platforms:Bulk procurement portals serve small and mid-sized water treatment operators in Southeast Asia with spot purchasing flexibility.
- Exporters:North African and Australian solar evaporation producers ship certified pharmaceutical and food-grade material to EU and Japanese importers facing REACH and PMDA compliance requirements.
Volume placements concentrate in direct sales; online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Dahej Petroleum, Chemicals and Petrochemicals Investment Region concentrates chlor-alkali capacity expansions that anchor Indian salt offtake. The state's salt-works-to-chemicals corridor exemplifies how special economic zones reshape regional demand geography.
United States
Texas and Louisiana chemical corridors source industrial-grade sodium chloride through solution-mined brine processed by skid-mounted electrodialysis units. EPA discharge permits for brine handling govern solar evaporation economics along the Gulf Coast. The Ohio River Valley hosts ten-year offtake agreements between chlor-alkali majors and Appalachian brine producers that displace traditional merchant distributors.
Germany
REACH compliance and ECHA's expanded SVHC candidate list force capital upgrades across chlor-alkali feedstock purification. The EU F-Gas Regulation accelerates demand for refrigerants derived from high-purity salt feedstock. K+S Aktiengesellschaft anchors Central European supply through controlled access to German and Spanish rock salt formations concentrated in Lower Saxony.
China
State-mandated channel control through China National Salt Industry Corporation dominates domestic distribution networks. GB standards for industrial salt purity shape product specifications for chemical-grade feedstock. The Yangtze River Delta chemical clusters consume volume throughput for PVC and polyurethane precursors.
India
Gujarat-Maharashtra industrial belt expansions in chlor-alkali capacity anchor regional salt offtake growth. FSSAI standards govern anti-caking additive limits and iodine fortification protocols for food-grade supply. Tata Chemicals operates integrated evaporation assets serving Mithapur chemical complexes.
Vietnam
State-owned water utilities negotiate framework contracts for membrane maintenance chemicals tied to reverse osmosis capacity scaling. The country's national environmental regulator tightens brine discharge limits in coastal manufacturing zones. Ho Chi Minh City and Mekong Delta industrial zones concentrate desalination utility procurement.
Global Sodium Chloride Market Competitive Landscape
North American producers anchor one tier through integrated evaporation and packaging networks; European specialists hold another through controlled access to rock salt formations. The vendor base stratifies between volume-driven solar evaporation operators and certification-focused mechanical processors. Three archetypes dominate: integrated agribusiness conglomerates with salt as a sidestream, state-mandated national champions with distribution channel control, and captive chemical producers with backward integration into brine sourcing. Competitive moves concentrate on direct procurement contract displacement of merchant distributors and qualification of captive offshore assets for REACH compliance.
Within the state-mandated champion tier, China National Salt Industry Corporation exemplifies channel control through domestic distribution networks. Among integrated agribusiness operators, Cargill occupies a position representing North American solar evaporation and packaging integration. K+S Aktiengesellschaft anchors the European specialist archetype through controlled access to German and Spanish rock salt formations.
| Leading Market Players |
|---|
| Cargill |
| K+S Aktiengesellschaft |
| Compass Minerals |
| China National Salt Industry Corporation |
| Tata Chemicals |
| Nouryon |
| INEOS |
| Wacker Chemie AG |
| Südwestdeutsche Salzwerke AG |
| Others |
Supply & Pricing Matrix
State-mandated national champions with captive distribution networks anchor supply-side discipline, translating channel control into pricing power that resists spot-market volatility. Their integrated evaporation and packaging assets compress working capital cycles for buyers, while independent solar-evaporation operators absorb margin pressure from energy price spikes.
Pricing Analysis
Premium pricing attaches to short lead-time delivery of pharmaceutical-grade material with USP and EP certification, while spot inventories of industrial-grade salt trade at discounts reflecting storage carrying costs. Contract-based long-term offtake agreements dominate chlor-alkali procurement, with price differentiation driven by certification grade and volume scale. Cost compression in mechanical processing tiers is intensifying because natural gas and electricity markets spike unpredictably. Municipal road authorities show highest price sensitivity during mild winter cycles, while pharmaceutical formulators accept premium pricing for documented impurity profiles.
Supply Chain Analysis
Freight costs from North African solar evaporation sites to EU pharmaceutical importers compress margins for uncertified producers unable to document REACH-compliant substance lifecycle data. Supply concentrates in China, Germany, and India, with raw material dependencies spanning brine chemistry, membrane filtration media, and natural gas for vacuum evaporation. Single-source vulnerability runs through Central European rock salt deposits controlled by limited seam access. Distribution runs through direct procurement contracts displacing traditional merchant distributors in North American chemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rock salt seam depletion rates in mature German and Spanish deposits prop pricing discipline by constraining solution-mining capacity expansion. Supply constraints tighten whenever ECHA expands SVHC candidate lists, forcing qualification of captive offshore assets.
For Market Incumbents: Anticipate potassium chloride substitution in Scandinavian and Alpine deicing markets by qualifying blended-product certification and expanding pharmaceutical-grade capacity in North Africa. Channel control through state-mandated distribution networks remains the priority lever against independent solar-evaporation entrants. Defensive consolidation should target captive brine-to-chemicals circular models in EU F-Gas Regulation-driven refrigerant supply chains. For New Entrants and Emerging Players: Small and mid-sized water treatment operators in Vietnam and Thailand represent an underserved buyer archetype accessible through bulk procurement portals with spot purchasing flexibility. White-space targets include USP and EP compliance gaps in Eastern European and Latin American production, plus containerized purification units for Chilean and Australian solar-mechanical hybrid processing. Go-to-market positioning should emphasize documented impurity profiles for ECHA REACH authorization. For Investors and Strategic Acquirers: Ten-year offtake agreement announcements between chlor-alkali majors and Appalachian or Louisiana brine producers are the leading indicator that direct procurement compression of merchant distributors is accelerating. Long-term viability favors integrated solar-mechanical hybrid processors with captive offshore assets qualified for multi-jurisdictional certification. Acquisition targets should display controlled access to certified rock salt formations or state-mandated channel infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Sourcing | Chlor-alkali majors in Texas and Louisiana secure captive supply through Appalachian solution-mining contracts. |
| Pharmaceutical-Grade Certification Investment | North African solar evaporation assets qualify for ECHA REACH compliance, opening EU pharmaceutical channels. |
| Long-term Supply Agreement | Ten-year offtake contracts between Ohio River Valley chemical processors displace traditional merchant salt distributors. |
| Green Manufacturing Transition | EU F-Gas Regulation acceleration expands demand for chlor-alkali-derived refrigerants from high-purity salt feedstock. |
| Joint Venture | Southeast Asian water utilities partner with membrane maintenance chemical suppliers for reverse osmosis capacity scaling. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with chlor-alkali plant managers, pharmaceutical procurement leads, water utility framework contract negotiators, and solar evaporation facility operators. Cefic chemical industry reports, ECHA substance registration databases, US EPA discharge permit records, and SEC 10-K filings from integrated salt producers provided validation layers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Reconciliation of production volume data from national salt associations with import-export customs statistics and end-use consumption surveys shaped the analytical framework across the analysis window. Segmentation dimensions modeled include purification grade tier, end-use industry application, and regional production hub concentration. CAGRs derived from regression analysis of historical capacity expansion rates against projected chlor-alkali and desalination utility demand. Forecast inputs incorporated ECHA SVHC list expansion timelines and F-Gas Regulation phase-down schedules.
Revisions become necessary when brine discharge limit tightenings in coastal manufacturing zones materialize, or when potassium chloride substitution rates in municipal deicing exceed projected thresholds. Forecasts reflect assumptions about membrane technology adoption curves and energy market volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market