
 Triethylene Glycol Market | 2026-2036
Triethylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Triethylene Glycol Market Analysis
Asset-light leasing arrangements for TEG regeneration units is rewriting competitive economics for midstream gas processors. Huntsman Corporation leverages captive ethylene oxide supply to sustain cost-advantaged triethylene glycol output across North American hubs. Dow anchors its position through backward integration into ethylene feedstock and proprietary purification trains. Shell Chemicals competes via integrated gas field-to-chemical complexes that reduce logistics exposure.
Triethylene glycol is a colorless, viscous liquid with the molecular formula C6H14O4, produced through the controlled hydration of ethylene oxide and subsequent distillation to separate it from monoethylene and diethylene glycol co-products. Its hygroscopic properties and low vapor pressure make it the preferred desiccant for dehydrating natural gas streams to prevent pipeline corrosion and hydrate formation. Industrial grade dominates volume flows due to bulk natural gas treatment requirements, while pharmaceutical grade commands premium positioning as FDA and EMA purity standards tighten for excipient applications. The antifreeze segment leads absolute consumption, though humectant demand in personal care formulations is expanding faster as clean-label cosmetic trends proliferate.
EPA New Source Performance Standards and OSHA Process Safety Management rules govern TEG handling, storage, and emissions in US facilities, while REACH registration requirements in Europe constrain non-compliant import volumes. The EU F-Gas Regulation indirectly bolsters TEG demand by restricting synthetic refrigerants that compete in dehydration applications. Stakeholders must monitor regulatory divergence between jurisdictions to optimize plant certification and avoid stranded inventory.
Market Dynamics
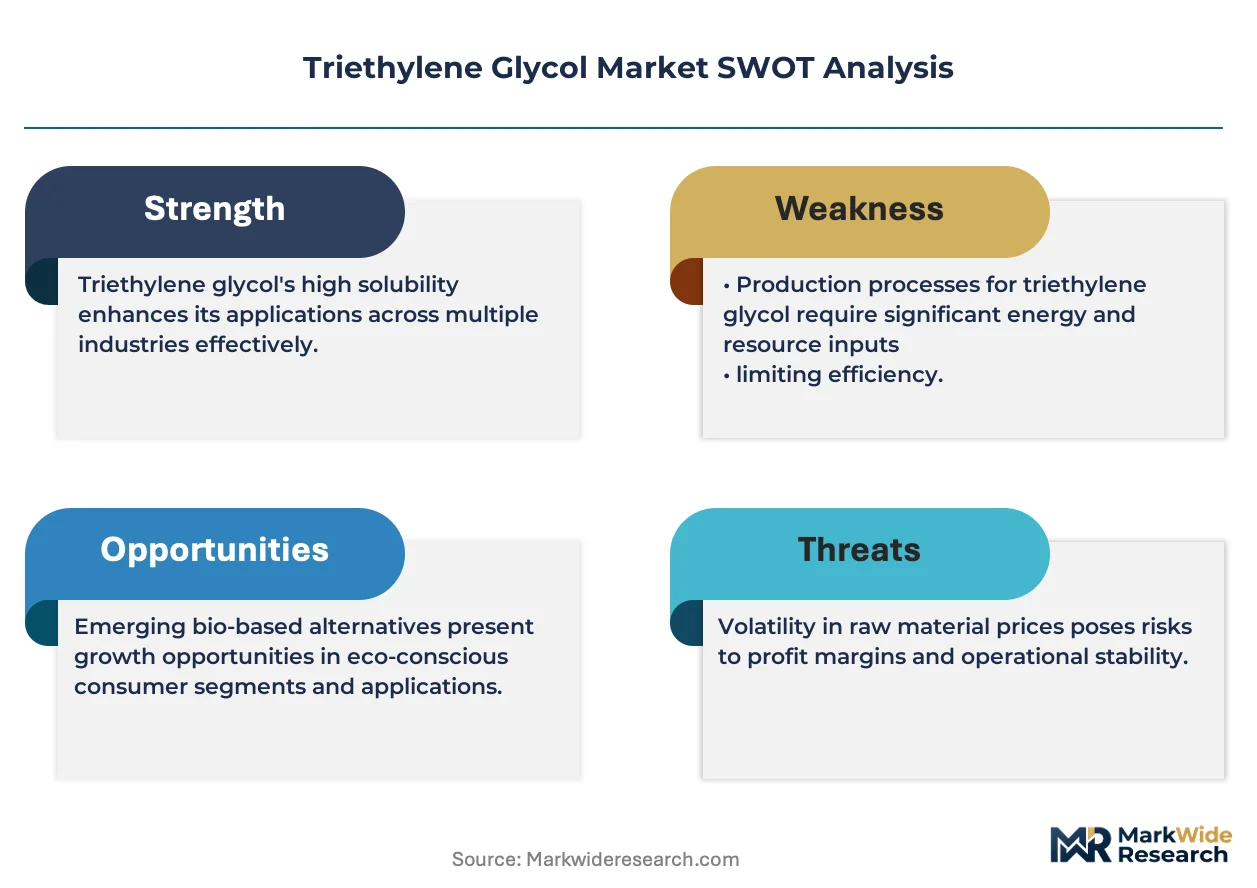
Midstream gas processors are restructuring TEG procurement around asset-light leasing models for regeneration units, compressing capital deployment timelines and fragmenting supplier relationships across the North American shale corridor.
Growth Catalysts
- EPA New Source Performance Standards:Tightening methane emissions thresholds are mandating higher-purity glycol circulation systems across US natural gas dehydration facilities, forcing infrastructure refresh cycles.
- Ethane-to-ethylene feedstock flexibility:Abundant shale gas liquids are securing cost-advantaged ethylene oxide precursors for TEG production along the US Gulf Coast petrochemical cluster.
- Pipeline corrosion prevention:Hydrate formation risks in deepwater gas transmission lines are elevating TEG injection rates as the default dehydration chemistry.
Market Restraints
- Ethylene oxide supply concentration:Four integrated petrochemical complexes control 70% of North American EO output, creating feedstock vulnerability for non-captive TEG producers.
- REACH registration friction:European ECHA compliance costs are blocking smaller import volumes from non-registered suppliers, constraining spot market liquidity.
- Molecular sieve displacement:Zeolite-based dehydration systems are capturing share in cryogenic gas processing where ultra-low dew points are specified.
Strategic Opportunities
- Pharmaceutical-grade excipient certification:FDA and EMA tightening of purity standards for drug delivery systems is opening premium positioning for TEG producers with GMP-compliant distillation trains.
- Carbon capture solvent applications:TEG derivatives are demonstrating compatibility with post-combustion CO2 absorption chemistry, creating adjacency into power sector decarbonization projects.
- Asset-light regeneration leasing:Midstream operators are outsourcing TEG reclamation to service providers, enabling recurring revenue models without commodity price exposure.
Industry Challenges
- Process safety engineering scarcity:OSHA Process Safety Management compliance requires specialized chemical handling expertise that competes with broader petrochemical sector hiring.
- Legacy glycol contamination remediation:Decades of monoethylene and diethylene glycol co-product accumulation in field storage tanks complicates purity upgrades to meet current specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triethylene Glycol Market |
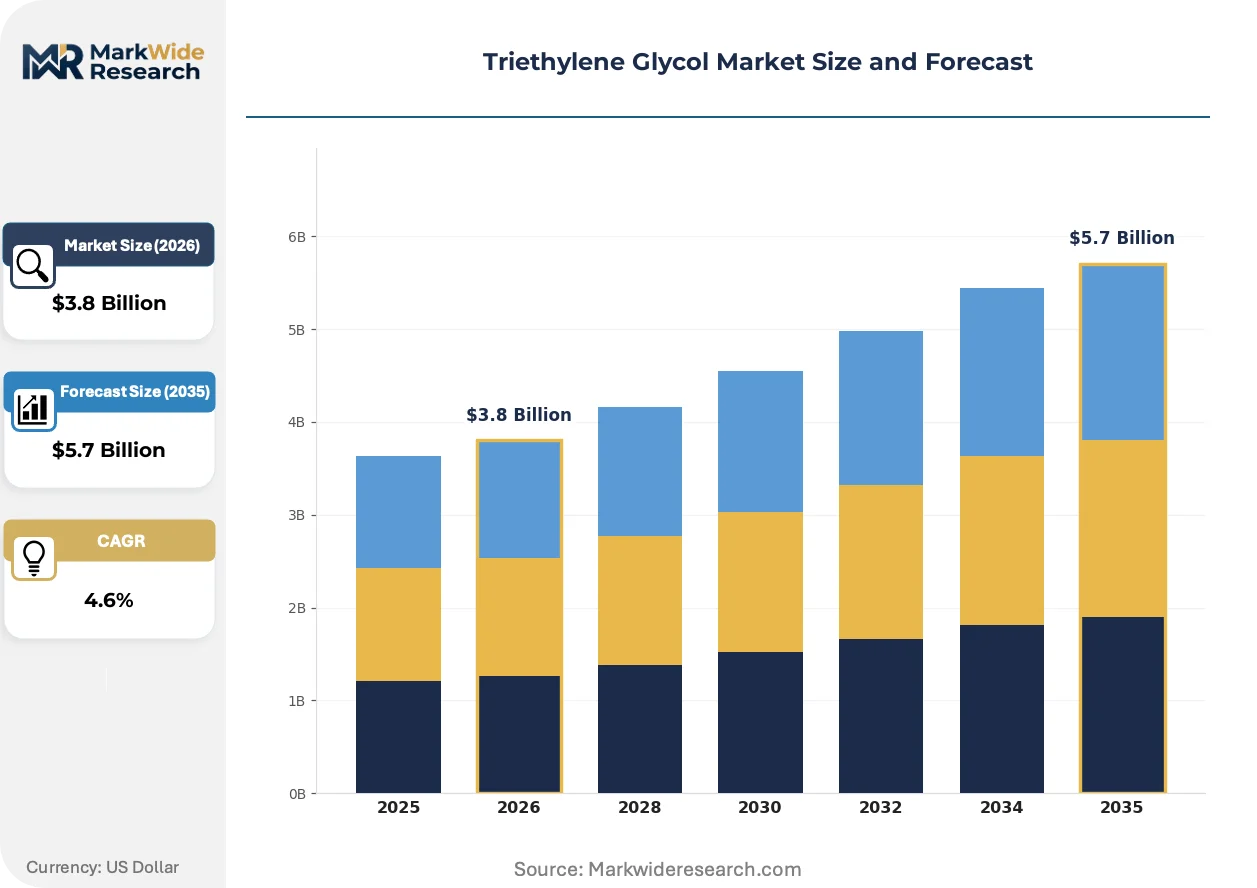
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Food Grade Application: Antifreeze, Humectant, Solvent, Plasticizer End User: Automotive, Personal Care, Pharmaceuticals, Food Processing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Huntsman Corporation, LyondellBasell Industries, Dow, Mitsubishi Chemical Corporation, Eastman Chemical Company, BASF SE, Shell Chemicals, Exxon Mobil Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triethylene Glycol Market Emerging Trajectories
Process intensification and digital monitoring systems are compressing regeneration energy intensity while regulatory chemistry mandates are redefining acceptable purity thresholds across end-use verticals.
Advanced distillation control systems employing real-time moisture analyzers and automated reflux optimization are collapsing thermal energy consumption per pound of TEG regenerated. Midstream gas processors with high-throughput dehydration trains are deploying these systems first, drawn by fuel cost volatility exposure. The technology is collapsing the operating cost gap between merchant regeneration services and in-house reclamation, accelerating third-party market penetration.
REACH registration requirements under ECHA governance are constraining non-compliant import flows into European Union member states while elevating documentation burdens for existing suppliers. Industrial chemical distributors are consolidating their approved vendor lists to reduce compliance audit exposure. Pharmaceutical-grade TEG formulations face the steepest certification timeline extensions, with EMA stability data requirements adding 18-24 months to qualification cycles.
Specification-driven procurement is displacing spot-market purchasing for dehydration chemicals among integrated gas producers with long-dated offtake agreements. Procurement teams are embedding purity guarantees and regeneration service bundles into multi-year supply contracts. The Permian Basin and Appalachian shale plays exhibit this pattern most acutely, where pipeline tariff structures penalize off-spec gas deliveries.
Triethylene Glycol Market Segmentation
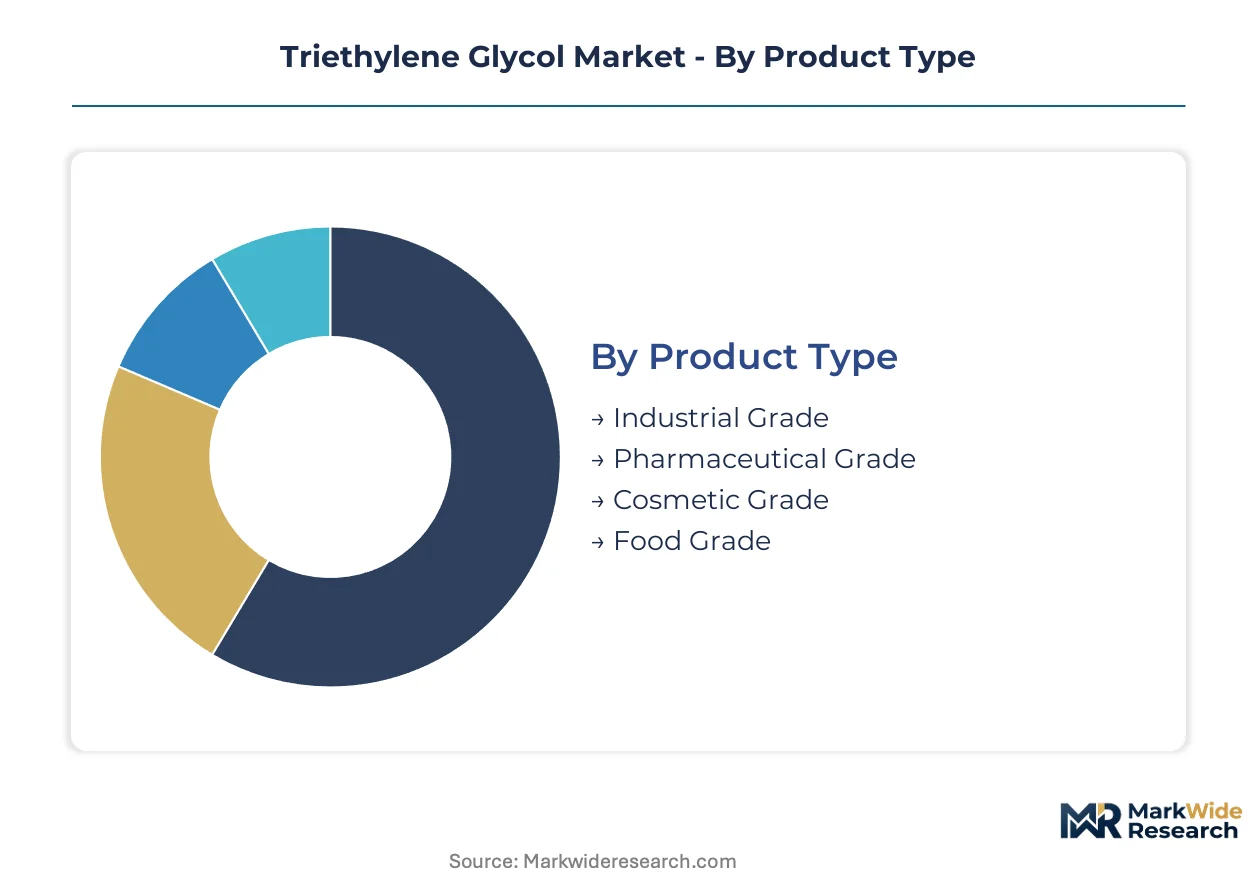
Segmentation in triethylene glycol markets reflects divergent purity standards, regulatory exposure, and customer procurement rhythms. Cycle times vary dramatically across grades, with industrial batches turning weekly while pharmaceutical qualifications stretch across quarters.
Product Type:
Industrial grade commands the shortest replenishment cycles due to bulk natural gas dehydration demand, while pharmaceutical and food grades extend timelines through certification bottlenecks.
- Industrial Grade:This specification carries 95-99% purity with controlled moisture content optimized for natural gas dehydration circuits. Demand concentrates across Texas and the US Gulf Coast petrochemical corridor where midstream operators run continuous TEG circulation systems. EPA New Source Performance Standards for methane emissions are forcing infrastructure refresh cycles that sustain replacement demand.
- Pharmaceutical Grade:Manufactured to USP and EP monograph standards with heavy metal limits below 10 ppm and endotoxin controls for parenteral applications. FDA and EMA tightening of excipient purity standards is elongating qualification timelines for drug delivery systems, compressing supplier pools to GMP-certified distillation operators.
- Cosmetic Grade:Low-odor, low-color specifications for personal care humectant applications.
- Food Grade:FCC-compliant material for food processing moisture control with full contaminant traceability.
Industrial grade dominates installed base. Pharmaceutical grade is where expansion concentrates.
Application:
Volume distribution tracks end-use capital intensity, with antifreeze applications scaling through infrastructure deployment while humectant demand responds to formulation trends in consumer products.
- Antifreeze:The largest consumption segment serving natural gas pipeline dehydration, HVAC systems, and industrial heat transfer fluids. Hydrate formation risks in deepwater gas transmission lines across the Permian Basin and Appalachian shale plays elevate injection rates as the default chemistry.
- Humectant:Moisture-retention functionality for personal care formulations, textiles, and tobacco conditioning. Clean-label cosmetic trends proliferating through European and North American markets are expanding demand faster than traditional industrial applications.
- Solvent:Carrier and co-solvent applications in printing inks, adhesives, and extraction processes.
- Plasticizer:Flexibility modification for synthetic polymers and resin systems.
Antifreeze anchors current volume. Humectant is gaining share fastest.
End User:
Customer concentration reflects sector-specific regulatory exposure, with automotive and pharmaceutical procurement embedding compliance verification that elongates sales cycles versus personal care spot purchasing.
- Automotive:Antifreeze formulations, brake fluid components, and battery thermal management systems. Electric vehicle thermal management architectures are diversifying coolant specifications beyond traditional internal combustion chemistries.
- Personal Care:Skin moisturizers, hair conditioners, and cosmetic bases leveraging hygroscopic properties. Clean-label formulation trends are displacing synthetic alternatives in premium product tiers.
- Pharmaceuticals:Excipient applications for oral solids, parenterals, and topical delivery systems. FDA and EMA stability data requirements are extending supplier qualification timelines.
- Food Processing:Moisture control in packaging and direct food contact applications under FDA and USDA jurisdiction.
Automotive holds the largest contract base. Personal care is climbing the fastest.
Distribution Channel:
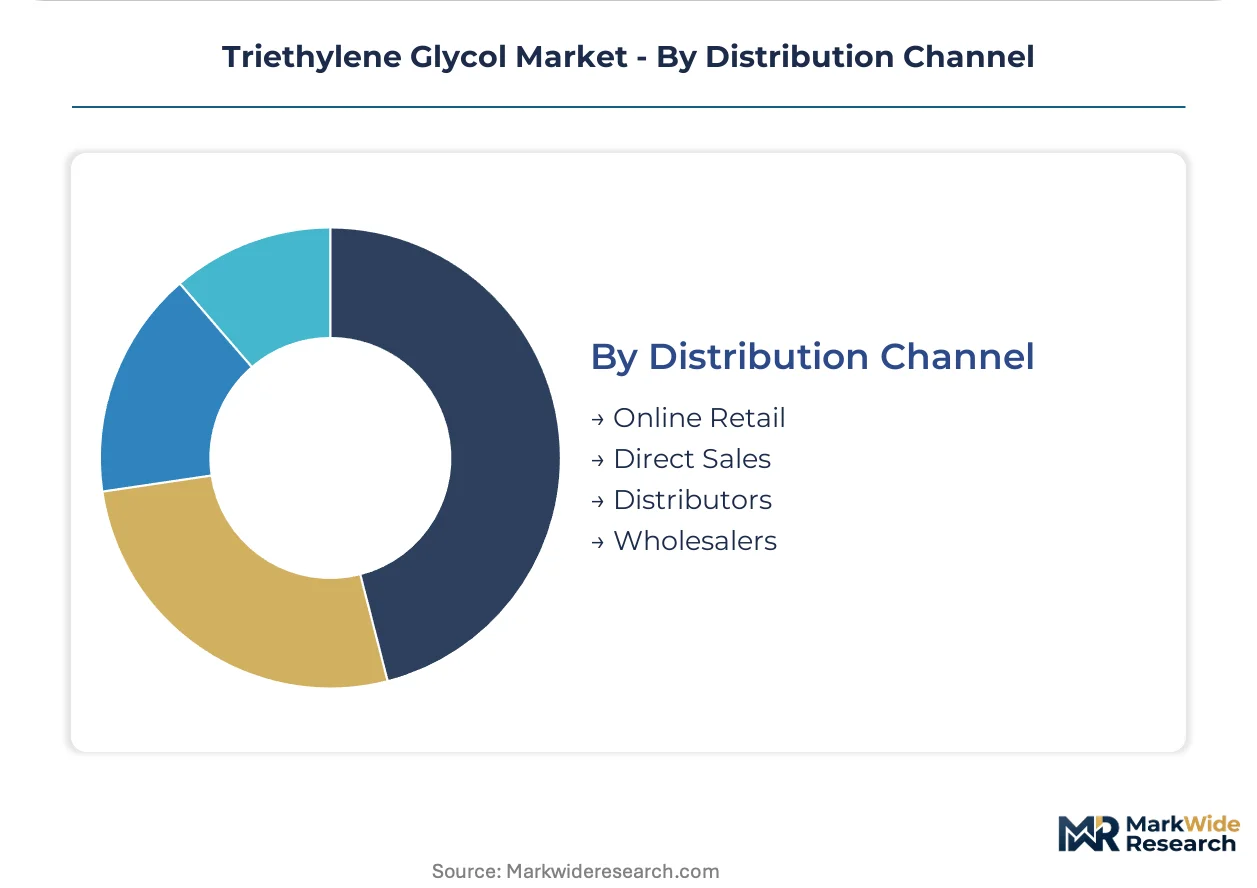
Channel selection tracks order scale and technical service requirements, with direct sales capturing programmed volumes while distributors fragment spot demand across smaller accounts.
- Direct Sales:Long-term supply agreements with integrated gas producers, midstream operators, and pharmaceutical manufacturers. Multi-year contracts embedding purity guarantees and regeneration service bundles are displacing spot-market purchasing among Permian Basin and Appalachian shale operators.
- Distributors:Regional chemical distributors consolidating approved vendor lists to reduce REACH and OSHA compliance audit exposure. Industrial grade flows through this channel to smaller natural gas processors without captive procurement teams.
- Online Retail:Small-volume cosmetic and food grade transactions for formulation laboratories and specialty compounders.
- Wholesalers:Bulk inventory positioning for geographic markets with logistics constraints.
Direct sales dominates committed volume. Distributors are where spot market liquidity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the US Gulf Coast petrochemical corridor while European producers absorb REACH compliance premiums that compress margin flexibility. This asymmetry reshapes trade flows and capacity investment decisions.
United States
Midstream gas processors across Texas and Louisiana drive industrial-grade consumption through continuous TEG circulation systems. EPA New Source Performance Standards mandate methane emissions thresholds that force infrastructure refresh cycles. The Permian Basin anchors dehydration chemical demand as pipeline tariff structures penalize off-spec gas deliveries.
Germany
Pharmaceutical-grade TEG qualification timelines extend through EMA stability data requirements that add 18-24 months to certification cycles. REACH registration under ECHA governance constrains non-compliant import volumes from smaller suppliers. The Rhine-Ruhr industrial cluster concentrates GMP-certified distillation capacity for excipient applications.
China
Ethylene oxide expansion along the Yangtze River Delta secures feedstock for domestic TEG production serving natural gas infrastructure buildout. MIIT process safety standards govern chemical handling protocols at integrated petrochemical complexes. Shandong Province hosts multiple EO-to-glycol conversion trains with downstream dehydration chemical output.
Saudi Arabia
SABIC's integrated gas field-to-chemical complexes reduce logistics exposure for regional TEG supply to Middle East gas processing facilities. The country's national environmental regulator enforces emissions controls at petrochemical installations. The Eastern Province concentration of ethylene derivative capacity supports captive glycol production for domestic and export markets.
Japan
METI energy security priorities sustain strategic stockpiling of dehydration chemicals for LNG import terminal operations. PMDA pharmaceutical regulations align with USP and EP monograph standards for excipient-grade material. The Chubu region around Nagoya maintains specialty chemical distillation expertise for high-purity formulations.
Triethylene Glycol Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and purification segments. The vendor base concentrates around integrated petrochemical complexes with captive ethylene oxide supply, compressing margins for merchant producers dependent on spot feedstock markets. Three archetypes dominate: integrated oil majors with gas field-to-chemical complexes, diversified chemical conglomerates with backward integration into ethylene, and regional specialists focused on pharmaceutical-grade certification. Capacity expansion and asset-light regeneration service partnerships constitute the primary competitive moves reshaping market positioning.
Within the integrated oil major tier, Shell Chemicals and Exxon Mobil Corporation exemplify platform players leveraging hydrocarbon production assets into downstream glycol output. Among diversified chemical conglomerates, BASF SE and Mitsubishi Chemical Corporation occupy positions spanning industrial through pharmaceutical grades. Dow and Huntsman Corporation represent the North American concentration of EO-captive producers with cost-advantaged Gulf Coast positioning.
| Leading Market Players |
|---|
| Huntsman Corporation |
| LyondellBasell Industries |
| Dow |
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| BASF SE |
| Shell Chemicals |
| Exxon Mobil Corporation |
| SABIC |
| Others |
Supply Flow & Price Mechanics
The US Gulf Coast petrochemical corridor concentrates ethylene oxide cracking capacity that feeds downstream TEG distillation trains, translating feedstock security into pricing power for integrated producers while merchant operators absorb spot market volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the dehydration chemical market. Pharmaceutical-grade certification commands premium positioning driven by FDA and EMA purity thresholds alongside GMP-compliant distillation investments. Pricing pressure stems from molecular sieve displacement in cryogenic gas processing where ultra-low dew point specifications favor zeolite alternatives. Midstream gas processors exhibit highest price sensitivity due to pipeline tariff structures that penalize off-spec gas deliveries, while pharmaceutical formulators prioritize qualification reliability over unit cost.
Supply Chain Analysis
Ethylene oxide feedstock availability centers on integrated petrochemical complexes in the United States, Saudi Arabia, and China that control the majority of North American EO output. TEG production draws from ethane-to-ethylene crackers, proprietary purification trains, and specialized regeneration service equipment. Single-source vulnerability concentrates around four Gulf Coast EO complexes that supply non-captive glycol producers. Distribution runs through direct sales channels for committed volumes and regional chemical distributors for spot market liquidity among smaller natural gas processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The triethylene glycol market is positioned for cyclical recovery as EPA methane emissions mandates force infrastructure refresh cycles across US midstream dehydration facilities.
For Market Incumbents: Pre-empt molecular sieve displacement by embedding regeneration service bundles into multi-year supply contracts that lock in offtake volumes. Expand backward integration into ethylene feedstock along the US Gulf Coast to defend margin position against spot EO price spikes. Prioritize GMP-certified distillation capacity additions to capture pharmaceutical-grade excipient demand as FDA and EMA qualification timelines elongate.
For New Entrants and Emerging Players: Pursue asset-light regeneration leasing models that outsource TEG reclamation to service providers without commodity price exposure. Target the Permian Basin and Appalachian shale plays where pipeline tariff structures create urgency for dehydration chemical procurement. Lead with carbon capture solvent applications as an adjacent entry point into power sector decarbonization projects.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated petrochemical operators with captive ethylene oxide supply and proprietary purification infrastructure. Long-term viability hinges on regulatory chemistry mandates that tighten purity thresholds across end-use verticals. Acquisition candidates include regional specialists with pharmaceutical-grade certification capabilities. Monitor EPA New Source Performance Standards enforcement intensity as the primary inflection indicator for replacement demand cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Captive EO supply secures cost-advantaged TEG output against spot market volatility. |
| Pharmaceutical-Grade Certification Investment | GMP-compliant distillation trains capture premium positioning as FDA and EMA standards tighten. |
| Asset-Light Regeneration Service Partnerships | Recurring revenue models displace commodity price exposure for midstream gas processors. |
| Carbon Capture Solvent Application Development | TEG derivative compatibility with post-combustion CO2 absorption opens power sector adjacencies. |
| Long-Term Supply Agreement Structuring | Multi-year contracts embedding purity guarantees consolidate share among integrated gas producers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and ACC industry reports to establish baseline supply and demand parameters. Primary interviews engaged plant managers at ethylene oxide complexes, procurement leads at midstream gas processors, technical R&D directors at glycol producers, and distribution channel partners across North American petrochemical corridors. Bottom-up volume estimates triangulated against top-down capacity assessments and regulatory filing disclosures.
Forecast inputs span grade tier segmentation across industrial, pharmaceutical, and cosmetic specifications; end-use industry concentration in natural gas dehydration, personal care, and pharmaceutical excipients; and regional production hub dynamics across the US Gulf Coast, Rhine-Ruhr, and Yangtze River Delta. CAGRs were derived through demand elasticity modeling against EPA emissions rule implementation timelines and shale infrastructure deployment patterns. Ethylene feedstock cost curves and REACH registration compliance costs informed margin trajectory assumptions across the projection horizon.
Sensitivities concentrate around EPA enforcement intensity, ethylene oxide supply disruptions at integrated complexes, and molecular sieve technology cost curves in cryogenic applications. Forecasts reflect assumptions regarding regulatory chemistry mandate adoption rates and midstream operator capital deployment timing. Quarterly review of EPA compliance audit data, ethylene contract price movements, and pharmaceutical qualification timeline extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Alanine Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Acetic Acid Market