
 Terephthalic Aldehyde Market | 2026-2036
Terephthalic Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Terephthalic Aldehyde Market Outlook
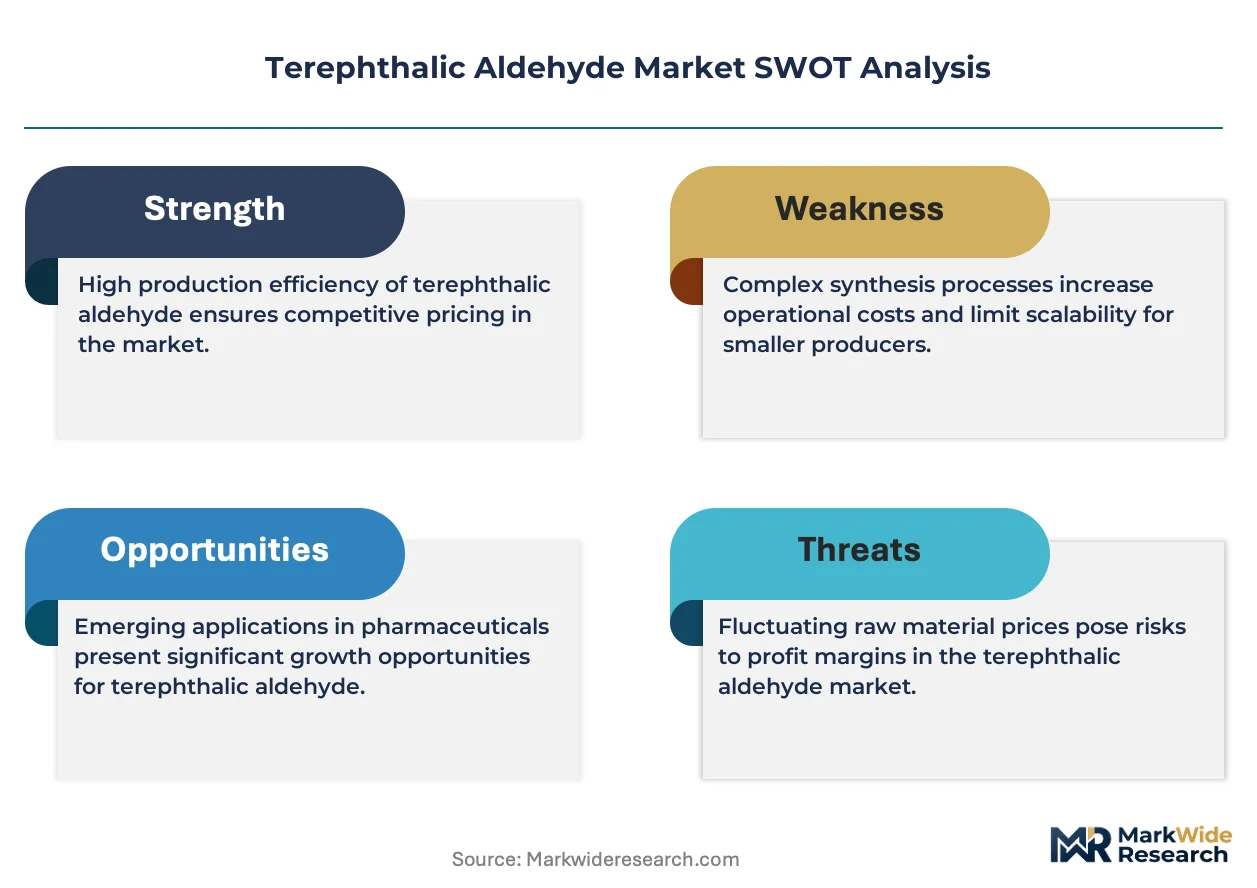
Specialty chemical margin pools is tilting from commodity bulk sales toward pharmaceutical-grade purification and custom synthesis services. Haihang Industry Co. Ltd. leverages its Shandong manufacturing base to dominate industrial-grade exports. Hunan Astar Biochemical Technology Co. Ltd. specializes in high-purity batches for European pharmaceutical offtake. Sigma-Aldrich Corporation controls laboratory-grade distribution channels across North American research institutions.
Terephthalic aldehyde (1,4-benzenedicarbaldehyde, CAS 623-27-8) functions as a dialdehyde aromatic intermediate with two formyl groups para-substituted on a benzene ring, synthesized primarily via controlled oxidation of para-xylene derivatives or Vilsmeier-Haack formylation routes, serving as a critical building block for polyester modification, pharmaceutical active ingredient synthesis, and luminescent polymer precursors. Pharmaceutical grade commands the strongest margin expansion as CDMOs tighten incoming raw material specifications under EMA and FDA drug master file requirements. Industrial grade remains volume-dominant through textile and resin applications where cost sensitivity anchors procurement decisions toward Chinese bulk producers.
EPA toxic substance control reviews and REACH authorization lists are elevating analytical documentation burdens for importers into the United States and European Union respectively. China's NMPA alignment with ICH Q3D elemental impurity guidelines is reshaping export qualification protocols for domestic manufacturers. Stakeholders must monitor regulatory divergence between major import jurisdictions to avoid batch rejection costs and customs detention.
Market Dynamics
Pharmaceutical-grade purification requirements are compressing industrial-grade margin pools as CDMOs enforce EMA and FDA drug master file specifications on dialdehyde aromatic intermediates. This regulatory tightening is forcing capacity reallocation across Chinese bulk producers and European specialty distributors.
Growth Catalysts
- REACH Authorization Lists:ECHA's tightening purity benchmarks for imported chemical intermediates are elevating documentation standards that favor established high-purity manufacturers with existing EU qualified supplier status.
- CDMO Expansion:Contract development and manufacturing organizations in China and India are scaling pharmaceutical intermediate capacity, pulling dialdehyde demand for active ingredient synthesis.
- Luminescent Polymer R&D:OLED precursor applications in South Korean and Japanese display manufacturing are creating specialized offtake channels for ultra-high-purity terephthalic aldehyde batches.
Market Restraints
- Para-xylene Feedstock Volatility:Aromatic feedstock price swings tied to crude oil benchmarks compress margin predictability for oxidation-route producers in Shandong province.
- Single-Geography Supply Concentration:Industrial-grade capacity clustering in eastern China creates concentration risk for European and North American textile resin formulators.
- Vilsmeier-Haack Waste Profile:Phosphorus oxychloride byproduct disposal costs and environmental permitting constraints limit greenfield expansion of formylation-based production.
Strategic Opportunities
- Indian Pharmaceutical Intermediates:CDSCO's alignment with ICH Q3D guidelines is opening export qualification pathways for domestic manufacturers targeting European generic API producers.
- Bioconjugation Chemistry:Dialdehyde crosslinking applications in antibody-drug conjugate manufacturing are emerging as a high-margin specialty channel distinct from traditional polymer modification.
- EPA Green Chemistry Incentives:Safer solvent substitution mandates under the Toxic Substances Control Act are creating preference windows for aqueous-phase oxidation technologies.
Industry Challenges
- Analytical Methodology Standardization:Divergent residual solvent testing protocols between FDA, EMA, and NMPA create multi-jurisdiction qualification burdens for batch release.
- Legacy Equipment Retrofit Costs:Glass-lined reactor fleets designed for commodity bulk production require capital-intensive upgrades to meet pharmaceutical-grade containment and cleaning validation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terephthalic Aldehyde Market |
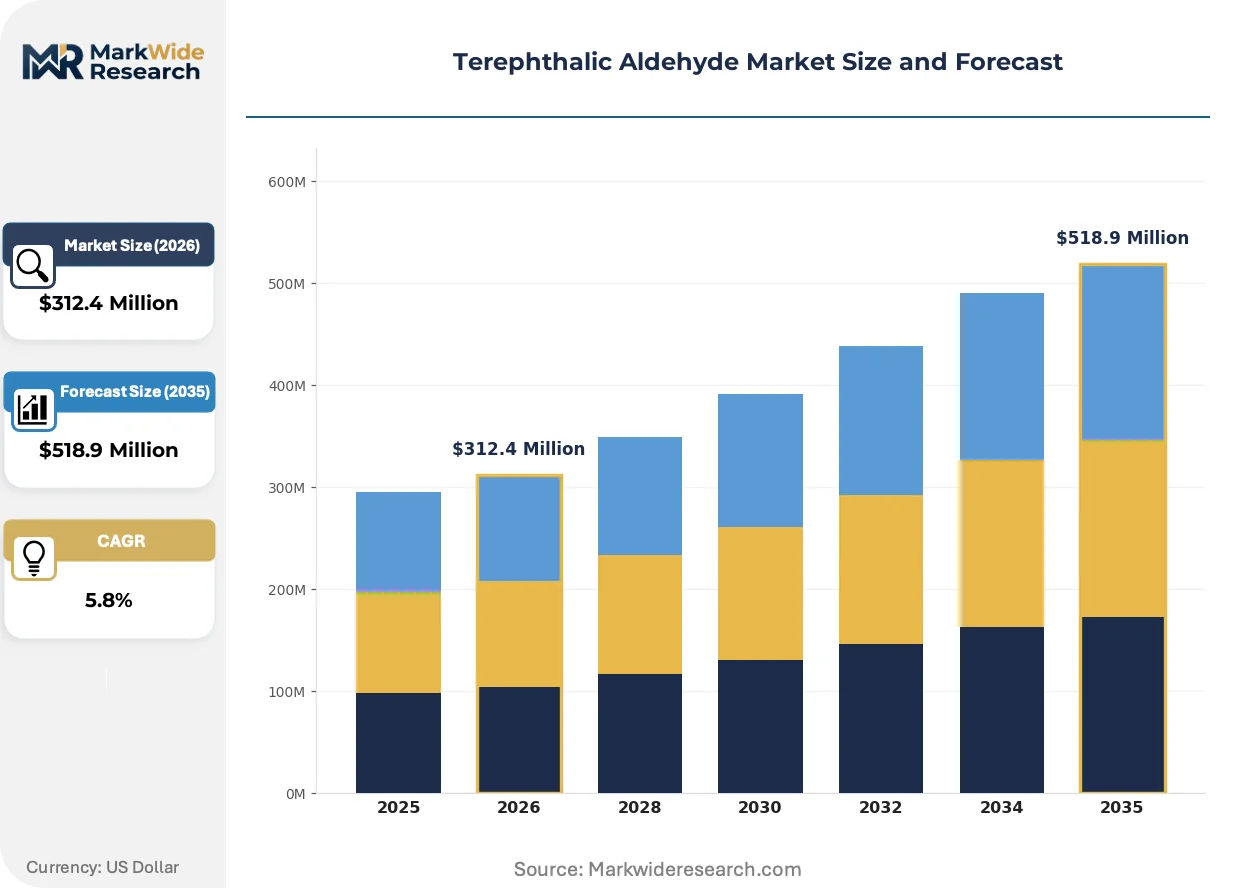
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Laboratory Grade Application: Textiles, Resins, Coatings, Adhesives End User: Manufacturers, Laboratories, Chemical Companies, Pharmaceuticals Delivery Mode: Bulk, Packaged, Liquid, Solid |
| Companies Covered | Haihang Industry Co. Ltd., Wuhai Xinye Chemical Co. Ltd., Hunan Astar Biochemical Technology Co. Ltd., Tokyo Chemical Industry Co. Ltd., Dalian Richfortune Chemicals Co. Ltd., Hebei Xingyu Chemical Ltd., Sigma-Aldrich Corporation, Alfa Aesar, Acros Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terephthalic Aldehyde Market Strategic Shifts
Process analytical technology integration and green chemistry route development are redefining competitive capability in dialdehyde aromatic production. These shifts are compressing the gap between industrial and pharmaceutical grade qualification timelines.
Continuous flow oxidation reactors equipped with real-time spectroscopic monitoring are digitizing batch record documentation for EMA and FDA submission packages. CDMO technical teams in Basel and Boston are adopting these systems to compress drug master file amendment cycles. The technology is digitizing quality assurance workflows that previously required manual chromatographic verification.
REACH's 2025 authorization sunset dates for certain aromatic solvent carriers are forcing reformulation of Vilsmeier-Haack process conditions. German and Swiss specialty chemical producers are piloting ionic liquid-mediated formylation to maintain European manufacturing footprint. Pharmaceutical-grade producers with existing authorized substance registrations are capturing margin premiums as competitors face supply continuity gaps.
Specification-driven spot purchasing is displacing annual volume contracts among North American research institutions and mid-tier CDMOs. Sigma-Aldrich and regional distributors are responding with SKU proliferation across purity grades and packaging formats. This pattern is most visible in Massachusetts and California biotech clusters where project-based funding creates demand volatility.
Terephthalic Aldehyde Market Segmentation
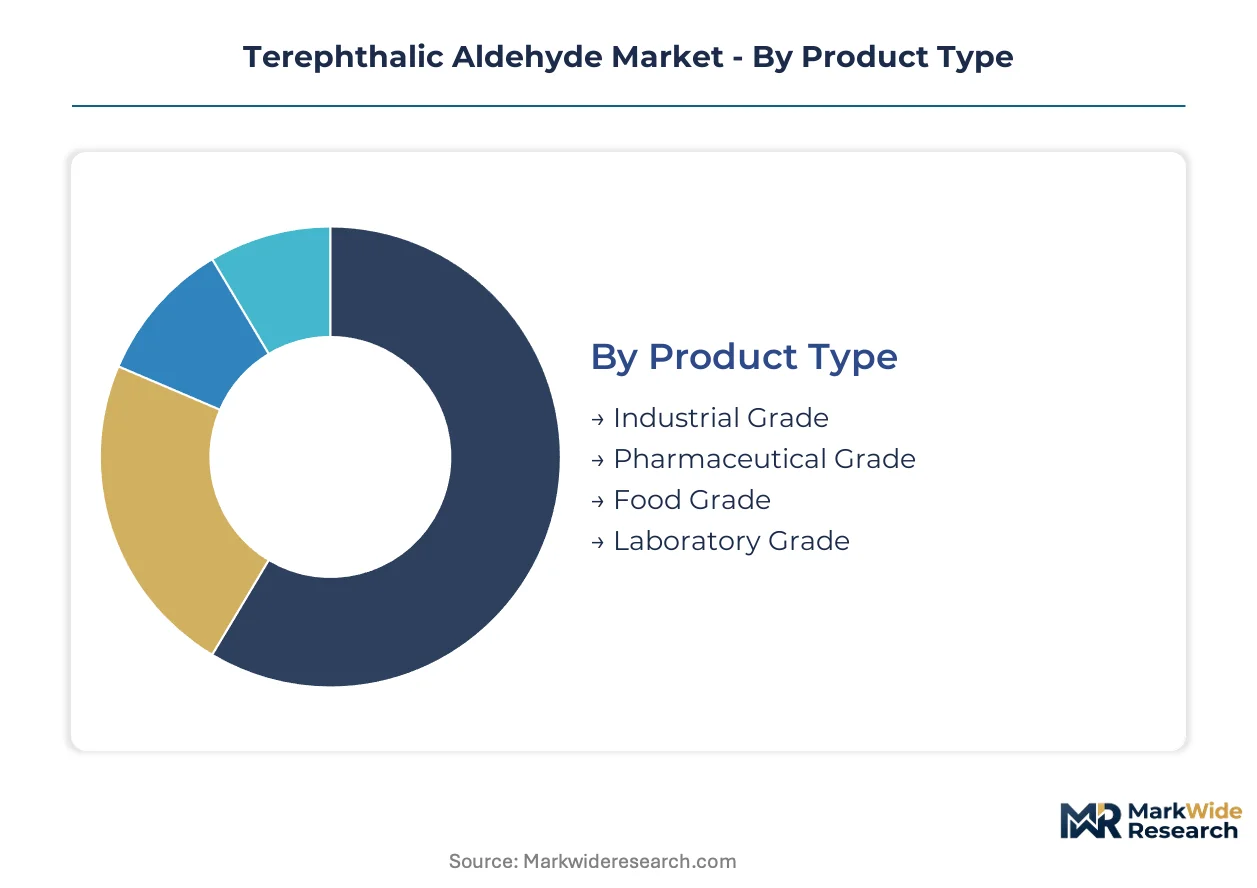
Terephthalic aldehyde segmentation reflects divergent purity protocols across pharmaceutical, industrial, and research channels. Specification tiers determine regulatory documentation burdens, supply chain qualification timelines, and margin capture potential for producers.
Product Type:
After-sales service intensity escalates dramatically from industrial bulk shipments to pharmaceutical-grade batch certification, with laboratory-grade demanding the highest technical support frequency.
- Industrial Grade:Standard dialdehyde aromatic purity for textile modification and resin crosslinking applications. Demand concentrates in Shandong province textile clusters where cost sensitivity anchors procurement toward oxidation-route bulk producers facing para-xylene feedstock volatility.
- Pharmaceutical Grade:Ultra-high purity with full EMA and FDA drug master file documentation packages. CDMO technical teams in Basel and Boston enforce incoming raw material specifications that compress qualification timelines and elevate supplier switching costs.
- Food Grade:Compliance-focused purity tier meeting FSSAI and FDA food contact substance requirements with specialized migration testing protocols.
- Laboratory Grade:Research-scale batches with certificate of analysis variability tolerances suited to method development and academic synthesis.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is ahead.
Application:
Cost tier stratification separates commodity textile offtake from specialty coating formulations where performance premiums justify specification investment.
- Textiles:Polyester modification and fiber crosslinking dominate oxidation-route consumption. Shandong province manufacturers anchor volume demand despite margin compression from crude-linked feedstock swings.
- Resins:Formaldehyde-free curing systems for wood panel and composite applications. European REACH solvent restrictions are accelerating waterborne resin formulation shifts in German and Italian manufacturing.
- Coatings:High-performance automotive and industrial finishes requiring dialdehyde aromatic crosslink density.
- Adhesives:Structural bonding applications in construction and electronics assembly with thermal stability specifications.
Textiles commands the largest volume share. Coatings demonstrates the steepest expansion trajectory as automotive OEMs tighten volatile organic compound emission standards.
End User:
Customer type determines procurement rhythm, with Manufacturers running continuous bulk contracts against Pharmaceuticals operating project-based spot purchasing with SKU proliferation requirements.
- Manufacturers:Integrated textile and resin producers with annual volume contracts and specification lock-in periods spanning multiple feedstock price cycles.
- Pharmaceuticals:CDMOs and API producers enforcing ICH Q3D elemental impurity compliance with batch-specific analytical documentation.
- Laboratories:Research institutions in Massachusetts and California biotech clusters with grant-funded demand volatility and packaging format diversity requirements.
- Chemical Companies:Specialty distributors and formulation houses serving mid-tier industrial accounts with blended product portfolios.
Manufacturers absorb the highest absolute tonnage. Pharmaceuticals is expanding most quickly as contract manufacturing scales in China and India.
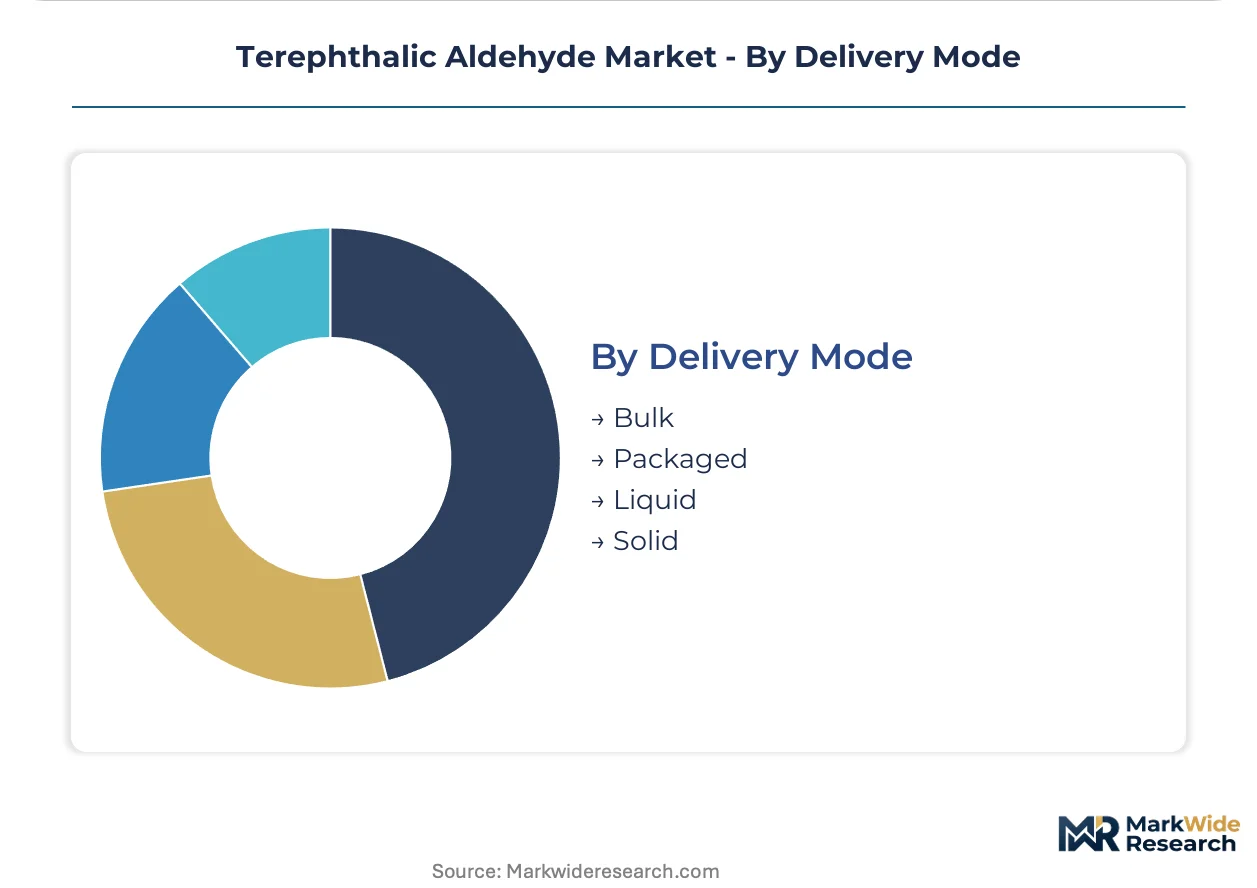
Delivery Mode:
Supply concentration in eastern China shapes logistics configuration, with Bulk dominating industrial-grade flows and Packaged serving fragmented research demand.
- Bulk:Tanker and railcar shipments for textile and resin manufacturers with dedicated storage infrastructure and just-in-line feedstock integration.
- Packaged:Drum and pail formats for mid-volume chemical companies and regional distributors requiring inventory flexibility.
- Liquid:Solution-phase delivery for coatings and adhesives formulators seeking direct metered addition without solid handling.
- Solid:Crystalline or powdered terephthalic aldehyde for pharmaceutical synthesis and laboratory-scale reactions with precise stoichiometry control.
Bulk leads by volume throughput. Packaged is gaining share fastest as specification-driven spot purchasing displaces annual contracts among North American research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese industrial-grade buyers exhibit extreme feedstock price elasticity, while European pharmaceutical offtake shows near-zero substitution willingness. This demand-elasticity contrast shapes regional investment patterns across oxidation-route and formylation-based production.
China
Shandong province textile clusters absorb oxidation-route bulk volumes despite margin compression from crude-linked para-xylene volatility. NMPA alignment with ICH Q3D guidelines is reshaping export qualification protocols for domestic manufacturers targeting European CDMOs. The Yangtze River Delta pharmaceutical intermediate corridor is scaling capacity to serve Basel and Boston drug master file requirements.
Germany
REACH authorization sunset dates for aromatic solvent carriers are forcing Vilsmeier-Haack process reformulation among specialty chemical producers. ECHA tightening purity benchmarks elevates documentation standards that favor established high-purity manufacturers with existing EU qualified supplier status. The Rhine-Ruhr industrial belt is piloting ionic liquid-mediated formylation to maintain domestic manufacturing footprint.
United States
Massachusetts and California biotech clusters drive specification-driven spot purchasing with grant-funded demand volatility. EPA toxic substance control reviews under the Toxic Substances Control Act are elevating analytical documentation burdens for importers. Greater Boston CDMO technical teams are adopting continuous flow oxidation reactors to compress drug master file amendment cycles.
India
CDSCO alignment with ICH Q3D guidelines is opening export qualification pathways for domestic manufacturers targeting European generic API producers. Maharashtra and Gujarat pharmaceutical intermediate corridors are scaling dialdehyde capacity to serve contract manufacturing demand. Mumbai-Pune CDMO clusters enforce incoming raw material specifications that compress supplier qualification timelines.
Japan
South Korean and Japanese display manufacturers are creating specialized offtake channels for ultra-high-purity terephthalic aldehyde batches serving OLED precursor applications. METI industrial policy is supporting luminescent polymer R&D commercialization. The Kansai-Osaka chemical manufacturing belt is concentrating high-purity batch production for Asian electronics supply chains.
Terephthalic Aldehyde Market Competitive Environment
Industrial-grade bulk producers and pharmaceutical-grade specialists split the market along purity-documentation fault lines. The vendor base concentrates among Chinese oxidation-route fabricators serving textile demand and European-Japanese distributors controlling research-grade channels. Three archetypes dominate: Shandong-based bulk manufacturers, Swiss-German specialty distributors with REACH-authorized registrations, and North American laboratory chemical suppliers with SKU proliferation capabilities. Capacity reallocation and regulatory qualification investments represent the dominant competitive moves as margin pools compress toward high-purity segments.
Among Chinese manufacturers, Haihang Industry Co. Ltd., Hunan Astar Biochemical Technology Co. Ltd., and Dalian Richfortune Chemicals Co. Ltd. exemplify the Shandong-northeast industrial cluster concentration. These entities occupy positions within the oxidation-route bulk production archetype. Sigma-Aldrich Corporation anchors the North American laboratory-grade distribution tier with research institution channel control. Tokyo Chemical Industry Co. Ltd. sits within the Japanese specialty chemical exporter archetype serving Asian electronics and pharmaceutical demand.
| Leading Market Players |
|---|
| Haihang Industry Co. Ltd. |
| Wuhai Xinye Chemical Co. Ltd. |
| Hunan Astar Biochemical Technology Co. Ltd. |
| Tokyo Chemical Industry Co. Ltd. |
| Dalian Richfortune Chemicals Co. Ltd. |
| Hebei Xingyu Chemical Ltd. |
| Sigma-Aldrich Corporation |
| Alfa Aesar |
| Acros Organics |
| Others |
Value Chain & Pricing Dynamics
Shandong province oxidation-route producers anchor industrial-grade supply, compressing margin pools downstream toward pharmaceutical-grade purification and CDMO technical services. Para-xylene feedstock volatility transmits directly into bulk pricing, while REACH-authorized registrations in Germany and Switzerland capture premium tiers through documentation barriers.
Pricing Analysis
After-sales certification revenue from drug master file amendment support and batch-specific analytical documentation drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical, industrial, and laboratory grades reflects divergence in purity protocols and regulatory documentation burdens. Cost compression in industrial-grade runs through crude-linked para-xylene volatility, with Shandong bulk producers facing the steepest price sensitivity. CDMO technical teams in Basel and Boston exhibit near-zero substitution willingness for qualified pharmaceutical-grade supply.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become standard for Shandong textile cluster procurement, locking in annual volume commitments against feedstock price cycles. Raw material dependencies rest on para-xylene derivatives, phosphorus oxychloride for Vilsmeier-Haack routes, and ionic liquid carriers for greenfield European production. Single-geography concentration in eastern China creates tariff exposure and logistics chokepoint vulnerability for North American and European resin formulators. Distribution runs through Swiss-German specialty distributors with REACH-authorized registrations and North American laboratory chemical suppliers with SKU proliferation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terephthalic aldehyde sits in early-cycle expansion as CDMOs scale pharmaceutical intermediate capacity and OLED precursor applications commercialize across South Korean and Japanese display manufacturing.
For Market Incumbents: Entrench qualified supplier status with EMA and FDA through continuous flow oxidation reactor investments that compress drug master file amendment cycles. Backward integration into para-xylene derivatives secures margin predictability against crude-linked volatility. CDMO technical teams in Basel and Boston enforce incoming raw material specifications that elevate switching costs for established registrants. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical intermediate corridors where CDSCO alignment with ICH Q3D guidelines opens export qualification pathways. Bioconjugation chemistry applications in antibody-drug conjugate manufacturing represent the most penetrable white-space segment. Target Maharashtra and Gujarat CDMO clusters with aqueous-phase oxidation technologies that qualify for EPA green chemistry preference windows. For Investors and Strategic Acquirers: Capital is best deployed toward Swiss-German specialty distributors with existing REACH-authorized substance registrations and ionic liquid process pilots. Long-term viability hinges on regulatory qualification moats rather than commodity volume scale. The signal to watch is ECHA authorization sunset date enforcement that forces supply continuity gaps among non-registered competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Oxidation Scale-Up | Real-time spectroscopic monitoring digitizes EMA and FDA batch documentation for CDMOs. |
| Ionic Liquid Process Transition | German and Swiss producers pilot formylation routes that maintain EU manufacturing footprint post-REACH sunset. |
| Backward Integration into Para-Xylene | Shandong bulk producers secure feedstock cost predictability against crude benchmark volatility. |
| ICH Q3D Compliance Investment | Indian and Chinese manufacturers unlock European generic API producer qualification pathways. |
| OLED Precursor Channel Development | Ultra-high-purity batches serve South Korean and Japanese display manufacturing specialized offtake. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed chemical producers, ECHA authorization lists, and NMPA export qualification protocols. Plant managers at Shandong oxidation facilities, procurement leads at European textile resin formulators, CDMO technical directors in Basel and Boston, and distribution channel partners in North American laboratory supply provided structured input. Bottom-up volume triangulation from grade-specific production estimates was cross-checked against top-down demand aggregation across textile, pharmaceutical, and electronics applications.
Forecast inputs span pharmaceutical-grade purity tiers, industrial-grade volume contracts, research-grade spot purchasing patterns, and regional production hub concentration across the projection horizon. Analytical frameworks modeled grade tier, end-use industry, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate synthesis anchored to observable capacity expansion and CDMO contract announcements. Feedstock price elasticity and regulatory qualification timeline compression served as industry-specific forecast inputs.
Stress conditions across para-xylene price bands, REACH authorization enforcement intensity, and CDMO outsourcing penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment trajectories and capacity reallocation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Alanine Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Bio-Acetic Acid Market