
 USA and Canada Potassium Sulfate Market | 2026-2036
USA and Canada Potassium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Potassium Sulfate Market Analytics
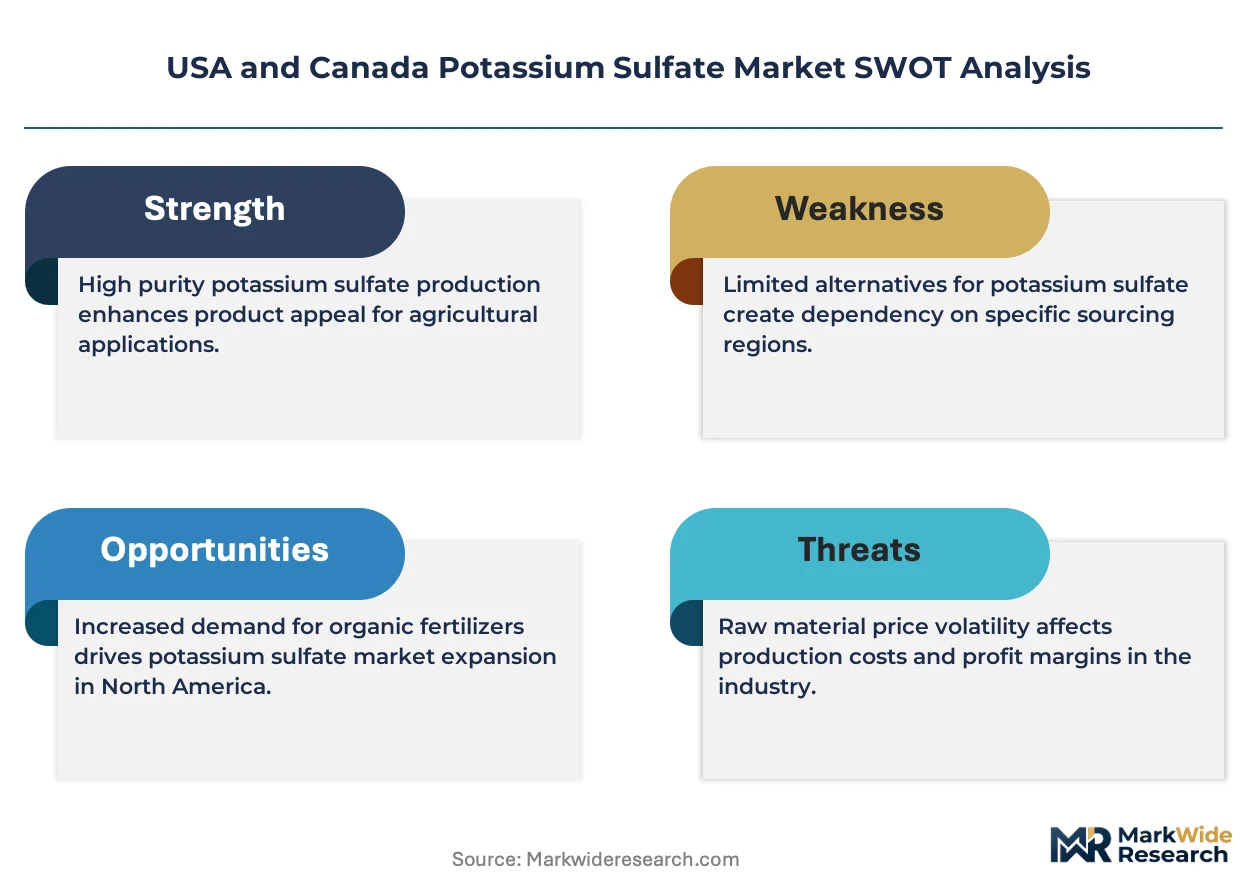
High-purity agricultural-grade potassium sulfate is rotating toward premium positioning as chloride-sensitive crops expand acreage. Nutrien leverages its integrated potash network to secure feedstock access across Saskatchewan and Manitoba. Mosaic Company anchors its competitive stance through phosphate-sulfate co-production economics at Florida facilities. Compass Minerals specializes in evaporite-derived sulfate salts from Great Salt Lake brine operations.
Potassium sulfate is a binary inorganic salt containing potassium and sulfur in a 2:1 molar ratio, typically manufactured through the Mannheim process reacting potassium chloride with sulfuric acid at temperatures exceeding 600°C, and serves primarily as a chloride-free fertilizer source for sulfur-deficient soils and chloride-intolerant crops. Granular formulations dominate volume flows into bulk blending operations, while liquid potassium sulfate captures expanding drip-irrigation and fertigation channels in California and Florida vegetable production. Crystal-grade product occupies narrower industrial and food-additive segments where solubility specifications exceed agricultural thresholds.
EPA nutrient management guidelines under the Clean Water Act constrain phosphorus and nitrogen runoff, indirectly elevating potassium sulfate as a lower-risk alternative for balanced fertilization programs. USDA conservation programs and state-level 4R nutrient stewardship frameworks in Iowa and Illinois shape application timing and placement standards. Canadian Food Inspection Agency oversight of fertilizer registration creates cross-border product harmonization requirements. Stakeholders must monitor evolving sulfur dioxide emissions regulations at Mannheim process facilities and assess brine extraction permitting risks at evaporite operations.
Market Dynamics
Chloride-free fertilizer mandates from the EPA's Clean Water Act nutrient management guidelines are restructuring potassium sulfate procurement across specialty crop regions. Sulfur-deficient soil conditions in the US Corn Belt compound this regulatory pull, forcing bulk blenders and retail agronomists to rebalance potassium sourcing away from muriate of potash.
Growth Catalysts
- 4R Nutrient Stewardship Frameworks:Iowa and Illinois state programs mandate precise fertilizer placement and timing, elevating potassium sulfate as a controlled-release option for sulfur-deficient zones.
- Drip Irrigation Expansion:California Central Valley vegetable producers are converting acreage to fertigation systems that require fully soluble, chloride-free potassium sources.
- Sulfur Soil Depletion:Atmospheric sulfur deposition has fallen below crop removal rates across the Corn Belt, creating agronomic dependency on supplemented sulfate inputs.
Market Restraints
- Mannheim Process Energy Intensity:Sulfuric acid and thermal energy inputs account for substantial production cost exposure, with natural gas price volatility compressing facility margins.
- Evaporite Permitting Risk:Great Salt Lake brine extraction operations face water rights and environmental review delays that constrain sulfate salt output scalability.
- Potassium Chloride Substitution:Standard muriate of potash retains cost advantage for chloride-tolerant row crops, limiting potassium sulfate penetration in price-sensitive segments.
Strategic Opportunities
- Controlled-Release Formulation Development:Polymer-coated potassium sulfate granules align with precision agriculture adoption curves and command premium positioning in specialty markets.
- Canadian Prairie Expansion:Saskatchewan and Manitoba pulse crop acreage growth creates chloride-sensitive demand pockets currently underserved by regional distribution infrastructure.
- Organic Certification Channel:OMRI-listed potassium sulfate captures price premiums in organic vegetable and fruit segments where synthetic chloride fertilizers are prohibited.
Industry Challenges
- Mannheim Emissions Compliance:Sulfur dioxide scrubbing upgrades at high-temperature reaction facilities require capital deployment amid uncertain regulatory enforcement timelines.
- Blending Equipment Compatibility:Bulk fertilizer terminals must segregate potassium sulfate from standard potash to prevent chloride contamination, complicating logistics and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Potassium Sulfate Market |
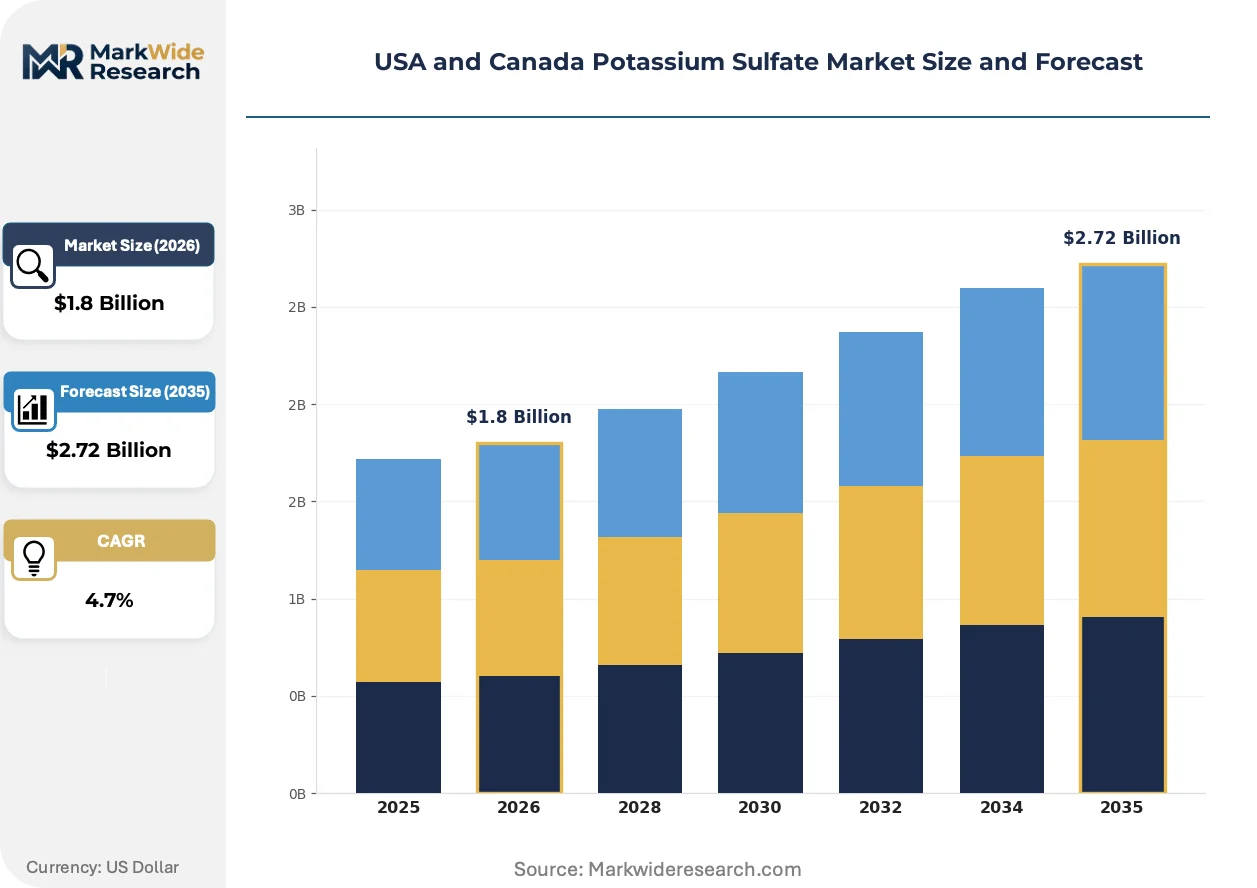
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Crystal Application: Agricultural Fertilizers, Industrial Processes, Animal Feed, Food Preservation End User: Agronomists, Food Manufacturers, Feed Producers, Chemical Plants Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Nutrien, Mosaic Company, Compass Minerals, SQM, K+S Group, Yara International, ICL, Jost Chemical Co., American Elements, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Potassium Sulfate Market Evolving Landscape
Precision agriculture hardware and chloride-free input requirements are converging to reshape how potassium sulfate reaches farmgate. Product formulation, regulatory compliance architecture, and procurement channels are all undergoing simultaneous recalibration.
Liquid potassium sulfate concentrate is fragmenting traditional granular distribution channels in high-value vegetable production. California and Florida drip-irrigation operators are adopting bulk liquid delivery systems that bypass conventional wholesale blending infrastructure. This shift compresses margins for regional fertilizer distributors while creating direct-supply relationships between manufacturers and large-scale produce operations.
EPA nutrient management guidelines under the Clean Water Act are tightening phosphorus and nitrogen runoff thresholds across watersheds draining into the Mississippi River basin. These constraints indirectly elevate potassium sulfate as a lower-risk alternative for balanced fertilization programs in corn-soy rotations. Iowa and Illinois agronomy retailers are reformulating recommendations to emphasize chloride-free potassium where sulfur deficiency co-occurs with phosphorus restrictions.
Certification-driven procurement is displacing commodity-grade purchasing in organic and specialty crop segments. OMRI listing and food-grade purity specifications now filter supplier selection before price negotiation begins. This behavioral shift concentrates volume with manufacturers maintaining dual agricultural-industrial production capabilities, squeezing single-grade competitors in California and Florida premium markets.
USA and Canada Potassium Sulfate Market Segmentation
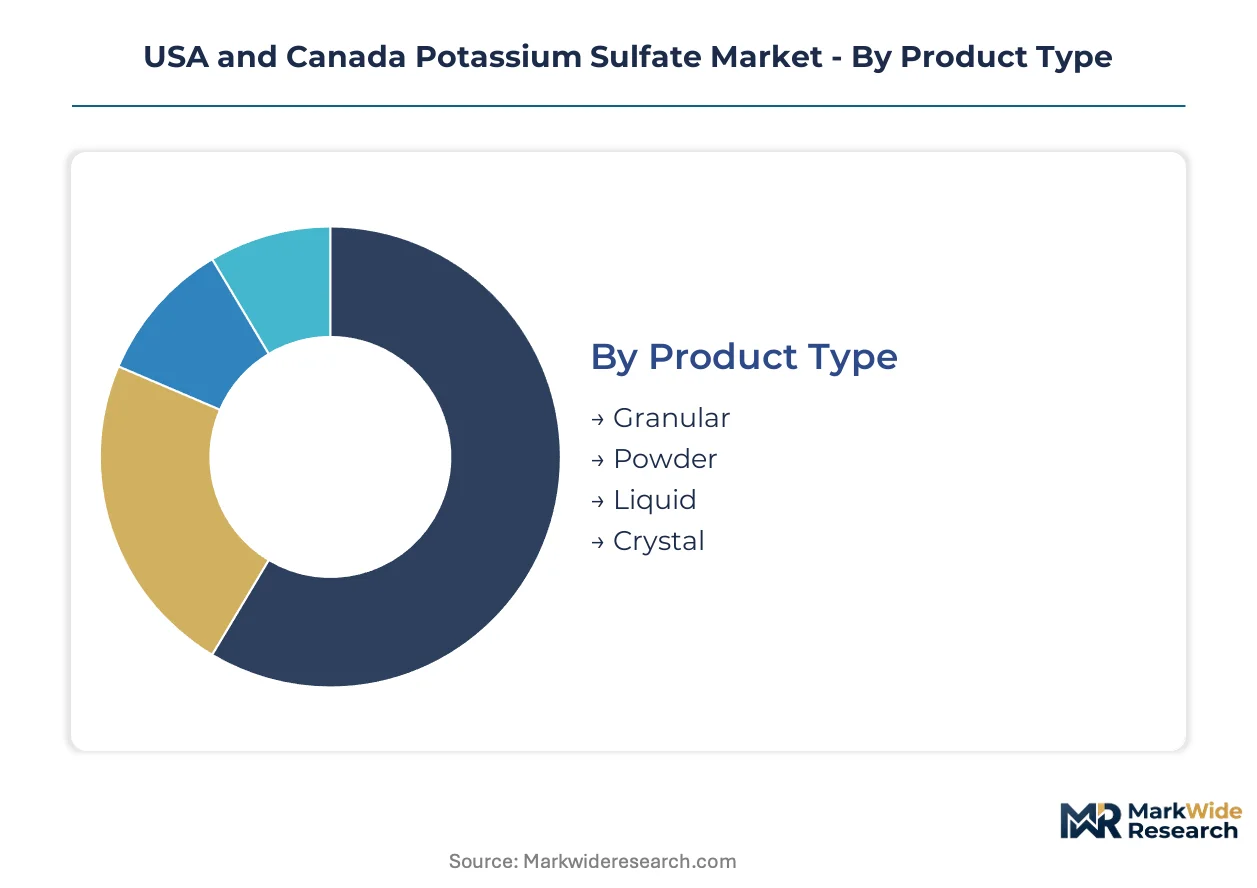
Potassium sulfate procurement patterns diverge sharply across product forms and customer types in the USA and Canada. Segmentation reveals where chloride-free specifications command premium positioning versus commodity-grade competition.
Product Type:
Granular formulations dominate domestic bulk blending infrastructure, while liquid concentrates serve export-adjacent specialty crop zones in California and Florida.
- Granular:Standard prill size ranges from 2-4mm for mechanical spreading compatibility. Iowa and Illinois bulk blenders favor this form for sulfur-deficient Corn Belt corn-soy rotations where chloride sensitivity intersects with high-volume potassium demand.
- Liquid:Fully soluble concentrate at 50-52% K₂O equivalence enables fertigation injection without filtration. California Central Valley vegetable producers and Florida greenhouse operators are converting acreage to drip systems that bypass granular wholesale channels entirely.
- Powder:Fine-ground material below 0.5mm serves industrial compounders and specialty blenders requiring rapid dissolution kinetics.
- Crystal:High-purity evaporite-derived product meets food-additive and pharmaceutical specifications where solubility thresholds exceed agricultural grades.
Granular holds the largest share; momentum sits with liquid as fertigation expands.
Application:
Cost tier stratification separates premium chloride-free agricultural grades from commodity industrial volumes.
- Agricultural Fertilizers:Chloride-free potassium source for sulfur-deficient soils and salt-sensitive crops. EPA Clean Water Act nutrient management guidelines in the Mississippi River watershed indirectly elevate this segment as phosphorus restrictions force rebalancing toward sulfate-based potassium.
- Industrial Processes:Glass manufacturing, dye production, and chemical synthesis consume standard-grade material without chloride sensitivity constraints. Pricing follows sulfur and potash feedstock indices rather than agronomic premiums.
- Animal Feed:Potassium supplementation for ruminant diets requires feed-grade certification under CFIA and state agriculture department oversight.
- Food Preservation:Crystal-grade product with FCC and food-additive purity specifications serves processed fruit and vegetable applications where chloride alternatives alter taste profiles.
Agricultural fertilizers command margin premiums; industrial processes represent volume scale.
End User:
Customer sophistication determines specification stringency and procurement channel selection.
- Agronomists:Certified crop advisors in Iowa, Illinois, and California Central Valley specify potassium sulfate for 4R Nutrient Stewardship compliance and sulfur deficiency correction.
- Food Manufacturers:Processors of organic and specialty crops require OMRI-listed or food-grade certified material with chain-of-custody documentation.
- Feed Producers:Ration formulators blend potassium sulfate into mineral premixes for dairy and beef operations across Wisconsin and Alberta.
- Chemical Plants:Industrial compounders purchase standard-grade material through long-term supply contracts indexed to sulfur and potash benchmarks.
Agronomists drive premium-grade demand; chemical plants anchor baseline volume.
Distribution Channel:
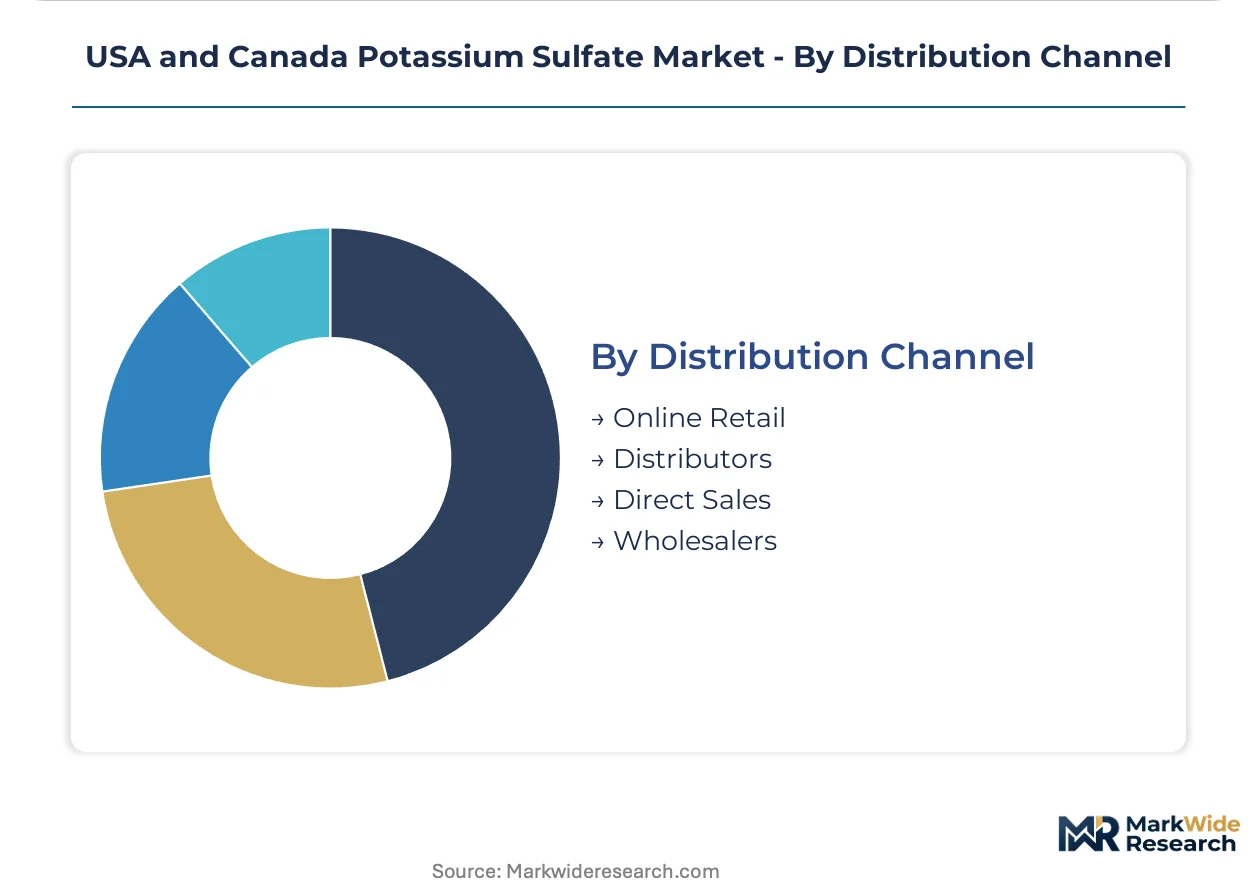
Channel selection reflects shipment scale, urgency, and technical support requirements.
- Distributors:Regional fertilizer wholesalers in the Corn Belt maintain segregated potassium sulfate storage to prevent chloride cross-contamination. Iowa and Illinois retail agronomy networks depend on this channel for seasonal availability.
- Direct Sales:Large-scale California and Florida vegetable producers negotiate manufacturer-direct contracts for liquid concentrate delivered to on-farm storage. This channel bypasses traditional wholesale markups and enables custom formulation.
- Online Retail:E-commerce platforms serve small-acreage organic growers and hobby farmers requiring sub-ton quantities with OMRI certification transparency.
- Wholesalers:Volume aggregators supply industrial processors and export markets from Great Lakes and Gulf Coast port facilities.
Distributors retain the largest share; direct sales are climbing fastest as large produce operations consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows between the United States and Canada dominate continental potassium sulfate movement, with Canadian potash feedstock supplying Mannheim process facilities across the Midwest while specialty-grade product moves south to California's Central Valley vegetable belt.
United States Corn Belt
Iowa and Illinois soybean-corn rotations drive bulk potassium sulfate consumption where sulfur-deficient soils intersect with EPA Clean Water Act phosphorus restrictions. State-level 4R Nutrient Stewardship frameworks mandate precise placement and timing, elevating chloride-free potassium sources in agronomic recommendations. Bulk blender networks across Des Moines and Peoria maintain segregated storage infrastructure to prevent chloride cross-contamination.
California Central Valley
Specialty vegetable and nut producers in Fresno and Kern counties convert acreage to drip fertigation systems requiring fully soluble, chloride-free potassium inputs. EPA regional water quality control boards enforce agricultural runoff limits under the Clean Water Act, indirectly favoring sulfate-based fertilization programs. Direct manufacturer contracts now bypass traditional wholesale channels for large-scale tomato and almond operations.
Florida Peninsula
Phosphate-sulfate co-production facilities anchor supply to sugarcane and winter vegetable producers across the Everglades Agricultural Area. State water management districts enforce nutrient source controls under the Everglades Forever Act, restricting phosphorus loads while permitting sulfate supplementation. Greenhouse and hydroponic operations in Miami-Dade County drive food-grade crystal demand for premium produce segments.
Canadian Prairie Provinces
Saskatchewan and Manitoba pulse crop expansion creates chloride-sensitive demand pockets for lentil and pea producers. Canadian Food Inspection Agency fertilizer registration requirements create cross-border harmonization pressure with US EPA standards. Nutrien's integrated potash network leverages captive feedstock access across Regina and Brandon production corridors.
USA and Canada Potassium Sulfate Market Competitive Landscape
Concentration sits with integrated resource holders who control upstream potash or sulfate feedstock access. The market structure tiers between bulk agricultural-grade suppliers serving Corn Belt blenders and specialty-grade producers capturing California and Florida premium channels. Three archetypes dominate: integrated potash-sulfate producers with captive mineral rights, evaporite-derived specialists leveraging brine chemistry advantages, and regional compounders blending imported sulfate salts. Capacity expansion and backward integration into sulfur or potash sourcing represent the dominant competitive moves as energy and feedstock volatility compress facility margins.
Among North American integrated producers, Nutrien exemplifies the resource-backed archetype through its Saskatchewan potash network, while Mosaic Company anchors the phosphate-sulfate co-production model at Florida facilities. Compass Minerals occupies the evaporite-specialist position through Great Salt Lake brine operations. SQM and K+S Group represent import-dependent suppliers serving coastal markets, with Yara International and ICL occupying diversified fertilizer portfolio positions. Jost Chemical Co. and American Elements sit within the high-purity industrial and food-additive segments where certification requirements exceed agricultural thresholds.
| Leading Market Players |
|---|
| Nutrien |
| Mosaic Company |
| Compass Minerals |
| SQM |
| K+S Group |
| Yara International |
| ICL |
| Jost Chemical Co. |
| American Elements |
| Others |
Value Network & Pricing Analysis
Mannheim process capacity utilization above 85 percent across Saskatchewan and Manitoba facilities concentrates feedstock buying power among integrated potash producers. This scale concentration elevates price floors for agricultural-grade sulfate salts while compressing margins for regional compounders lacking captive sulfuric acid supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across glass manufacturing and chemical synthesis segments. Price differentiation rests on certification grade and volume scale, with food-additive FCC tiers commanding substantial premiums over standard agricultural grades. Cost compression in commodity potash is intensifying because muriate of potash retains cost advantage for chloride-tolerant row crops. Chemical plants demonstrate highest price sensitivity due to index-linked purchasing, while organic vegetable producers show least sensitivity given OMRI certification requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites sulfur feedstock security for North American Mannheim facilities, with Saudi and Qatari sulfur exports feeding Gulf Coast acid plants. Geographic supply concentration centers on Canada, the United States, and Chile for potash and sulfate salts. Raw material dependencies draw from sulfur, potassium chloride, and natural gas thermal energy. Single-source vulnerability runs through concentrated sulfuric acid supply from integrated oil refining. Distribution runs through regional fertilizer wholesalers maintaining segregated storage to prevent chloride cross-contamination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive access to low-cost potash feedstock or brine-derived sulfate salts represents the scarcest capability in this market, separating margin-sustainable integrated producers from import-dependent compounders facing energy cost volatility.
For Market Incumbents: Consolidate backward integration into sulfuric acid production or captive natural gas supply to defend against feedstock cost volatility at Mannheim facilities. Acquire or expand evaporite brine extraction permits across Utah and Saskatchewan to secure non-Mannheim sulfate salt capacity. Lock in long-term offtake agreements with California Central Valley vegetable cooperatives before liquid concentrate channels bypass traditional wholesale markups entirely. For New Entrants and Emerging Players: Liquid concentrate technical support services represent the most under-served layer, with incumbents lacking on-farm fertigation system integration expertise. Target Saskatchewan and Manitoba pulse crop acreage expansion zones where chloride-sensitive demand outpaces regional distribution infrastructure. Pursue OMRI certification and direct-to-grower liquid delivery contracts as the primary go-to-market angle, bypassing established bulk blender networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated potash-sulfate producers with captive feedstock access and long-term agricultural offtake contracts. Five-to-ten year viability favors evaporite-derived specialists with water rights secured at Great Salt Lake or similar brine deposits. Monitor EPA Clean Water Act enforcement timelines in the Mississippi River watershed as the key inflection signal for potassium sulfate demand acceleration versus muriate substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive sulfur supply insulates Mannheim facilities from oil-refining byproduct volatility. |
| Evaporite Brine Extraction Expansion | Great Salt Lake water rights secure lower-carbon sulfate salt output outside thermal processes. |
| Long-term Supply Agreement | Direct contracts with California tomato and almond operations lock premium liquid concentrate volumes. |
| OMRI Certification Investment | Organic certification opens price-insensitive channels prohibited from synthetic chloride fertilizers. |
| Controlled-Release Formulation Development | Polymer-coated granules align with Iowa and Illinois 4R Nutrient Stewardship placement mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork with crop advisors at Iowa and Illinois retail agronomy networks, plant managers at Mannheim process facilities, procurement leads at California vegetable cooperatives, and distribution channel partners in the Corn Belt. Secondary validation drew from EPA Clean Water Act enforcement databases, USDA conservation program filings, Canadian Food Inspection Agency fertilizer registrations, and SEC 10-K disclosures from integrated potash producers. Bottom-up volume estimates from county-level fertilizer consumption data were triangulated against top-down capacity assessments across North American production facilities.
Across the analysis window, the forecasting framework modeled potassium sulfate demand through segmentation by product form, application grade, end-user sophistication, and distribution channel structure. CAGRs were derived from regression analysis against sulfur soil depletion rates, drip irrigation adoption curves, and regulatory enforcement intensity indices. Key inputs included atmospheric sulfur deposition monitoring data from the National Atmospheric Deposition Program and EPA regional water quality control board enforcement patterns.
Forecasts assume regulatory continuity in EPA Clean Water Act phosphorus restrictions and state-level 4R Nutrient Stewardship frameworks; material policy shifts would require re-modeling demand trajectories. Energy price volatility at Mannheim facilities and evaporite permitting delays represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as EPA regional enforcement priorities and natural gas supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Global Bitumen Market