
 Global Lithium Carbonate Market | 2026-2036
Global Lithium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Carbonate Market Outlook
The divergence between battery-grade and industrial-grade lithium carbonate is repositioning how producers allocate refining capacity, with purity thresholds splitting contract terms and pricing mechanisms into separate tiers. Albemarle Corporation leverages its Chilean brine assets to sustain long-term supply agreements with cathode makers. Ganfeng Lithium Co., Ltd. anchors its cost position through backward integration into Australian spodumene mining. Tianqi Lithium Corporation dominates the premium segment by controlling one of the world's lowest-cost brine operations.
Lithium carbonate is a lithium salt of carbonic acid, typically produced at purities exceeding 99.5% for battery applications through either solar evaporation of brine or acid roasting of hard-rock ore, and it serves as the primary feedstock for cathode active materials in lithium-ion cells. Battery grade material commands the dominant value share as automakers lock in multi-year offtake agreements, while industrial grade remains mature with slower expansion tied to glass and ceramics manufacturing. The automotive end user segment absorbs the majority of volume growth, whereas electronics manufacturers compete for constrained pharmaceutical-grade supply.
The EU Green Deal and REACH framework in Europe, China's dual carbon goals administered by MEE, and the US Inflation Reduction Act administered through relevant agencies are each tightening traceability and carbon-intensity requirements for battery materials, effectively raising compliance costs for non-integrated producers. Battery-grade certification standards from ISO and IEC are becoming de facto market access filters. Stakeholders must monitor how regulatory divergence between jurisdictions reshapes the geographic viability of new extraction projects.
Market Dynamics
The battery-grade lithium carbonate market is bifurcating around purity thresholds, with automakers enforcing 99.5% minimum specifications that disqualify legacy industrial-grade supply chains from cathode material procurement.
Growth Catalysts
- EU Green Deal battery mandates:The European Commission's carbon-intensity caps for imported cells are forcing cathode makers to source certified low-carbon lithium carbonate, redirecting procurement toward Chilean brine operations with solar evaporation footprints.
- Direct lithium extraction:DLE technologies are compressing production timelines from 18-month solar evaporation cycles to 90-day continuous processing, unlocking previously uneconomic brine resources in Argentina's Salares.
- Automaker offtake contracting:Electric vehicle manufacturers are signing 5-7 year binding purchase agreements with fixed-volume escalators, de-risking capital deployment for greenfield refinery investments.
Market Restraints
- Spodumene concentrate volatility:Australian hard-rock mining output fluctuates with construction labor availability, transmitting cost instability into Chinese conversion plants dependent on imported feedstock.
- Chilean brine permitting congestion:Chile's CORFO licensing framework imposes multi-year environmental review timelines that delay capacity expansion despite proven geological resources.
- Sodium-ion substitution:CATL and BYD are commercializing sodium-ion cells for sub-300km range vehicles, threatening lithium carbonate absorption in entry-level electric vehicle segments.
Strategic Opportunities
- North American IRA localization:The US Inflation Reduction Act's critical mineral sourcing requirements are creating tariff-advantaged demand for domestic or free-trade-agreement lithium carbonate, incentivizing Nevada clay and California geothermal project development.
- Pharmaceutical-grade verticals:Bipolar disorder treatment formulations require ultra-high-purity lithium carbonate with trace metal specifications below 10ppm, commanding 3-4x battery-grade pricing from specialized refiners.
- Recycling feedstock integration:Black mass hydrometallurgical recovery is unifying end-of-life battery streams with primary production, enabling circular certification that satisfies EU battery passport traceability rules.
Industry Challenges
- Analytical chemist scarcity:Battery-grade certification requires ICP-MS trace metal analysis capabilities that outstrip current laboratory workforce training pipelines in emerging production regions.
- Refinery commissioning delays:Acid roasting and purification train startups face 12-18 month qualification periods with cathode maker qualification protocols, stranding capital during price cycle downturns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Carbonate Market |
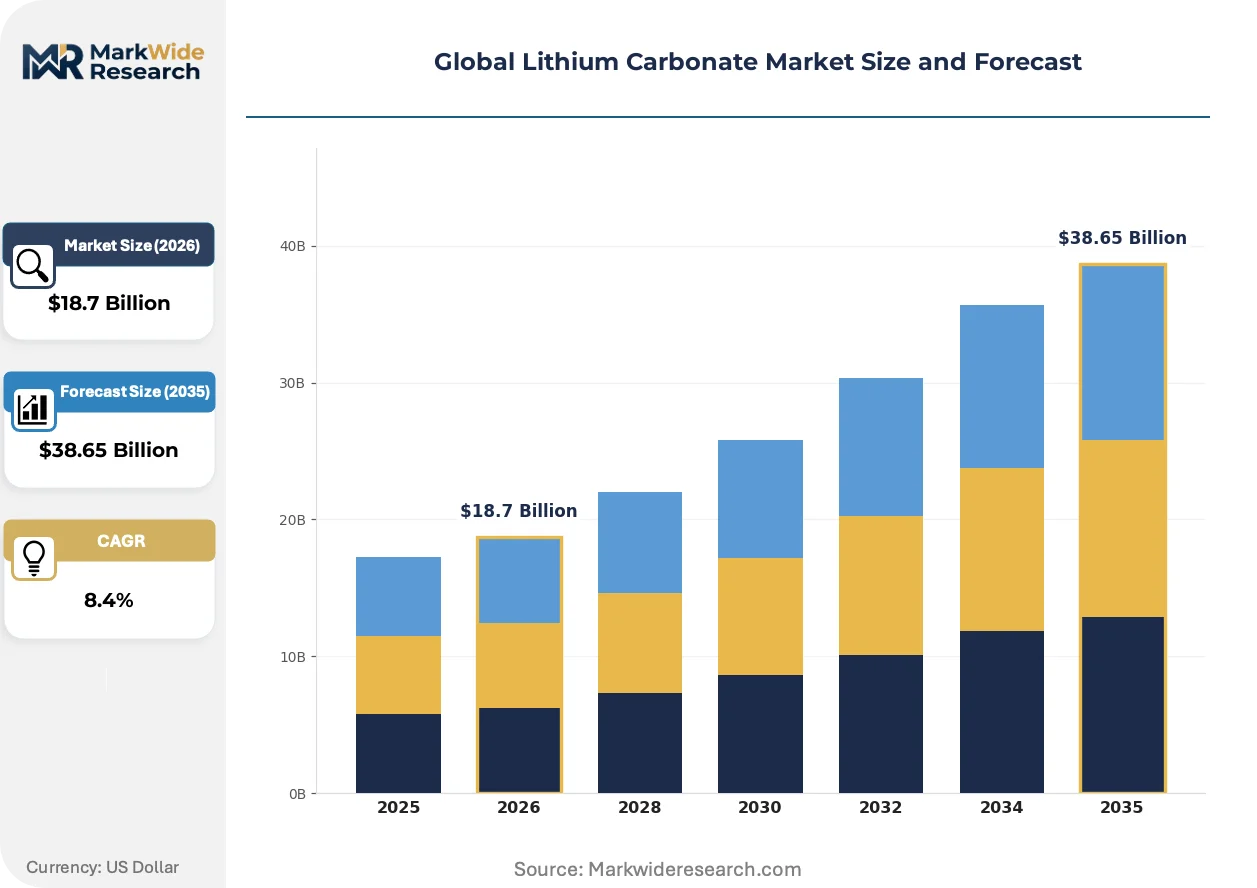
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Electric Vehicles, Energy Storage Systems, Electronics, Pharmaceuticals End User: Automotive Industry, Electronics Manufacturers, Renewable Energy Providers, Healthcare Sector Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Sociedad Química y Minera de Chile S.A. (SQM), Lithium Americas Corp., Albemarle Corporation, Tianqi Lithium Corporation, Bacanora Lithium Plc, Ganfeng Lithium Co., Ltd., Allkem Limited, Mineral Resources Limited, Livent Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Carbonate Market Strategic Shifts
Continuous processing technologies are displacing batch refining in lithium carbonate production, compressing energy intensity and enabling real-time quality control that satisfies automaker audit requirements.
Direct lithium extraction using selective sorbents is unifying brine concentration and impurity rejection into single-unit operations. Albemarle and Controlled Thermal Resources are deploying these systems at California's Salton Sea and Argentina's Cauchari-Olaroz. The technology is eliminating evaporation pond footprints and reducing water consumption by 90% compared with Atacama-style solar processing, enabling production in jurisdictions with stricter environmental review.
China's MIIT has issued GB/T 26008-2024 battery-grade lithium carbonate national standards that mandate stricter sodium, potassium, and calcium limits than incumbent IEC 62660 specifications. The regulation is forcing non-Chinese producers to retool purification circuits or forfeit access to the world's largest cathode manufacturing base. Australian spodumene converters are responding by adding secondary crystallization stages to meet the new thresholds.
Automakers are consolidating supplier relationships around vertically integrated lithium-to-cathode partnerships rather than spot-market purchasing. Tesla, Ford, and BMW are negotiating equity stakes in refinery projects to secure volume allocation during supply crunches. This behavioral shift is most visible in binding offtake structures emerging from Quebec's James Bay and Western Australia's Greenbushes expansion corridors, where producers must demonstrate 10-year reserve life to qualify for strategic partnership status.
Global Lithium Carbonate Market Segmentation
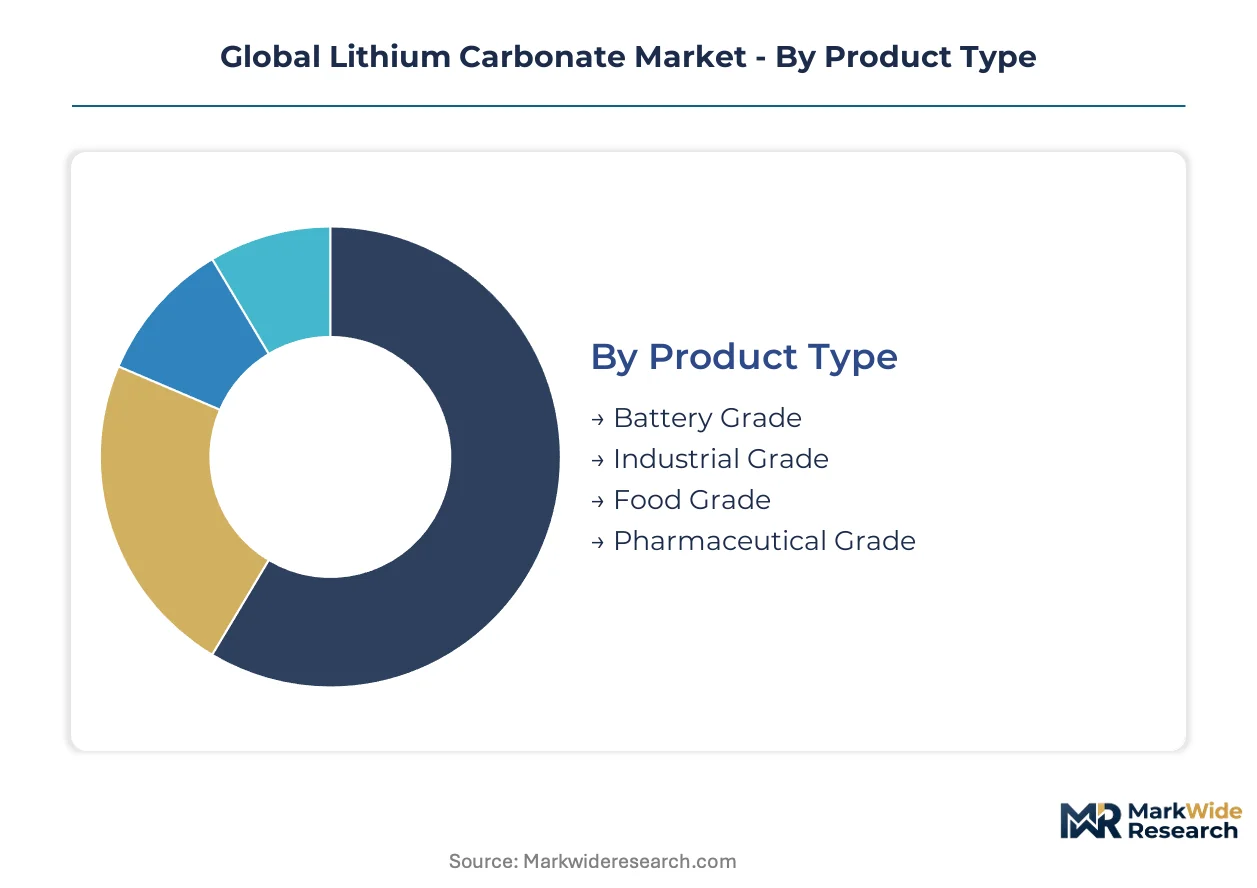
Lithium carbonate markets stratify around purity thresholds that determine contract eligibility, pricing tiers, and regulatory compliance pathways. Each segment category reflects distinct technical specifications, customer qualification requirements, and geographic procurement patterns that reshape competitive positioning.
Product Type:
Customization intensity rises with purity specifications, splitting production infrastructure between mass-market industrial output and precision-engineered battery and pharmaceutical grades.
- Battery Grade:Lithium carbonate exceeding 99.5% purity serves as the primary feedstock for cathode active materials in lithium-ion cells, with sodium and potassium limits tightened under China's GB/T 26008-2024 standards. Automakers in Germany and the United States enforce ICP-MS certification protocols that disqualify lower-purity supply from long-term offtake agreements.
- Industrial Grade:Material at 99.0-99.5% purity flows into glass and ceramics manufacturing, where fluxing properties matter more than trace metal control. Demand concentrates in China's Guangdong and Shandong ceramic belts, with slower expansion tied to mature construction and consumer goods sectors.
- Food Grade:Meets CODEX Alimentarius specifications for acidity regulators in beverage and dairy applications, with production concentrated among Chinese and European chemical processors holding FSSAI or EFSA food additive registrations.
- Pharmaceutical Grade:Ultra-high-purity material with trace metals below 10ppm serves bipolar disorder treatment formulations, commanding specialized refining capacity from Albemarle's North Carolina and Tianqi's Jiangsu facilities.
Most installed capacity flows through Battery Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Volume concentration follows electrification intensity, with mobility applications absorbing capacity at scales that dwarf stationary and consumer electronics demand.
- Electric Vehicles:Cathode material procurement from NMC and LFP chemistries dominates volume absorption, with Tesla, BYD, and Volkswagen Group locking in multi-year supply agreements that de-risk refinery capital deployment.
- Energy Storage Systems:Grid-scale battery installations for renewable integration drive demand for cost-optimized LFP-grade material, with procurement concentrating in China's Xinjiang and Qinghai utility corridors.
- Electronics:Portable device batteries compete for constrained high-purity supply against automotive offtake, with Samsung SDI and LG Energy Solution qualifying smaller volume allocations from Ganfeng and SQM.
- Pharmaceuticals:Mood stabilizer manufacturing requires dedicated batch production with pharmacopeial compliance, serving Teva, Novartis, and Sun Pharmaceutical formulation networks.
Electric Vehicles capture the dominant volume share. Energy Storage Systems are climbing the fastest.
End User:
Customer sophistication varies across qualification protocols, with automotive OEMs imposing the most stringent audit and traceability requirements.
- Automotive Industry:OEMs and tier-one cathode makers enforce 10-year reserve life demonstrations and carbon-intensity disclosures under EU Green Deal and US IRA frameworks, consolidating procurement around vertically integrated suppliers.
- Electronics Manufacturers:Consumer device assemblers prioritize supply security over purity optimization, accepting spot-market pricing volatility that automakers reject through binding contracts.
- Renewable Energy Providers:Utility and independent power producers source through engineering-procurement-construction contractors, with Sungrow and CATL Energy absorbing volume for solar-wind hybrid storage projects.
- Healthcare Sector:Pharmaceutical compounders demand DEA-controlled substance handling and FDA/EMA current good manufacturing practice compliance, limiting eligible supplier pools.
Automotive Industry channels the majority of premium-grade volume. Healthcare Sector maintains the tightest supplier qualification barriers.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to conversion capacity.
- Direct Sales:Long-term offtake agreements between Chilean brine operators and Asian cathode makers eliminate intermediary margins, with Albemarle and SQM operating dedicated account management for CATL and LG Chem.
- Distributors:Regional chemical traders serve mid-scale industrial and pharmaceutical buyers requiring just-in-time delivery and local inventory buffering, particularly in India's Gujarat and Maharashtra manufacturing clusters.
- Online Sales:E-procurement platforms facilitate spot transactions for laboratory and research quantities, with Alibaba and specialty chemical marketplaces handling sub-tonnage orders.
- Retailers:Limited to consumer-facing lithium supplement and specialty ceramic supply, with negligible share in industrial or battery-grade flows.
Direct Sales handles the majority of battery-grade tonnage. Distributors retain relevance in pharmaceutical and fragmented industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean brine chemists and Australian geologists anchor the specialized workforce pools that concentrate lithium carbonate expertise. Their technical depth sustains the two dominant extraction methodologies defining global supply geography.
Chile
Atacama salt flat operations supply the majority of battery-grade material through solar evaporation infrastructure. CORFO licensing frameworks impose multi-year environmental reviews that delay capacity expansion despite proven geological resources. Antofagasta and Calama host the primary concentration and export corridors serving Asian cathode makers.
Australia
Hard-rock spodumene mining in Western Australia's Greenbushes and Pilbara regions feeds Chinese conversion plants with concentrate feedstock. Construction labor availability fluctuates, transmitting cost instability into downstream refining economics. Perth serves as the technical services hub coordinating metallurgical testing and shipment logistics.
China
Jiangxi and Sichuan provinces concentrate conversion capacity that transforms imported spodumene and domestic brine into battery-grade carbonate. MIIT's GB/T 26008-2024 standards mandate stricter sodium, potassium, and calcium limits than IEC specifications, forcing foreign producers to retool purification circuits. Ganzhou and Yibin host the primary refining clusters supplying CATL and BYD.
Argentina
Salares in Jujuy and Catamarca provinces contain undeveloped brine resources attracting direct lithium extraction pilot deployments. DLE technologies compress production timelines from 18-month solar cycles to 90-day processing, unlocking previously uneconomic reserves. Cauchari-Olaroz anchors the primary development corridor with integrated extraction and conversion infrastructure.
United States
Nevada clay deposits and California's Salton Sea geothermal brines position domestic feedstock development under IRA critical mineral sourcing requirements. The Inflation Reduction Act creates tariff-advantaged demand for free-trade-agreement lithium carbonate, incentivizing refinery investment. Reno and Imperial Valley host the primary project development clusters targeting cathode maker qualification.
Global Lithium Carbonate Market Competitive Environment
Top-tier vendors anchor integrated brine-to-carbonate operations, while mid-scale converters compete on feedstock procurement flexibility. Chilean and Australian asset bases concentrate among a handful of producers with decade-long reserve positions. Two strategic archetypes dominate: brine operators leveraging solar evaporation cost structures, and hard-rock miners controlling spodumene concentrate supply. Competitive moves center on multi-year offtake contracting with automakers and backward integration into mining assets.
Within the brine-operator archetype, Sociedad Química y Minera de Chile S.A. and Albemarle Corporation exemplify the integrated model with Chilean asset bases. Tianqi Lithium Corporation occupies a position among the vertically integrated Chinese producers with Australian mining exposure. These three entities represent the dominant competitive anchors structuring long-term supply negotiations with cathode manufacturers.
| Leading Market Players |
|---|
| Sociedad Química y Minera de Chile S.A. (SQM) |
| Lithium Americas Corp. |
| Albemarle Corporation |
| Tianqi Lithium Corporation |
| Bacanora Lithium Plc |
| Ganfeng Lithium Co., Ltd. |
| Allkem Limited |
| Mineral Resources Limited |
| Livent Corporation |
| Others |
Value Chain & Pricing Dynamics
Direct lithium extraction technology is compressing production cycles from eighteen-month solar evaporation timelines to ninety-day continuous processing, simultaneously eroding the cost advantage of Chilean brine operators and fragmenting supply concentration across Argentina's Salares and California's Salton Sea. This production-method transition enables new entrants to undercut legacy pricing while automakers enforce stricter certification costs that favor integrated suppliers.
Pricing Analysis
Bundled long-term offtake agreements dominate premium battery-grade transactions, while unbundled spot-market sales persist for industrial-grade material. Three-tier pricing structure across battery-grade, industrial-grade, and pharmaceutical-grade separates contract eligibility, with automakers absorbing 3-4x premiums for ICP-MS-certified supply. Cost compression in industrial-grade is intensifying because Chinese converters flood spot markets with excess spodumene-derived output. Electronics manufacturers exhibit highest price sensitivity, accepting purity trade-offs, whereas pharmaceutical compounders reject any price negotiation on trace-metal specifications.
Supply Chain Analysis
Container freight rates from Chilean ports to Asian cathode plants constitute 8-12% of delivered battery-grade costs, incentivizing producers to co-locate refining with extraction. Supply concentrates in Chile, Australia, and China, with Argentine DLE projects eroding this triad. Hard-rock spodumene from Western Australia feeds Chinese conversion capacity, while Chilean brine operations anchor direct sales to Korean and Japanese cathode makers. Single-source vulnerability runs through Australian mining labor pools, where construction availability fluctuates with commodity supercycles. Distribution runs through long-term offtake structures rather than spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lithium carbonate rests on direct lithium extraction cost-down trajectories and pharmaceutical-grade premium capture, as automaker certification requirements widen spreads between qualified and unqualified supply.
For Market Incumbents: To counter sodium-ion substitution in entry-level electric vehicles, Albemarle and SQM should deepen captive brine-to-carbonate integration while accelerating DLE retrofitting at Chilean assets. Securing CORFO license expansions ahead of Argentine project commissioning preserves volume allocation leverage with CATL and LG Chem. For New Entrants and Emerging Players: The 40-60% price-point gap between battery-grade and industrial-grade lithium carbonate offers white-space entry through pharmaceutical-grade specialization or Nevada clay-based IRA-compliant supply. Argentina's Salares present the most penetrable geography, with DLE technology enabling faster qualification than Chilean permitting timelines allow. Joint venture structures with established cathode makers de-risk offtake contracting. For Investors and Strategic Acquirers: Valuations sit cheapest among Australian spodumene converters facing Chinese GB/T 26008-2024 retooling costs. Long-term viability favors brine operators with 15-plus year reserve life and demonstrated automaker qualification. The signal to watch is CORFO licensing velocity, as permit acceleration would compress Argentine project IRR advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Lithium Extraction Scale-Up | Albemarle's California deployment cuts water consumption 90% versus Atacama evaporation, unlocking ESG-compliant supply. |
| Backward Integration into Brine Assets | Ganfeng's Cauchari-Olaroz stake secures captive feedstock for Jiangxi refining clusters serving CATL. |
| Pharmaceutical-Grade Capacity Addition | Tianqi's Jiangsu facility captures 4x battery-grade pricing from Teva and Novartis bipolar disorder formulations. |
| Long-Term Offtake Restructuring | Tesla's equity stakes in Quebec refinery projects bind volume allocation through 2030 supply crunches. |
| Recycling Feedstock Integration | Black mass hydrometallurgical recovery satisfies EU battery passport rules for circular certification. |
Study Parameters
Coverage spans Chile, Australia, China, Argentina, and the United States, with primary inputs from each territory's extraction and conversion clusters. Primary interviews with brine field chemists, cathode procurement directors, CORFO licensing officials, and DLE technology engineers combined with secondary validation from SEC filings, Chilean customs export data, Chinese MIIT standard releases, and Argentine provincial mining registries. Bottom-up project economics triangulated against top-down cathode demand forecasts.
Granularity-level modeling addressed purity tiers, extraction methodology, end-use application, and automaker qualification status across the projection horizon. Segment-specific CAGRs derived from battery chemistry adoption curves, electric vehicle production forecasts, and stationary storage deployment pipelines. Pricing trajectories incorporated spodumene concentrate spot indices, brine royalty structures, and freight rate volatility.
Caveats apply where CORFO permitting delays, Argentine political risk, or sodium-ion chemistry substitution could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Tin Fluoborate Market