
 Global Ethylene Market | 2026-2036
Global Ethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethylene Market Analysis
Electrification of steam cracking furnaces is reshaping capital deployment across the ethylene value chain. Dow Inc leverages its Gulf Coast infrastructure to anchor North American export competitiveness. SABIC specializes in integrating crude-to-chemicals complexes at scale in Jubail. ExxonMobil Corporation extends its technology leadership through proprietary furnace designs that cut CO2 intensity per ton of output.
Ethylene is an unsaturated hydrocarbon with the formula C2H4, produced primarily via steam cracking of naphtha, ethane, or propane at temperatures exceeding 800°C; it serves as the foundational building block for polyethylene, ethylene oxide, and ethylene glycol. Ethylene glycol commands substantial margin pools due to its polyester and antifreeze applications, while ethylene oxide grows fastest in surfactants and medical sterilization. Packaging dominates end-use consumption, though automotive lightweighting applications in ethylene-based composites are gaining structural importance.
The US EPA enforces emissions standards under the Clean Air Act that constrain older cracking assets, while the EU F-Gas Regulation and REACH framework restrict fluorinated process agents and mandate chemical safety documentation. China's MEE imposes carbon intensity benchmarks on new petrochemical investments. Stakeholders must monitor feedstock cost spreads between ethane and naphtha, track regulatory compliance timelines across jurisdictions, and assess low-carbon technology readiness before committing to greenfield capacity.
Market Dynamics
Electrification of steam cracking furnaces is compressing the capital efficiency gap between legacy naphtha crackers and advantaged ethane-based assets, forcing mid-margin operators to accelerate retrofit timelines or exit.
Growth Catalysts
- US Inflation Reduction Act:Tax credits for low-carbon hydrogen production are subsidizing pilot retrofits at Gulf Coast steam crackers, cutting CO2 intensity per ton of ethylene output.
- Flexible packaging substitution:Food and beverage brands are displacing glass and metal with multilayer ethylene films, tightening resin specifications for barrier performance.
- Crude-to-chemicals integration:Saudi Arabia's Jubail complex is capturing 45% more liquid chemicals per barrel than conventional refineries, resetting feedstock economics for C2-C4 olefins.
Market Restraints
- Ethane-naphtha spread volatility:US ethane prices at Mont Belvieu swing with natural gas liquids extraction rates, eroding margin predictability for export-oriented derivatives.
- Chinese capacity concentration:State-backed Sinopec and private Hengli installations account for over 60% of Asian net additions, compressing regional operating rates.
- Fluorinated agent restrictions:The EU F-Gas Regulation phases down hydrofluorocarbon process cooling agents, stranding refrigeration-dependent cracking assets without retrofit capital.
Strategic Opportunities
- Bio-ethylene feedstock pilots:Brazilian sugarcane bagasse and EU woody biomass gasification projects are qualifying for RED III renewable fuel credits, opening premium polymer offtake contracts.
- Automotive composite penetration:Ethylene-vinyl acetate copolymers are replacing metal in electric vehicle battery encapsulation, with German OEMs qualifying new grades for thermal runaway protection.
- Carbon border adjustment mechanism:The EU CBAM will impose embodied emissions tariffs on imported polyethylene from 2026, advantaging crackers with certified low-carbon output.
Industry Challenges
- High-voltage furnace engineering talent:Electrified cracking requires power electronics and refractory design expertise scarce in incumbent petrochemical workforces, extending commissioning timelines.
- REACH compliance documentation:Ethylene oxide derivatives face escalating ECHA data requirements for carcinogenicity classification, forcing reformulation of medical sterilization and surfactant products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethylene Market |
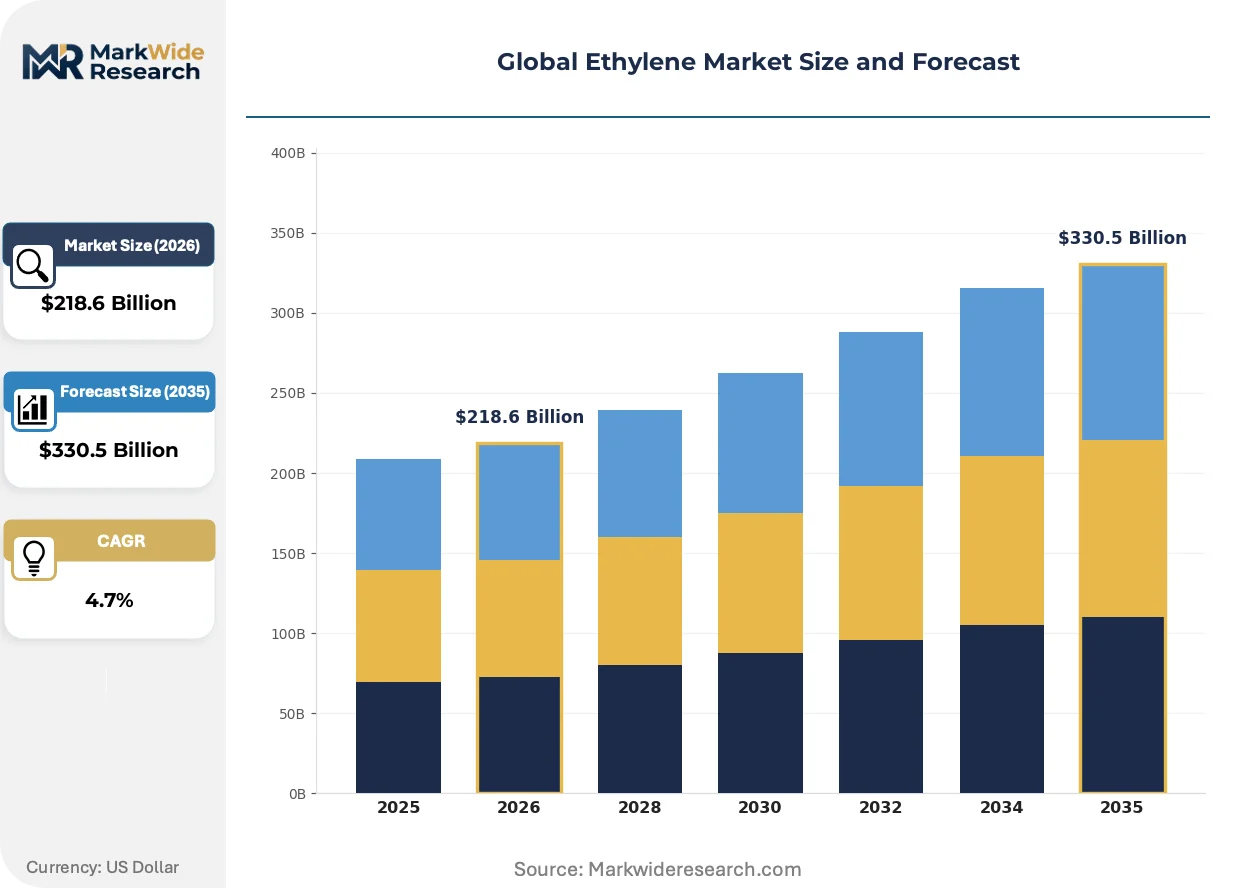
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $330.5 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Oxide, Ethylene Dichloride, Ethylene Glycol, Ethylbenzene End Use Industry: Packaging, Automotive, Construction, Textile Technology: Steam Cracking, Catalytic Cracking, Ethane Dehydrogenation, Oxidative Coupling Application: Plastics, Antifreeze, solvents, coatings |
| Companies Covered | ExxonMobil Corporation, China Petroleum & Chemical Corporation, LyondellBasell Industries, SABIC, Dow Inc, Reliance Industries Limited, Shell plc, Chevron Phillips Chemical Company, INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethylene Market Emerging Trajectories
Process intensification and feedstock diversification are bifurcating the ethylene value chain into carbon-intensive commodity supply and certified low-carbon premium tiers.
Electric cracking furnaces developed by technology licensors are rendering obsolete the fired heater designs that dominated steam cracking for six decades. European polyethylene compounders are piloting these units for specialty grades requiring narrow polydispersity. The capital cost premium is compressing acceptable payback periods from ten years to under seven for assets serving brand-owner carbon neutrality commitments.
The EU Green Deal's Fit for 55 package mandates 55% emissions reduction by 2030 against 1990 baselines, forcing crackers to source renewable power or install post-combustion carbon capture. German chemical parks at Ludwigshafen and Marl are aggregating CO2 transport infrastructure to shared sequestration sites. This regulatory pressure is fragmenting the polyethylene market into EU-compliant and export-only product lines with diverging price formations.
Brand-owner polymer procurement now requires mass-balance certification for recycled or bio-attributed content, displacing traditional spot-market purchasing for packaging applications. Major food retailers in France and the UK are auditing ethylene supply chains for Scope 3 emissions, rejecting uncertified volumes. This behavioral shift is most visible in flexible film extrusion, where long-term offtake agreements with fixed sustainability premiums are replacing quarterly tenders.
Global Ethylene Market Segmentation
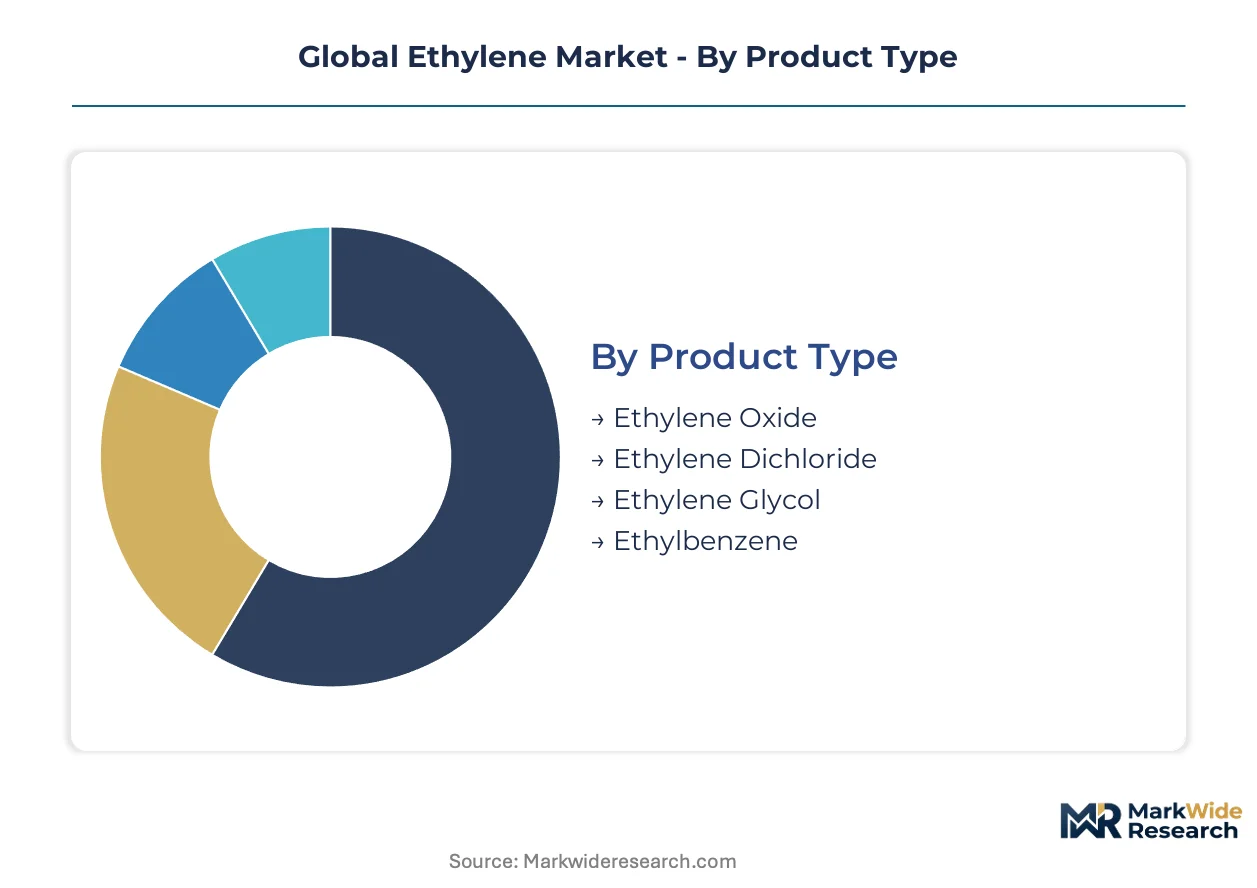
Ethylene derivatives span radically different value pools and margin profiles. Segmentation reveals where electrification retrofits concentrate versus where legacy assets retain cost advantage.
Product Type:
Derivatives range from commodity glycols to specialty oxides with diverging carbon intensity requirements.
- Ethylene Oxide:Highly reactive intermediate requiring pressurized reactor vessels and silver catalyst beds. Medical sterilization demand from German hospital networks and US pharmaceutical packaging plants is tightening purity specifications while REACH carcinogenicity reviews threaten legacy surfactant formulations.
- Ethylene Glycol:Primary feedstock for polyethylene terephthalate resin and engine coolant formulations. Polyester textile mills in Vietnam and Bangladesh are locking in long-term glycol contracts as fashion brands enforce mass-balance certification for recycled content claims.
- Ethylene Dichloride:Chlor-alkali coupling agent for PVC production chains.
- Ethylbenzene:Styrene monomer precursor serving expandable polystyrene packaging and ABS automotive components.
Established volume favors Ethylene Glycol; emerging adoption favors Ethylene Oxide.
End Use Industry:
Customer sectors impose distinct performance certifications and carbon accounting standards.
- Packaging:Flexible film converters and rigid container molders dominate resin offtake. French and UK supermarket chains are auditing Scope 3 emissions, rejecting uncertified polyethylene volumes and forcing fixed-sustainability-premium contracts over quarterly spot tenders.
- Automotive:Ethylene-vinyl acetate copolymers are displacing metal in electric vehicle battery encapsulation systems. German OEM thermal runaway protection standards are qualifying new copolymer grades with enhanced flame-retardant specifications.
- Construction:Cross-linked polyethylene piping and geomembrane sheeting.
- Textile:Polyester fiber intermediates for apparel and industrial yarn.
Margin concentration sits with Automotive; volume scale sits with Packaging.
Technology:
Process routes separate carbon-intensive legacy assets from emerging low-carbon pathways.
- Steam Cracking:Dominant production method using naphtha or ethane feedstock at furnace temperatures exceeding 800°C. US Gulf Coast operators are piloting electric furnace retrofits subsidized by Inflation Reduction Act hydrogen tax credits, cutting CO2 intensity per ton of output.
- Ethane Dehydrogenation:Direct conversion pathway bypassing cracking furnaces. Saudi Aramco and SABIC are scaling crude-to-chemicals integration at Jubail, capturing 45% more liquid chemicals per barrel than conventional refining configurations.
- Catalytic Cracking:Fluidized bed variants for heavy feedstock flexibility.
- Oxidative Coupling:Experimental methane-to-ethylene route with unresolved selectivity challenges.
Capital deployment favors Steam Cracking retrofits; technology optionality favors Ethane Dehydrogenation.
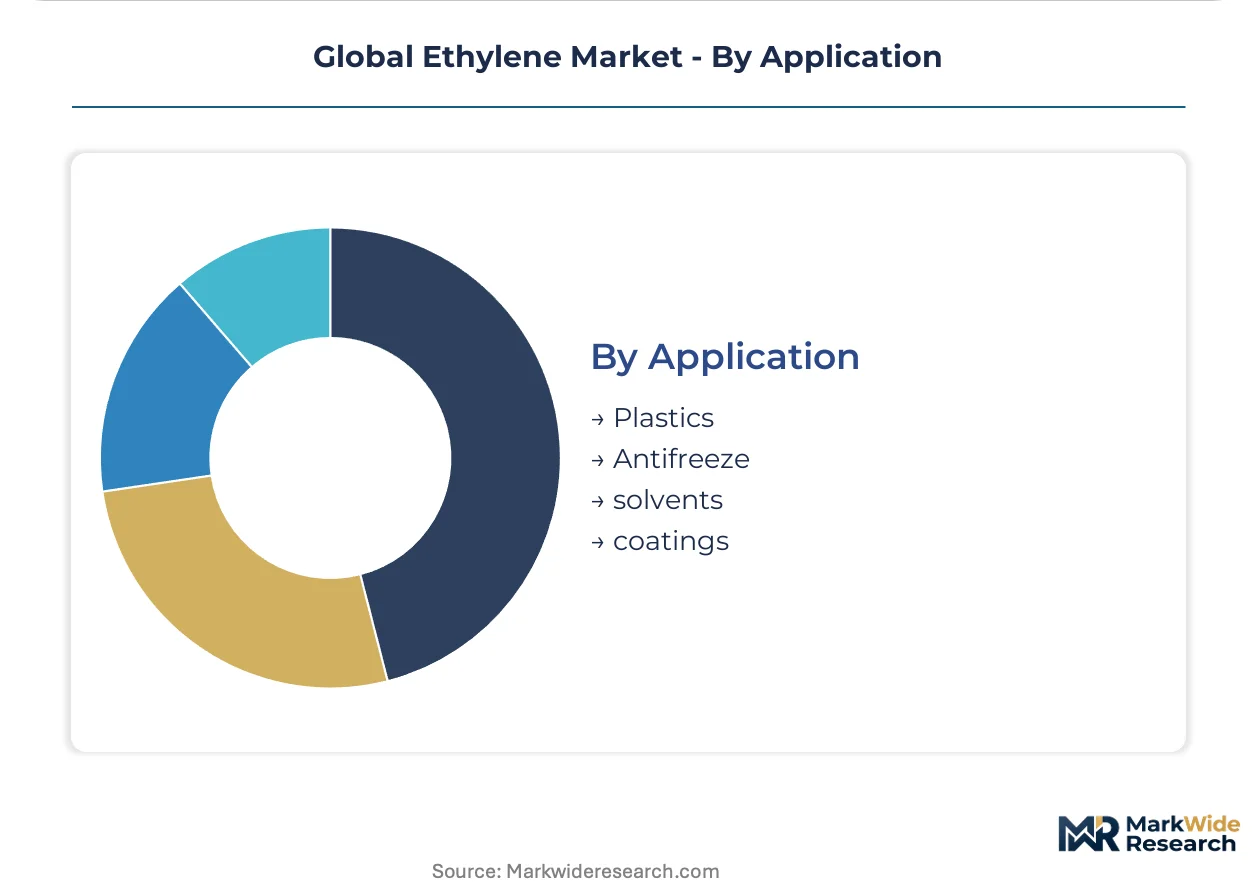
Application:
Downstream formulations split between durable goods and consumable chemical markets.
- Plastics:Polyethylene resin for film, injection molding, and blow-molding applications. EU CBAM embodied emissions tariffs from 2026 will advantage crackers with certified low-carbon output, fragmenting the polyethylene market into EU-compliant and export-only product lines.
- Antifreeze:Engine coolant and de-icing formulations with seasonal demand patterns.
- Solvents:Industrial cleaning and coating carrier applications.
- Coatings:Architectural and protective paint binders.
Regulatory exposure concentrates in Plastics; price volatility concentrates in Antifreeze.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters and automotive OEMs concentrate purchasing power across four distinct national production basins. Each territory shapes ethylene economics through divergent feedstock access and carbon regulation stringency.
United States
Flexible film converters in Texas and Louisiana drive resin offtake for food packaging exports. The EPA enforces Clean Air Act emissions standards that constrain older cracking assets in the Gulf Coast corridor. Mont Belvieu ethane pricing volatility shapes margin predictability for derivatives producers serving Latin American export markets.
China
State-backed Sinopec and private Hengli installations account for over sixty percent of Asian net capacity additions. The MEE imposes carbon intensity benchmarks on new petrochemical investments in the Yangtze River Delta. Zhejiang and Jiangsu provinces concentrate steam cracker complexes serving domestic polyethylene demand for e-commerce packaging.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg qualify ethylene-vinyl acetate copolymers for electric vehicle battery encapsulation. The EU Green Deal's Fit for 55 package mandates fifty-five percent emissions reduction by 2030 against 1990 baselines. Chemical parks at Ludwigshafen and Marl aggregate CO2 transport infrastructure to shared sequestration sites.
Saudi Arabia
Crude-to-chemicals integration at Jubail captures forty-five percent more liquid chemicals per barrel than conventional refining configurations. The national industrial development program subsidizes downstream derivative capacity for export-oriented glycol and polyethylene production. The Eastern Province concentrates SABIC-operated complexes serving European and Asian polymer offtake contracts.
Brazil
Sugarcane bagasse gasification projects qualify for renewable fuel credits under RED III equivalence agreements. The national bioethanol infrastructure supports pilot-scale bio-ethylene production for premium polymer offtake. São Paulo state clusters chemical conversion assets serving flexible packaging demand from Mercosur consumer goods manufacturers.
Global Ethylene Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where scale advantages separate Gulf Coast ethane crackers from European naphtha-based assets. The vendor base organizes around three strategic archetypes: integrated oil majors with captive feedstock, national champions with state-backed expansion mandates, and specialty compounders with sustainability certification focus. Dominant competitive moves include capacity expansion in low-carbon retrofits and strategic partnerships for bio-attributed feedstock offtake.
Among integrated oil majors, ExxonMobil Corporation and Shell plc exemplify technology leadership through proprietary furnace designs and carbon capture integration. SABIC occupies a distinctive position as a national champion with crude-to-chemicals scale economics. Dow Inc and LyondellBasell Industries represent Gulf Coast operators leveraging ethane cost advantages for export competitiveness. These three archetypes—technology-integrated majors, state-backed champions, and feedstock-advantaged independents—define competitive positioning across the 2026-2035 analysis window.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| China Petroleum & Chemical Corporation |
| LyondellBasell Industries |
| SABIC |
| Dow Inc |
| Reliance Industries Limited |
| Shell plc |
| Chevron Phillips Chemical Company |
| INEOS Group |
| Others |
Supply Flow & Price Mechanics
Houston-Rotterdam freight corridors shape margin distribution between US Gulf Coast exporters and European compounders, compressing price spreads when bunker fuel costs spike and advantaging integrated producers with captive shipping. Mont Belvieu ethane differentials against ARA naphtha quotes transmit directly into polyethylene pellet premiums, fragmenting contract structures by feedstock exposure.
Pricing Analysis
Cost-plus contracts indexed to ICIS Mont Belvieu ethane assessments and Platts naphtha cargo differentials dominate long-term offtake agreements between crackers and derivative producers. Price differentiation hinges on mass-balance certification tier and volume scale, with sustainability-premium contracts commanding fixed uplifts over spot benchmarks. Pricing pressure stems from Chinese state-backed capacity additions flooding Asian spot markets with uncommitted polyethylene volumes. Commodity resin buyers at Vietnamese textile mills exhibit highest price sensitivity, while German automotive OEMs qualify specialty copolymer grades with limited substitution options.
Supply Chain Analysis
Contract manufacturing concentration sits with SABIC-operated complexes at Jubail, Dow Inc facilities along the Texas Gulf Coast, and Sinopec installations in Zhejiang province. Feedstock supply draws from US shale gas basins, Saudi crude oil streams, and Chinese coal-to-chemicals conversion. Single-source vulnerability concentrates in ethane export terminal capacity at Marcus Hook and Morgan's Point. Distribution runs through integrated pipeline networks to downstream derivative plants, with seaborne resin cargoes serving Asian packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene market participants should treat carbon accounting services and mass-balance certification as attach-revenue streams expanding faster than base resin sales, as French and UK supermarket chains mandate Scope 3 auditing for polymer procurement.
For Market Incumbents: Insulate margin position by accelerating electric furnace retrofits at Gulf Coast assets before EU CBAM tariffs activate, and secure backward integration into bio-attributed feedstock supply through offtake partnerships with Brazilian bagasse gasification pilots. Electrification engineering talent scarcity threatens commissioning timelines for late movers. For New Entrants and Emerging Players: Build out specialty ethylene oxide capacity serving German hospital sterilization networks, where REACH carcinogenicity reviews are forcing reformulation of legacy surfactant products and creating qualification windows for pure-grade suppliers. Target medical packaging applications with dedicated purity certification. For Investors and Strategic Acquirers: Mid-scale compounders with established mass-balance certification infrastructure represent priority acquisition targets, as brand-owner procurement shifts from spot tenders to fixed-sustainability-premium contracts. Monitor EU CBAM implementation pace and certified low-carbon polyethylene price premiums as inflection signals for asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Cracking Retrofit | US Gulf Coast operators leveraging IRA hydrogen tax credits cut CO2 intensity per ton of ethylene output. |
| Crude-to-Chemicals Integration | Saudi Aramco and SABIC capture 45% more liquid chemicals per barrel at Jubail versus conventional refining. |
| Bio-Attributable Feedstock Partnership | Brazilian sugarcane bagasse gasification qualifies for RED III credits, opening premium polymer contracts. |
| Mass-Balance Certification Investment | French supermarket chains audit Scope 3 emissions, rejecting uncertified polyethylene volumes from spot markets. |
| Automotive Copolymer Qualification | German OEM thermal runaway protection standards drive ethylene-vinyl acetate substitution for metal battery encapsulation. |
Methodological Framework
Initial hypotheses were tested against primary input from steam cracker plant managers, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors at catalyst licensors, and refined through secondary validation against customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up capacity tallies triangulated against top-down demand elasticity models.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling across feedstock type, derivative grade tier, end-use industry, and regional production hub. CAGRs derived from elasticity-adjusted volume projections incorporating ethane-naphtha spread volatility and regulatory compliance cost trajectories. Forecast inputs included electric furnace technology readiness curves and EU CBAM tariff phase-in assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese producers or accelerated EU carbon border enforcement would shift outcomes beyond modeled ranges. Quarterly review of Mont Belvieu ethane differentials, EU carbon certificate pricing, and certified low-carbon polyethylene offtake premiums is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Diketene Market