
 Mercaptan Scavenger Market | 2026-2036
Mercaptan Scavenger Market Size, Share, and Industry Trends Forecast 2026-2036
Mercaptan Scavenger Market Foresight
Midstream gas processors is collapsing the historical dominance of refinery buyers in mercaptan scavenger procurement. Dow leverages its integrated chemical manufacturing base to sustain captive supply advantages across North American gas fields. SLB competes through technology leadership in high-pressure offshore scavenger deployment systems.
Mercaptan scavengers are sulfur-specific chemical agents, typically formulated from aldehyde-based or metal oxide compositions, that irreversibly bind thiol compounds to eliminate malodorous emissions and corrosion risks in hydrocarbon streams. Liquid scavengers dominate current volume owing to ease of continuous injection, while solid scavengers represent the fastest-growing category for remote offshore platforms where logistics constrain liquid handling. Natural gas processing applications anchor demand, though industrial waste management segments are gaining traction as environmental discharge standards tighten.
EPA sulfur regulations under the Clean Air Act shape product formulation requirements, while OSHA exposure limits drive handling protocol innovation across U.S. facilities. API standards for natural gas quality create certification barriers that filter supplier participation. Stakeholders must monitor evolving state-level hydrogen sulfide emission thresholds and assess backward integration into scavenger precursor chemicals as a hedge against feedstock volatility.
Market Dynamics
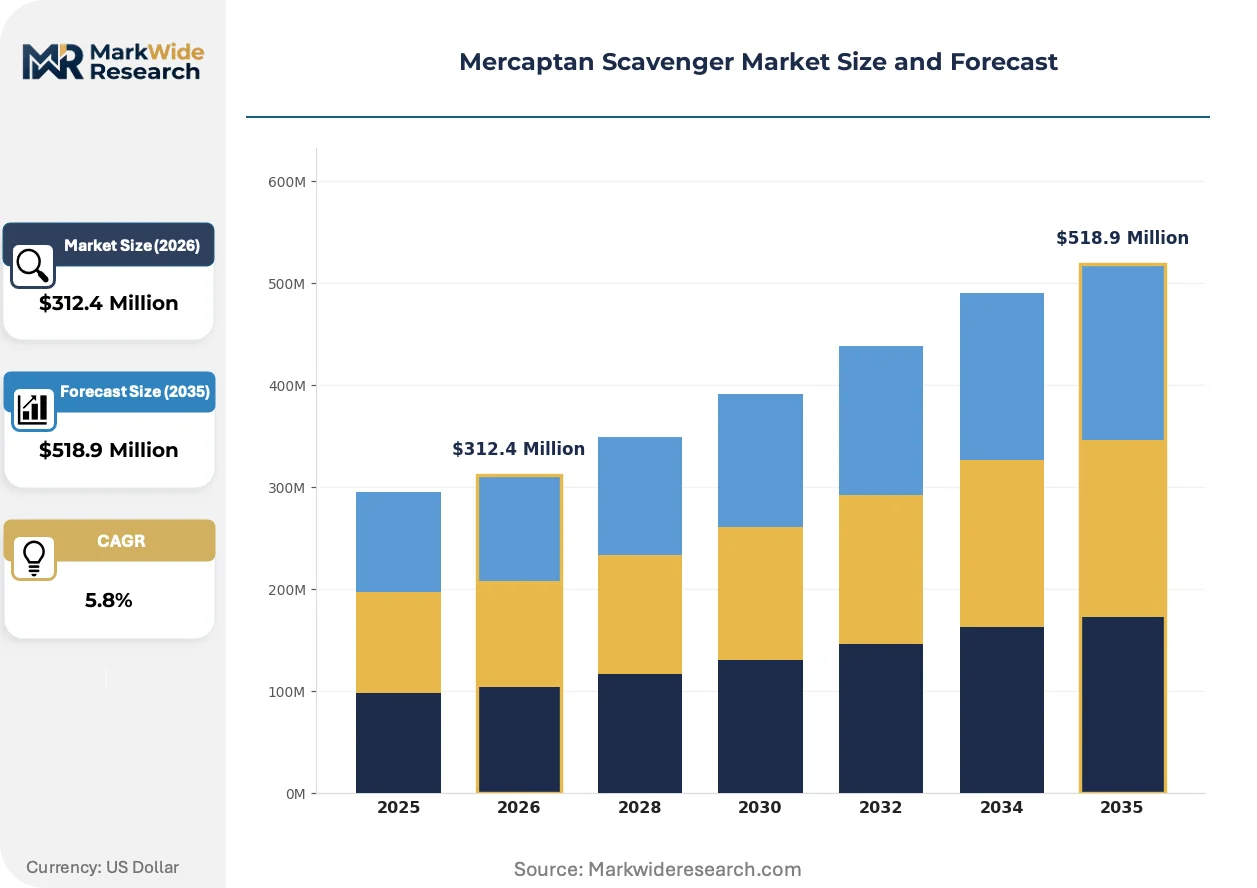
EPA sulfur emission standards under the Clean Air Act are compressing refinery operational margins and forcing accelerated scavenger deployment across sour gas treatment infrastructure, while midstream gas processors accumulate procurement leverage previously held by downstream buyers.
Growth Catalysts
- EPA Tier 3 Sulfur Standards:The regulation mandates maximum 10 parts per million sulfur in gasoline, compelling refineries to expand mercaptan scavenger injection capacity across catalytic reforming units and hydrotreater feed streams.
- Sour Gas Field Development:Permian Basin and Appalachian shale operators are scaling high-H2S production, creating continuous demand for scavenger systems at wellhead separation facilities and gathering compressor stations.
- Metal Oxide Formulation Advances:Iron-based and zinc oxide scavenger chemistries now achieve faster reaction kinetics at lower temperatures, enabling deployment in cryogenic natural gas processing environments previously unsuitable for aldehyde alternatives.
Market Restraints
- Formaldehyde Feedstock Volatility:Aldehyde-based scavenger production remains exposed to methanol price swings and formaldehyde supply disruptions from chemical manufacturing clusters in Texas and Louisiana.
- Specialized Logistics Infrastructure:Solid scavenger deployment requires pressurized pneumatic handling systems unavailable at many remote wellpad locations, constraining adoption to platforms with capital-intensive material handling investments.
- OSHA Permissible Exposure Limits:Worker handling protocols for concentrated scavenger formulations impose respiratory protection and ventilation requirements that elevate operational compliance costs above competing sulfur treatment technologies.
Strategic Opportunities
- Industrial Wastewater Treatment:Food processing and pulp mill effluent streams containing thiol compounds represent an emerging application segment with limited incumbent scavenger penetration and tightening discharge permits.
- Biogas Upgrading Facilities:Anaerobic digester operators in Germany and Denmark require mercaptan removal to meet grid injection specifications for biomethane, opening European demand outside traditional petrochemical channels.
- Modular Skid Systems:Containerized scavenger injection and regeneration units enable rental-based service models that reduce capital barriers for small-scale gas processors and intermittent production scenarios.
Industry Challenges
- API Monograph Certification Timelines:New scavenger formulations require 18-24 month qualification cycles through the American Petroleum Institute's natural gas quality standards, delaying commercialization and compressing effective patent windows.
- Cross-Contamination Risk Management:Scavenger carryover into downstream catalyst beds poisons hydrodesulfurization and reforming catalysts, necessitating complex analytical monitoring protocols that strain operational staffing.
- Legacy Amine System Integration:Existing acid gas removal units using MDEA or DEA chemistries require mechanical retrofitting to accommodate scavenger injection points, creating project execution complexity and extended turnaround schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercaptan Scavenger Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Scavengers, Solid Scavengers, Gas Scavengers, Adsorbents End User: Petrochemical Industry, Chemical Manufacturing, Oil Refineries, Water Treatment Deployment Mode: Onshore, Offshore, Mobile Units, Fixed Installations Application: Natural Gas Processing, Sour Gas Treatment, Refinery Operations, Industrial Waste Management |
| Companies Covered | BASF, Huntsman International, SLB, Nalco Water, INEOS, Halliburton, AkzoNobel, General Electric, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercaptan Scavenger Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are diverging across end-use requirements, with solid-phase systems gaining traction in offshore logistics-constrained environments while liquid systems automate for continuous refinery injection.
Non-regenerable solid scavenger media is fragmenting the historical dominance of liquid injection systems in offshore natural gas production. Shell and BP deploy iron-oxide impregnated ceramic pellets on North Sea platforms where helicopter logistics constrain liquid chemical resupply frequency. This shift compresses service contract margins for liquid scavenger suppliers while opening equipment-leasing revenue pools for solid media handling systems.
REACH authorization requirements for formaldehyde-based substances are forcing formulation reformulation across European mercaptan scavenger suppliers. The ECHA restriction process elevates metal oxide and non-aldehyde alternatives toward regulatory preference in EU member states. German chemical distributors now stock segregated inventory lines for REACH-compliant versus legacy formulations, creating dual-supply-chain complexity.
Long-term service agreements are displacing spot procurement at major gas processing facilities. Midstream operators in the US Gulf Coast now contract 3-5 year scavenger supply with embedded technical service and automated inventory monitoring. This consolidation concentrates volume with integrated chemical suppliers capable of field engineering deployment, marginalizing commodity traders and regional distributors.
Mercaptan Scavenger Market Segmentation
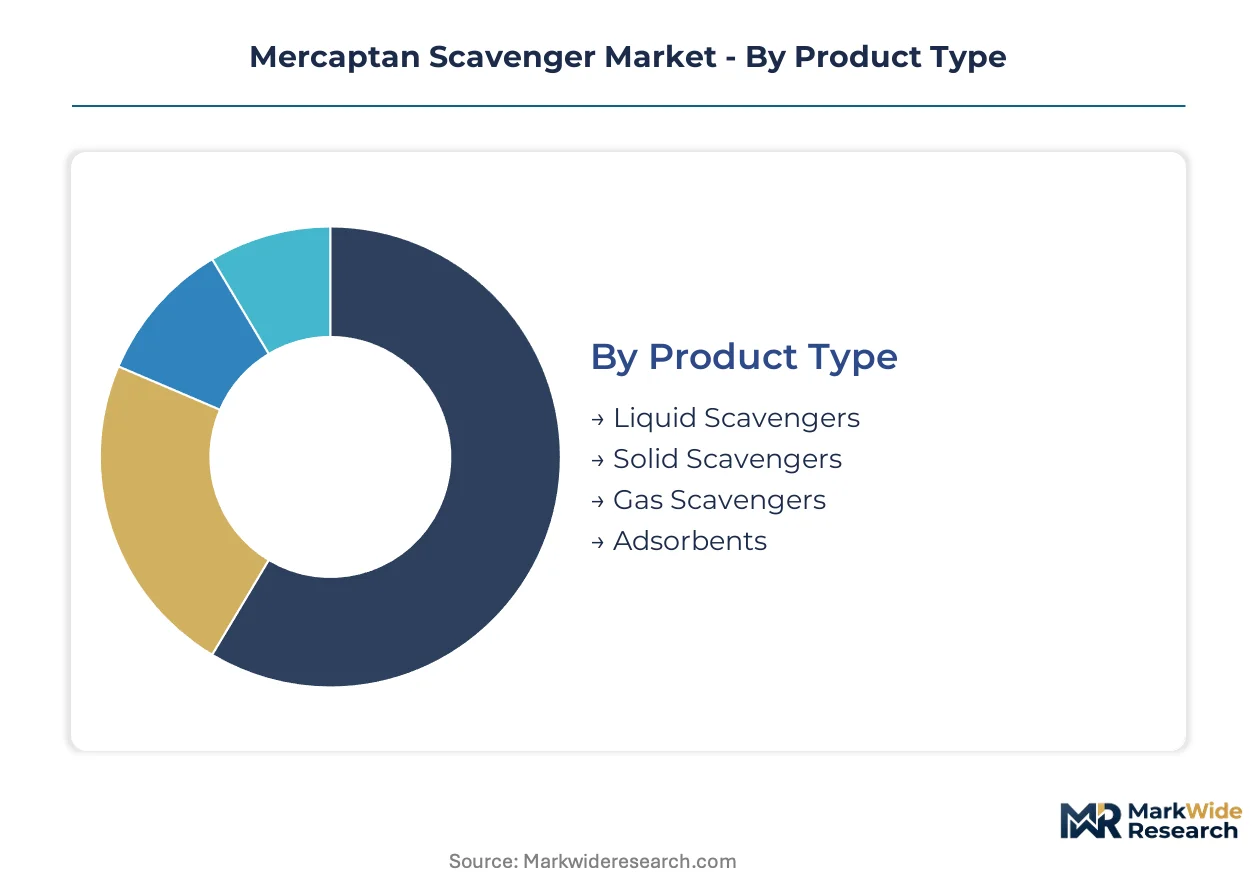
Mercaptan scavenger procurement patterns diverge sharply across product forms and deployment contexts, with logistics constraints and regulatory exposure reshaping how buyers evaluate substitution risks between aldehyde, metal oxide, and emerging non-formaldehyde alternatives.
Product Type:
Aldehyde-based formulations face intensifying substitution pressure from metal oxide and bio-based alternatives as OSHA exposure limits tighten and REACH authorization timelines accelerate reformulation investments.
- Liquid Scavengers:Continuous injection systems dominate refinery and midstream gas processing infrastructure, with Dow and SLB supplying automated dosing equipment integrated into existing amine unit footprints. EPA Tier 3 sulfur standards compress operational margins for refineries along the US Gulf Coast, forcing expanded scavenger capacity at catalytic reforming units.
- Solid Scavengers:Iron-oxide impregnated ceramic pellets enable deployment on North Sea platforms where helicopter logistics constrain liquid chemical resupply frequency. Shell and BP operations favor these systems for sour gas treatment in remote offshore environments with limited material handling infrastructure.
- Gas Scavengers:Vapor-phase injection systems target cryogenic natural gas processing where liquid carryover risks poison downstream catalyst beds.
- Adsorbents:Activated carbon and zeolite media compete in biogas upgrading facilities requiring mercaptan removal to meet grid injection specifications.
Liquid scavengers anchor the volume base while solid scavengers gain share at the steepest rate.
End User:
Procurement leverage concentrates with midstream gas processors as sour field development outpaces refinery capacity expansion, shifting volume concentration from downstream to upstream hydrocarbon handling.
- Petrochemical Industry:Ethylene cracker feedstock pretreatment and pyrolysis gas streams require mercaptan removal to protect precious metal catalysts from sulfur poisoning. Gulf Coast petrochemical corridor operators specify API-certified formulations with guaranteed non-detect carryover limits.
- Oil Refineries:Catalytic reforming and hydrotreater feed streams drive the largest absolute scavenger consumption volumes. EPA Tier 3 mandates for 10 ppm maximum gasoline sulfur compel expanded injection capacity across FCC naphtha and straight-run gasoline processing trains.
- Chemical Manufacturing:Specialty chemical producers handling thiol-containing feedstocks deploy scavengers for worker safety and product quality assurance.
- Water Treatment:Industrial effluent discharge permits for pulp mills and food processors represent an emerging application with limited incumbent penetration.
Oil refineries anchor the volume base while water treatment gains share most rapidly.
Deployment Mode:
Capital intensity and logistics frequency determine competitive positioning, with offshore and mobile configurations commanding premium pricing against standardized onshore installations.
- Onshore:Fixed pipeline injection skids and wellhead separation facilities at Permian Basin and Appalachian shale fields represent the highest-volume deployment category. Automated inventory monitoring and 3-5 year service agreements now dominate procurement patterns.
- Offshore:Platform-based scavenger systems face extreme logistics constraints that favor solid media and regenerable chemistries over continuous liquid injection. North Sea operators specify equipment-leasing models that transfer resupply risk to chemical suppliers.
- Mobile Units:Containerized skid systems enable rental-based service models for intermittent production scenarios and small-scale gas processors.
- Fixed Installations:Permanent integration with acid gas removal units requires mechanical retrofitting of MDEA or DEA systems to accommodate scavenger injection points.
Onshore deployments anchor the volume base while mobile units expand most quickly.
Application:
Natural gas quality specifications and sulfur emission thresholds create divergent formulation requirements, with refinery operations demanding higher-performance chemistries than industrial waste streams.
- Natural Gas Processing:Cryogenic turboexpander plants and NGL fractionation trains require mercaptan removal to meet pipeline tariff specifications and prevent hydrate formation. Metal oxide scavengers achieve faster reaction kinetics at lower temperatures than aldehyde alternatives.
- Refinery Operations:Catalytic reformer feed pretreatment and gasoline blending operations face the most stringent sulfur constraints. Cross-contamination risk into hydrodesulfurization catalyst beds necessitates complex analytical monitoring protocols.
- Sour Gas Treatment:High-H2S production from Permian Basin and Appalachian shale creates continuous demand at wellhead separation facilities and gathering compressor stations.
- Industrial Waste Management:Food processing and pulp mill effluent streams containing thiol compounds represent an emerging segment with tightening discharge permits and limited incumbent scavenger penetration.
Natural gas processing anchors the volume base while industrial waste management climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American mercaptan scavenger demand, with pipeline networks connecting Permian Basin production to Texas and Louisiana processing clusters.
United States
EPA Tier 3 sulfur standards and sour gas development in the Permian Basin and Appalachian shale fields drive procurement. OSHA permissible exposure limits for formaldehyde-based formulations shape handling protocols at Gulf Coast refineries. Houston and Beaumont host the densest concentration of catalytic reforming units deploying continuous liquid scavenger injection.
Germany
Biogas upgrading facilities in Lower Saxony and Bavaria require mercaptan removal for grid injection compliance. REACH authorization timelines for formaldehyde-based substances accelerate metal oxide formulation adoption. The Emsland region clusters anaerobic digester operators sourcing REACH-compliant scavenger alternatives.
Saudi Arabia
Sour gas processing at the Shaybah and Khurais fields sustains demand for high-temperature scavenger systems. The country's national oil company mandates API-certified formulations for natural gas quality assurance. The Eastern Province concentrates gas treatment infrastructure serving domestic petrochemical feedstock supply.
China
Shale gas development in Sichuan and tight gas production in Ordos Basin expand wellhead scavenger deployment. MIIT industrial standards for natural gas quality create certification requirements for sulfur treatment chemicals. The Yangtze River Delta hosts specialty chemical producers formulating metal oxide alternatives to imported aldehyde systems.
Brazil
Pre-salt field development off the Santos Basin drives offshore scavenger demand for floating production platforms. ANP natural gas quality specifications mandate mercaptan limits for pipeline delivery. Rio de Janeiro state anchors service contractor operations supporting deepwater gas treatment infrastructure.
Mercaptan Scavenger Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and oilfield service specialists. The vendor base stratifies across three tiers: global diversified chemical suppliers with captive raw material positions, specialized oilfield chemical providers with deployment technology, and regional distributors serving intermittent spot demand. Strategic moves center on backward integration into scavenger precursor chemicals and long-term service contracting to lock in midstream gas processor volumes.
Within the integrated chemical tier, BASF and Dow exemplify archetypes leveraging manufacturing scale and feedstock control across European and North American gas fields. SLB anchors the oilfield service specialist position, representing technology-led deployment capabilities in high-pressure offshore environments. These three occupy distinct competitive spaces: manufacturing depth versus field engineering integration versus platform-specific system design.
| Leading Market Players |
|---|
| BASF |
| Huntsman International |
| SLB |
| Nalco Water |
| INEOS |
| Halliburton |
| AkzoNobel |
| General Electric |
| Dow |
| Others |
Supply & Pricing Matrix
Long-term service agreements spanning three-to-five-year terms now lock in both scavenger supply access and price visibility for midstream gas processors across the US Gulf Coast, compressing spot market liquidity and transferring inventory risk to integrated chemical suppliers with captive formaldehyde and metal oxide precursor positions.
Pricing Analysis
Three-tier pricing structure across API-certified premium, standard industrial, and economy bulk grades separates refinery buyers demanding guaranteed non-detect carryover limits from cost-sensitive shale operators. Price differentiation hinges on certification tier and embedded technical service intensity. Pricing pressure stems from formaldehyde feedstock volatility at Texas and Louisiana chemical manufacturing clusters. Small-scale Appalachian gas processors exhibit highest price sensitivity, while Gulf Coast petrochemical corridor operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs through Houston Ship Channel congestion and container availability constraints on Asia-North America trade lanes elevate landed costs for metal oxide raw materials sourced from Chinese specialty chemical producers. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta anchoring metal oxide formulation capacity. Feedstock dependencies include methanol, formaldehyde, iron oxide precursors, and ceramic pellet substrates. Single-source vulnerability persists for high-purity zinc oxide. Distribution runs through integrated chemical suppliers with field engineering capabilities, marginalizing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where automated inventory monitoring, equipment leasing, and technical field support now expand faster than commodity scavenger volume, rewarding suppliers capable of bundling chemical supply with deployment engineering.
For Market Incumbents: Consolidate procurement leverage by extending backward integration into formaldehyde and metal oxide precursor production, insulating margin structures from methanol price swings. Deepen captive supply positions across Texas and Louisiana chemical manufacturing corridors. Lock in midstream gas processor volumes through embedded technical service contracts that raise switching costs for competitors lacking field engineering density. For New Entrants and Emerging Players: Technical service gaps in modular skid deployment for intermittent Permian Basin production scenarios offer white-space entry points. Target small-scale gas processors underserved by integrated suppliers requiring minimum volume commitments. Pursue equipment-leasing revenue models that transfer resupply risk to operators, avoiding direct competition on commodity scavenger pricing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated chemical suppliers with captive feedstock positions and field service infrastructure. Long-term viability over the coming decade hinges on regulatory compliance capabilities as REACH and OSHA exposure limits tighten. Monitor API Monograph certification timelines as inflection indicators for formulation commercialization velocity and effective patent window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive formaldehyde supply from Texas and Louisiana manufacturing clusters insulates margin exposure to methanol volatility. |
| Long-term Service Contracting | Three-to-five-year agreements with automated inventory monitoring lock in midstream gas processor volumes and raise rival switching costs. |
| Modular Skid System Deployment | Containerized injection and regeneration units enable rental-based models that reduce capital barriers for intermittent production scenarios. |
| REACH-Compliant Formulation Development | Metal oxide and non-aldehyde alternatives secure European market access as ECHA authorization timelines accelerate. |
| Offshore Equipment Leasing | Platform-based solid media handling systems transfer helicopter logistics risk to suppliers in North Sea and pre-salt environments. |
Research Methodology
A spread of perspectives from refinery operations managers, midstream gas procurement leads, chemical plant technical directors, and oilfield service deployment engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA regulatory filings, API standards documentation, customs and trade data, and SEC disclosures from integrated chemical suppliers. Bottom-up volume estimates from individual facility deployments triangulated against top-down market sizing from feedstock consumption patterns.
Segmentation dimensions modeled include scavenger formulation chemistry, product physical state, deployment mode capital intensity, end-use industry sulfur constraint severity, and regional regulatory framework clustering. CAGRs were derived from trend extrapolation of sour gas field development trajectories, refinery capacity utilization patterns, and EPA enforcement intensity across the projection horizon. Industry-specific forecast inputs incorporated Permian Basin H2S concentration trends and biogas upgrading facility commissioning rates in Germany and Denmark.
Forecasts assume regulatory continuity in EPA Tier 3 sulfur standards and REACH authorization timelines; material policy shifts would require re-modeling of refinery and biogas demand trajectories. Practitioners should keep alternative scenarios live as OSHA permissible exposure limit revisions and state-level hydrogen sulfide emission threshold adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Gluconic Acid Market