
 Europe Barium Carbonate Market | 2026-2036
Europe Barium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Barium Carbonate Market Intelligence
Asset-light leasing models for chemical processing equipment are rewriting competitive entry barriers across the European barium carbonate landscape. Solvay leverages its integrated chlor-alkali network to sustain captive feedstock advantages in Western Europe. Norkem Limited anchors its position through specialized distribution control across Nordic and British markets. AG Chemi Group competes by occupying niche technical-grade segments where batch consistency commands premium positioning.
Barium carbonate is an inorganic salt with the chemical formula BaCO₃, typically produced through the soda ash or carbonation of barium sulfide, and functions primarily as a fluxing agent, crystallization stabilizer, and source of barium oxide in high-temperature industrial processes. Technical grade material dominates volume flows into ceramic tile and sanitaryware production across Southern Europe, where cost-sensitive formulation standards prevail. Chemical grade segments are gaining structural importance in specialty glass manufacturing, particularly for CRT and optical applications where strontium-barium ratios require precise control. Optical grade categories concentrate margin pools through limited qualified supply and stringent particle-size distribution requirements enforced by German and French optical component fabricators.
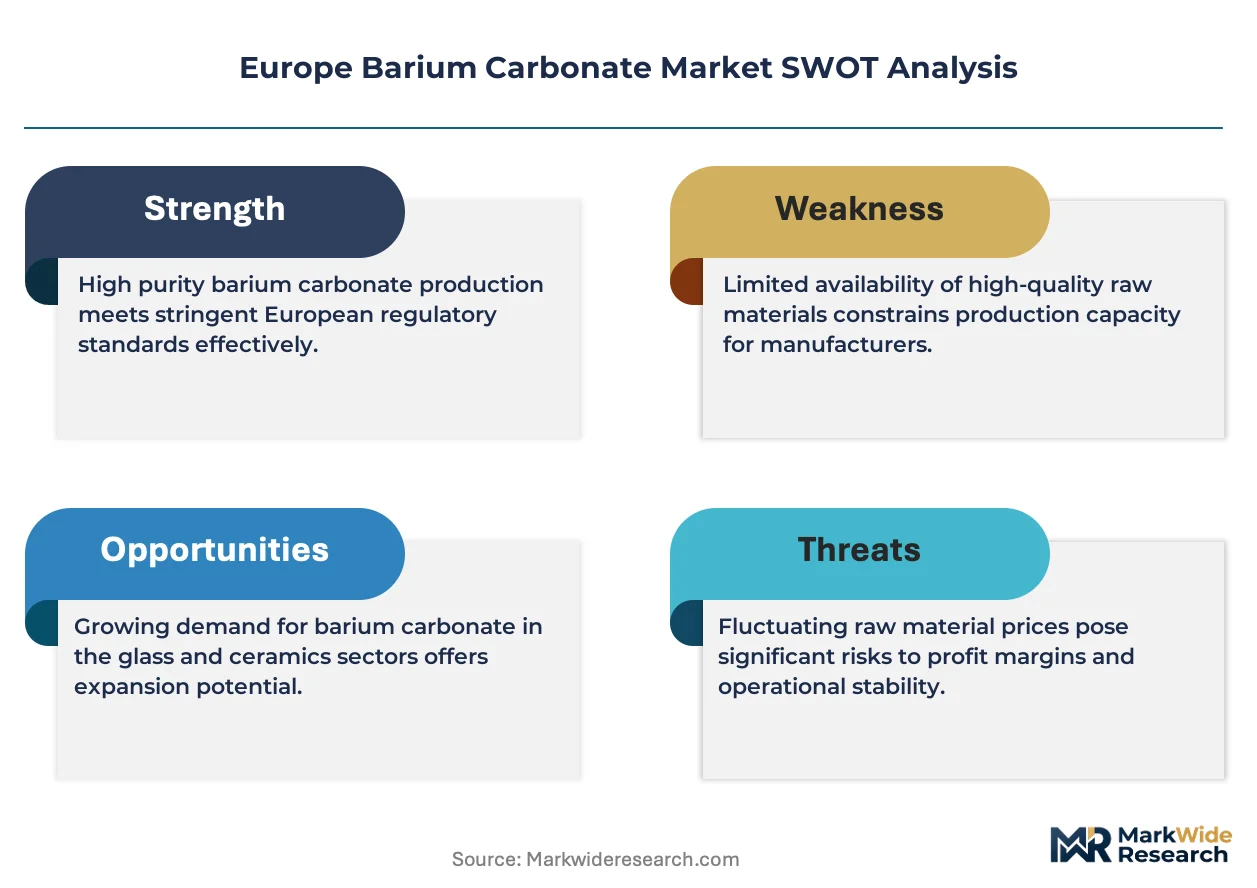
REACH registration obligations administered by ECHA mandate full substance dossiers for barium carbonate importers and manufacturers, elevating compliance costs that disproportionately burden smaller traders. The EU Green Deal's industrial emissions framework pushes ceramic and glass producers toward lower-carbon process routes, indirectly filtering barium carbonate sourcing toward suppliers with verified carbon footprints. Germany's Federal Institute for Risk Assessment and France's ANSES coordinate hazard classification updates that ripple through safety data sheet requirements and end-user handling protocols. Stakeholders must monitor evolving hazard classifications and carbon border adjustment mechanisms to preserve market access and margin structures.
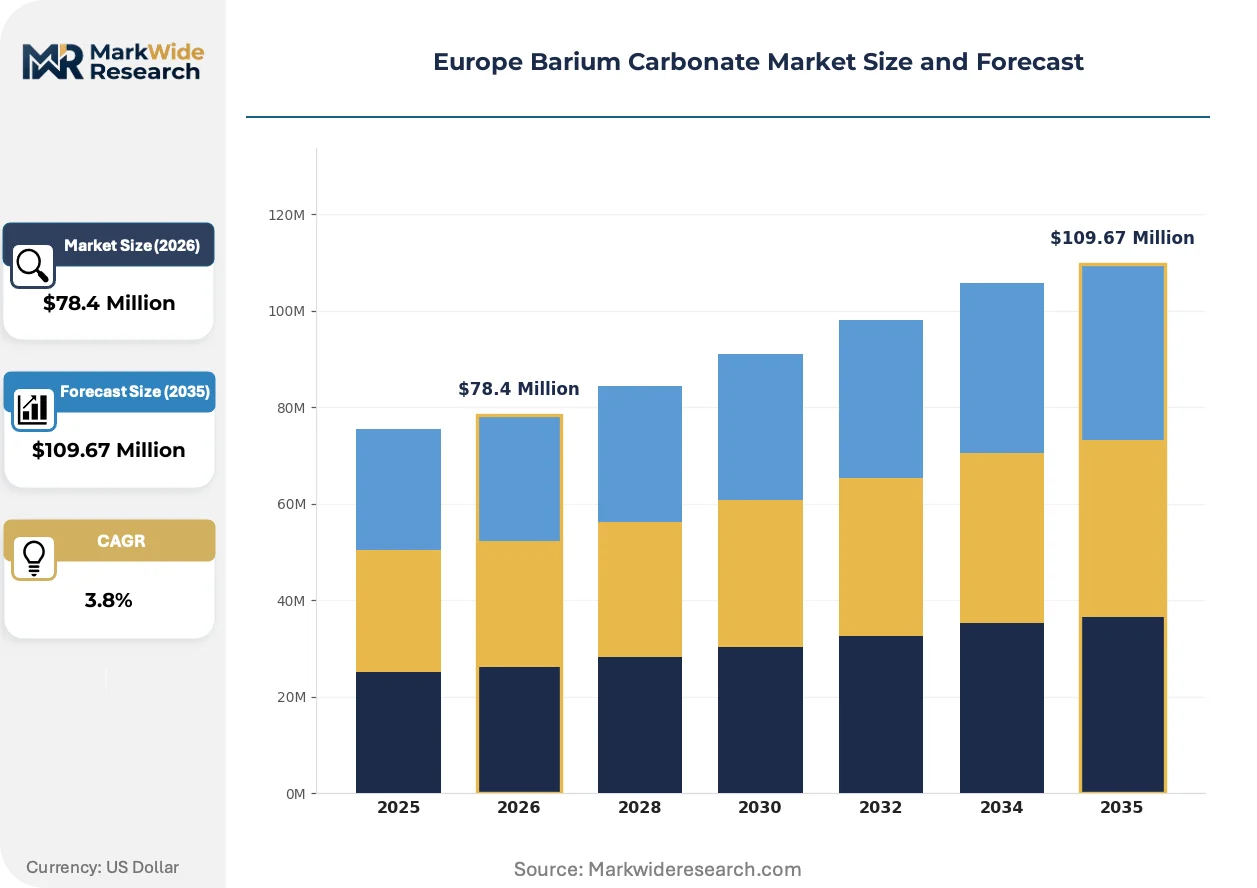
Market Dynamics
REACH compliance administered by ECHA is compressing supplier qualification timelines and elevating purity documentation burdens across European barium carbonate procurement channels. Specialty glass manufacturers in Germany and Italy now require third-party verified carbon footprints alongside traditional assay certificates, restructuring competitive entry barriers for traders and integrated producers alike.
Growth Catalysts
- EU Green Deal industrial emissions framework:Ceramic producers across Czech and Polish manufacturing clusters are retrofitting kilns with lower-carbon process routes, filtering sourcing toward barium carbonate suppliers with verified Scope 1-2 emissions data.
- Optical grade material qualification:German and French optical component fabricators are tightening particle-size distribution specifications for high-purity barium carbonate used in precision lens and prism manufacturing.
- Central European ceramic corridor expansion:Sanitaryware and tile production concentration around Czech and Polish industrial zones is concentrating volume demand for technical grade fluxing agents.
Market Restraints
- Barite ore supply concentration:Dependence on Chinese and Moroccan barite concentrate imports exposes European processors to freight volatility and geopolitical supply interruptions.
- REACH registration cost escalation:Full substance dossier requirements for barium carbonate importers disproportionately burden smaller traders, consolidating market access around capitalized incumbents.
- Strontium carbonate substitution:Partial replacement of barium in certain specialty glass formulations reduces volume elasticity in price-sensitive CRT legacy segments.
Strategic Opportunities
- Nordic distribution network gaps:Specialized chemical distributors with cold-chain and hazardous materials capabilities remain underdeveloped across Scandinavian markets relative to Continental density.
- Carbon border adjustment mechanism readiness:Early alignment with EU CBAM documentation requirements positions qualified suppliers for preferential access as full implementation phases in.
- Digital assay verification platforms:Blockchain-anchored certificate of analysis systems are emerging as differentiation tools for technical grade material procurement in Southern European tile manufacturing.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified laboratory personnel for ICP-MS trace metal analysis and particle characterization are concentrated in German and Swiss industrial clusters, constraining quality expansion elsewhere.
- Legacy kiln integration complexity:Ceramic manufacturers operating decades-old continuous firing equipment face technical barriers to optimizing barium carbonate dosing for modified fluxing profiles.
- Multi-jurisdiction safety data sheet harmonization:Divergent hazard classification updates between Germany's Federal Institute for Risk Assessment and France's ANSES create compliance friction for cross-border traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Barium Carbonate Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $109.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Chemical Grade, Optical Grade, Other Application: Glass Manufacturing, Ceramic Production, Rubber Industry, Pigments End User: Construction, Automotive, Electronics, Agriculture Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Norkem Limited, Kamman Group, AG Chemi Group, Chemical Products Corporation, Solvay, Nippon Chemical Industrial, Honeywell International Inc, Hebei Xinji Chemical Group Co., Ltd., Hubei Jingshan Chutian Barium Salt Corp. Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Barium Carbonate Market Strategic Shifts & Innovations
Process intensification technologies and digital quality assurance systems are restructuring production economics and procurement verification protocols across European barium carbonate value chains. These shifts are compressing batch-to-batch variability tolerance and accelerating supplier consolidation pressures.
Continuous carbonation reactor systems are collapsing the capital-labor tradeoffs that historically favored batch soda ash processing. German specialty chemical producers are piloting these units for high-purity optical grade output, achieving tighter particle-size distribution control than conventional equipment permits. This technology is collapsing minimum efficient scale thresholds for premium material segments.
REACH registration obligations administered by ECHA now mandate updated exposure scenario annexes for barium carbonate downstream uses. The regulation forces ceramic and glass manufacturers to document workplace inhalation controls and environmental release estimates, elevating documentation burdens for importers without in-house regulatory affairs capacity. Specialty glass segments in France and Italy are responding by consolidating supplier panels around REACH-consistent integrated producers.
Certificate-of-analysis unbundling from physical delivery is compressing procurement cycle times for technical grade material buyers. Southern European tile manufacturers now source assay-verified barium carbonate through digital platforms that decouple quality confirmation from logistics scheduling, displacing traditional distributor-held inventory models. This pattern concentrates most visibly in Spanish and Portuguese ceramic clusters where working capital efficiency commands formulation priority.
Europe Barium Carbonate Market Segmentation
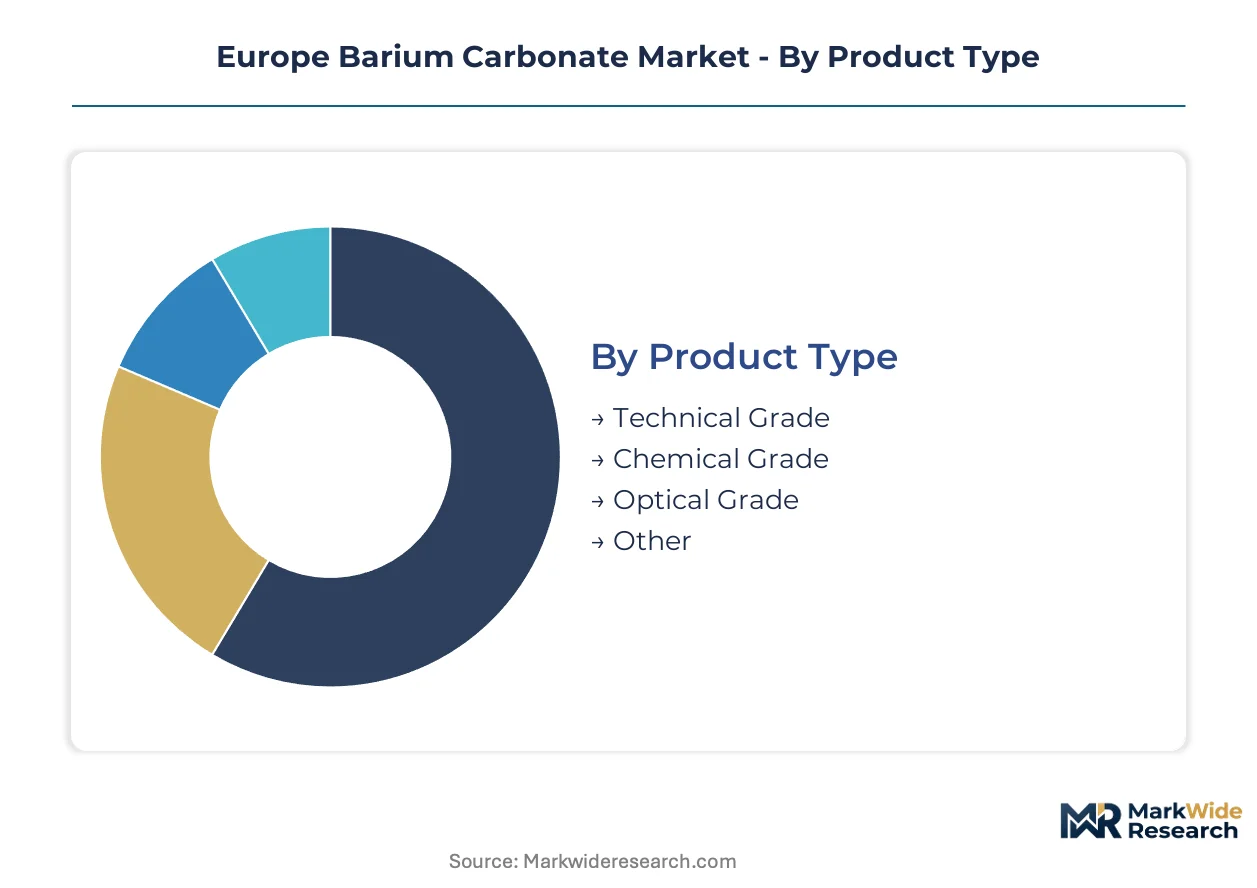
Barium carbonate procurement patterns across Europe diverge sharply by purity specification and end-use technical requirements. Each segment tier commands distinct qualification protocols, pricing structures, and supplier relationship models that reshape competitive positioning.
Product Type:
Technical specifications span fluxing agents for mass ceramic production through sub-micron optical materials for precision lens fabrication.
- Technical Grade:Standard purity material (98-99% BaCO₃) serves as the primary fluxing agent in ceramic tile and sanitaryware kilns across Spanish and Italian manufacturing clusters. Czech and Polish producers favor this grade for cost-sensitive continuous firing operations where batch consistency outweighs trace metal limits.
- Chemical Grade:Higher purity specifications (99.5%+ BaCO₃) with controlled chloride and sulfate content support specialty glass manufacturing in Germany and France. REACH documentation requirements from ECHA now mandate third-party assay verification for this tier, consolidating procurement around integrated producers with captive analytical capabilities.
- Optical Grade:Sub-micron particle-size distribution with stringent trace metal controls (Fe <10ppm, Sr <100ppm) for precision optical component fabrication.
- Other:Niche specifications including pharmaceutical-grade and laboratory reagent categories with limited European production volume.
Established volume favors Technical Grade; emerging adoption favors Optical Grade.
Application:
End-use concentration patterns track Central European industrial corridor development and specialty manufacturing enclaves.
- Glass Manufacturing:Specialty optical and display glass producers in Germany and France require precise strontium-barium ratio control for refractive index engineering. CRT legacy demand persists in Eastern European repair markets while optical segment growth concentrates around Munich and Stuttgart precision clusters.
- Ceramic Production:Sanitaryware and tile manufacturing across Czech, Polish, and Italian industrial zones consumes technical grade material as a primary flux to lower firing temperatures and control crystallization. Kiln retrofit programs under EU Green Deal emissions frameworks are modifying dosing protocols and supplier qualification standards.
- Rubber Industry:Filler and weighting agent applications in industrial rubber compounding with moderate purity requirements.
- Pigments:Lithopone precursor applications and specialty coating formulations with declining volume share.
Glass Manufacturing commands premium positioning; Ceramic Production anchors volume scale.
End User:
Customer archetypes range from capital-intensive continuous processors to specification-driven precision manufacturers.
- Construction:Ceramic tile and sanitaryware producers across Mediterranean and Central European manufacturing belts drive bulk technical grade procurement with price-sensitive tender processes.
- Automotive:Specialized glass applications for lighting and sensor housings with emerging demand from electric vehicle battery component sealing applications.
- Electronics:CRT display refurbishment markets in Eastern Europe and precision optical substrate fabrication for semiconductor equipment.
- Agriculture:Limited volume in rodenticide formulations with declining regulatory tolerance under EFSA hazard classification reviews.
Construction sector procurement dominates volume flows; Electronics segment captures margin concentration.
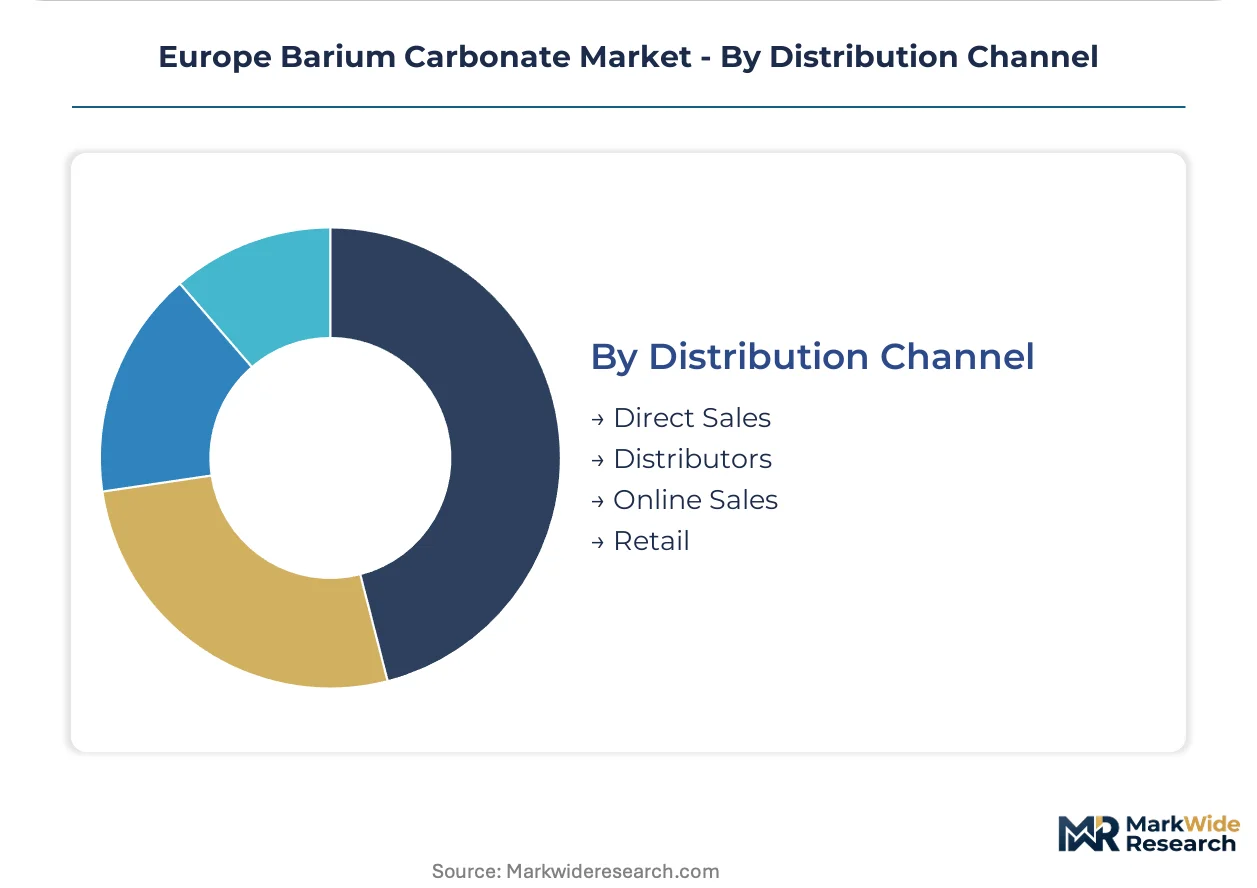
Distribution Channel:
Channel structure reflects hazardous material handling requirements and customer scale segmentation across the continent.
- Direct Sales:Integrated producers including Solvay supply large-volume ceramic and glass manufacturers through dedicated account management with embedded technical service support. German and French optical fabricators require direct relationships for customized particle-size distribution and certificate-of-analysis protocols.
- Distributors:Specialized chemical distributors including Norkem Limited control Nordic and British market access with cold-chain and hazardous materials capabilities. Southern European tile clusters increasingly source through digital platforms that unbundle assay verification from physical logistics.
- Online Sales:Laboratory and small-batch industrial procurement through B2B chemical marketplaces with standardized packaging.
- Retail:Minimal presence limited to artisan ceramic supply and educational laboratory segments.
Direct Sales concentrate in premium tiers; Distributors span geographic coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's barium carbonate trade flows reflect a structural import dependency, with Chinese and Moroccan barite concentrate feeding Central European processing corridors. REACH compliance administered by ECHA now filters cross-border shipments through tightened purity documentation requirements.
Germany
Optical glass fabricators in Munich and Stuttgart precision clusters drive demand for sub-micron particle-size distribution material. The Federal Institute for Risk Assessment coordinates hazard classification updates that ripple through safety data sheet requirements. Bavarian specialty chemical producers pilot continuous carbonation reactor systems for high-purity output.
Italy
Sanitaryware manufacturers across Emilia-Romagna consume technical grade fluxing agents for cost-sensitive continuous firing operations. ANSES hazard classification protocols create compliance friction for cross-border traders serving French optical component fabricators. Sassuolo ceramic tile clusters increasingly source through digital platforms that unbundle assay verification from logistics.
Czech Republic
Kiln retrofit programs under EU Green Deal emissions frameworks are modifying dosing protocols for Central European ceramic corridors. ECHA REACH registration obligations mandate full substance dossiers for importers operating without in-house regulatory affairs capacity. Plzeň manufacturing zones concentrate volume procurement for technical grade material.
Poland
Construction sector ceramic production anchors bulk technical grade procurement with price-sensitive tender processes. EU CBAM documentation requirements position early-aligned suppliers for preferential access as full implementation phases in. Łódź industrial belts host expanding sanitaryware manufacturing clusters.
France
Precision lens and prism fabricators enforce stringent trace metal controls on high-purity barium carbonate inputs. ANSES coordinates with German regulators on divergent hazard classification updates affecting cross-border safety data sheet harmonization. Auvergne-Rhône-Alpes optical component clusters tighten supplier qualification timelines.
Europe Barium Carbonate Market Key Industry Players
On the supply side, the industry is consolidating around integrated producers with captive feedstock networks and specialized distributors with hazardous materials capabilities. Three archetypes dominate: chlor-alkali integrated chemical majors controlling Western European production, Nordic-British specialized distributors managing cold-chain logistics, and batch-consistent technical grade specialists serving cost-sensitive Southern European ceramic clusters. Competitive moves center on REACH dossier completion for market access preservation and carbon footprint verification for EU Green Deal alignment.
Among integrated chemical producers, Solvay anchors the Western European supply position through chlor-alkali network integration. Specialized distributors Norkem Limited and AG Chemi Group occupy complementary geographic and segment positions, with the former controlling Nordic and British market access and the latter concentrating on technical grade batch consistency for premium positioning. These three entities exemplify the tiered competitive structure separating integrated production from distribution-controlled regional access.
| Leading Market Players |
|---|
| Norkem Limited |
| Kamman Group |
| AG Chemi Group |
| Chemical Products Corporation |
| Solvay |
| Nippon Chemical Industrial |
| Honeywell International Inc |
| Hebei Xinji Chemical Group Co., Ltd. |
| Hubei Jingshan Chutian Barium Salt Corp. Ltd. |
| Others |
Cost & Logistics Intelligence
Underutilized carbonation reactor capacity across German specialty chemical corridors is compressing spot pricing for optical-grade material while forcing technical-grade producers toward contract-of-take structures with Czech and Polish ceramic clusters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on REACH dossier completeness and verified carbon footprint documentation under EU Green Deal frameworks. Cost compression in technical-grade tiers is intensifying because Italian and Spanish tile manufacturers are consolidating procurement panels around digital assay-verified suppliers. Construction-sector ceramic producers exhibit highest price sensitivity, while German optical fabricators prioritize batch consistency over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration for barium carbonate processing rests with Solvay's chlor-alkali integrated network in Western Europe and specialized toll processors in Central European chemical corridors. Geographic supply draws from Chinese and Moroccan barite concentrate imports, with secondary dependence on Turkish and Kazakh ore sources. Raw material dependencies center on high-purity barite concentrate, soda ash fluxing agents, and sulfuric acid for sulfide intermediate production. Single-source vulnerability to Chinese barite export quotas creates structural risk exposure. Distribution runs through specialized chemical distributors with hazardous materials handling certifications serving Nordic and British market gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified ICP-MS analytical chemists are concentrated in German and Swiss industrial clusters, constraining quality expansion for REACH-compliant material production elsewhere in Europe.
For Market Incumbents: Build regulatory dossier moats by completing updated ECHA exposure scenario annexes for downstream ceramic and glass applications. Secure captive barite concentrate offtake agreements with Moroccan and Turkish mining operators to insulate against Chinese export quota volatility. Invest in continuous carbonation reactor capacity for optical-grade particle-size distribution control. For New Entrants and Emerging Players: Pursue Nordic distribution network gaps where cold-chain and hazardous materials capabilities remain underdeveloped relative to Continental density. Target technical-grade segments in Polish and Czech sanitaryware clusters where price-sensitive tender processes favor new suppliers with working capital flexibility. Establish digital assay verification platforms as differentiation tools for Southern European tile procurement. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with captive chlor-alkali feedstock networks and completed REACH registration portfolios. Long-term viability across the analysis window favors asset-light distributors with hazardous materials specialization over capital-intensive processing entrants. Watch for EU CBAM implementation phasing as inflection indicator for carbon-verified supplier preferential access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Concentrate Supply | Captive ore sourcing from Moroccan and Turkish deposits reduces Chinese quota exposure for European processors. |
| Continuous Carbonation Reactor Deployment | German specialty chemical producers achieve tighter particle-size distribution control than conventional batch equipment permits. |
| REACH Exposure Scenario Annex Completion | ECHA-mandated documentation for downstream ceramic and glass uses preserves market access against non-compliant traders. |
| Digital Assay Verification Platform Launch | Blockchain-anchored certificate-of-analysis systems compress procurement cycle times for Spanish and Portuguese tile clusters. |
| EU CBAM Documentation Alignment | Early carbon footprint verification positions suppliers for preferential access as full border adjustment implementation phases in. |
Research Approach
The analysis maps technical-grade, chemical-grade, and optical-grade production segments, each validated through plant managers at Central European ceramic manufacturers, procurement leads at German optical fabricators, distribution channel partners across Nordic markets, and technical R&D directors at specialty glass producers. Primary interview insights triangulate against secondary sources including ECHA REACH registration databases, Eurostat customs trade flows, Cefic chemical industry reports, and SEC filings from integrated chemical producers. Bottom-up volume modeling from individual production facilities reconciles with top-down demand aggregation across end-use industries.
Assumptions held fixed include ECHA regulatory enforcement intensity, EU Green Deal emissions framework trajectory, and Chinese barite export policy continuity; variables tested include kiln retrofit adoption rates across Czech and Polish ceramic corridors and digital procurement platform penetration in Southern Europe. Segmentation dimensions span purity grade tier, end-use industry concentration, and regional production hub clustering. CAGRs derive from logistic curve fitting to historical volume trajectories with elasticity adjustments for substitution risk from strontium carbonate in specialty glass formulations.
Macroeconomic conditions sit as an overlay; deviation in European construction sector output, Chinese industrial policy toward critical mineral exports, or ECHA hazard classification updates would shift the trajectory. Quarterly review of ECHA registration completion rates, EU CBAM pilot phase documentation requirements, and German Federal Institute for Risk Assessment hazard classification bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Precipitated Fine Hydrate Market