
 Barium Chloride Market | 2026-2036
Barium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Chloride Market Analysis
Modular packaging of barium chloride dihydrate in moisture-resistant bulk totes is hardening as the default procurement format for water treatment facilities. Solvay S.A. leverages its integrated chlor-alkali network to sustain cost-competitive anhydrous grades across European industrial channels. Shandong Xinke Environmental Chemistry Co., Ltd. anchors regional supply through backward integration into barite mining and hydrochloric acid recovery. American Elements specializes in high-purity electronic-grade material for semiconductor etching applications.
Barium chloride is an inorganic salt with the formula BaCl₂, existing as anhydrous (white solid, 962°C melting point) or hydrated forms (dihydrate and octahydrate), produced primarily via barite reduction with carbon followed by HCl leaching or direct reaction of barium carbonate with hydrochloric acid. Its primary industrial purpose centers on sulfate precipitation in brine purification, steel case hardening, and pigment manufacturing. The dihydrate segment dominates volume due to its stability in ambient storage and broad compatibility with water treatment dosing systems. Anhydrous barium chloride commands premium positioning from electronics manufacturers requiring controlled moisture content for chemical vapor deposition precursors. Application in chemical manufacturing retains the largest value pool, while pyrotechnics represents a specialized niche with stringent particle-size specifications.
REACH registration through ECHA governs substance identity and impurity thresholds for barium chloride placed on the European market, while China's MEE enforces discharge limits on barium-containing wastewater from chlor-alkali complexes. The US EPA regulates barium compounds under the Safe Drinking Water Act, influencing water treatment procurement specifications for maximum contaminant level compliance. Stakeholders must monitor evolving battery-grade barium salt specifications as sodium-ion and solid-state chemistries probe alternative electrolyte additives.
Market Dynamics
Chlor-alkali integration in China's Shandong province is concentrating feedstock supply for barium chloride production, compressing cost structures and reshaping competitive positioning among Western and Asian suppliers.
Growth Catalysts
- REACH compliance tightening:ECHA purity specifications for technical-grade material are elevating quality standards across European industrial channels, creating demand for certified production.
- Water treatment expansion:North American utilities are scaling sulfate removal systems that specify barium chloride dihydrate for brine purification operations.
- Semiconductor etching demand:Electronics manufacturers require high-purity anhydrous grades as chemical vapor deposition precursors for advanced chip fabrication.
Market Restraints
- Barite ore concentration:Captive mining rights in China's Guizhou and Hunan provinces limit feedstock access for non-integrated producers.
- Hydrochloric acid volatility:Chlor-alkali byproduct availability fluctuates with caustic soda demand cycles, squeezing margin predictability.
- Substitute precipitation agents:Calcium chloride and synthetic zeolites compete for sulfate removal in cost-sensitive water treatment bids.
Strategic Opportunities
- Battery-grade electrolyte additives:Sodium-ion and solid-state chemistry developers are probing barium salt specifications for alternative electrolyte formulations.
- Modular bulk packaging:Moisture-resistant totes are penetrating municipal water treatment procurement, displacing traditional bagged formats.
- India's industrial expansion:BIS certification pathways for technical-grade material are opening as domestic chlor-alkali capacity scales.
Industry Challenges
- Wastewater discharge compliance:China's MEE barium limits require capital-intensive effluent treatment retrofits at chlor-alkali complexes.
- Electronic-grade certification timelines:Semiconductor customer qualification cycles extend 18-24 months for new anhydrous supply sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Chloride Market |
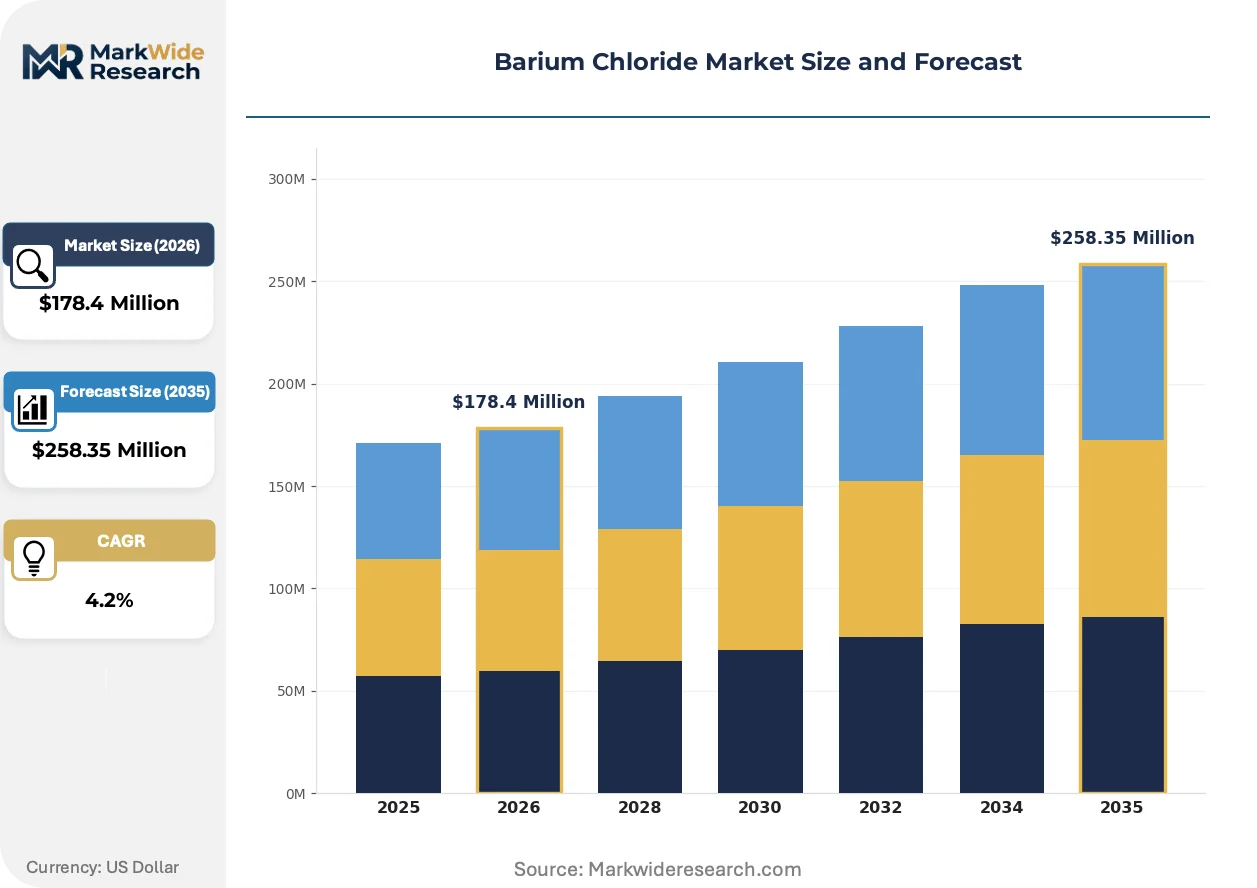
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $258.35 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Barium Chloride, Barium Chloride Dihydrate, Barium Chloride Octahydrate, Barium Chloride Flake Application: Medical Imaging, Chemical Manufacturing, Water Treatment, Pyrotechnics End User: Pharmaceuticals, Electronics, Pulp & Paper, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Chemical Products Corporation, Finoric LLC, Solvay S.A., Shandong Xinke Environmental Chemistry Co., Ltd., Jiaocheng Sanxi Chemical Co., Ltd., Nippon Chemical Industrial, Chaitanya Chemicals, Weifang Xinyuan Barium Co., Ltd., American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Chloride Market Emerging Trajectories
Barium chloride supply chains are pivoting from commodity bulk toward specification-driven segments, with packaging formats and purity grades diverging sharply by end-use vertical.
Continuous crystallization systems for dihydrate production are overtaking traditional batch processing in cost efficiency and particle-size consistency. Water treatment compounders in the US and Germany are adopting these systems to meet EPA and REACH documentation requirements. The technology is compressing working capital cycles while enabling just-in-time delivery contracts.
REACH registration through ECHA is hardening substance identity protocols and impurity thresholds for European market access. Industrial chemical distributors must now maintain batch-level traceability documentation that was previously optional. Technical-grade suppliers are responding by segregating production lines and investing in dedicated analytical laboratories.
Specification-driven procurement is fragmentizing traditional distributor relationships as end-users source directly from integrated manufacturers. Municipal water authorities and semiconductor fabs are negotiating long-term offtake agreements that bypass regional chemical distributors. This pattern is most pronounced in Germany's Ruhr industrial cluster and Texas's Permian Basin water treatment corridor.
Barium Chloride Market Segmentation
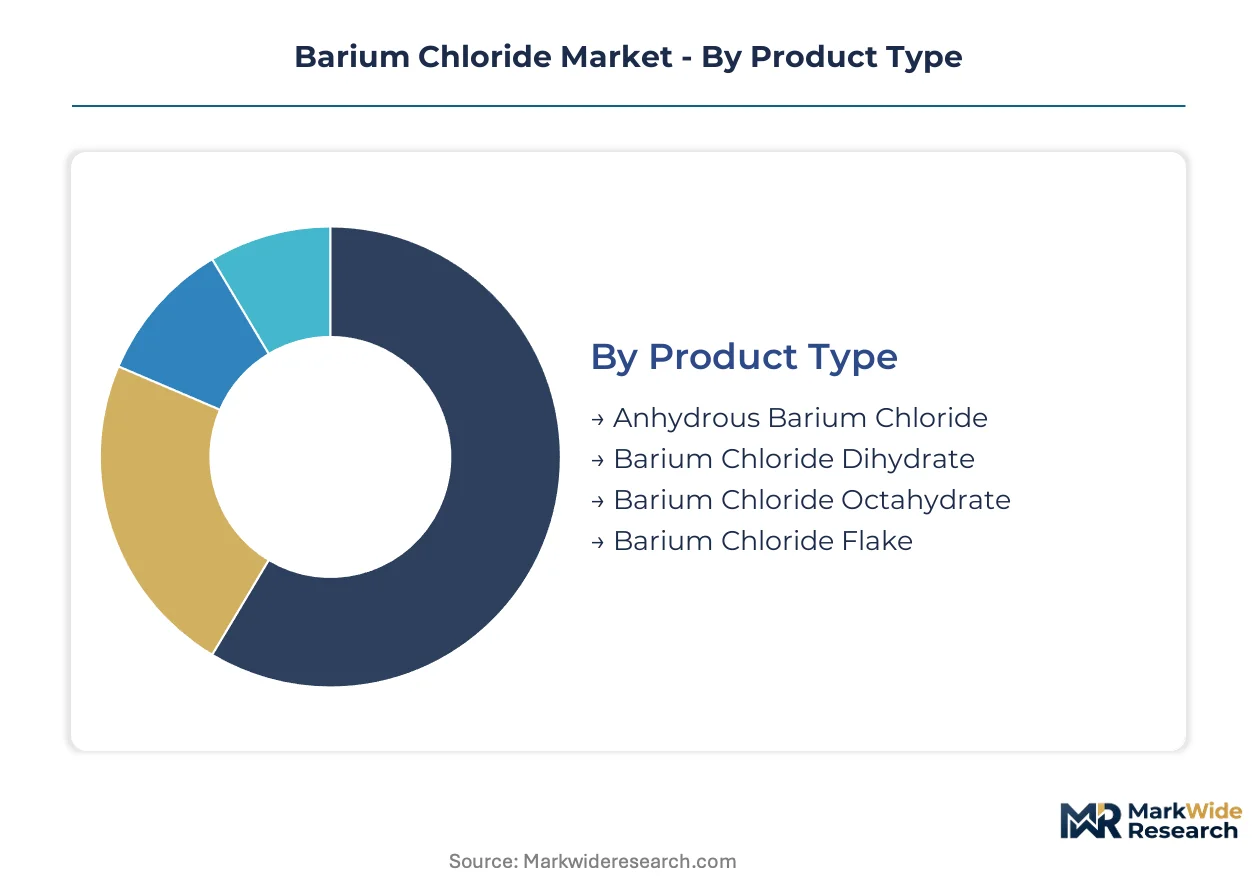
Barium chloride procurement patterns diverge sharply across product forms and end-use specifications, with water treatment utilities favoring stabilized dihydrate while electronics manufacturers demand anhydrous grades with controlled moisture content. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Buyers in this category differentiate primarily by moisture sensitivity and storage stability requirements, not by price alone.
- Barium Chloride Dihydrate:Crystalline solid containing two water molecules per barium chloride unit, stable under ambient humidity and temperature conditions. Water treatment facilities in Texas and Germany specify this grade for sulfate precipitation systems due to its predictable dissolution kinetics and compatibility with automated dosing equipment.
- Anhydrous Barium Chloride:White crystalline solid with 962°C melting point and zero water content, requiring hermetic packaging to prevent hydration. Semiconductor fabs in Japan and South Korea procure this grade as chemical vapor deposition precursors where moisture contamination would compromise thin-film deposition quality.
- Barium Chloride Octahydrate:Highly hydrated form with eight water molecules, offering lower effective barium concentration per unit weight.
- Barium Chloride Flake:Compressed or crystallized flat particles favored in pyrotechnics for controlled burn rates and specific surface area requirements.
Volume sits with dihydrate; growth tilts toward anhydrous.
Application:
Application selection tracks regulatory intensity and process criticality, with medical and semiconductor uses demanding documentation that commodity chemical channels cannot supply.
- Water Treatment:Sulfate removal from brine streams and industrial wastewater via barium sulfate precipitation. North American municipal utilities specify dihydrate grades with REACH-compliant impurity documentation for Safe Drinking Water Act compliance.
- Chemical Manufacturing:Intermediate for barium salts, pigments, and case-hardening compounds. Steel producers in India's Maharashtra state consume technical-grade material for surface hardening of machine components.
- Medical Imaging:Contrast agent precursor applications requiring pharmacopeial-grade purity and batch-level traceability.
- Pyrotechnics:Green colorant in fireworks formulations with stringent particle-size distribution specifications for burn rate control.
Revenue concentrates in chemical manufacturing; steepest expansion trajectory appears in water treatment.
End User:
End-user segmentation reflects divergence between specification-driven procurement and volume-driven commodity purchasing.
- Electronics:Semiconductor and display manufacturers requiring sub-ppm impurity limits and moisture-controlled packaging. Japanese and South Korean fabs negotiate 18-24 month qualification cycles for new anhydrous supply sources.
- Pharmaceuticals:Contrast media and API manufacturers subject to pharmacopeial monographs and FDA or EMA inspection protocols.
- Pulp & Paper:Bleaching and chemical recovery operations favoring technical-grade dihydrate with flexible delivery scheduling.
- Agriculture:Minor end-use for specific soil amendment and pesticide formulations with less stringent purity requirements.
Margin pools favor electronics; volume scales fastest in pulp and paper.
Distribution Channel:
Channel selection correlates with buyer scale and specification complexity, fragmenting traditional distributor relationships.
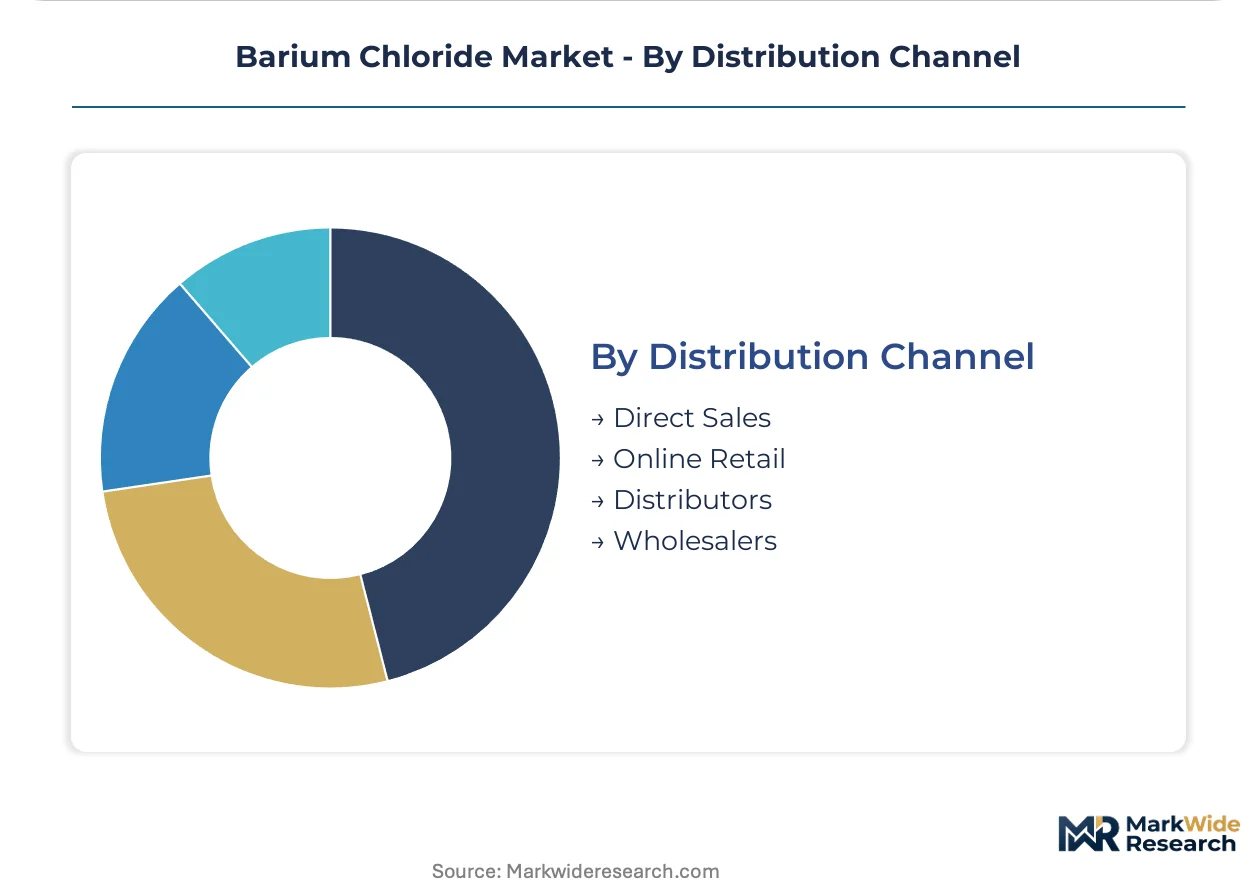
- Direct Sales:Long-term offtake agreements between integrated manufacturers and large water authorities or semiconductor fabs. Germany's Ruhr industrial cluster and Texas's Permian Basin water corridor show pronounced direct procurement patterns.
- Distributors:Regional chemical distributors serving mid-size industrial accounts with technical support and inventory buffering.
- Online Retail:E-commerce platforms penetrating small-laboratory and research-scale procurement with rapid fulfillment.
- Wholesalers:Bulk aggregators serving cost-sensitive commodity applications with minimal technical service.
Direct sales capture value; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production through chlor-alkali integration in Shandong province, while consumption disperses across water treatment utilities in the United States, steel hardening operations in India, and semiconductor fabs in Japan and South Korea.
United States
Texas water treatment corridors and Pennsylvania steel mills drive dihydrate consumption for sulfate precipitation and case hardening. EPA Safe Drinking Water Act specifications shape procurement documentation requirements for municipal utilities. The Permian Basin water corridor shows pronounced direct procurement patterns bypassing traditional distributors.
China
Shandong province anchors production through captive barite mining and hydrochloric acid recovery from chlor-alkali operations. MEE wastewater discharge limits force capital-intensive effluent treatment retrofits at manufacturing complexes. Guizhou and Hunan provinces concentrate barite ore reserves, constraining feedstock access for non-integrated producers.
Germany
Ruhr industrial cluster chemical manufacturers specify REACH-compliant technical grades for pigment and salt intermediate production. ECHA substance identity protocols harden batch-level traceability requirements that distributors must now maintain. North Rhine-Westphalia's steel sector consumes material for surface hardening of precision components.
Japan
Osaka and Nagoya semiconductor fabs procure anhydrous grades as chemical vapor deposition precursors for advanced chip fabrication. METI industrial standards govern impurity thresholds for electronics-grade material. Kyushu-based display manufacturers negotiate 18-24 month qualification cycles for new supply sources.
India
Maharashtra steel producers and Gujarat chlor-alkali complexes expand technical-grade consumption for case hardening and captive chemical synthesis. BIS certification pathways are opening as domestic production capacity scales. Mumbai-Pune industrial corridor distributors serve mid-size manufacturing accounts with inventory buffering.
Barium Chloride Market Vendor Landscape
The competitive structure tilts toward integrated manufacturers with captive feedstock control. Chlor-alkali integration in China's Shandong province compresses cost structures and reshapes positioning among Western and Asian suppliers. Three archetypes dominate: integrated chemical conglomerates with mining-to-manufacturing control, specialty inorganic salt producers serving specification-driven verticals, and regional distributors providing technical support and logistics buffering. Capacity expansion and direct long-term offtake agreements represent the dominant competitive moves.
Within the integrated tier, Solvay S.A. and Shandong Xinke Environmental Chemistry Co., Ltd. exemplify backward integration into chlor-alkali networks and barite mining. American Elements occupies a position among specialty producers targeting high-purity electronic-grade specifications. These three anchors illustrate how feedstock control separates cost-competitive commodity supply from premium specification-driven segments.
| Leading Market Players |
|---|
| Chemical Products Corporation |
| Finoric LLC |
| Solvay S.A. |
| Shandong Xinke Environmental Chemistry Co., Ltd. |
| Jiaocheng Sanxi Chemical Co., Ltd. |
| Nippon Chemical Industrial |
| Chaitanya Chemicals |
| Weifang Xinyuan Barium Co., Ltd. |
| American Elements |
| Others |
Supply Flow & Price Mechanics
Barite ore indices in Guizhou and Hunan provinces cascade through chlor-alkali integrated supply chains, compressing dihydrate pricing tiers while elevating premiums for REACH-certified anhydrous grades destined for semiconductor fabs.
Pricing Analysis
Cost-down pressure on technical-grade dihydrate accelerates because Shandong's captive chlor-alkali producers leverage backward integration into barite mining. Three-tier pricing structure across electronic-grade, technical-grade, and commodity-grade levels separates semiconductor precursors from water treatment chemicals from pyrotechnics inputs. REACH compliance documentation and ECHA batch traceability drive premium capture in European channels. Municipal utilities in Texas and Germany exhibit highest price sensitivity, while Japanese semiconductor fabs absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for moisture-sensitive anhydrous grades. Production concentrates in China, Germany, and the United States, with Shandong province commanding upstream control over barite feedstock and hydrochloric acid recovery. Supply chains draw from barite ore, chlor-alkali byproduct acid, and specialized packaging materials. Single-source vulnerability concentrates in Guizhou barite mining concessions held by integrated conglomerates. Distribution runs through direct long-term offtake agreements for large water authorities and semiconductor fabs, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into barite mining and captive chlor-alkali networks has become the decisive lever separating cost-competitive commodity supply from premium specification-driven segments.
For Market Incumbents: Deploy dedicated analytical laboratories to segregate REACH-compliant production lines from commodity grades. Solvay S.A. and Shandong Xinke Environmental Chemistry Co., Ltd. exemplify how upstream control over barite reserves defends margin position against hydrochloric acid volatility and substitute precipitation agents like calcium chloride. Capacity additions in India's Gujarat chlor-alkali corridor preempt emerging BIS certification demand. For New Entrants and Emerging Players: Begin with modular bulk packaging of dihydrate in moisture-resistant totes for North American municipal water treatment procurement. India's Maharashtra steel hardening sector offers penetrable white-space as domestic chlor-alkali capacity scales. A technical service partnership with regional distributors in the Mumbai-Pune industrial corridor provides faster qualification than direct semiconductor fab engagement. For Investors and Strategic Acquirers: The window for entry favors specialty inorganic salt producers with existing pharmacopeial-grade certification infrastructure. Long-term viability hinges on positioning for battery-grade electrolyte additive specifications as sodium-ion chemistry developers probe alternative formulations. Watch for MEE wastewater discharge compliance retrofits as capital intensity signals at Chinese manufacturing complexes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive ore supply from Guizhou reserves insulates Shandong producers from feedstock access constraints. |
| REACH Certification Investment | ECHA batch-level traceability documentation opens premium European industrial channels to compliant suppliers. |
| Modular Bulk Packaging Scale-Up | Moisture-resistant totes penetrate Texas and Germany municipal procurement, displacing traditional bagged formats. |
| Electronic-Grade Qualification Cycles | 18-24 month Japanese and South Korean fab approval timelines lock in anhydrous supply relationships. |
| Battery-Grade Electrolyte Development | Sodium-ion and solid-state chemistry developers probe barium salt specifications for alternative formulations. |
Methodological Framework
Independent corroboration across chlor-alkali plant managers, water treatment procurement leads, semiconductor chemical buyers, and specialty chemical distributors underwrites the qualitative findings. Primary interviews with downstream OEMs and distribution channel partners combined with secondary validation from customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings established demand-side patterns. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume estimates.
Rate-of-change decomposition across grade tier, end-use industry, packaging format, and regional production hub shaped the analytical framework. CAGRs derived from segment-level growth trajectories and elasticity assumptions across the analysis window incorporated barite ore price volatility, REACH compliance cost pass-through, and semiconductor capital expenditure cycles as industry-specific forecast inputs.
Underlying measurement precision varies by segment; electronic-grade and pharmaceutical-grade categories carry tighter precision than commodity technical-grade due to qualification documentation density. Forecasts reflect documented assumptions regarding chlor-alkali integration rates, MEE enforcement intensity, and battery chemistry substitution timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Titanium Dioxide Market