
 Diethylene Glycol (DEG) Market | 2026-2036
Diethylene Glycol (DEG) Market Size, Share, and Industry Trends Forecast 2026-2036
Diethylene Glycol (DEG) Market Analysis
Propylene glycol is repositioning DEG economics in personal care and food-grade applications where toxicity sensitivity limits DEG penetration. BASF SE leverages integrated ethylene oxide capabilities to sustain cost leadership across European supply chains. SABIC anchors Middle Eastern export volumes through advantaged feedstock access at Jubail industrial complexes. Dow competes on specification breadth, offering USP-grade and industrial-grade portfolios that span pharmaceutical and antifreeze end uses.
Diethylene glycol is a hygroscopic organic compound produced through the controlled hydration of ethylene oxide, yielding a colorless liquid with a boiling point near 244 degrees Celsius and molecular formula C4H10O3. It serves primarily as a chemical intermediate for unsaturated polyester resins, polyurethane polyols, and morpholine derivatives, while functioning as a solvent, humectant, and plasticizer across industrial formulations. Industrial-grade DEG dominates volume flows into antifreeze and polyester resin manufacturing, where margin pools remain deepest due to scale-intensive procurement by automotive and construction material suppliers. USP-grade and cosmetic-grade categories command premium positioning in pharmaceutical and personal care applications, with humectant demand in skincare formulations outpacing solvent growth in mature textile processing segments.
The EPA regulates DEG content in consumer products through toxicity thresholds, while REACH mandates registration and hazard communication for European chemical imports. China's SAMR enforces GB standards on diol purity in food-contact and cosmetic applications, directly conditioning market access for imported material. India's BIS certification requirements for industrial chemicals are tightening specification compliance burdens for regional distributors. Stakeholders must monitor evolving purity mandates and carbon-intensity disclosures across these jurisdictions to anticipate specification premiums and supply qualification barriers.
Market Dynamics
Polyester resin manufacturers across Asia-Pacific are expanding DEG offtake as ethylene glycol co-feedstock, while REACH compliance in Europe and China's dual carbon goals tighten purity specifications and energy intensity benchmarks simultaneously.
Growth Catalysts
- Dual carbon policy framework:China's SAMR enforcement of GB standards on diol purity is accelerating specification upgrades across domestic production bases, creating qualified supply shortages that premium-grade importers exploit.
- Polyester fiber capacity expansion:Textile processors in India are scaling operations under PLI scheme incentives, concentrating DEG demand in polyester resin intermediate manufacturing.
- Antifreeze formulation stability:Industrial-grade DEG maintains cost advantage in automotive coolant applications where propylene glycol substitution remains price-prohibitive for fleet operators.
Market Restraints
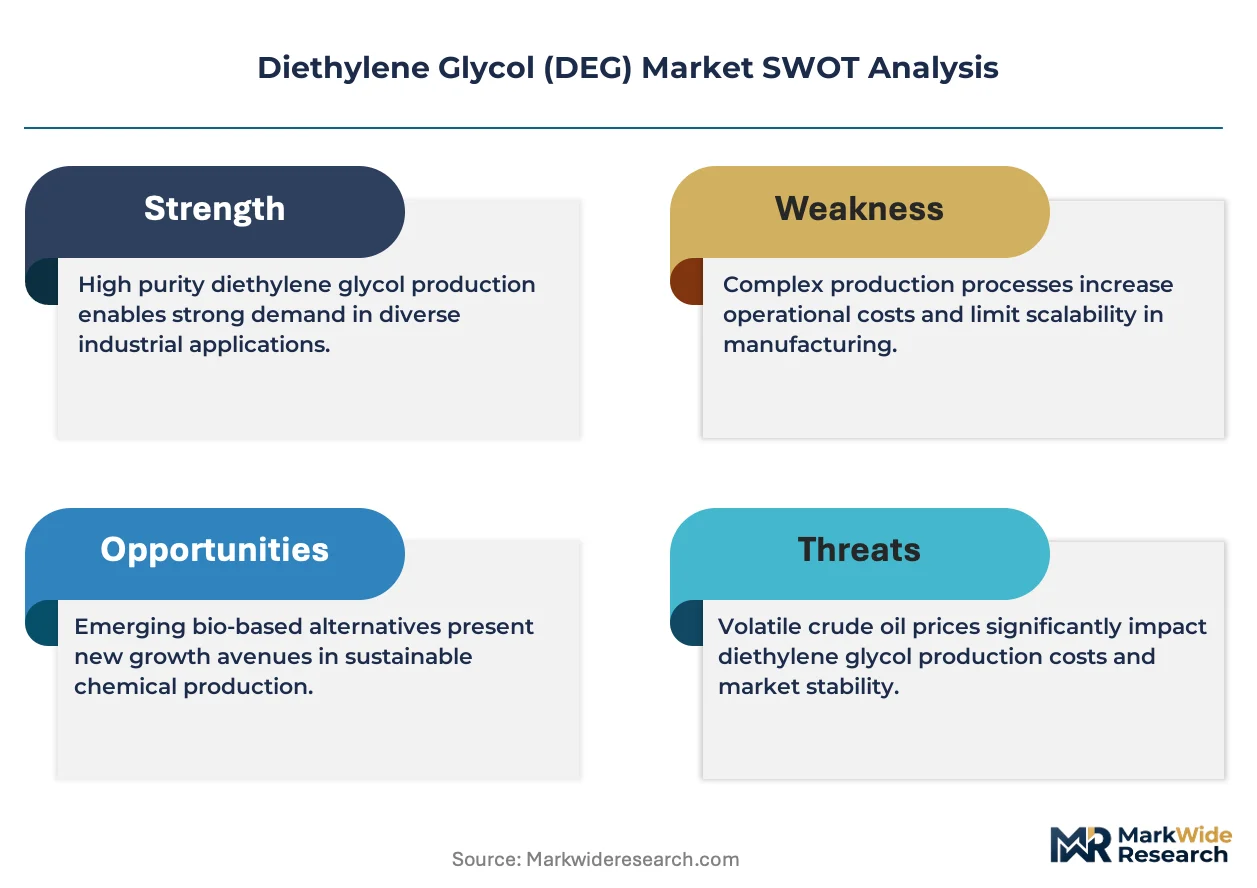
- Ethylene oxide feedstock volatility:Cracker operating rates and naphtha price swings transmit directly to DEG margin compression, particularly for non-integrated producers lacking captive ethylene supply.
- Toxicity threshold enforcement:EPA content limits in consumer products and ECHA hazard communication mandates create formulation reformulation costs that deter small-volume personal care entrants.
- Propylene glycol substitution:Food-grade and pharmaceutical humectant applications face displacement where toxicity sensitivity justifies higher input costs for USP-grade alternatives.
Strategic Opportunities
- Carbon intensity disclosure mandates:EU CSRD requirements for scope 3 chemical sourcing create first-mover advantage for producers with verified low-carbon ethylene oxide pathways and documented supply chain emissions.
- Biobased feedstock convergence:Ethanol-to-ethylene oxide process innovations are modularizing with conventional steam cracker routes, enabling renewable-content DEG positioning for brand-sensitive cosmetic formulators.
- Specialty morpholine derivatives:Downstream amination chemistry for gas treatment and rubber processing represents underpenetrated application expansion beyond commodity resin and solvent markets.
Industry Challenges
- Cross-jurisdictional certification timelines:Simultaneous BIS, REACH, and SAMR registration requirements extend product qualification cycles, freezing working capital in multi-standard compliance documentation.
- Legacy antifreeze specification lock-in:Automotive OEM coolant approval protocols resist formulation changes, delaying DEG displacement even where propylene glycol performance parity exists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethylene Glycol (DEG) Market |
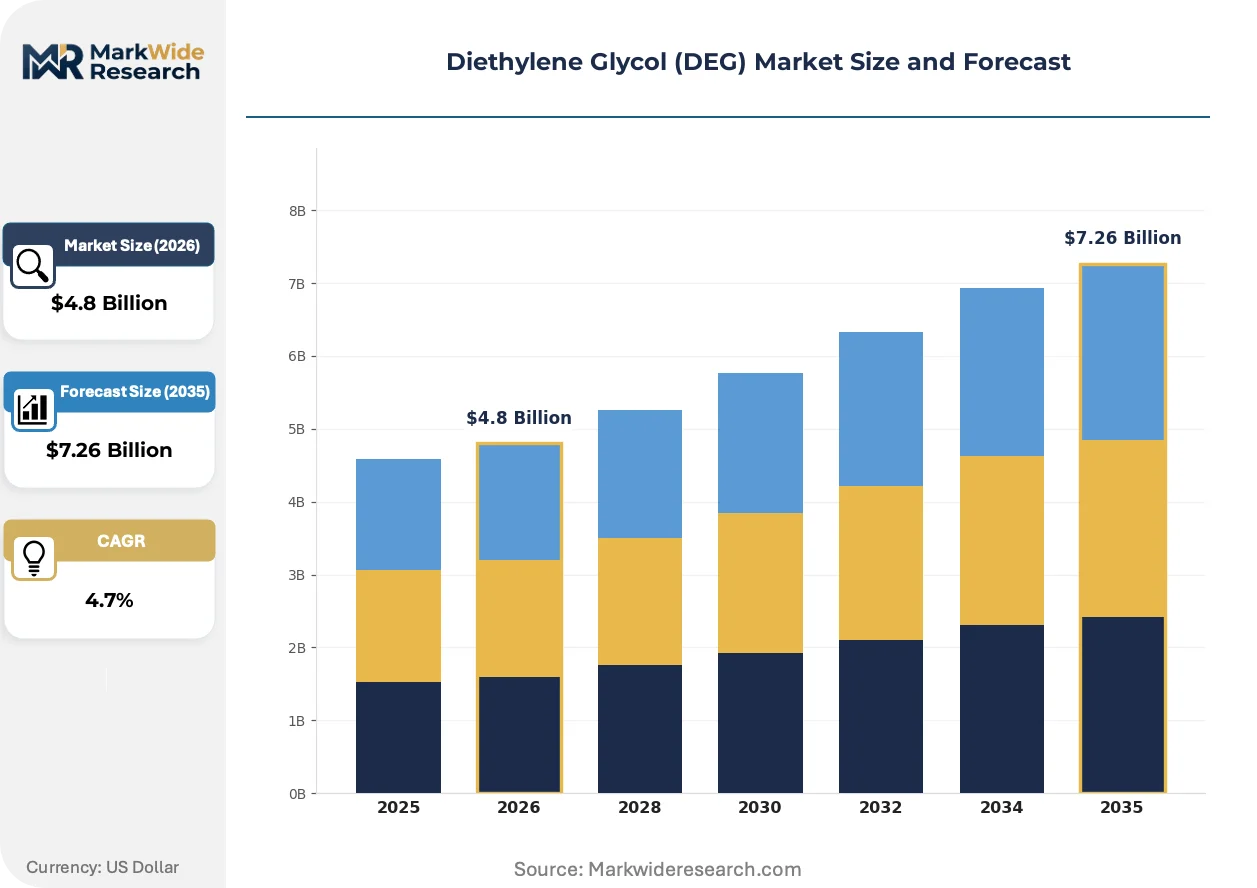
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, USP Grade, Cosmetic Grade, Food Grade Application: Antifreeze, Plasticizer, Solvent, Humectant End User: Automotive, Textile, Personal Care, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Reliance Industries Limited, SABIC, BASF SE, Shell, Mitsubishi Chemical Corporation, LyondellBasell, Dow, Huntsman International LLC, GC Glycol Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethylene Glycol (DEG) Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are reshaping how DEG producers compete on specification breadth rather than volume scale alone.
Membrane separation technology for ethylene oxide purification is modularizing downstream DEG distillation configurations. Specialty chemical producers in Germany and Japan are adopting skid-mounted units to isolate high-purity fractions for cosmetic-grade certification. This modularization compresses capital requirements for multi-grade portfolios and enables rapid specification pivots without full plant redesign.
REACH registration dossier updates under ECHA's substance evaluation program are forcing retroactive toxicological data submissions for imported DEG volumes. European distributors now demand extended safety data sheets from Middle Eastern and Asian suppliers as condition of contract renewal. The industrial-grade segment bears the heaviest documentation burden, with some traders exiting rather than funding compliance archaeology for legacy supply relationships.
Direct procurement contracts between polyester resin manufacturers and ethylene oxide producers are displacing merchant DEG spot purchases in India and China. Large textile processors negotiate captive offtake agreements that guarantee specification consistency and volume allocation priority. This concentration is most visible in Gujarat and Zhejiang industrial clusters, where integrated petrochemical complexes internalize intermediate supply chains.
Diethylene Glycol (DEG) Market Segmentation
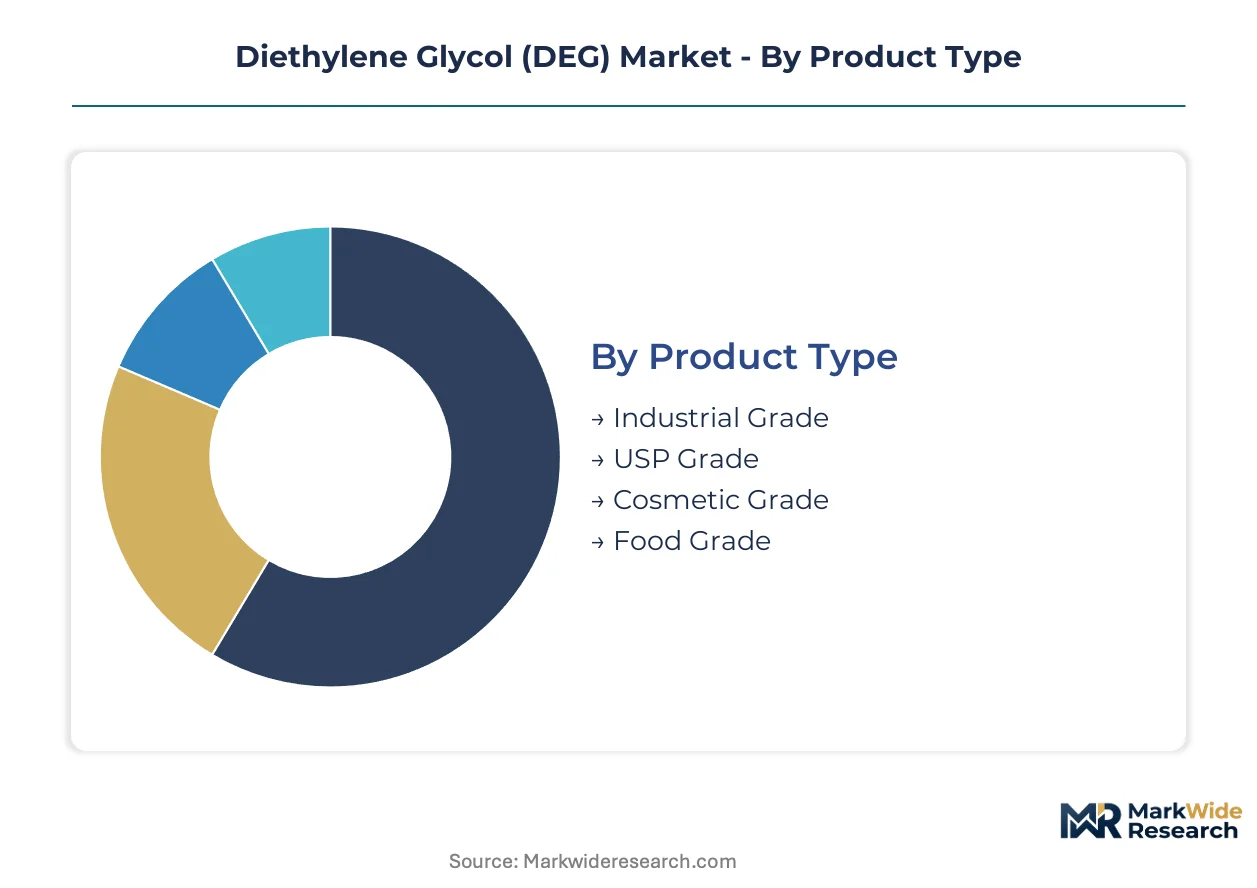
DEG procurement decisions hinge on specification purity, regulatory certification burden, and end-use toxicity thresholds. Buyers segment supply sources by grade tier and application risk profile, with automotive and pharmaceutical sectors imposing divergent qualification requirements.
Product Type:
Specification tier determines qualification pathway, with purity thresholds separating commodity volume from premium-margin segments.
- Industrial Grade:Colorless liquid with 99% minimum diol content serves unsaturated polyester resin manufacturing and automotive coolant formulations. Demand concentrates in India and China where textile processors and automotive suppliers prioritize cost efficiency over certification overhead.
- USP Grade:Meets United States Pharmacopeia monograph standards for residual ethylene oxide and heavy metal limits, enabling pharmaceutical solvent and excipient applications. FDA enforcement of toxicity thresholds in drug manufacturing drives specification compliance investments among importers.
- Cosmetic Grade:Ultra-low impurity profile satisfies humectant requirements in skincare formulations.
- Food Grade:Complies with FDA indirect food additive regulations for packaging and processing equipment applications.
Volume sits with Industrial Grade; growth tilts toward USP Grade.
Application:
Functional role in formulation chemistry determines margin capture, with intermediate applications outpacing commodity solvent uses.
- Antifreeze:Industrial-grade DEG depresses freezing points in automotive coolant and aircraft de-icing formulations. Fleet operators in North America and Europe resist propylene glycol substitution due to price premiums, preserving DEG's cost advantage in heavy-duty vehicle segments.
- Humectant:Hygroscopic properties stabilize moisture content in pharmaceutical tablets and cosmetic creams. Personal care formulators in Western Europe specify cosmetic-grade material to satisfy ECHA hazard communication mandates.
- Plasticizer:Softens polymeric matrices in adhesives and coatings.
- Solvent:Dissolves resins and dyes in textile printing and ink formulations.
Antifreeze commands current volume; humectant applications expand most quickly.
End User:
Industry-specific regulatory exposure shapes procurement sophistication, with pharmaceutical and personal care buyers demanding documentation depth unavailable to automotive purchasers.
- Automotive:Coolant blenders and OEM service chemical suppliers specify industrial-grade DEG for aftermarket and factory-fill antifreeze. EPA content limits in consumer-facing products constrain formulation flexibility, locking in established supply relationships.
- Pharmaceuticals:Drug manufacturers require USP-grade material with validated supply chain documentation. CDSCO registration requirements in India extend qualification timelines, favoring producers with established regulatory dossiers.
- Textile:Polyester fiber producers consume DEG as ethylene glycol co-feedstock.
- Personal Care:Cosmetic formulators specify low-toxicity humectant grades.
Textile processing absorbs the largest share; pharmaceutical qualification is climbing the fastest.
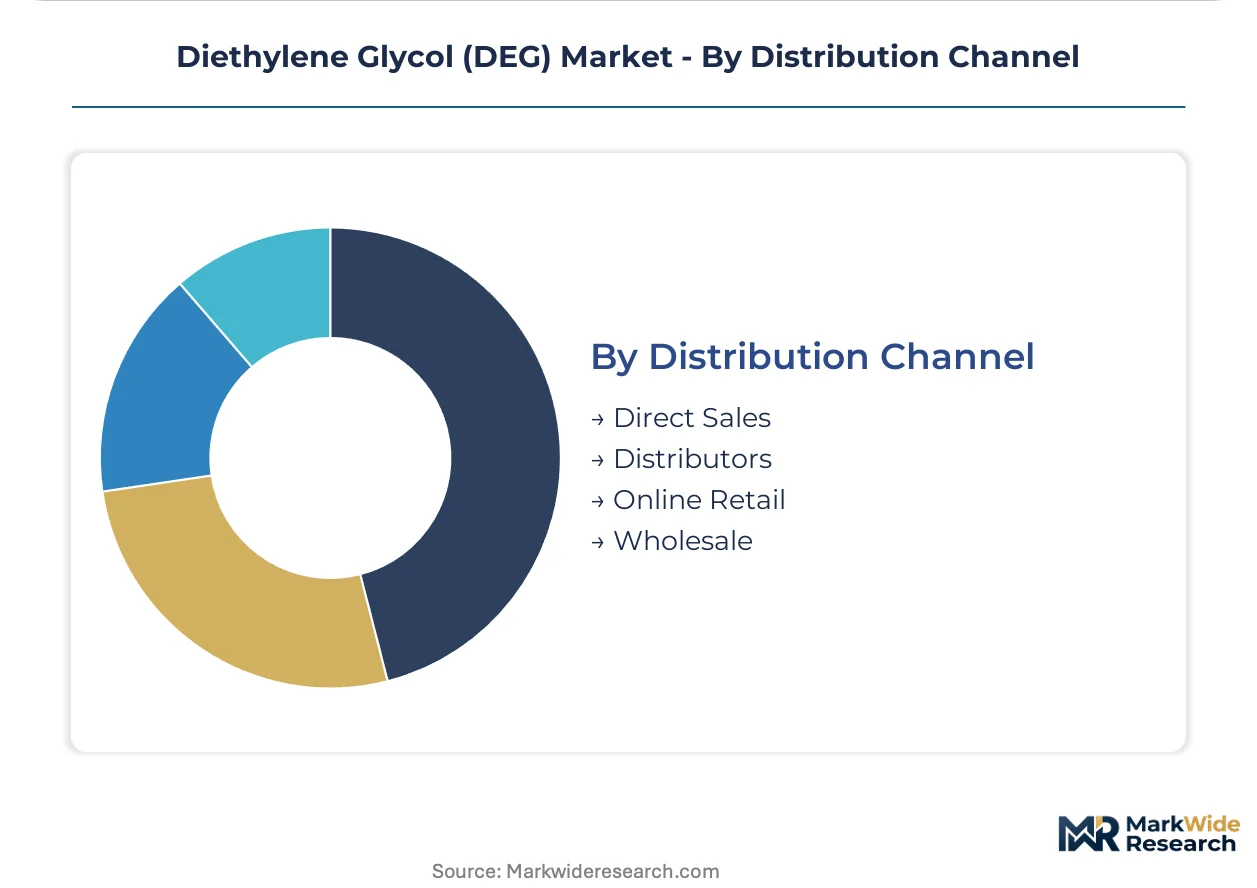
Distribution Channel:
Channel selection reflects purchase scale and specification complexity, with direct procurement displacing intermediaries in high-volume segments.
- Direct Sales:Integrated petrochemical producers negotiate captive offtake agreements with polyester resin manufacturers. Reliance Industries and comparable processors in Gujarat industrial clusters internalize intermediate supply through direct contracts.
- Distributors:Regional chemical traders manage REACH registration documentation and BIS certification for imported volumes. European distributors now demand extended safety data sheets from Middle Eastern suppliers as contract renewal conditions.
- Wholesale:Aggregates spot purchases for small-volume industrial buyers.
- Online Retail:Serves research and specialty chemical procurement at laboratory scale.
Direct Sales dominates volume flows; Distributor networks gain share in compliance-intensive geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates DEG offtake growth as polyester fiber processors scale manufacturing clusters. China's dual carbon mandates reshape purity specifications across domestic production bases. Regulatory divergence between EPA enforcement in the United States, REACH in Europe, and BIS certification in India fragments qualification pathways for multinational suppliers.
China
SAMR enforcement of GB standards on diol purity accelerates specification upgrades at domestic ethylene oxide plants. The dual carbon policy framework tightens energy intensity benchmarks for chemical producers in Jiangsu and Zhejiang provinces. Yangtze River Delta industrial clusters internalize DEG supply through direct procurement contracts with integrated petrochemical complexes.
India
Textile processors in Gujarat and Maharashtra expand polyester resin operations under PLI scheme incentives. CDSCO registration requirements extend pharmaceutical-grade DEG qualification timelines for imported material. Reliance Industries anchors captive consumption at its Jamnagar complex, concentrating demand in the western industrial corridor.
Germany
BASF SE leverages integrated ethylene oxide capabilities to sustain cost leadership across European supply chains. ECHA substance evaluation programs force retroactive toxicological data submissions for REACH-registered DEG volumes. Ludwigshafen and Marl chemical parks house membrane separation units that isolate high-purity fractions for cosmetic-grade certification.
United States
EPA toxicity thresholds in consumer products constrain formulation flexibility for antifreeze blenders and personal care manufacturers. Dow competes on specification breadth with USP-grade and industrial-grade portfolios spanning pharmaceutical and coolant applications. Gulf Coast petrochemical corridors maintain merchant DEG availability despite direct procurement trends in Asian markets.
Saudi Arabia
SABIC anchors Middle Eastern export volumes through advantaged feedstock access at Jubail industrial complexes. SAMR-equivalent import standards in destination markets extend documentation burdens for regional traders. Eastern Province production bases supply industrial-grade material to polyester resin manufacturers in India and Southeast Asia.
Diethylene Glycol (DEG) Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated petrochemical producers scale ethylene oxide derivatives output. The vendor base stratifies into three tiers: global integrated majors with captive feedstock, regional specialists serving compliance-intensive geographies, and merchant traders managing certification documentation for imported volumes. Strategic archetypes include backward-integrated resin manufacturers internalizing intermediate supply, and distributors building regulatory dossier capabilities as competitive moats. Portfolio diversification and geographic expansion represent the two dominant competitive moves, with producers adding cosmetic-grade and USP-grade fractions to industrial portfolios while extending sales presence into India's qualification-intensive market.
Among integrated petrochemical majors, BASF SE, SABIC, and Dow exemplify the scale-driven archetype. BASF SE occupies a position within European supply chains where membrane purification capabilities enable multi-grade positioning. SABIC anchors export volumes from Middle Eastern production bases with feedstock cost structures unavailable to European and Asian competitors. Dow sits within the North American market with specification breadth that spans industrial coolant applications through pharmaceutical-grade certification. Reliance Industries represents the backward-integrated model, internalizing DEG consumption within polyester fiber manufacturing operations that concentrate demand in the Indian market.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| SABIC |
| BASF SE |
| Shell |
| Mitsubishi Chemical Corporation |
| LyondellBasell |
| Dow |
| Huntsman International LLC |
| GC Glycol Company |
| Others |
Supply Flow & Price Mechanics
Polyester resin manufacturers in Gujarat and Zhejiang industrial clusters negotiate direct procurement contracts that compress spot market liquidity and anchor pricing power with integrated ethylene oxide producers. REACH registration dossiers and BIS certification requirements impose documentation premiums that widen spreads between qualified and unqualified supply tiers.
Pricing Analysis
Volume concentrates in industrial-grade material where naphtha-linked ethylene oxide feedstock costs transmit directly to contract negotiations, while USP-grade and cosmetic-grade fractions capture margin premiums through purity certification investments. Price differentiation rests on GB standard compliance for China-bound volumes and REACH dossier completeness for European qualification. Cost compression in the industrial tier intensifies as Reliance Industries and comparable processors internalize captive supply. Automotive coolant blenders exhibit highest price sensitivity due to fleet operator procurement benchmarks, whereas pharmaceutical formulators absorb premium tier pricing to satisfy FDA toxicity thresholds.
Supply Chain Analysis
Dual-sourcing mandates from polyester fiber processors in India and China require simultaneous qualification of Middle Eastern and domestic suppliers, extending vendor onboarding timelines. Supply concentrates in Saudi Arabia, Germany, and China where integrated petrochemical complexes control ethylene oxide derivative output. Raw material dependencies center on naphtha cracker yields, ethylene oxide purification catalysts, and membrane separation modules for high-purity fractions. Single-source vulnerability persists in specialty cosmetic-grade certification where German and Japanese producers dominate membrane technology. Distribution runs through direct sales contracts for high-volume polyester resin offtake, with distributor networks managing REACH and BIS documentation for fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs function as a structural barrier-to-entry moat, forcing retroactive toxicological data investments that exclude merchant traders lacking regulatory dossier capabilities.
For Market Incumbents: Hedge feedstock exposure through backward integration into ethylene oxide production or long-term naphtha supply agreements that dampen margin volatility from cracker operating rate swings. Deepen cosmetic-grade and USP-grade certification portfolios to capture specification premiums as propylene glycol substitution threatens industrial-grade humectant applications. Prioritize carbon intensity disclosure investments ahead of EU CSRD scope 3 mandates to secure first-mover positioning in brand-sensitive cosmetic supply chains. For New Entrants and Emerging Players: Enter via specialty morpholine derivatives for gas treatment and rubber processing, an underpenetrated application segment beyond commodity resin and solvent markets where incumbent capacity concentrates. Target Indian pharmaceutical-grade demand where CDSCO registration timelines favor producers with established regulatory dossiers over merchant importers. Deploy biobased feedstock positioning for cosmetic formulators seeking renewable-content certification, leveraging ethanol-to-ethylene oxide process innovations that modularize with conventional routes. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with REACH and BIS documentation capabilities in compliance-intensive geographies where qualification timelines freeze working capital. Long-term viability hinges on supply chain emissions transparency and verified low-carbon ethylene oxide pathways. Monitor ECHA substance evaluation program announcements as inflection indicators for retroactive compliance cost burdens that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply insulates Reliance Industries from naphtha price volatility in polyester resin manufacturing. |
| Green Manufacturing Transition | Ethanol-to-ethylene oxide pathways enable renewable-content DEG positioning for ECHA-compliant cosmetic formulators. |
| Long-term Supply Agreement | Direct procurement contracts between SABIC and Gujarat textile processors guarantee volume allocation priority. |
| Capacity Expansion | Membrane separation unit additions at Ludwigshafen and Marl chemical parks isolate high-purity cosmetic-grade fractions. |
| Joint Venture | Partnerships with Indian distributors accelerate BIS certification timelines for imported pharmaceutical-grade material. |
Methodological Framework
Document review covered customs and trade flow databases, SEC 10-K filings from integrated petrochemical majors, and ECHA REACH registration dossiers, complemented by interviews with plant managers at ethylene oxide derivative facilities, procurement leads at polyester resin manufacturers, distribution channel partners managing BIS certification, and technical R&D directors overseeing membrane separation process development. Secondary validation drew from ACC and Cefic industry reports, SAMR GB standard publications, and CDSCO pharmaceutical registration guidelines. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from production facility disclosures.
Cross-referencing historical price series against expert panel input on feedstock cost transmission and regulatory compliance premiums shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include specification grade tier, end-use industry application, regional production hub concentration, and certification burden intensity. CAGRs were derived from trend extrapolation of ethylene oxide derivative demand and substitution elasticity estimates for propylene glycol displacement scenarios. Industry-specific forecast inputs encompass PLI scheme incentive uptake in Indian textile processing and dual carbon policy enforcement timelines in Chinese chemical manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under naphtha price volatility spikes or accelerated ECHA substance evaluation mandates. Model outputs reflect assumptions on cracker operating rates, REACH registration renewal timelines, and SAMR enforcement intensity. A model refresh is warranted upon material change in China's dual carbon policy implementation or EU CSRD scope 3 disclosure requirements for chemical sourcing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Glycidol Market
Solvents
Benzyl Alcohol Market
Solvents
Ethyl Pyruvate Market
Solvents
North America Acetonitrile Market
Solvents
Oxygenated Solvents Market
Solvents
Chloroacetonitrile Market
Solvents
Monochlorobenzene Market
Solvents
Methyl Formate Market
Solvents
Reactive Diluents Market
Solvents
Nitroglycerin Market
Solvents
Japan Acetonitrile Market
Solvents
Phenol Derivatives Market
Solvents
Diethyl Ether Market
Solvents
United States Acetonitrile Market
Solvents
Europe Acetonitrile Market
Solvents
N-Hexane Market