
 Ethylene Dichloride Market | 2026-2036
Ethylene Dichloride Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Dichloride Market Intelligence
The direct sales channel for bulk chemical feedstocks is fragmenting as regional buyers and smaller specialty chemical makers seek more flexible supply contracts. Occidental Petroleum Corporation leverages its substantial production capacity to serve major vinyl chloride monomer (VCM) producers globally. Westlake Chemical Corporation sustains its market position through deeply integrated operations covering the entire vinyls production chain. In contrast, Shin-Etsu Chemical Co., Ltd. differentiates by offering high-purity grades for niche solvent and pharmaceutical intermediate applications.
Ethylene dichloride, a chlorinated hydrocarbon with the formula C2H4Cl2, is a colorless liquid produced via the direct chlorination or oxychlorination of ethylene. Its main industrial purpose is to act as a chemical intermediate in manufacturing vinyl chloride monomer (VCM), the precursor to polyvinyl chloride (PVC). The chemical feedstock application for VCM synthesis represents the dominant market segment by volume. Demand from the plastics end-user sector, particularly for applications in construction and packaging, defines overall market trajectory.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the EU's ECHA under REACH impose strict controls on the handling, transportation, and emission of ethylene dichloride. These rules directly influence production plant designs and ongoing operational protocols, adding to compliance costs for manufacturers. For market participants, the critical decision revolves around investing in advanced, lower-emission production technologies versus managing the operational and reputational risks of older, less efficient assets.
Market Dynamics
The primary structural force is the direct conflict between sustained demand for polyvinyl chloride from the global construction sector and intensifying environmental regulations governing chlorinated hydrocarbon production, particularly from bodies like the EPA and ECHA.
Growth Catalysts
- Urbanization in Developing Economies:Large-scale infrastructure and housing projects, especially in China and India, drive consistent volume demand for PVC products like pipes and window profiles, thereby securing baseline consumption of ethylene dichloride.
- Feedstock for VCM Synthesis:The chemical's role as the indispensable precursor for vinyl chloride monomer production links its market directly to the health of the vast global plastics industry, specifically the PVC segment.
- Process Technology Advancement:Continuous improvements in direct chlorination and oxychlorination processes increase production yields and reduce energy consumption, enhancing the cost-competitiveness of ethylene dichloride.
Market Restraints
- Input Price Volatility:Market stability is constrained by fluctuating prices of primary raw materials, namely ethylene derived from crude oil or natural gas and chlorine from the chlor-alkali process.
- Stringent Environmental Regulations:Rules from the US EPA and the EU's ECHA under REACH impose significant compliance costs for emission control and waste disposal, impacting operational margins.
- Logistical and Safety Risks:The hazardous nature of ethylene dichloride necessitates specialized handling, storage, and transportation infrastructure, adding complexity and cost to the supply chain and carrying significant reputational risk.
Strategic Opportunities
- High-Purity Solvent Applications:Development of ultra-pure grades opens new, higher-margin markets for use as a specialty solvent or as an intermediate in the synthesis of pharmaceutical and agrochemical compounds.
- Growth in Southeast Asian Markets:Expanding construction and manufacturing sectors in countries like Vietnam and Indonesia present underpenetrated markets for PVC and, by extension, ethylene dichloride.
- Carbon Capture Integration:Investing in carbon capture and utilization technologies at production sites offers a pathway to create lower-carbon-footprint ethylene dichloride, appealing to environmentally conscious downstream customers.
Industry Challenges
- Capital-Intensive Infrastructure:The high capital expenditure required to construct new world-scale production plants that meet modern environmental standards, or to retrofit older facilities, presents a significant barrier to entry and expansion.
- Complex Permitting Processes:Navigating the lengthy and intricate permitting processes for new chemical plants under authorities like the MEE in China or the EPA in the US can delay projects and increase costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Dichloride Market |
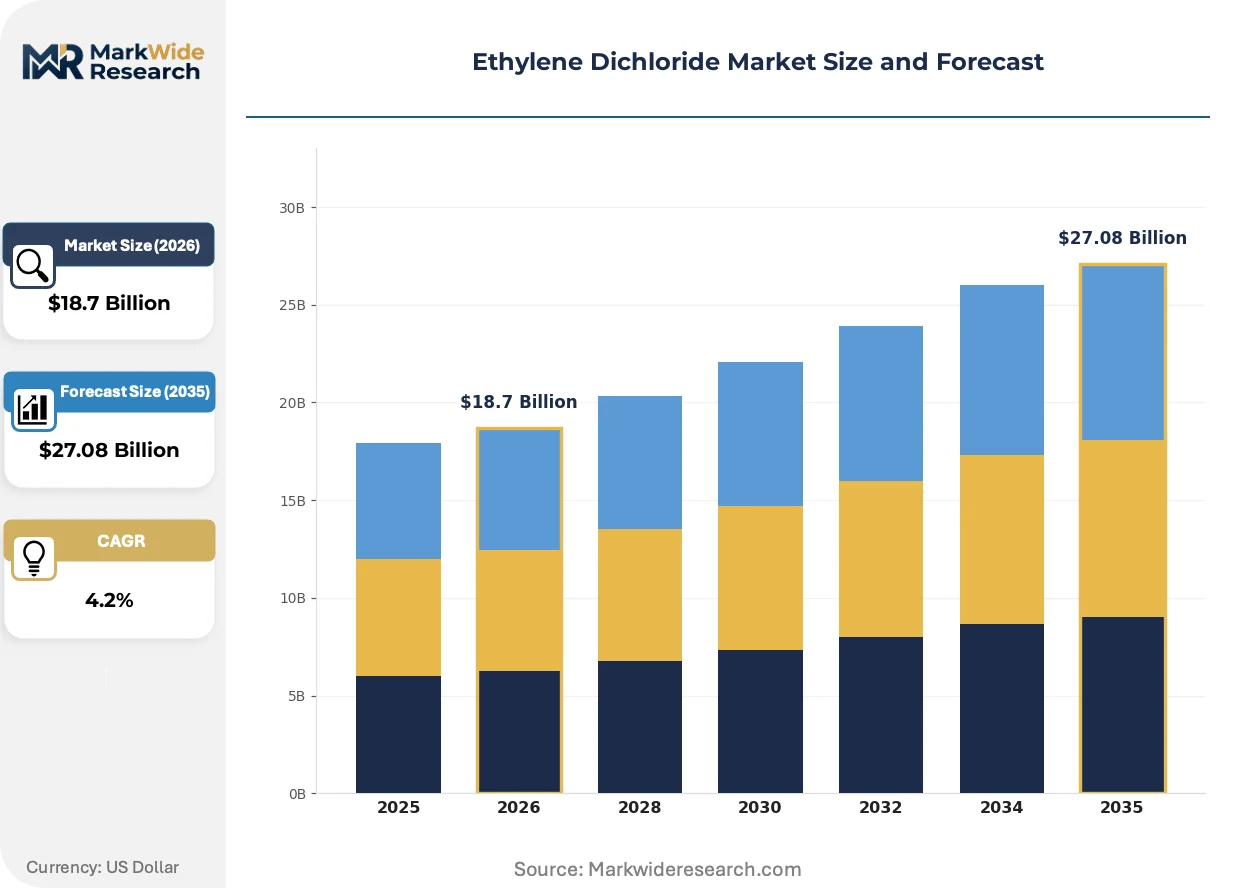
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Vapor, Solution Application: Solvent, Intermediate, Additive, Chemical Feedstock End User: Chemical Industry, Pharmaceuticals, Agriculture, Plastics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Westlake Chemical Corporation, Saudi Basic Industries Corporation, Occidental Petroleum Corporation, Shin-Etsu Chemical Co., Ltd., Formosa Plastics Corporation, INEOS Group Holdings S.A., LyondellBasell Industries N.V., Olin Corporation, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Dichloride Market Strategic Shifts & Innovations
Process intensification and the nascent integration of circular economy principles are defining the next phase of ethylene dichloride production. Manufacturers are responding to regulatory pressure and downstream demand for improved sustainability profiles through technological and operational adjustments.
Advanced catalytic systems for oxychlorination improve selectivity towards ethylene dichloride, minimizing the formation of unwanted byproducts. Major chemical producers are adopting these catalysts to increase asset efficiency and reduce downstream purification loads. This continuous improvement in catalyst performance is rendering obsolete older, less-selective reactor technologies that incur higher operational and environmental costs.
The European Union’s Green Deal and its associated Circular Economy Action Plan create a strong impetus for chemical recycling. This policy framework directly encourages the development of processes to convert post-consumer PVC waste back into chemical feedstocks. European producers are most affected, facing pressure to investigate and invest in routes to VCM that utilize recycled chlorinated materials.
A shift from long-term, fixed-volume offtake agreements to more flexible, shorter-duration supply contracts is altering procurement patterns. This change fragments the traditional direct sales channel, empowering smaller specialty chemical makers who require more adaptable sourcing. The trend is most visible in North America, where a diverse and dynamic downstream customer base values supply chain agility over long-term price locks.
Ethylene Dichloride Market Segmentation
The Ethylene Dichloride market's segmentation reveals the diverse pathways through which this critical chemical intermediate reaches its end-users. Understanding these distinct categories provides clarity on demand drivers, supply chain dynamics, and the specific regulatory pressures impacting each market facet.
Product Type:
The product type segmentation for ethylene dichloride reflects a mature market where processing and handling dictate the physical form, with established methods dominating production and delivery.
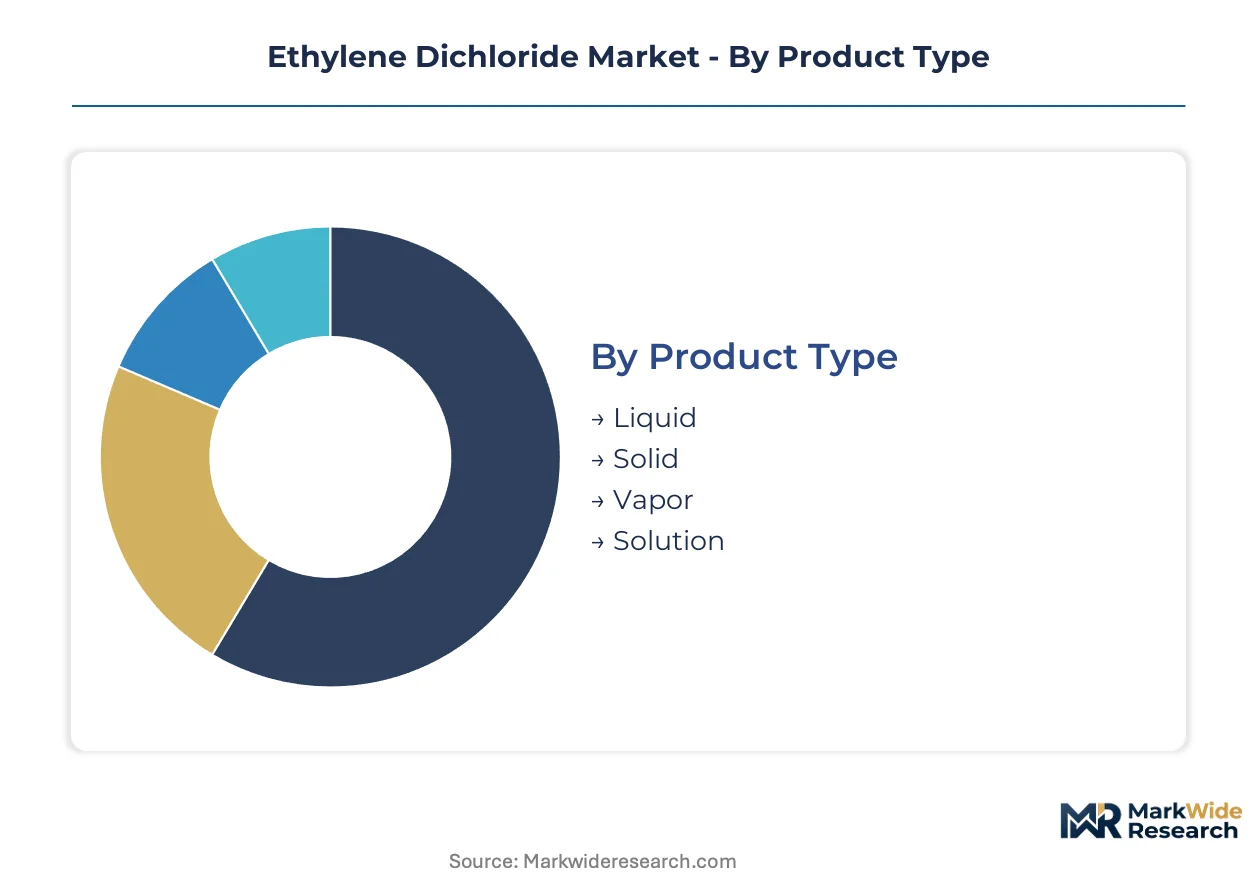
- Liquid:This is the most prevalent and commercially significant form of ethylene dichloride, typically stored and transported in bulk tankers. Global demand for liquid EDC is heavily concentrated in large-scale vinyl chloride monomer production facilities, particularly in China and the US Gulf Coast.
- Solution:Ethylene dichloride can be supplied as a solution, often blended with other solvents or diluents for specific industrial processes or safety requirements. This form finds niche applications in specialized chemical synthesis, where precise concentration and reactivity are critical for pharmaceutical intermediates.
- Vapor:EDC exists as vapor during production, requiring stringent emission controls within closed industrial systems.
- Solid:The solid form is less common, relevant under low-temperature conditions or when adsorbed onto solid carriers.
Liquid ethylene dichloride handles the majority of throughput; solution formulations are the fastest mover on share for niche applications.
Application:
The application landscape for ethylene dichloride is primarily driven by its role as a fundamental building block in the chemical industry, with varying technical requirements across uses.
- Chemical Feedstock:This represents the dominant application, where ethylene dichloride undergoes pyrolysis to produce vinyl chloride monomer (VCM). The vast majority of global EDC production is dedicated to this purpose, directly linking its market health to the global polyvinyl chloride (PVC) industry.
- Intermediate:Ethylene dichloride serves as a versatile chemical intermediate beyond VCM, participating in the synthesis of various organic compounds. High-purity grades are particularly valued in pharmaceutical and agrochemical synthesis, offering higher margin opportunities for specialized producers.
- Solvent:EDC functions as a solvent for fats, waxes, and resins, though US EPA regulations limit its use.
- Additive:In limited instances, EDC serves as an additive, with its application heavily regulated due to toxicity.
The chemical feedstock application drives the largest volumes; the intermediate use for specialty chemicals is gaining share due to higher purity demands.
End User:
The end-user segmentation highlights the primary industries that consume ethylene dichloride, reflecting its foundational role in material production and specialized chemical synthesis.
- Plastics:This sector is the largest consumer of ethylene dichloride, primarily through its conversion to vinyl chloride monomer (VCM) for polyvinyl chloride (PVC) production. Demand from construction and packaging industries, especially in Asia, directly influences EDC consumption.
- Chemical Industry:This broad category includes manufacturers using ethylene dichloride as a key intermediate for various organic compounds, including other chlorinated solvents. Major chemical producers like Occidental Petroleum serve this foundational sector.
- Pharmaceuticals:The pharmaceutical industry utilizes high-purity EDC as a solvent or intermediate in API synthesis.
- Agriculture:EDC finds limited application in agriculture as an intermediate for pesticides, facing environmental scrutiny.
The plastics industry accounts for the bulk of consumption, while the pharmaceutical segment exhibits significant growth potential due to demand for high-purity grades.
Distribution Channel:
The distribution channel for ethylene dichloride reflects the logistical complexities of hazardous chemical transport and the evolving procurement patterns of industrial buyers.
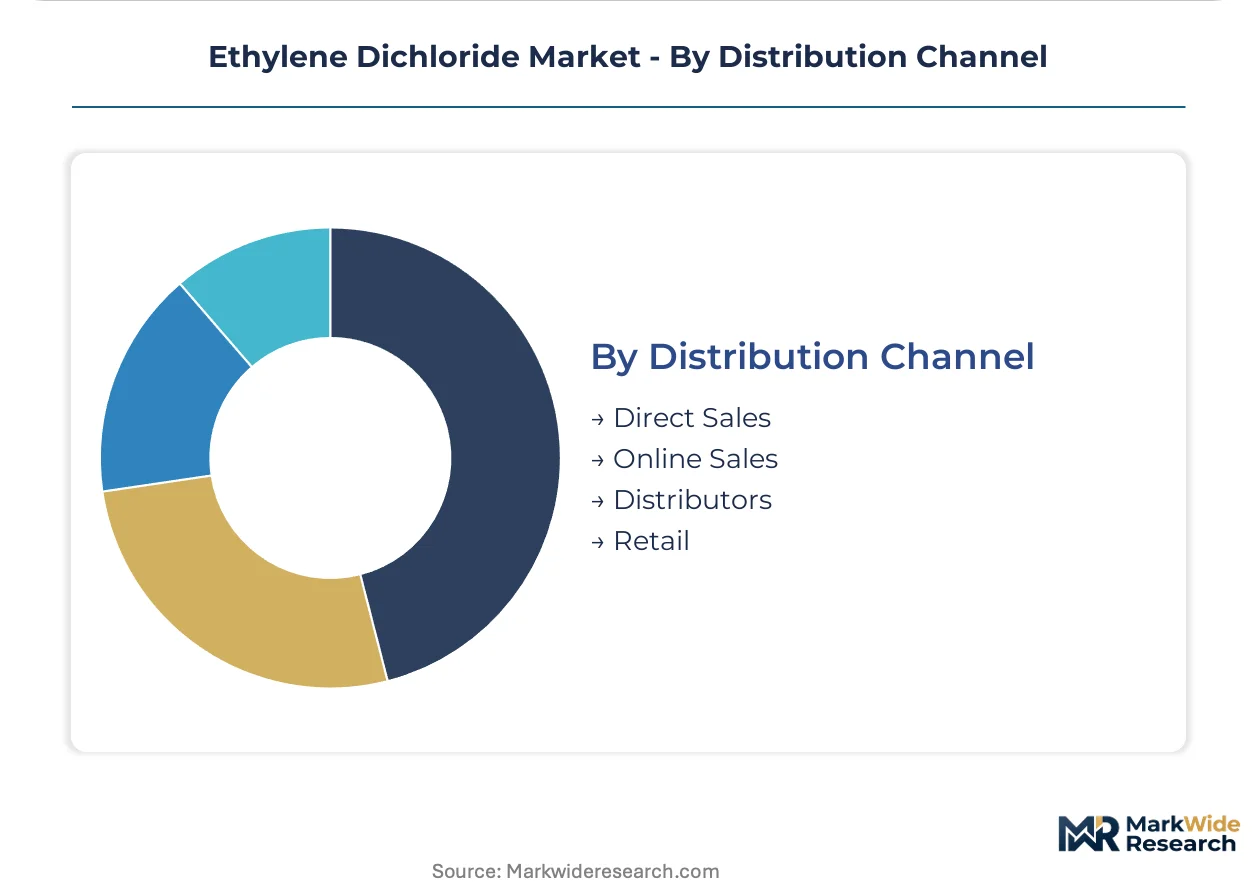
- Direct Sales:Major producers, such as Occidental Petroleum, primarily engage in direct sales to large-volume customers, including integrated VCM manufacturers. This channel facilitates customized contracts and technical support for bulk chemical feedstocks.
- Distributors:This channel serves smaller-volume buyers and specialty chemical manufacturers requiring flexible supply contracts and localized inventory. Distributors manage complex logistics and regulatory compliance for diverse regional clients.
- Online Sales:Online platforms are emerging for smaller chemical transactions, supporting laboratory-scale purchases or research needs.
- Retail:The retail channel is generally not applicable for bulk industrial chemicals due to their hazardous nature.
Direct sales dominate the high-volume procurement landscape, while distributors are crucial for reaching fragmented market segments and smaller specialty chemical makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US EPA regulations significantly influence ethylene dichloride production across major chemical hubs. Global demand for PVC, particularly from construction, drives sustained consumption in key regions. Manufacturing centers in Asia and North America remain critical to market dynamics.
United States
Continued demand for vinyl chloride monomer synthesis supports ethylene dichloride consumption within the plastics industry. The US EPA imposes strict emission controls on chemical manufacturing facilities. Major production sites along the US Gulf Coast, particularly in Texas, maintain high output capacity for global supply.
China
Large-scale infrastructure and housing projects generate consistent demand for PVC products, securing baseline ethylene dichloride consumption. China's MEE (Ministry of Ecology and Environment) enforces stringent environmental protection standards. Chemical complexes in the Yangtze River Delta continue to expand their production capabilities.
Germany
European chemical industry demand for specialty chemicals and pharmaceutical intermediates supports a segment of ethylene dichloride use. The EU's ECHA, under REACH, governs the safe use and handling of chlorinated hydrocarbons. Advanced chemical manufacturing facilities in the Rhine-Ruhr region focus on process efficiency.
India
Urbanization and infrastructure development projects drive consistent volume demand for PVC, particularly for pipes and profiles. The BIS (Bureau of Indian Standards) establishes quality benchmarks for chemical products. Petrochemical complexes in Gujarat are undergoing significant capacity expansions.
Vietnam
Expanding construction and manufacturing sectors present underpenetrated markets for PVC and its precursors. National environmental protection laws guide the establishment of new industrial zones. The Southern Economic Region, including areas near Ho Chi Minh City, attracts investment in chemical production.
Ethylene Dichloride Market Key Industry Players
Integrated chemical giants and niche specialty producers split the market for ethylene dichloride. The market exhibits a tiered structure, with large-scale players dominating bulk supply. Strategic archetypes include vertically integrated behemoths and agile high-purity specialists. Companies pursue capacity expansion and product differentiation to secure market share.
Among integrated chemical producers, Occidental Petroleum Corporation exemplifies leveraging substantial production capacity to serve major vinyl chloride monomer producers globally. Westlake Chemical Corporation sustains its market position through deeply integrated operations covering the entire vinyls production chain. Shin-Etsu Chemical Co., Ltd. occupies a position as a high-purity specialist, offering differentiated grades for niche solvent and pharmaceutical intermediate applications.
| Leading Market Players |
|---|
| Westlake Chemical Corporation |
| Saudi Basic Industries Corporation |
| Occidental Petroleum Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Formosa Plastics Corporation |
| INEOS Group Holdings S.A. |
| LyondellBasell Industries N.V. |
| Olin Corporation |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Overcapacity in major production hubs like the US Gulf Coast directly influences supplier behavior and pricing posture for ethylene dichloride. This utilization level dictates producers' willingness to offer flexible contracts versus maintaining long-term fixed arrangements.
Pricing Analysis
Geographic price spreads for ethylene dichloride reflect regional supply-demand imbalances and localized production costs. The market largely operates on a commodity spot pricing model, though major VCM producers often secure contract-based long-term offtake agreements. Price differentiation stems from quality grade for specialty applications and geographic delivery costs, particularly for intercontinental shipments. Pricing softness reflects fluctuating input prices for ethylene and chlorine, impacting operational margins. Large-scale VCM manufacturers are less price-sensitive due to integrated operations, while smaller specialty chemical makers exhibit higher sensitivity.
Supply Chain Analysis
Export controls on dual-use chemicals can limit the free flow of ethylene dichloride across certain geopolitical boundaries. Supply concentration is prominent in China, the US Gulf Coast, and the Rhine-Ruhr region of Germany, which are major production centers. The supply chain draws from primary raw materials like ethylene, often derived from crude oil, and chlorine from the chlor-alkali process. Regulatory restrictions and the hazardous nature of EDC present a structural supply chain risk. Distribution largely runs through direct sales to large, integrated chemical producers, complemented by distributors serving fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene dichloride market presents a fragmentation opportunity, driven by a demand-side shift towards high-purity grades for niche pharmaceutical and agrochemical applications.
For Market Incumbents: Insulate core VCM feedstock volumes by deepening backward integration into ethylene and chlorine production, mitigating raw material price volatility. Invest in advanced catalytic systems to improve production yields and reduce energy consumption, enhancing cost-competitiveness against emerging threats from regulatory compliance costs. Expand capacity in strategic regions like Southeast Asia to capture new demand.
For New Entrants and Emerging Players: Underpenetration in specialty solvent applications for high-purity ethylene dichloride offers a viable entry point. Target the pharmaceutical and agrochemical sectors in developing economies, particularly in India and Vietnam, where demand for intermediates is growing. A go-to-market angle focused on custom synthesis and certified high-purity grades can differentiate smaller players.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated producers with captive raw material supply and diverse end-market exposure. Focus on acquisition targets that demonstrate robust intellectual property in advanced catalytic processes or possess strategic production assets in growing Asian markets. The signal to watch is the adoption rate of carbon capture technologies by producers, indicating long-term environmental compliance viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Increases supply to meet growing PVC demand from urbanization projects in Vietnam and Indonesia. |
| Backward Integration into Ethylene Production | Mitigates input price volatility and secures a stable supply of a critical raw material for EDC synthesis. |
| Investment in Advanced Catalytic Systems | Enhances process efficiency and selectivity, reducing operational costs and environmental impact for producers. |
| Development of High-Purity Grades | Unlocks higher-margin opportunities in pharmaceutical and agrochemical intermediate applications for specialized firms. |
| Integration of Carbon Capture Technologies | Addresses environmental regulations and appeals to downstream customers seeking lower-carbon-footprint chemical products. |
Research Approach
Desk research of customs and trade data, industry association reports from ACC and Cefic, and SEC 10-K filings preceded structured interviews with plant managers, procurement leads at downstream OEMs, and technical R&D directors. This primary and secondary data triangulation ensured a comprehensive view of market dynamics. Bottom-up analysis of production capacities and top-down validation of market sizing were then performed.
Assumptions regarding global economic growth trajectories and the stability of regulatory frameworks were held fixed across the analysis window, while raw material prices for ethylene and chlorine were varied. The analytical framework modeled market demand across grade tier, end-use industry, and regional production hub. Compound Annual Growth Rates were derived from historical data trends and projected future demand scenarios. Industry-specific forecast inputs included VCM production capacity expansions and construction sector growth rates.
Practitioners should monitor shifts in environmental regulations, particularly from the US EPA and EU's ECHA, for early signals of market disruption. Forecasts reflect these underlying assumptions, and material shifts in global trade policies or raw material supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Asia-Pacific Formic Acid Market