
 Propionaldehyde Market | 2026-2036
Propionaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Propionaldehyde Market Analysis
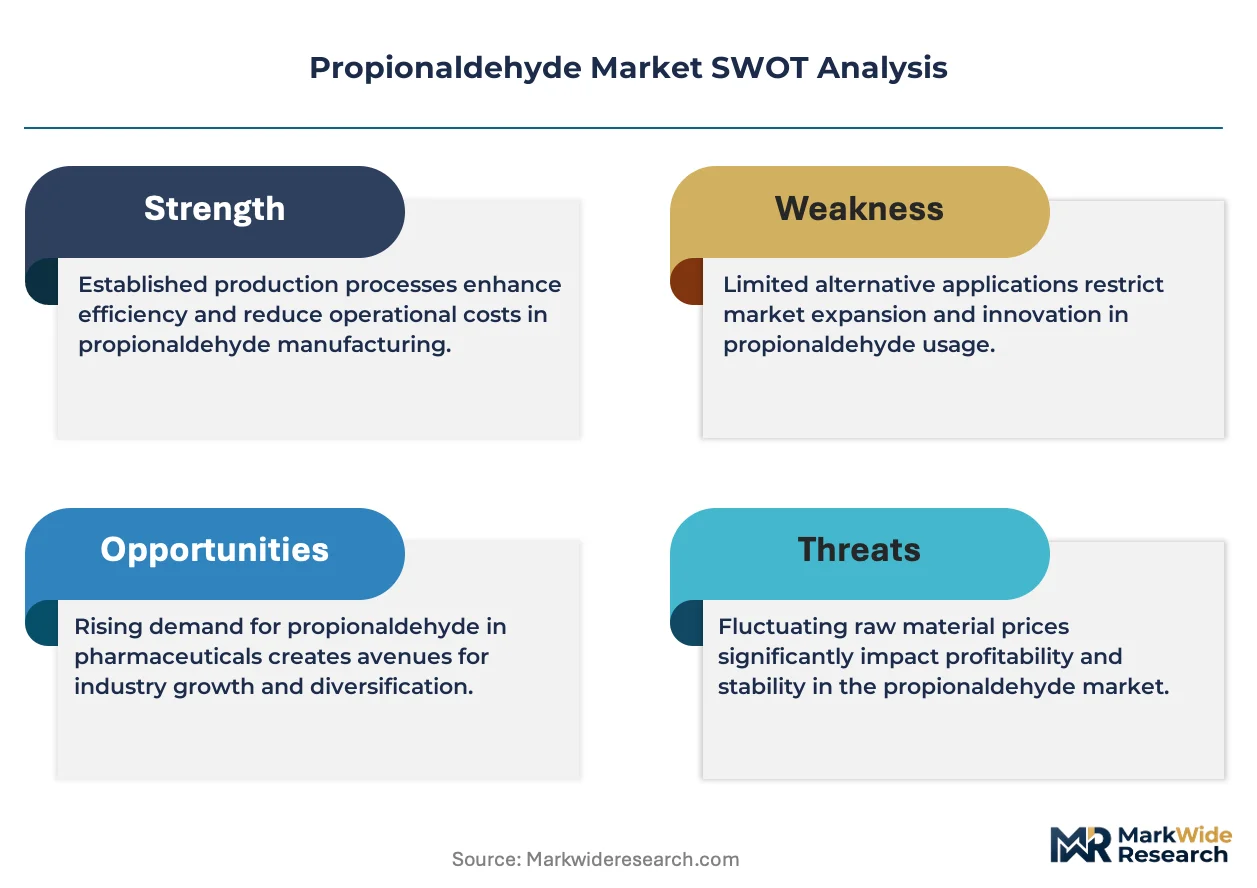
ISO 9001 certification for chemical manufacturing quality management is collapsing as a baseline requirement for propionaldehyde suppliers serving European pharmaceutical and personal care buyers. BASF SE leverages its integrated C1 chemistry platform to sustain captive propionaldehyde supply for downstream polymer intermediates. Eastman Chemical Company anchors North American availability through its oxo-alcohol process network. Perstorp Holding AB specializes in high-purity grades that meet pharmaceutical formulation standards.
Propionaldehyde (propanal, CH3CH2CHO) is a three-carbon aldehyde with a molecular weight of 58.08 g/mol, produced industrially via hydroformylation of ethylene with carbon monoxide and hydrogen, serving primarily as a chemical intermediate for n-propionic acid, n-propanol, and polyvinyl butyral plasticizers. Industrial grade material dominates volume flows into plastic manufacturing and agriculture, where margin pools are deepest from commodity-scale offtake. Pharmaceutical grade commands premium positioning due to stringent impurity thresholds, while food and cosmetic grades occupy narrower but defensible niches in flavoring and preservative applications. Liquid form prevails across all segments because of handling efficiency in drums and IBC tanks, though bulk container logistics are reshaping procurement economics for large agrochemical buyers.
REACH registration requirements in the European Union, EPA Toxic Substances Control Act oversight in the United States, and China's GB standards under SAMR collectively determine market access thresholds for purity, labeling, and environmental release limits. These frameworks compel producers to maintain dual certification portfolios, raising fixed compliance costs that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving classification of propionaldehyde under carcinogenicity review protocols, as any reclassification would trigger reformulation mandates across personal care and pharmaceutical end uses.
Market Dynamics
REACH compliance tightening in the European Union is forcing propionaldehyde suppliers to reconfigure purification protocols, while agrochemical buyers in China consolidate procurement into long-term offtake agreements that reshape contract structures.
Growth Catalysts
- Pharmaceutical synthesis expansion:Active ingredient manufacturers in Germany are scaling propionaldehyde purchases for antibiotic and vitamin precursor production.
- REACH registration thresholds:ECHA mandates for substance volume tracking create compliance-driven demand for documented supply chain traceability.
- Agrochemical derivative output:N-propionic acid production for herbicide formulations in China's Shandong province is pulling additional propionaldehyde volumes.
Market Restraints
- Ethylene feedstock volatility:Hydroformylation economics hinge on ethylene pricing, with naphtha-cracker output fluctuations in the US Gulf Coast transmitting directly to propionaldehyde cost structures.
- Supply concentration in integrated petrochemicals:Captive production within C1 chemistry platforms limits merchant market liquidity and spot availability.
- Propionic acid substitution:Fermentation-derived propionic acid from agricultural waste streams is encroaching on synthetic routes in European food preservative applications.
Strategic Opportunities
- High-purity pharmaceutical grades:Impurity thresholds below 50 ppm for parenteral drug applications command margin premiums in Switzerland and Germany.
- Biobased feedstock integration:Bio-ethylene from Brazilian sugarcane ethanol is converging with conventional hydroformylation to produce mass-balance-certified propionaldehyde.
- Direct-to-formulator e-commerce:Specialty chemical platforms are disintermediating traditional distributor networks for sub-ton pharmaceutical and personal care orders.
Industry Challenges
- Dual-certification complexity:Producers serving both EU REACH and US EPA TSCA jurisdictions face divergent dossier requirements that extend registration timelines.
- Specialized analytical chemist scarcity:Gas chromatography expertise for aldehyde impurity profiling is concentrated among aging workforces in Western Europe.
- Legacy tank farm reconfiguration:Bulk storage facilities designed for commodity aldehydes require retrofitting for pharmaceutical-grade segregation and cleaning validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propionaldehyde Market |
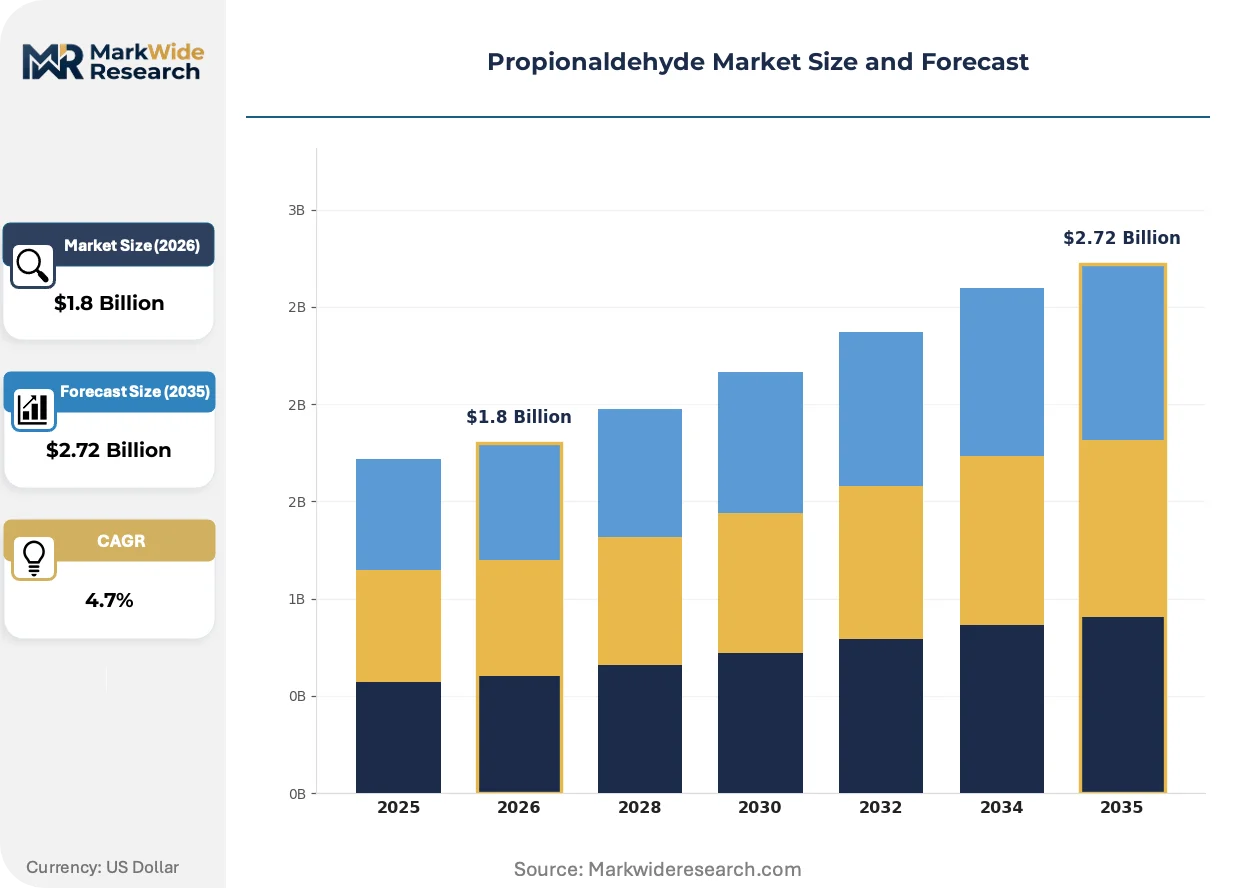
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Cosmetic Grade End Use Industry: Plastic Manufacturing, Agriculture, Pharmaceuticals, Personal Care Form: Liquid, Solid, Powder, Tablets Packaging Type: Drums, IBC Tanks, Bottles, Bulk Containers |
| Companies Covered | BASF SE, Eastman Chemical Company, The Dow Chemical Company, Celanese Corporation, Perstorp Holding AB, DuPont, Zibo Nuoao Chemical Co. Ltd., OQ Chemicals GmbH, China National Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propionaldehyde Market Emerging Trajectories
Continuous hydroformylation reactor designs are displacing batch operations, while regulatory pressure on carbon intensity forces process chemistry revisions. These shifts are compressing capital recovery timelines and rewriting supplier qualification protocols.
Membrane-based propionaldehyde separation is supplanting conventional distillation in newer plant installations. Pharmaceutical-grade producers in Switzerland are adopting this technology to reduce thermal degradation and color-body formation. The shift is enabling tighter impurity specifications that command premium positioning in parenteral drug applications.
ECHA's 2023 updated guidance on aldehyde carcinogenicity classification is triggering reformulation reviews across personal care and cosmetic applications. Formulators in France and Germany are preemptively sourcing alternative preservatives or demanding enhanced toxicological dossiers from suppliers. Fragrance and cosmetic grade segments are responding with accelerated purity certification investments.
Agrochemical buyers are consolidating annual propionaldehyde requirements into single-source framework agreements with volume commitments and fixed-price collars. This behavior is displacing spot-market purchasing that dominated procurement through 2020. The pattern is most visible in China's Hebei and Shandong provinces where herbicide manufacturers seek supply security amid feedstock volatility.
Propionaldehyde Market Segmentation
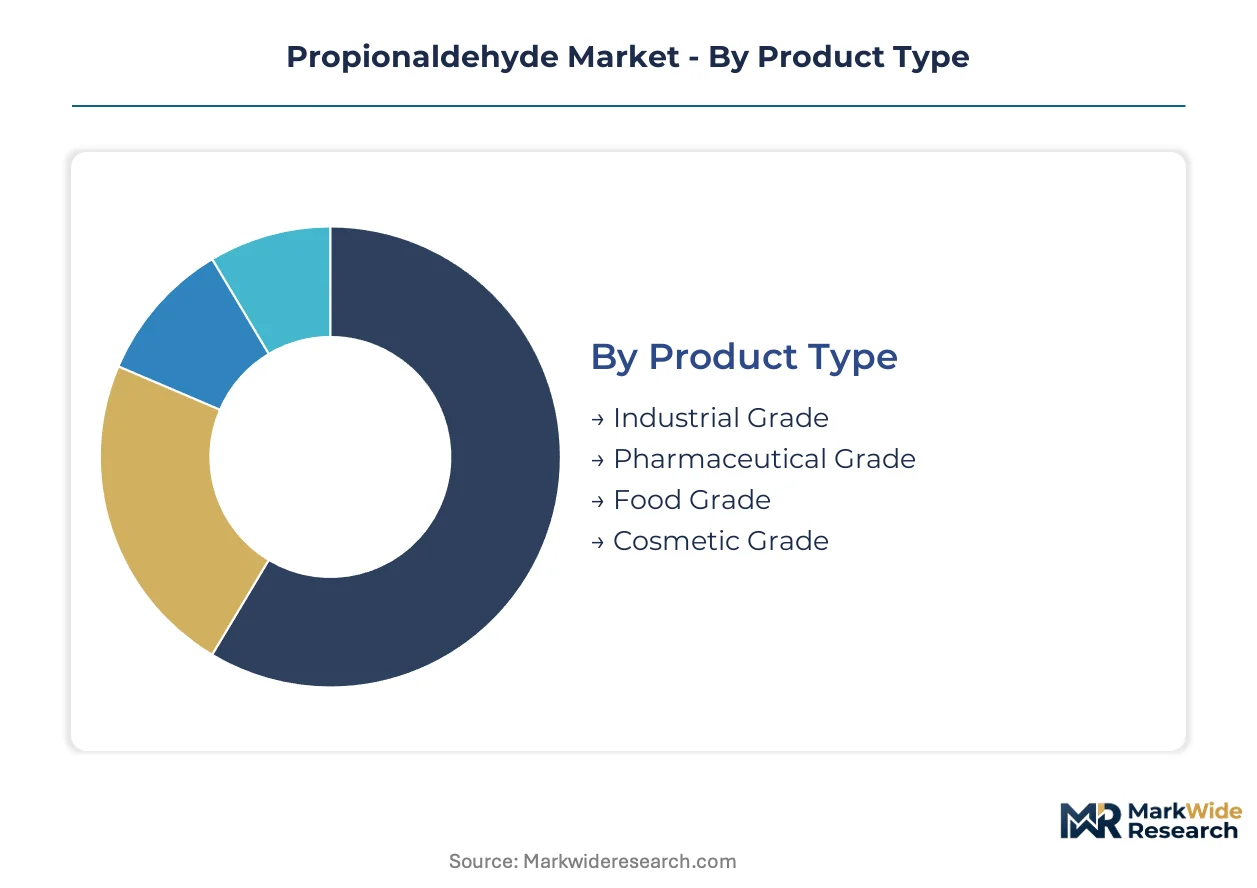
Propionaldehyde procurement patterns diverge sharply across purity grades and handling formats, with regulatory thresholds in pharmaceuticals and cost pressures in agriculture creating distinct commercial segments. Understanding these divides reveals where margin pools concentrate and where commoditization erodes returns.
Product Type:
REACH purity mandates in the European Union and FDA pharmaceutical standards in the United States enforce tiered certification requirements that reshape supplier economics.
- Industrial Grade:Material with 95-98% purity serves bulk chemical synthesis and plasticizer manufacturing. Agrochemical producers in China's Shandong province absorb the largest volumes, prioritizing feedstock cost over impurity thresholds.
- Pharmaceutical Grade:Specifications below 50 ppm total impurities enable parenteral drug applications. Swissmedic and EMA documentation requirements drive captive production investments by integrated C1 chemistry platforms serving Basel and Ludwigshafen clusters.
- Food Grade:Flavoring and preservative applications under FSSAI and FDA jurisdiction require organoleptic neutrality. Fermentation-derived propionic acid is displacing synthetic routes in European food applications.
- Cosmetic Grade:Fragrance formulation demands color stability and low aldehyde reactivity. ECHA's carcinogenicity review protocols are triggering reformulation away from propionaldehyde-based preservatives in French and German cosmetic manufacturing.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
End Use Industry:
Customer scale and contract duration separate segments, with agrochemical offtake consolidating into multi-year frameworks while pharmaceutical orders fragment across specialty distributors.
- Plastic Manufacturing:Polyvinyl butyral plasticizer production consumes commodity-scale propionaldehyde flows. Naphtha-cracker economics in the US Gulf Coast and Rotterdam-Antwerp corridor determine regional cost competitiveness.
- Agriculture:N-propionic acid herbicide precursors drive demand concentration in China's Hebei province. Volume commitments with fixed-price collars are displacing spot procurement that dominated through 2020.
- Pharmaceuticals:Antibiotic and vitamin precursor synthesis requires documented supply chain traceability under ECHA volume-tracking mandates. Gas chromatography expertise for aldehyde impurity profiling is concentrated among aging analytical chemist workforces in Western Europe.
- Personal Care:Fragrance and preservative applications face ECHA reformulation pressure. Formulators are demanding enhanced toxicological dossiers or switching to alternative chemistries.
Margin stability concentrates in Pharmaceuticals; volume expansion concentrates in Agriculture.
Form:
Handling efficiency and thermal stability govern format selection, with liquid dominance challenged only by specialized pharmaceutical packaging requirements.
- Liquid:Prevails across all grades due to pumpability in drums and IBC tanks. Bulk container logistics are reshaping procurement economics for large agrochemical buyers seeking reduced handling costs.
- Solid:Encapsulated or stabilized forms for controlled-release pharmaceutical applications. Limited commercial penetration outside experimental drug delivery systems.
- Powder:Spray-dried derivatives for specialty polymer additive manufacturing. Moisture sensitivity constrains storage and transport economics.
- Tablets:Compressed excipient forms for precise-dose pharmaceutical compounding. Niche positioning in compounding pharmacy supply chains.
Liquid commands throughput economics; solid and powder formats remain developmental.
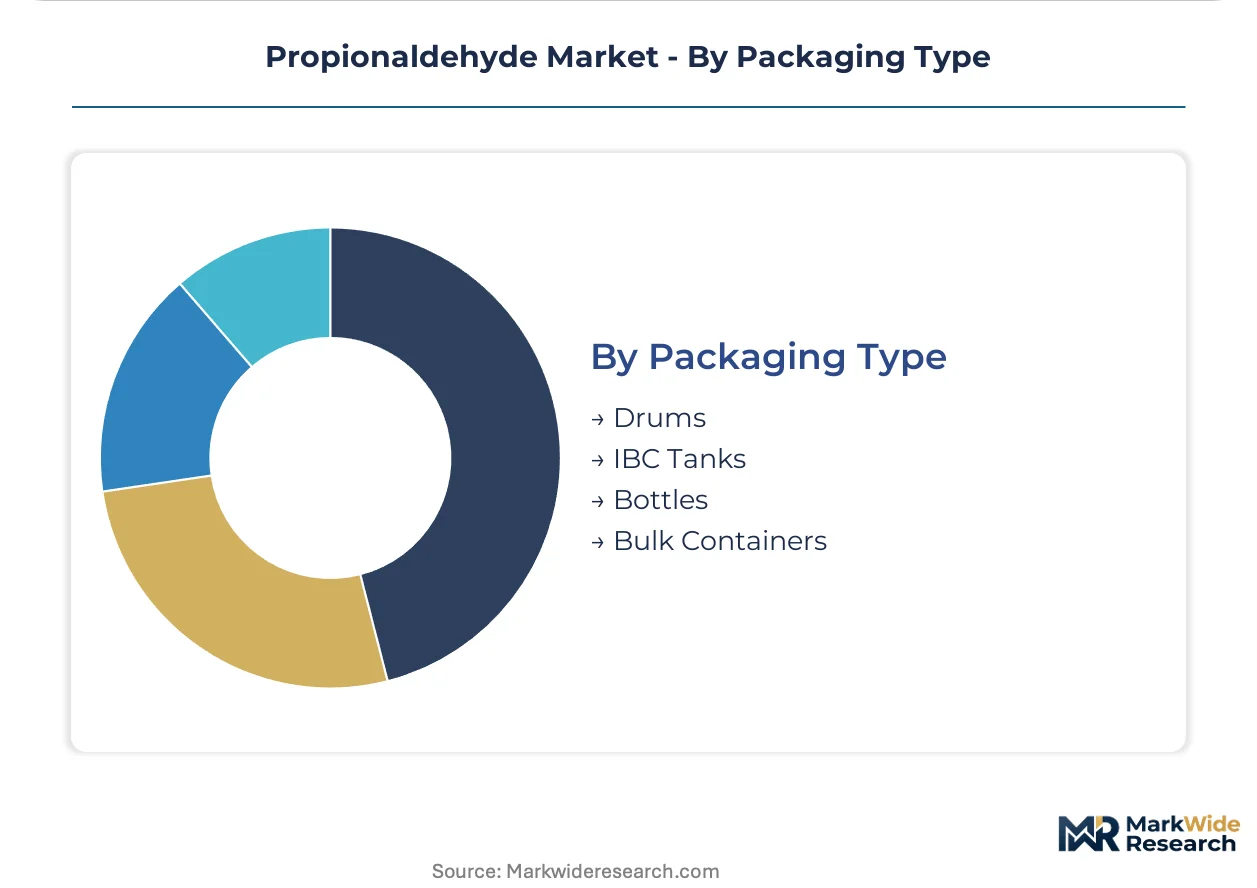
Packaging Type:
Container scale directly maps to customer procurement sophistication, with drum and IBC networks fragmenting while bulk infrastructure consolidates.
- Drums:Standard 200-liter steel containers serve mid-scale pharmaceutical and personal care formulators. Cleaning validation protocols for pharmaceutical-grade segregation raise per-unit logistics costs.
- IBC Tanks:Intermediate bulk containers enable semi-bulk flows to regional agrochemical blenders. Returnable container programs are emerging in European closed-loop supply chains.
- Bottles:Laboratory-scale packaging for analytical standard and R&D applications. High per-liter cost limits commercial scale deployment.
- Bulk Containers:ISO tank and dedicated tanker shipments serve integrated propionaldehyde consumers with direct pipeline connections. Tank farm reconfiguration for grade segregation requires capital investment at Rotterdam and Houston terminals.
Drums and IBCs fragment across customer bases; bulk containers concentrate with integrated processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates in the European Union are redirecting purification investments, while China's agrochemical consolidation and US Gulf Coast feedstock dynamics are reshaping regional supply architectures across the propionaldehyde market.
China
Shandong and Hebei provinces dominate n-propionic acid derivative output for herbicide manufacturing. SAMR's GB standards enforcement is tightening purity documentation for chemical imports. Hebei's agrochemical clusters are consolidating annual propionaldehyde requirements into single-source framework agreements with volume commitments.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen are expanding propionaldehyde purchases for antibiotic and vitamin precursor synthesis. ECHA's updated aldehyde carcinogenicity guidance is triggering reformulation reviews across personal care applications. The BASF SE integrated C1 chemistry platform sustains captive supply for downstream polymer intermediates.
United States
Eastman Chemical Company anchors North American availability through oxo-alcohol process networks serving plasticizer manufacturers. EPA Toxic Substances Control Act oversight determines market access thresholds for environmental release limits. US Gulf Coast naphtha-cracker output fluctuations transmit directly to propionaldehyde cost structures.
Switzerland
Swissmedic documentation requirements drive captive production investments for parenteral drug applications. Membrane-based propionaldehyde separation technology is supplanting conventional distillation in newer plant installations. Basel's pharmaceutical cluster is adopting this technology to reduce thermal degradation and enable tighter impurity specifications.
Sweden
Perstorp Holding AB specializes in high-purity grades that meet pharmaceutical formulation standards for European personal care buyers. REACH registration thresholds for substance volume tracking create compliance-driven demand for documented supply chain traceability. The company's analytical capabilities support impurity profiling requirements for parenteral applications.
Propionaldehyde Market Vendor Landscape
Listed leaders compete with private specialists across integrated petrochemical platforms and merchant market niches. The vendor base clusters around three structural positions: diversified chemical conglomerates with captive C1 chemistry integration, regional oxo-alcohol specialists serving commodity plasticizer demand, and high-purity focused operators targeting pharmaceutical certification. Competitive moves center on backward integration into ethylene feedstock control and purification technology licensing for REACH compliance.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify scale-driven positions anchored by oxo-alcohol process networks. Among European high-purity specialists, Perstorp Holding AB occupies a certification-focused niche serving Swiss and German pharmaceutical clusters. Chinese merchant market participation includes Zibo Nuoao Chemical Co. Ltd., representing regional supply capacity oriented toward agrochemical derivative output.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| The Dow Chemical Company |
| Celanese Corporation |
| Perstorp Holding AB |
| DuPont |
| Zibo Nuoao Chemical Co. Ltd. |
| OQ Chemicals GmbH |
| China National Petroleum Corporation |
| Others |
Supply Flow & Price Mechanics
REACH registration thresholds in the European Union simultaneously gate supplier qualification and enable price stratification across purity grades. ECHA volume-tracking mandates force documentation investments that concentrate pricing power with scaled manufacturers capable of absorbing fixed compliance costs. This regulatory architecture compresses margins for merchant market participants while rewarding integrated C1 chemistry platforms with captive supply economics.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade propionaldehyde. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects impurity thresholds and documentation burdens. Cost compression in industrial-grade segments intensifies because agrochemical buyers in China's Shandong province consolidate procurement into volume-commitment frameworks. Pharmaceutical manufacturers in Germany and Switzerland exhibit the lowest price sensitivity due to parenteral drug application requirements.
Supply Chain Analysis
Inventory cycles for pharmaceutical-grade material extend lead times beyond industrial-grade spot availability. Supply concentrates in Germany, the United States, and China, with BASF SE's Ludwigshafen complex and Eastman Chemical's US Gulf Coast operations anchoring regional availability. Hydroformylation economics draw from ethylene feedstock pricing, with naphtha-cracker output volatility transmitting directly to cost structures. Single-source vulnerability runs through China's agrochemical derivative producers, who depend on merchant market liquidity. Distribution runs through drum and IBC networks for specialty orders, while bulk ISO tank shipments serve integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propionaldehyde procurement increasingly attaches to analytical certification and regulatory dossier services that expand faster than commodity chemical margins. Swiss and German pharmaceutical buyers now bundle gas chromatography validation and REACH documentation into long-term supply agreements.
For Market Incumbents: Secure backward integration into ethylene feedstock control to insulate margin structures from naphtha-cracker volatility. Invest in membrane-based separation technology to reduce thermal degradation and capture pharmaceutical-grade premiums. Defend against fermentation-derived propionic acid substitution by accelerating biobased feedstock certification through Brazilian sugarcane ethanol pathways. For New Entrants and Emerging Players: FDA pharmaceutical-grade fast-track certification opens white-space positioning in parenteral drug applications where impurity thresholds below 50 ppm command sustained premiums. Target cosmetic-grade reformulation demand in France and Germany, where ECHA carcinogenicity reviews displace incumbent preservatives. Pursue direct-to-formulator e-commerce channels for sub-ton pharmaceutical and personal care orders, disintermediating traditional distributor networks. For Investors and Strategic Acquirers: ECHA's updated aldehyde carcinogenicity guidance reshapes the acquisition landscape by triggering reformulation mandates across personal care applications. Position for five-to-ten year viability by targeting high-purity specialists with captive analytical capabilities and Swissmedic documentation portfolios. Monitor SAMR enforcement of GB standards in China as the signal indicating regulatory convergence or divergence with REACH protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Separation Technology Adoption | Swiss pharmaceutical clusters deploy this to achieve sub-50 ppm impurity thresholds for parenteral applications. |
| Biobased Feedstock Certification | Brazilian sugarcane ethanol convergence enables mass-balance credentials for European REACH compliance. |
| Long-term Supply Agreement Restructuring | Hebei agrochemical consolidators lock volume commitments with fixed-price collars amid ethylene volatility. |
| Direct-to-Formulator E-commerce Platform | Specialty chemical marketplaces disintermediate distributors for sub-ton pharmaceutical and personal care orders. |
| Analytical Chemist Capability Acquisition | Gas chromatography expertise for aldehyde profiling concentrates among aging Western European workforces. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at hydroformylation facilities, procurement leads at agrochemical derivative manufacturers, distribution channel partners in European drum networks, and technical R&D directors specializing in aldehyde purification. These interviews were refined against secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings from integrated petrochemical conglomerates, and ECHA registration dossiers. Bottom-up volume modeling across grade tiers and end-use industries was triangulated with top-down market sizing from production capacity disclosures.
Variance decomposition across the projection horizon isolates feedstock price elasticity, regulatory compliance cost trajectories, and substitution threat intensity from fermentation-derived propionic acid. Segmentation dimensions modeled include purity grade tier, end-use industry concentration, packaging format scale, and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific forecast inputs incorporate ethylene contract pricing dynamics and ECHA carcinogenicity review timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement or abrupt ethylene feedstock disruption would require recalibration. Forecasts reflect assumptions about hydroformylation capacity utilization and pharmaceutical-grade certification retention rates. Revision becomes warranted when fermentation-derived propionic acid cost parity crosses synthetic route thresholds in European food preservative applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Global Nitrite Market